
 Service Truck Market | 2026-2036
Service Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Service Truck Market Insights
Modular upfitting packages are recalibrating how fleet managers configure service trucks, shifting from fixed-body specifications to standardized component ecosystems that reduce procurement complexity. Ford Motor Company leverages its chassis dominance to anchor fleet partnerships across utility and construction segments. Knapheide Manufacturing Company specializes in body fabrication configurations that sustain premium positioning in the medium-duty category. Isuzu Motors Limited competes through diesel powertrain efficiency in urban delivery and roadside assistance applications.
A service truck is a commercial vehicle engineered with integrated storage compartments, utility bodies, and specialized equipment mounting systems, typically built on chassis with gross vehicle weight ratings from 8,500 to 33,000 pounds, designed to transport tools, parts, and technicians to field service locations. Light-duty trucks occupy the highest volume tier due to last-mile accessibility and lower total cost of ownership for telecommunications and delivery services. Heavy-duty trucks concentrate margin pools in oilfield and mining support where payload capacity and hydraulic system integration command premium pricing. Electric power technology is displacing conventional hydraulic auxiliary systems in urban utility applications where noise ordinances and idling restrictions apply.
NHTSA commercial vehicle safety standards govern brake performance and stability control requirements that shape chassis specification decisions for domestic manufacturers. EPA Phase 3 greenhouse gas regulations and CARB advanced clean trucks rules are forcing powertrain diversification timelines that affect fleet replacement cycles. OSHA work platform standards influence aerial device configurations on specialty truck builds. Stakeholders must monitor state-level zero-emission fleet mandates and utility electrification procurement timelines to align product development with evolving operator requirements.
Market Dynamics
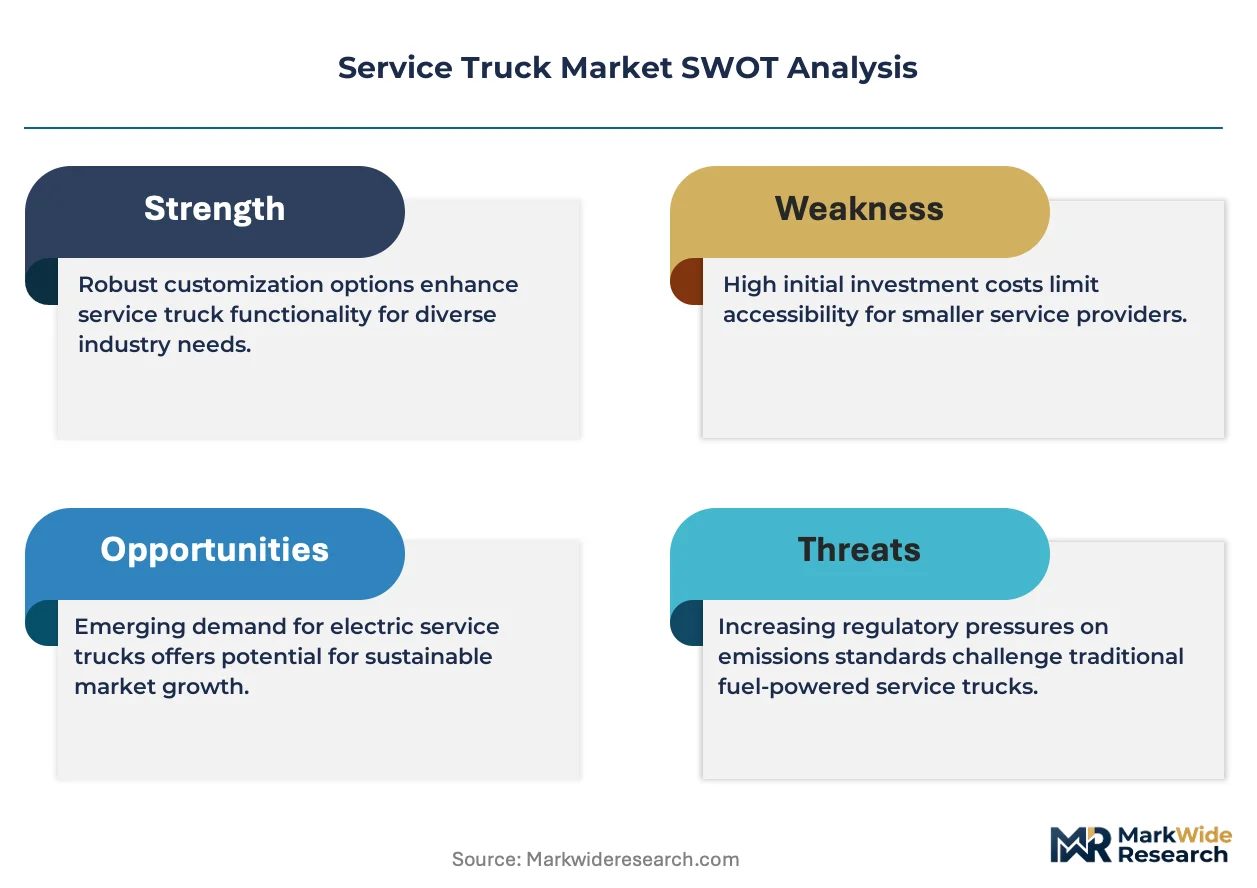
Powertrain electrification timelines are compressing fleet replacement cycles as operators balance EPA Phase 3 greenhouse gas regulations against hydraulic system integration requirements for heavy-duty applications.
Growth Catalysts
- CARB Advanced Clean Trucks Rules:California's zero-emission fleet mandates are pulling forward electric chassis procurement across utility and municipal segments.
- Oilfield Services Concentration:Permian Basin equipment maintenance demand in Texas is expanding mobile service truck deployment for hydraulic fracturing fleets.
- Telecommunications Infrastructure:5G network densification is driving last-mile service truck utilization for cell tower maintenance and fiber optic repairs.
Market Restraints
- Battery Cost Volatility:Lithium-ion cell price fluctuations are compressing electric chassis gross margins for medium-duty upfitters.
- Steel Supply Concentration:Domestic body fabrication depends on concentrated North American steel mill capacity, exposing fabricators to input price spikes.
- Hydraulic System Limitations:Electric power take-off units cannot yet match conventional hydraulic lift capacity for heavy aerial device applications.
Strategic Opportunities
- Utility Electrification Procurement:Investor-owned utilities in California and New York are specifying battery-electric service trucks in RFP requirements.
- Modular Component Convergence:Standardized mounting systems are converging with telematics platforms to enable rapid body reconfiguration across fleet pools.
- Rural Broadband Deployment:USDA Rural Utility Service financing is opening municipal service truck demand in underserved counties.
Industry Challenges
- Electric Powertrain Technician Shortage:Fleet maintenance departments lack certified high-voltage system specialists for battery-electric chassis diagnostics.
- OSHA Aerial Device Certification:Work platform inspection and recertification timelines are extending specialty truck delivery schedules.
- Legacy Fleet Integration:Telematics retrofit compatibility is creating data fragmentation between new electric chassis and existing diesel units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Truck Market |
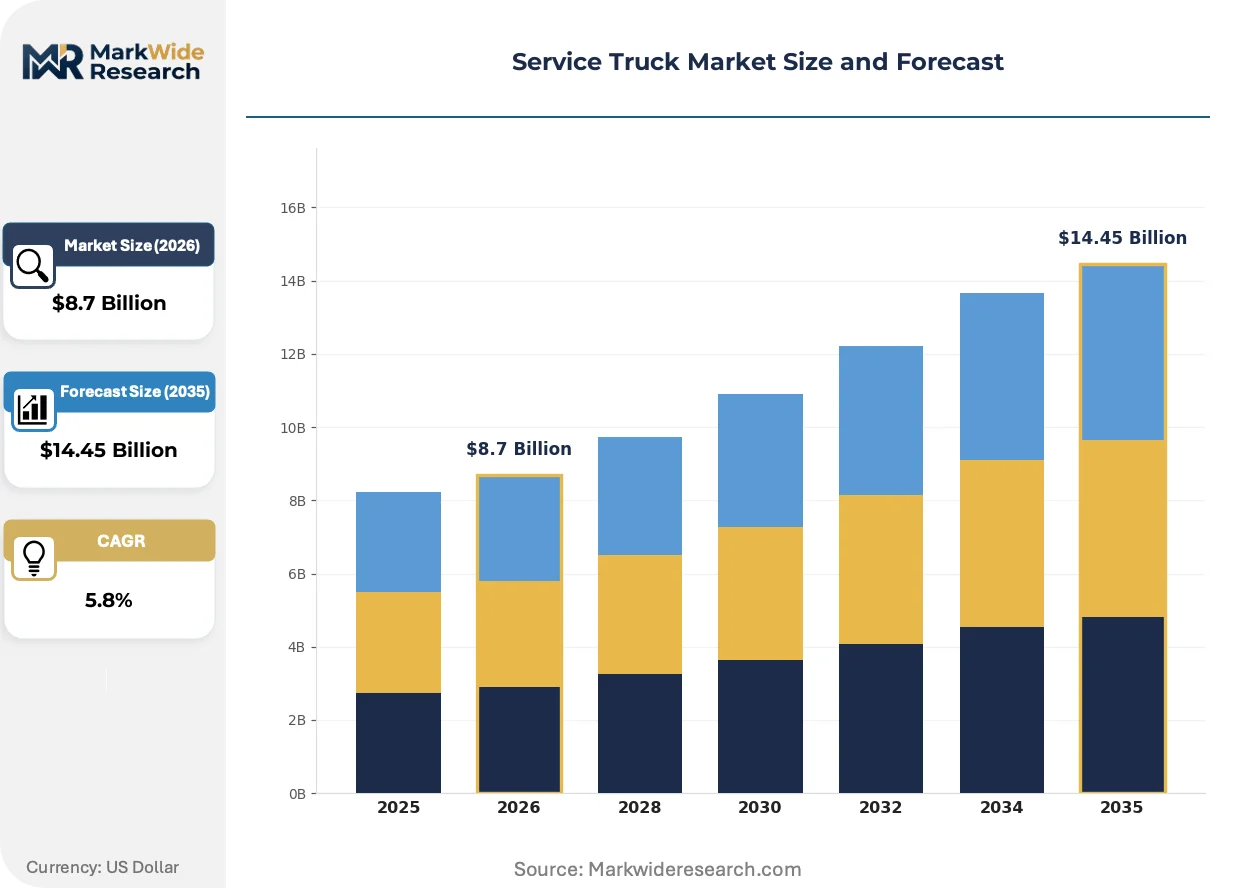
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Duty Trucks, Medium-Duty Trucks, Heavy-Duty Trucks, Specialty Trucks End User: Construction, Utility, Telecommunications, Emergency Services Application: Mobile Maintenance, Equipment Repair, Roadside Assistance, Delivery Services Technology: Hydraulic Systems, Electric Power, Pneumatic Tools, GPS Tracking |
| Companies Covered | Ford Motor Company, General Motors Company, Oshkosh Corporation, Altec Industries Inc., Mercedes-Benz, Dongfeng Motor Corporation, Isuzu Motors Limited, Knapheide Manufacturing Company, Volvo Trucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Truck Market Trends and Innovations
Telematics integration is rewriting how fleet operators manage asset utilization, compressing the gap between chassis specification and real-world duty cycle optimization. Three developments are accelerating this transformation.
Electric power take-off systems are rewriting auxiliary equipment operation in urban utility applications. Municipal fleets in noise-restricted zones are adopting battery-driven hydraulic pumps for aerial devices. This convergence is rewriting the specification trade-off between payload capacity and emissions compliance for Class 6 trucks.
EPA Phase 3 greenhouse gas regulations are forcing powertrain diversification timelines that outpace charging infrastructure deployment. Fleet managers are hedging with hybrid auxiliary systems rather than full battery-electric conversions. Heavy-duty segments in Texas oilfield services are responding with extended diesel chassis lifecycles to amortize capital before zero-emission mandates tighten.
Outcome-based fleet management contracts are displacing traditional equipment procurement in utility segments. Service providers now bundle chassis, maintenance, and uptime guarantees into single monthly fees. This shift is most visible in California investor-owned utilities where electrification targets require vendor risk-sharing on battery performance.
Service Truck Market Segmentation
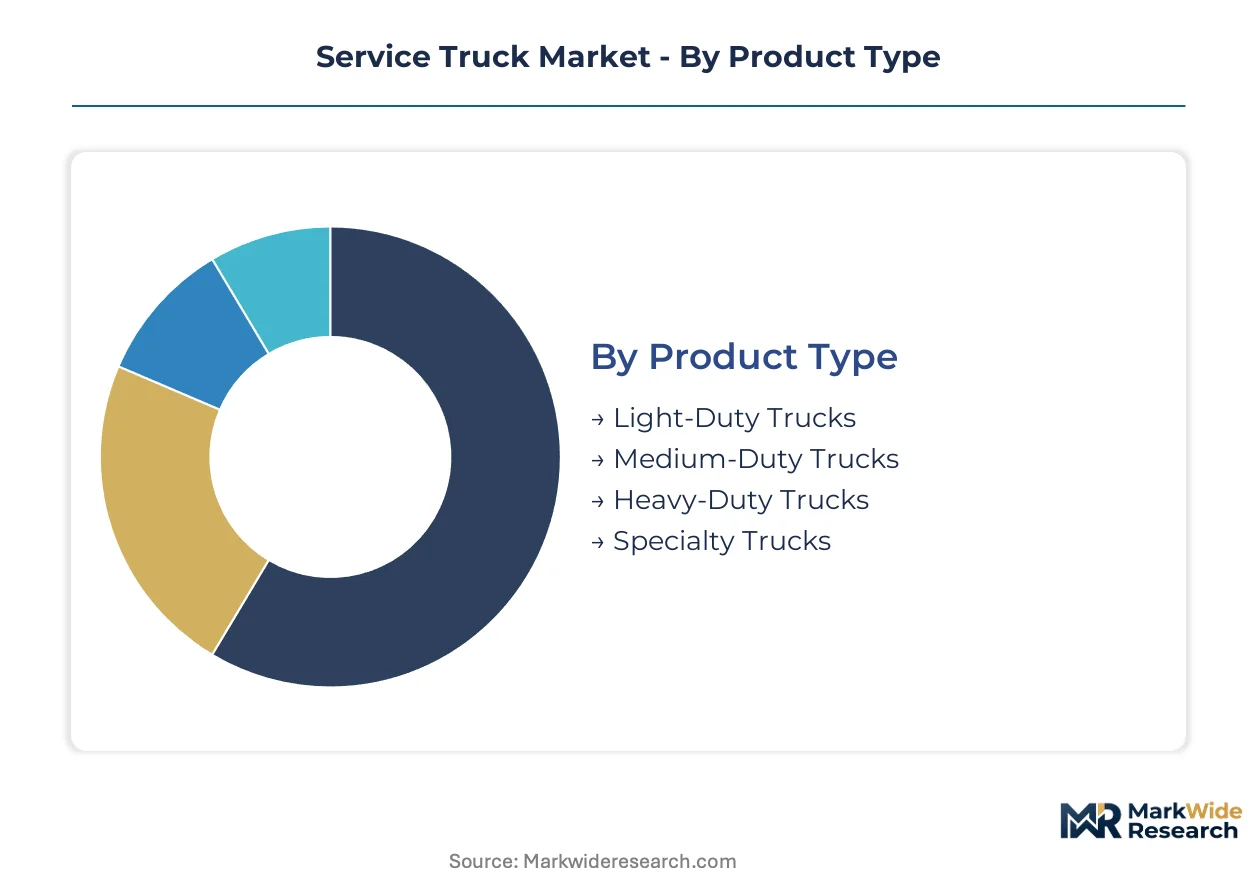
Service truck configuration varies sharply across operating environments, from urban telecom fleets prioritizing maneuverability to oilfield operators demanding hydraulic lift capacity. Fleet managers segment procurement decisions by duty cycle intensity, regulatory exposure, and equipment integration requirements rather than chassis specifications alone.
Product Type:
The customization-vs-standardization spectrum stretches from mass-produced light-duty platforms to bespoke heavy-duty fabrications with integrated hydraulic systems.
- Light-Duty Trucks:Chassis rated 8,500–14,000 pounds GVWR dominate telecommunications and last-mile delivery fleets. Verizon and AT&T procurement specifications prioritize compact turning radius and curb weight compliance for dense urban cell tower access routes.
- Heavy-Duty Trucks:Class 7–8 platforms rated 26,000–33,000 pounds GVWR anchor Permian Basin oilfield service operations. Hydraulic fracturing fleet operators specify integrated power take-off systems and 10,000-pound crane capacity for wellhead maintenance.
- Medium-Duty Trucks:Municipal utility fleets in California balance payload requirements with CARB emissions compliance through Class 6 hybrid configurations.
- Specialty Trucks:Aerial device integrations for electrical utilities command extended lead times due to OSHA work platform certification requirements.
Most installed capacity flows through Light-Duty Trucks. Expansion is steepest in Heavy-Duty Trucks.
End User:
Cost tier differentiation separates capital-intensive utility fleets from price-sensitive municipal purchasers.
- Utility:Investor-owned utilities in California and New York specify battery-electric chassis with outcome-based uptime guarantees. Pacific Gas and Electric procurement contracts now bundle maintenance, telematics, and charging infrastructure into per-mile fees.
- Telecommunications:5G network densification drives demand for compact service trucks with fiber optic splicing equipment integration. Crown Castle and American Tower fleet specifications emphasize low-floor body configurations for technician ergonomics.
- Construction:General contractor fleets prioritize interchangeable body systems across mixed equipment maintenance roles.
- Emergency Services:Municipal fire departments and disaster response units specify all-terrain capability and auxiliary power generation for field command operations.
Procurement volume concentrates in Utility. Customer acquisition costs run highest in Emergency Services.
Application:
Geography dictates application mix, with urban density favoring mobile maintenance and rural expansion driving equipment repair specialization.
- Mobile Maintenance:Field technicians perform preventive maintenance on heavy equipment without transporting assets to fixed facilities. Caterpillar and John Deere dealer networks deploy regional service truck pools to minimize customer downtime.
- Roadside Assistance:AAA and commercial fleet service providers specify light-duty chassis with wheel-lift and flatbed compatibility for highway incident response.
- Equipment Repair:Mining and aggregate operations in Nevada and Arizona require on-site welding and hydraulic hose fabrication capabilities.
- Delivery Services:Last-mile parts distribution for industrial distributors emphasizes cargo security and inventory tracking integration.
Mobile Maintenance captures the majority of fleet operating hours. Equipment Repair commands the highest revenue per truck.
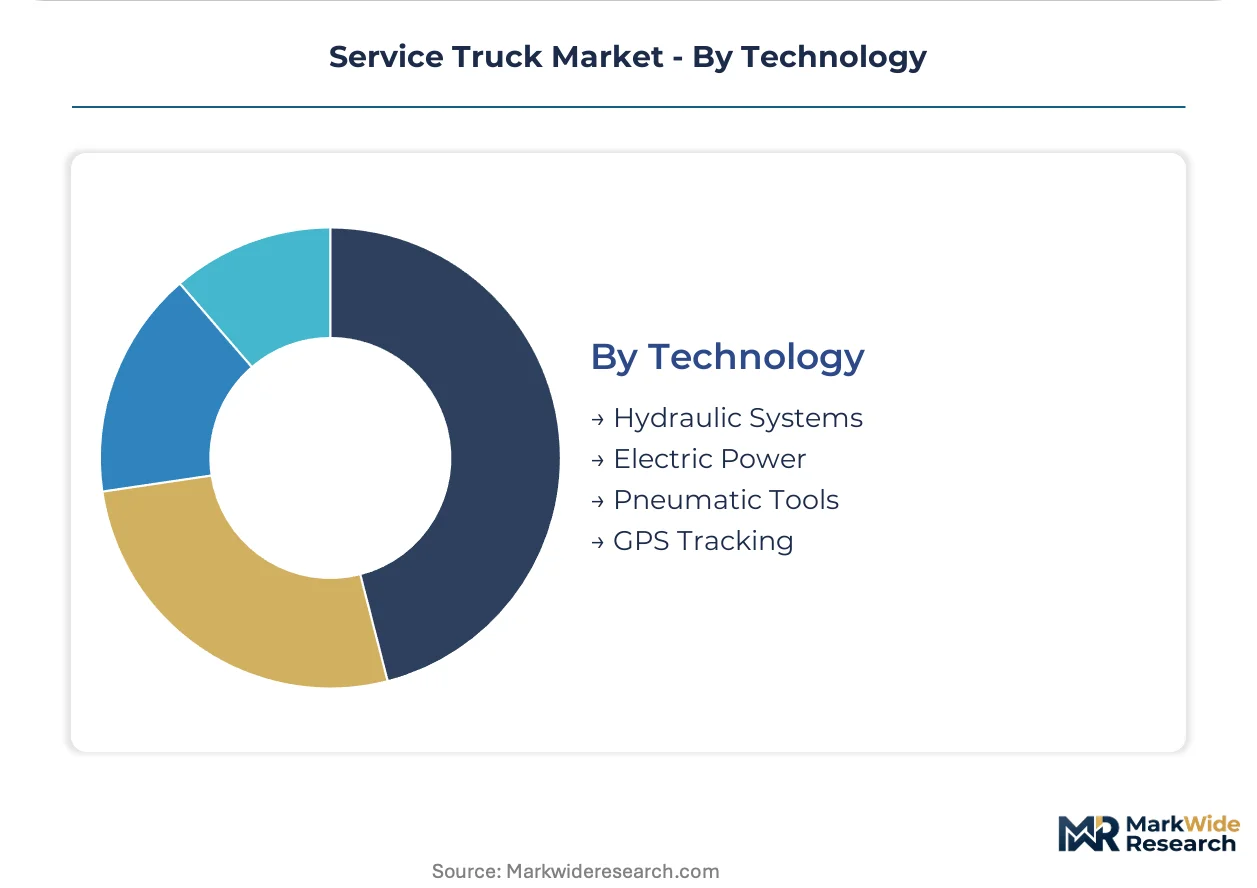
Technology:
Technology maturity separates proven hydraulic architectures from emerging electric power systems facing integration constraints.
- Hydraulic Systems:Conventional power take-off units deliver 50,000+ pound lift capacity for heavy aerial devices. Texas oilfield fleets resist electrification timelines due to hydraulic performance requirements.
- Electric Power:Battery-driven auxiliary systems eliminate idling emissions in California municipal noise zones. Los Angeles Department of Water and Power specifications mandate electric power take-off for new Class 6 acquisitions.
- Pneumatic Tools:Compressed air systems remain standard for tire service and general mechanical work across independent repair fleets.
- GPS Tracking:Real-time location and diagnostic monitoring enables outcome-based fleet management contracts with utilization guarantees.
Hydraulic Systems retain the largest installed base. Electric Power is gaining share fastest among urban utility specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The service truck industry traces its modern form to post-war American utility infrastructure expansion, when integrated chassis-body systems replaced horse-drawn maintenance wagons. Texas oilfield operations and California municipal electrification programs established the dual demand poles that still define procurement patterns. Geographic concentration now follows energy extraction zones and utility investment corridors.
United States
Texas Permian Basin operators deploy heavy-duty hydraulic fracturing service trucks for wellhead maintenance, while California utilities accelerate battery-electric chassis procurement under CARB mandates. EPA Phase 3 greenhouse gas regulations compress fleet replacement cycles nationwide. Houston anchors oilfield service truck demand, with local fabricators integrating 10,000-pound crane capacity into Class 8 platforms.
Germany
Industrial machinery maintenance fleets in the Ruhr region specify precision-engineered service vehicles for factory equipment repair. KBA vehicle type approval requirements govern auxiliary power take-off system certification. Bavarian automotive supplier networks deploy mobile maintenance trucks for just-in-time production line support across Munich-Stuttgart corridor manufacturing clusters.
China
State Grid Corporation electrification investments drive medium-duty service truck demand for transmission line maintenance across western provinces. MIIT new energy vehicle mandates accelerate electric chassis adoption in municipal utility fleets. Yangtze River Delta manufacturing clusters near Shanghai concentrate domestic body fabrication capacity for regional utility procurement.
Canada
Alberta oil sands extraction operations require all-terrain service trucks with extreme cold-weather hydraulic system specifications. Transport Canada CMVSS safety standards align with NHTSA brake performance requirements for cross-border fleet compatibility. Calgary-based energy service companies maintain regional equipment pools for remote wellsite maintenance operations.
Australia
Mining operations in Western Australia's Pilbara region demand heavy-duty service trucks with integrated welding and hose fabrication capabilities. National Heavy Vehicle Regulator mass limits influence axle configuration specifications for outback road train compatibility. Perth-based equipment distributors coordinate mobile maintenance fleet deployment across remote extraction sites.
Service Truck Market Competitive Landscape
Premium-margin players sit above commodity-margin players across body fabrication specialization and chassis integration depth. The market structures around three tiers: full-line chassis manufacturers with captive upfitting partnerships, independent body fabricators with standardized component platforms, and regional specialists serving single industry verticals. Dominant competitive moves include strategic chassis-body partnerships and modular platform standardization to reduce procurement complexity for fleet operators.
Among North American manufacturers, Ford Motor Company and Knapheide Manufacturing Company exemplify the chassis-body partnership archetype, while Isuzu Motors Limited represents diesel powertrain efficiency positioning in urban delivery applications. These entities occupy positions spanning integrated fleet supply and specialized component fabrication rather than competing directly across identical specification ranges.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| Oshkosh Corporation |
| Altec Industries Inc. |
| Mercedes-Benz |
| Dongfeng Motor Corporation |
| Isuzu Motors Limited |
| Knapheide Manufacturing Company |
| Volvo Trucks |
| Others |
Pricing and Supply Chain Analysis
Utility fleet procurement concentration in California and Texas anchors contract-based long-term offtake pricing for heavy-duty chassis, compressing margin flexibility for regional body fabricators serving price-sensitive municipal segments. Steel input volatility and EPA compliance costs are reshaping how upfitters structure component sourcing against fixed-price fleet agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated chassis-body packages from modular upfit configurations and bare chassis transactions. Price differentiation rests on CARB certification tier and hydraulic system integration depth, with premium tiers commanding substantial markups for zero-emission compliance. Cost compression in the standard tier is intensifying because lithium-ion battery price volatility erodes electric chassis margins. Municipal fleets exhibit highest price sensitivity, while Permian Basin oilfield operators prioritize payload capacity over unit cost.
Supply Chain Analysis
Direct-to-fleet channels handle utility and oilfield buyer demand, bypassing traditional dealer networks for specification-heavy orders. Geographic supply concentration centers on the United States, Mexico, and Canada for chassis assembly, with domestic steel mill capacity in Indiana and Ohio feeding body fabrication. Raw material dependencies draw from North American steel coil, hydraulic pump assemblies, and battery cell imports. Single-source vulnerability in specialized aerial device components creates delivery risk. Distribution runs through OEM-captive upfitting partnerships and independent fabricator networks serving regional fleet pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market depends on modular platform standardization reducing procurement complexity, while electric powertrain integration opens premium-tier positioning for CARB-compliant specifications.
For Market Incumbents: Cement chassis-body partnership exclusivity through multi-year fleet maintenance bundling, locking out modular competitors from California utility procurement. Deepen captive supply of hydraulic system components to offset steel price volatility. Defend against emerging electric specialist entrants by accelerating high-voltage technician certification programs before zero-emission mandates tighten. For New Entrants and Emerging Players: Rural broadband deployment contractors represent an underserved buyer archetype with limited incumbent coverage and USDA financing availability. Target municipal fleets in underserved counties lacking integrated service providers. Penetrate through telematics-enabled outcome-based contracts that shift capital burden from cash-constrained buyers. For Investors and Strategic Acquirers: Chassis manufacturers with captive upfitting capabilities are the most active acquirer in this space, seeking body fabrication depth to capture margin pools. Long-term viability favors specialists with electric powertrain integration expertise and CARB certification infrastructure. Watch California investor-owned utility RFP timelines as the inflection indicator for electric chassis adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Ford and Knapheide partnerships demonstrate reduced procurement complexity for multi-fleet operators. |
| Electric Powertrain Integration | Los Angeles Department of Water and Power mandates are pulling forward battery-electric Class 6 specifications. |
| Outcome-Based Fleet Contracts | Pacific Gas and Electric bundles maintenance and uptime guarantees into per-mile fees, transferring battery risk. |
| Backward Integration into Hydraulics | Texas oilfield fabricators source power take-off systems directly to secure lift capacity for fracturing fleet demand. |
| Telematics Platform Convergence | Real-time diagnostic monitoring enables rapid body reconfiguration across Verizon and AT&T mixed fleet pools. |
Research Methodology
Multiple input streams — fleet procurement managers, body fabrication engineers, utility electrification planners, and chassis OEM product directors — were reconciled against regulatory filing databases and utility RFP archives. Primary interviews with maintenance directors at investor-owned utilities and oilfield service fleet operators were validated against secondary sources including EPA Phase 3 regulatory dockets, CARB advanced clean trucks rulemakings, and NHTSA commercial vehicle safety standards. Bottom-up chassis shipment analysis and top-down fleet replacement cycle modeling were triangulated to cross-verify volume estimates.
Historical replacement patterns were cross-referenced against expert panel input on electrification timeline compression. The analytical framework segmented across vehicle class, powertrain architecture, end-use vertical, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from duty cycle intensity projections and fleet turnover velocity assumptions. Key inputs included utility electrification procurement schedules and oilfield equipment maintenance demand correlations with Permian Basin drilling activity.
Inputs from EPA and CARB regulatory dockets were available through the study window; gaps in fleet-level telematics utilization data introduce uncertainty bands around electric chassis adoption velocity. Forecasts reflect assumptions on charging infrastructure deployment pace and battery cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Electric Truck Market