
 Europe Vacuum Pump Market | 2026-2036
Europe Vacuum Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vacuum Pump Market Insights
Project finance for semiconductor fabs is reshaping procurement patterns across the Europe vacuum pump landscape. Atlas Copco AB leverages its oil-free compressor heritage to extend into dry vacuum systems for EU lithography projects. Leybold GmbH anchors its position through captive service networks spanning Dresden and Eindhoven. Edwards Vacuum differentiates via semiconductor-specific contamination control protocols that align with foundry qualification timelines.
A vacuum pump is a mechanical device that evacuates gas molecules from a sealed volume to create pressure below atmospheric levels, typically achieving ultimate pressures from rough vacuum (above 10⁻³ mbar) through high and ultra-high vacuum regimes (below 10⁻⁷ mbar) using rotary vane, scroll, or turbomolecular mechanisms. Its primary industrial purpose centers on process environment control, where precise pressure regimes enable thin-film deposition, electron beam processing, and sterile packaging operations. Rotary vane pumps still occupy the largest installed base across European chemical processing, though scroll technology is displacing legacy wet pumps in food packaging lines where oil contamination risks trigger regulatory non-compliance. Semiconductor manufacturing applications command the highest margin pools, with kinetic transfer pumps dominating front-end wafer fabrication while positive displacement units sustain back-end packaging operations.
The EU F-Gas Regulation and REACH framework restrict fluorinated sealing materials and lubricants, forcing redesigns of liquid ring and rotary vane architectures toward fluorine-free chemistries. CE marking under the Machinery Directive governs safety integration for pumps deployed in pharmaceutical cleanrooms, while Germany's KBA enforces leak-rate standards for automotive battery vacuum drying cells. Stakeholders must monitor how the EU Chips Act funding tranches alter equipment qualification timelines and local content requirements for vacuum subsystem suppliers.
Market Dynamics
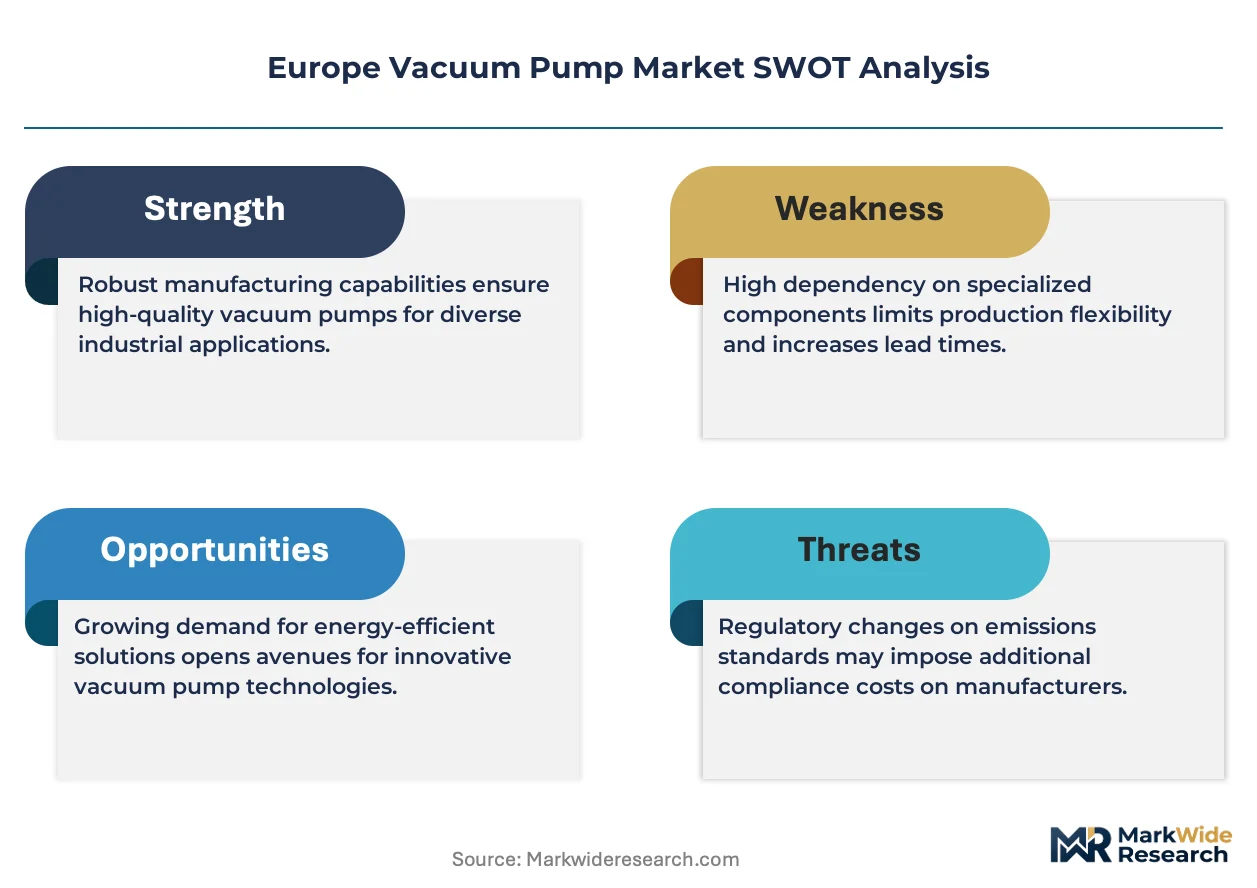
EU chip sovereignty mandates are rerouting capital toward lithography-adjacent vacuum infrastructure, compressing qualification timelines for dry pump architectures that eliminate fluorinated chemistries from front-end wafer processing.
Growth Catalysts
- EU Chips Act funding tranches:Direct capital allocation to Dresden and Eindhoven cleanroom clusters accelerates vacuum subsystem procurement cycles for advanced node fabrication.
- F-Gas Regulation phase-down:Binding fluorinated gas reduction targets force fabs toward oil-free dry pump technologies, eliminating legacy wet pump installed bases.
- Lithography tool clustering:ASML's Veldhoven ecosystem concentrates demand for ultra-high vacuum kinetic transfer pumps within a 100-kilometer Benelux corridor.
Market Restraints
- Specialized alloy supply concentration:High-purity stainless steel and nickel-based superalloys for turbomolecular rotors source predominantly from German and Austrian metallurgical suppliers, creating single-point vulnerability.
- REACH compliance friction:Fluorine-free lubricant reformulation timelines lag pump redesign schedules, delaying CE marking for rotary vane architectures.
- Technical limitation in hydrogen handling:Existing dry pump sealing technologies face degradation thresholds below 10⁻⁶ mbar in hydrogen-rich etch processes, constraining adoption in emerging atomic layer deposition lines.
Strategic Opportunities
- Poland and Czechia fab greenfield sites:EU structural funds for semiconductor manufacturing in Central Europe create first-mover vacuum infrastructure contracts outside established Benelux-Dresden axis.
- Battery cell vacuum drying:Automotive gigafactory buildouts in Hungary and Germany apply semiconductor-grade vacuum protocols to electrode drying, transferring technical specifications across verticals.
- CSRD disclosure mandates:Corporate sustainability reporting requirements create aftermarket service revenue streams for pump efficiency auditing and carbon footprint documentation.
Industry Challenges
- Turbomolecular bearing specialist scarcity:Magnetic levitation and ceramic ball bearing expertise concentrates among German and Swiss engineering pools, constraining workforce scaling for production ramp.
- Foundry qualification timeline compression:EU Chips Act disbursement schedules force vacuum subsystem validation into 18-month windows versus historical 36-month cycles, elevating field failure risk.
- Legacy wet pump retrofit complexity:Chemical processing installed bases in Rotterdam-Antwerp corridor face production downtime conflicts during fluorinated lubricant elimination upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vacuum Pump Market |
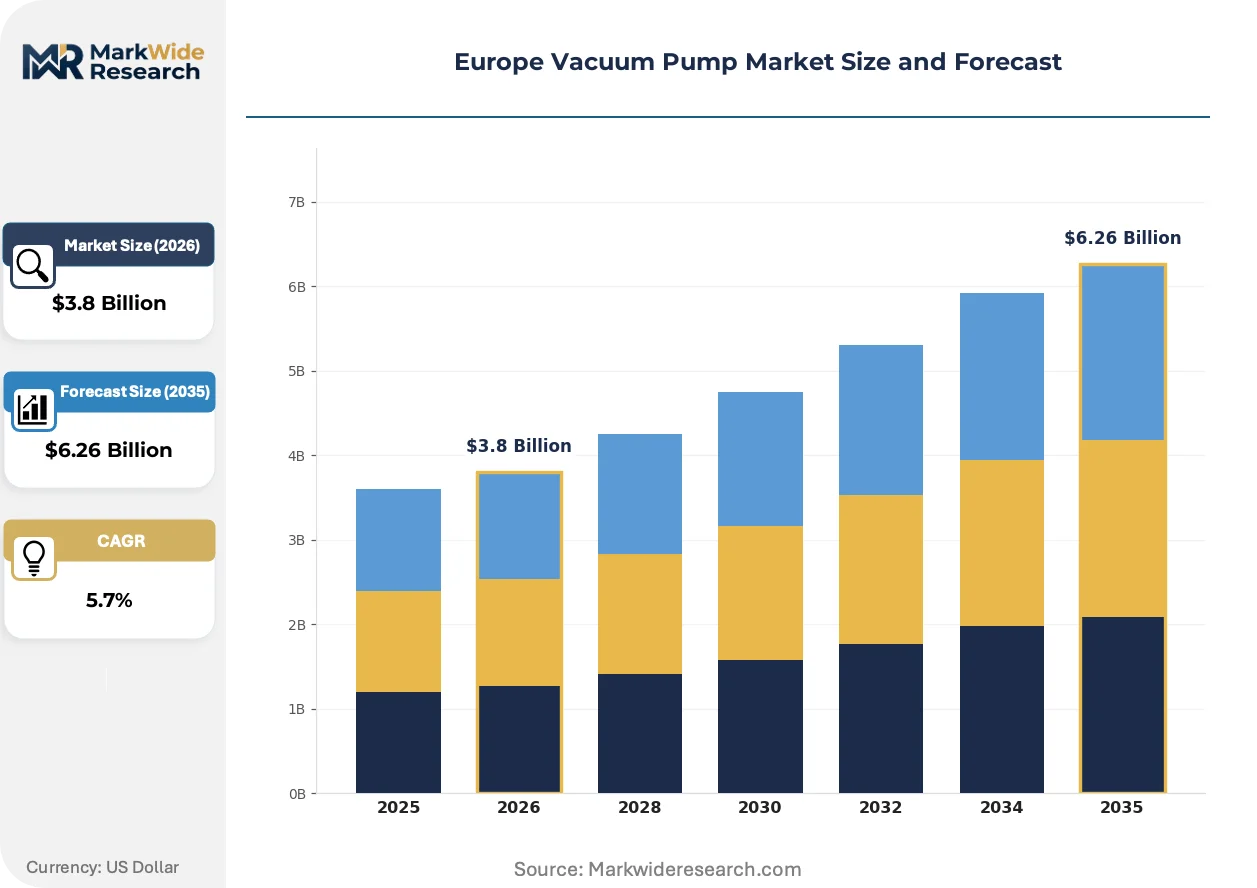
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Vane, Diaphragm, Scroll, Liquid Ring Application: Semiconductor Manufacturing, Food Packaging, Chemical Processing, Medical Equipment End User: Aerospace, Automotive OEMs, Pharmaceuticals, Electronics Operating Principle: Positive Displacement, Kinetic, Thermal, Molecular |
| Companies Covered | Atlas Copco AB, Edwards Vacuum, Leybold GmbH, Pfeiffer Vacuum GmbH, Busch Vacuum Solutions, Gebr. Becker GmbH, Flowserve Corporation, Bosch Rexroth AG, SIHI Group B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vacuum Pump Market Trends and Innovations
Hybrid pump architectures that combine positive displacement and kinetic transfer stages are compressing footprint requirements while EU regulatory chemistry bans force materials science innovation in sealing and lubrication systems.
Scroll pump technology is hybridizing with turbomolecular booster stages to deliver oil-free roughing performance for electron beam lithography tools. ASML's tier-one suppliers in the Netherlands and Germany are qualifying these integrated systems for 300mm wafer processing. The convergence is collapsing traditional pump-train footprints by eliminating separate backing pump configurations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling reformulation of rotary vane pump lubricants toward synthetic hydrocarbon and polyether chemistries. German pump OEMs face 18-month requalification cycles for food-contact and pharmaceutical applications. The regulatory pressure is most acute in Hesse and Bavaria packaging corridors where CE-marked pumps require updated safety data sheets.
Service contract unbundling is fragmenting traditional captive maintenance relationships as foundry procurement teams separate vacuum hardware from predictive maintenance analytics. Dutch semiconductor fabs are piloting third-party IoT monitoring platforms that displace OEM service agreements. The behavioral shift is most visible in Eindhoven's High Tech Campus where shared service models pool pump uptime data across competing foundry tenants.
Europe Vacuum Pump Market Segmentation
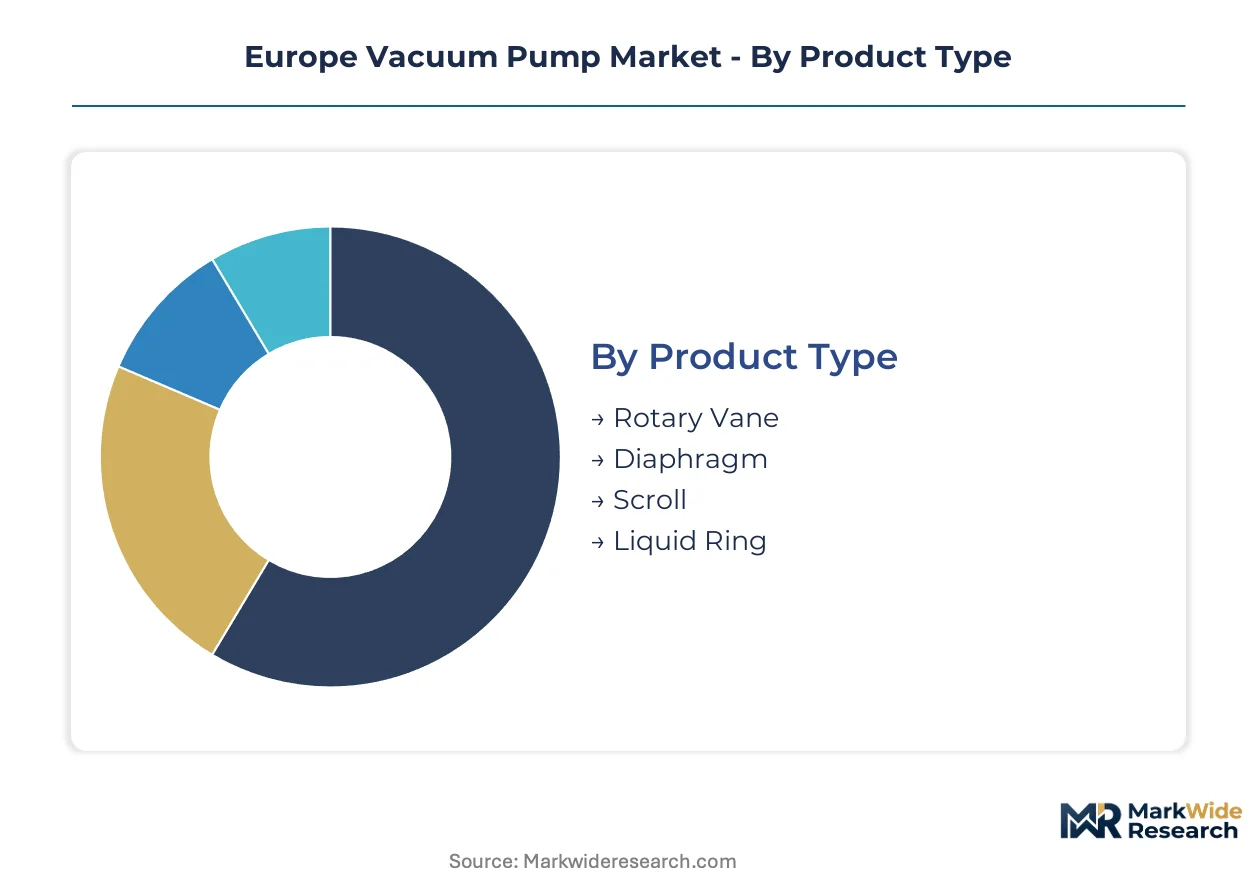
Vacuum pump procurement patterns diverge sharply across end-use verticals, with semiconductor fabs demanding predictive maintenance contracts while chemical processors prioritize spare parts availability. Service intensity and qualification timelines vary by segment, reshaping how OEMs structure aftermarket revenue streams across the European installed base.
Product Type:
After-sales service intensity escalates dramatically with pump complexity, with turbomolecular and scroll architectures requiring specialized technician networks that rotary vane suppliers struggle to replicate.
- Rotary Vane:Oil-sealed positive displacement pumps dominate chemical processing installed bases across the Rotterdam-Antwerp corridor. REACH Annex XVII fluorinated lubricant bans force German OEMs through 18-month reformulation cycles, compressing margin pools for legacy wet pump architectures.
- Scroll:Oil-free orbital scroll mechanisms displace rotary vane units in food packaging lines where HACCP compliance mandates zero contamination risk. Benelux dairy packaging clusters near Groningen and Leeuwarden drive fastest replacement cycles as CE-marked scroll pumps eliminate oil vapor recovery systems.
- Diaphragm:Dry-running elastomer-diaphragm pumps serve pharmaceutical tablet coating operations in Hesse and Bavaria where batch integrity trumps pumping speed.
- Liquid Ring:Water-sealed systems sustain ethylene cracking vacuum distillation at Ludwigshafen and Antwerp petrochemical complexes.
Rotary Vane holds the largest share; momentum sits with Scroll.
Application:
Margin tiering separates front-end wafer fabrication from back-end packaging, with lithography tool integration commanding 3-4x service contract premiums over food packaging deployments.
- Semiconductor Manufacturing:EUV lithography tools require kinetic transfer pumps achieving 10⁻⁸ mbar base pressures with magnetic levitation bearings. Dresden and Eindhoven cleanroom clusters concentrate demand within ASML's supplier ecosystem, where qualification timelines compress to 18 months under EU Chips Act disbursement schedules.
- Food Packaging:Modified atmosphere packaging lines in Northern Italy and Denmark apply rough vacuum regimes for oxygen evacuation. Scroll and diaphragm architectures displace oil-sealed alternatives as F-Gas Regulation phase-downs eliminate fluorinated sealing chemistries from food-contact applications.
- Chemical Processing:Corrosion-resistant liquid ring pumps handle chlorine and hydrogen fluoride streams at BASF Ludwigshafen and INEOS Antwerp.
- Medical Equipment:Sterile suction and autoclave evacuation systems in German university hospitals specify oil-free diaphragm pumps with FDA-equivalent MDR Class IIa certification.
Semiconductor Manufacturing commands premium pricing; Food Packaging expands most quickly.
End User:
Customer concentration patterns determine contract structure, with aerospace primes demanding fixed-price overhaul agreements while automotive OEMs push unit-cost reduction through multi-year frame contracts.
- Automotive OEMs:Battery cell vacuum drying at Hungarian and German gigafactories applies semiconductor-grade turbomolecular pumping to electrode solvent evacuation. KBA leak-rate standards for automotive battery cells transfer metrology protocols from wafer fabrication to gigafactory quality systems.
- Pharmaceuticals:Sterile manufacturing suites in Basel and Cambridge require oil-free scroll pumps with continuous particle monitoring. MDR Annex I general safety and performance requirements govern vacuum subsystem validation for aseptic filling lines.
- Aerospace:Satellite thermal vacuum chambers at Airbus Defence and Space Toulouse specify cryogenic pumping trains for space simulation.
- Electronics:Display panel OLED evaporation systems in South Korean-owned Slovakian fabs import Korean vacuum specifications into EU regulatory frameworks.
Pharmaceuticals holds the largest share; Automotive OEMs climbs the fastest.
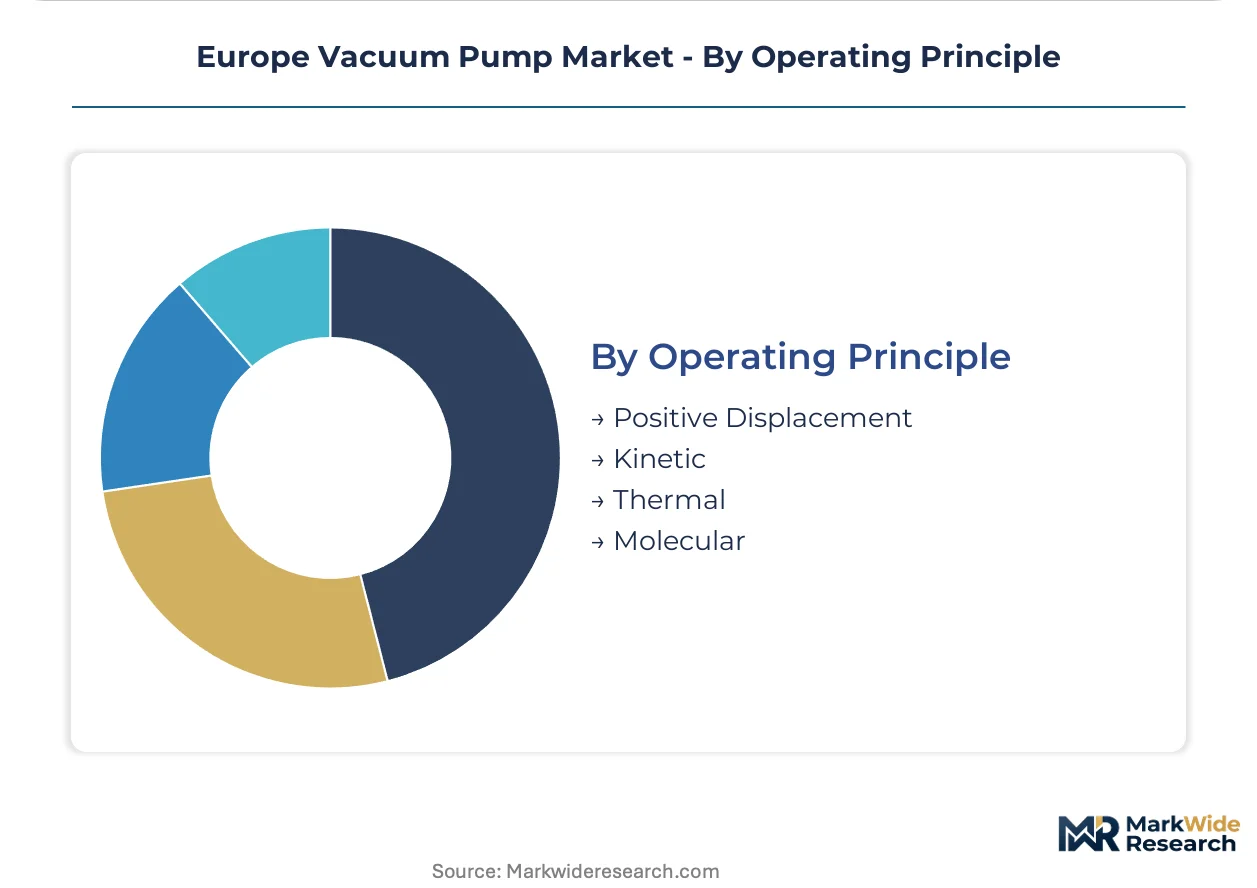
Operating Principle:
Volume scaling potential concentrates in positive displacement architectures where manufacturing tolerances permit Central European production expansion, while kinetic transfer pumps face magnetic bearing specialist scarcity.
- Positive Displacement:Rotary vane, scroll, and diaphragm mechanisms sustain rough and medium vacuum regimes across 80% of European installed base. Polish and Czech pump assemblers exploit EU structural funds to capture share from German and Dutch incumbents in standard industrial applications.
- Kinetic:Turbomolecular and diffusion pumps achieve ultra-high vacuum for electron microscopy and mass spectrometry. Swiss and German magnetic levitation bearing expertise constrains production scaling for semiconductor front-end applications.
- Thermal:Sorption pumps using zeolite or activated carbon capture gases through cryogenic condensation in space simulation chambers.
- Molecular:Ion, getter, and cryopump technologies sustain 10⁻¹⁰ mbar regimes for particle accelerator beam lines at CERN Geneva.
Positive Displacement holds the largest share; Kinetic gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Chips Act is redistributing vacuum pump procurement across national cleanroom clusters, with funding tranches accelerating equipment qualification timelines in semiconductor manufacturing corridors.
Germany
Dresden's Silicon Saxony cluster drives turbomolecular pump demand for advanced node fabrication. KBA leak-rate standards for automotive battery cells transfer metrology protocols from wafer fabrication to gigafactory quality systems. Bavarian pump assemblers in Nuremberg exploit proximity to Siemens Energy and Infineon supply chains.
Netherlands
ASML's Veldhoven headquarters concentrates EUV lithography vacuum subsystem demand within a 100-kilometer supplier radius. REACH Annex XVII fluorinated lubricant bans force Dutch OEMs through reformulation cycles for rotary vane architectures. Eindhoven's High Tech Campus pools pump uptime data across competing foundry tenants.
Belgium
Antwerp's petrochemical complex sustains liquid ring pump demand for ethylene cracking vacuum distillation. F-Gas Regulation phase-downs eliminate fluorinated sealing chemistries from INEOS processing lines. Flanders packaging corridors near Ghent apply CE-marked scroll pumps for modified atmosphere food lines.
Poland
EU structural funds for semiconductor manufacturing in Central Europe create first-mover vacuum infrastructure contracts outside established Benelux-Dresden axis. Polish pump assemblers capture share from German incumbents in standard industrial applications. Lower Silesian manufacturing zones near Wrocław attract battery cell gigafactory investments.
France
Airbus Defence and Space Toulouse specifies cryogenic pumping trains for satellite thermal vacuum chambers. CSRD disclosure mandates create aftermarket service revenue streams for pump efficiency auditing. Île-de-France pharmaceutical clusters demand oil-free diaphragm pumps with MDR Class IIa certification.
Europe Vacuum Pump Market Competitive Landscape
On the supply side, the industry is consolidating around captive service networks and semiconductor-specific qualification protocols. Swedish and German engineering groups anchor premium-tier positioning through magnetic levitation bearing expertise. Three archetypes dominate: integrated compressor-to-vacuum diversifiers, lithography-adjacent subsystem specialists, and regional service-intensive incumbents. Competitive moves center on portfolio diversification into dry pump architectures and geographic expansion toward Central European fab greenfields.
Within the integrated engineering tier, Atlas Copco AB exemplifies compressor heritage extension into dry vacuum systems. Among Germany-based vacuum specialists, Leybold GmbH and Pfeiffer Vacuum GmbH occupy positions defined by proximity to Dresden and Veldhoven cleanroom clusters. Edwards Vacuum represents the contamination-control archetype, with qualification protocols aligned to foundry timeline compression.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Edwards Vacuum |
| Leybold GmbH |
| Pfeiffer Vacuum GmbH |
| Busch Vacuum Solutions |
| Gebr. Becker GmbH |
| Flowserve Corporation |
| Bosch Rexroth AG |
| SIHI Group B.V. |
| Others |
Pricing and Supply Chain Analysis
German and Austrian metallurgical suppliers dominate high-purity stainless steel and nickel-based superalloy feedstocks for turbomolecular rotors, anchoring margin capture in semiconductor-grade pump tiers while compressing pricing flexibility for mid-range architectures serving chemical processing.
Pricing Analysis
Certification level creates the primary spread between semiconductor-grade and industrial pump tiers, with CE marking under the Machinery Directive and MDR Class IIa medical certification commanding substantial premiums over standard industrial configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by magnetic levitation bearing complexity, contamination control protocol stringency, and predictive maintenance bundling. Cost compression in standard rotary vane architectures intensifies as Polish and Czech assemblers exploit EU structural funds to undercut German incumbents on unit pricing. Automotive OEMs exhibit highest price sensitivity through multi-year frame contracts, while pharmaceutical cleanroom operators accept premium positioning for batch integrity assurance.
Supply Chain Analysis
High-purity stainless steel feedstocks source predominantly from German and Austrian specialty metallurgical suppliers, with magnetic levitation bearing assemblies concentrating among Swiss and German engineering pools. Ceramic ball bearing production rests on Japanese and German precision manufacturing capabilities, while fluorine-free lubricant formulations draw from Belgian and Dutch chemical compounders. Single-source vulnerability concentrates in turbomolecular rotor forging capacity, where qualification timelines for alternative suppliers extend beyond EU Chips Act disbursement windows. Distribution runs through captive OEM service networks in Dresden and Eindhoven for semiconductor applications, contrasting with third-party industrial distributors for chemical processing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply across Central European fab greenfields as EU structural funds disperse semiconductor manufacturing beyond the established Benelux-Dresden corridor, creating niches for specialized vacuum subsystem suppliers.
For Market Incumbents: Harden qualification protocol advantages by compressing foundry validation cycles below 18-month EU Chips Act windows through pre-integrated contamination control architectures. Deepen backward integration into magnetic levitation bearing production to offset Swiss and German specialist scarcity threatening capacity scaling. Lock in long-term service contracts with Eindhoven High Tech Campus foundries before third-party IoT monitoring platforms displace OEM captive relationships.
For New Entrants and Emerging Players: Build out Poland and Czechia service infrastructure to capture first-mover vacuum infrastructure contracts at EU-funded fab greenfield sites outside established supply corridors. Target battery cell gigafactory vacuum drying applications in Hungary and Lower Silesia, where semiconductor-grade specifications transfer to automotive quality systems without lithography-tool qualification barriers. Lead with outcome-based service contracts that bundle hardware efficiency guarantees with CSRD-mandated carbon footprint documentation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial pump specialists possessing regional service networks but lacking semiconductor qualification credentials. Five-to-ten-year viability hinges on EU chip sovereignty sustaining capital allocation to lithography-adjacent vacuum infrastructure beyond initial EU Chips Act tranches. Watch for F-Gas Regulation enforcement acceleration as inflection indicator forcing replacement demand in legacy wet pump installed bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Lubricant Reformulation | REACH Annex XVII compliance unlocks CE marking for rotary vane architectures in food-contact applications. |
| Magnetic Levitation Bearing In-Housing | Captive production of Swiss-grade turbomolecular components reduces specialist dependency for semiconductor front-end pumps. |
| Central European Service Network Expansion | Polish and Czech technician pools capture EU structural fund-driven fab investments outside Benelux-Dresden axis. |
| Predictive Maintenance Platform Unbundling | Third-party IoT monitoring displaces OEM service agreements at Eindhoven High Tech Campus foundry clusters. |
| Battery Cell Vacuum Diversification | Hungarian and German gigafactory electrode drying applies semiconductor-grade turbomolecular protocols to automotive quality systems. |
Research Methodology
The analysis maps rotary vane, scroll, diaphragm, and turbomolecular pump sub-sectors, each validated through semiconductor fab procurement directors, chemical processing plant engineers, pharmaceutical manufacturing heads, and aftermarket service managers. Primary fieldwork combined structured interviews with OEM technical directors and foundry qualification specialists across Dresden, Veldhoven, and Eindhoven clusters. Secondary validation drew from ECHA REACH substance restrictions, EU Chips Act funding disbursement schedules, CE marking documentation under the Machinery Directive, and customs trade data for high-purity alloy imports. Bottom-up installed base sizing triangulated against top-down semiconductor capital equipment forecasts.
Assumption sets held EU F-Gas Regulation phase-down schedules and REACH Annex XVII enforcement timelines as fixed boundary conditions while varying EU Chips Act disbursement velocity and Central European fab construction cadence across sensitivity scenarios. Segmentation modeling captured product type, application vertical, end-user industry, and operating principle dimensions alongside geographic production cluster proximity to ASML's supplier ecosystem. CAGRs derived from equipment procurement cycle analysis correlated with foundry qualification timeline compression. Industry-specific inputs included magnetic levitation bearing production capacity constraints and fluorine-free lubricant reformulation lead times.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mid-cap specialists or accelerated Polish and Czech assembler scaling would shift outcomes. Material shifts in EU Chips Act funding allocation toward battery cell manufacturing away from semiconductor front-end fabrication, or breakthrough hydrogen-compatible dry pump sealing technologies, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Air Bearings Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Digital Servo Press Market