
 Cable Granulator Market | 2026-2036
Cable Granulator Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Granulator Market Outlook
The split between premium precision granulators and commodity shredding lines is hardening as copper purity standards diverge across customer tiers. Herbold leverages its German engineering base to dominate high-throughput wet granulation systems for industrial cable processors. WEIMA competes through modular machine architecture that lets scrap yards scale capacity incrementally without full line replacement.
A cable granulator is an industrial shredding and separation system that reduces insulated copper or aluminum cables into granular metal and plastic fractions through mechanical cutting, density separation, and often electrostatic or magnetic refinement stages; typical units process 500 kg to 5 tonnes per hour with purity targets exceeding 99.5% copper for smelter acceptance. Dry granulator configurations lead installed base volumes due to lower water treatment overhead, though electrostatic technology lines capture expanding share as Chinese and Southeast Asian operators face tighter effluent rules. Recycling facilities represent the deepest end-user margin pool because they internalize both feedstock arbitrage and refined copper resale economics rather than contracting processing services.
The EPA oversees hazardous waste classifications for cable insulation containing legacy flame retardants in the United States, while REACH restricts certain phthalate plasticizers in European cable scrap streams, and China's MEE enforces emissions controls on thermal separation processes that push operators toward mechanical and electrostatic alternatives. Stakeholders must track how copper scrap import quota volatility across major economies reshapes regional equipment utilization rates and replacement cycles.
Market Dynamics
Copper purity thresholds are bifurcating the Cable Granulator Market into two distinct equipment tiers, as smelters tighten feedstock specifications while scrap processors absorb price volatility from import quota fluctuations.
Growth Catalysts
- EU WEEE Directive mandates:Extended producer responsibility frameworks in Germany and France compel electronics manufacturers to finance cable collection infrastructure, directly stimulating granulator procurement by certified recyclers.
- Urban mining initiatives:State-backed programs in China prioritize domestic metal recovery over scrap imports, accelerating deployment of high-capacity dry separation lines at provincial processing hubs.
- Automotive wiring harness recovery:End-of-life electric vehicle dismantling operations require specialized granulation for mixed copper-aluminum harnesses, creating dedicated equipment demand from vehicle shredder operators.
Market Restraints
- Copper scrap import quota volatility:China's Ministry of Ecology and Environment (MEE) adjusts inbound material allowances unpredictably, forcing processors to idle capacity or pivot feedstock sourcing.
- Electrostatic separation capex intensity:Wet granulation lines with closed-loop water treatment demand capital outlays that exclude smaller scrap yard operators from compliance with tightening effluent rules.
- Legacy flame retardant contamination:Cable insulation containing halogenated compounds triggers EPA hazardous waste classifications in the United States, adding disposal costs that erode processing margins.
Strategic Opportunities
- Modular equipment architecture:Scalable machine configurations allow Southeast Asian operators to expand throughput incrementally without full line replacement, reducing barrier-to-entry for mid-tier processors.
- REACH plasticizer restrictions:Phthalate bans in European cable scrap streams create demand for advanced density separation capable of isolating contaminated polymer fractions for alternative recovery pathways.
- Industrial symbiosis clusters:Co-location of granulators with copper smelters and compounders in China's Yangtze River Delta enables just-in-time metal delivery and reduced logistics overhead.
Industry Challenges
- Electrostatic technician scarcity:Operation of high-voltage separation stages requires specialized training that outpaces vocational program output in emerging recycling markets.
- Smelter certification timelines:Achieving 99.5% copper purity validation for major non-ferrous metal consumers involves extended sample testing protocols that delay revenue recognition.
- Legacy mechanical system integration:Retrofitting electrostatic refinement stages into existing dry granulation lines creates throughput mismatches and material handling bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Granulator Market |
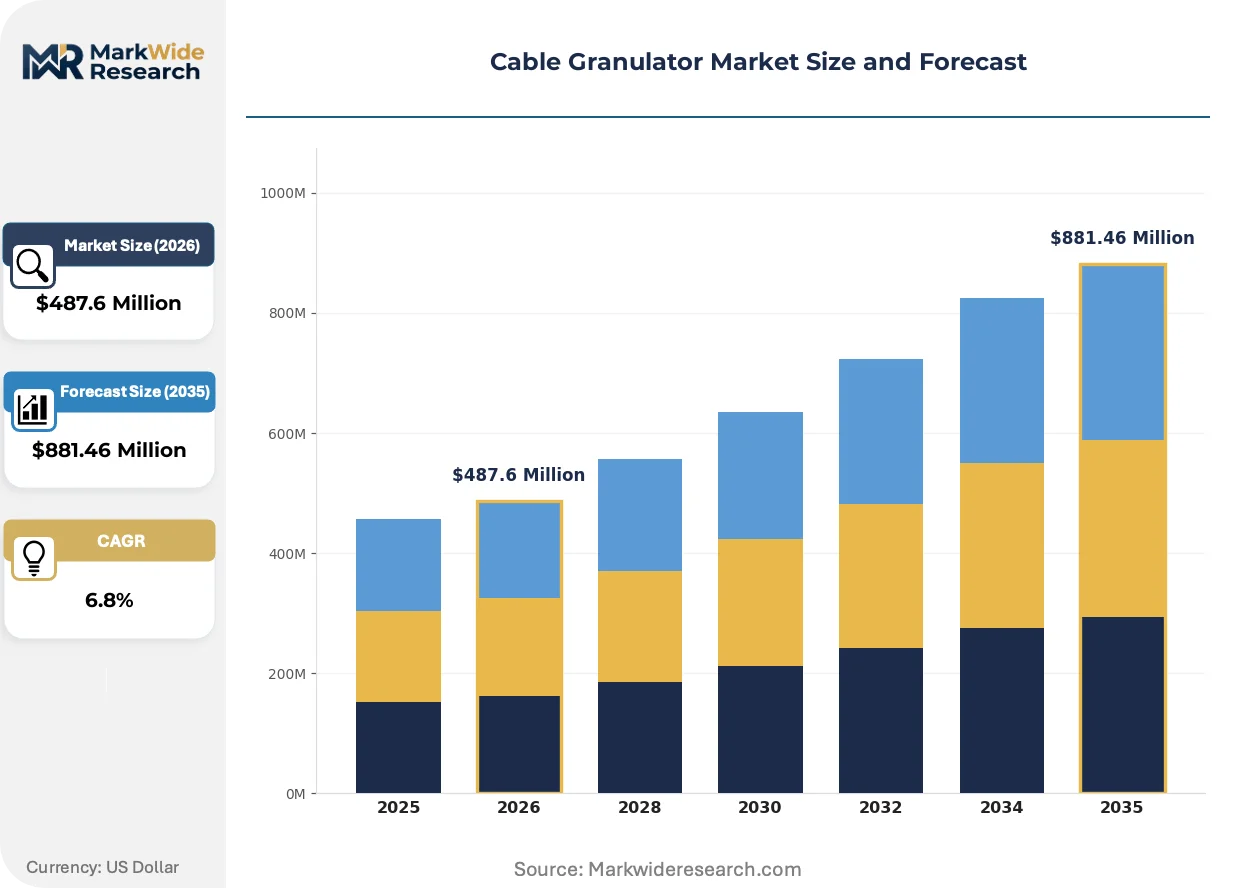
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
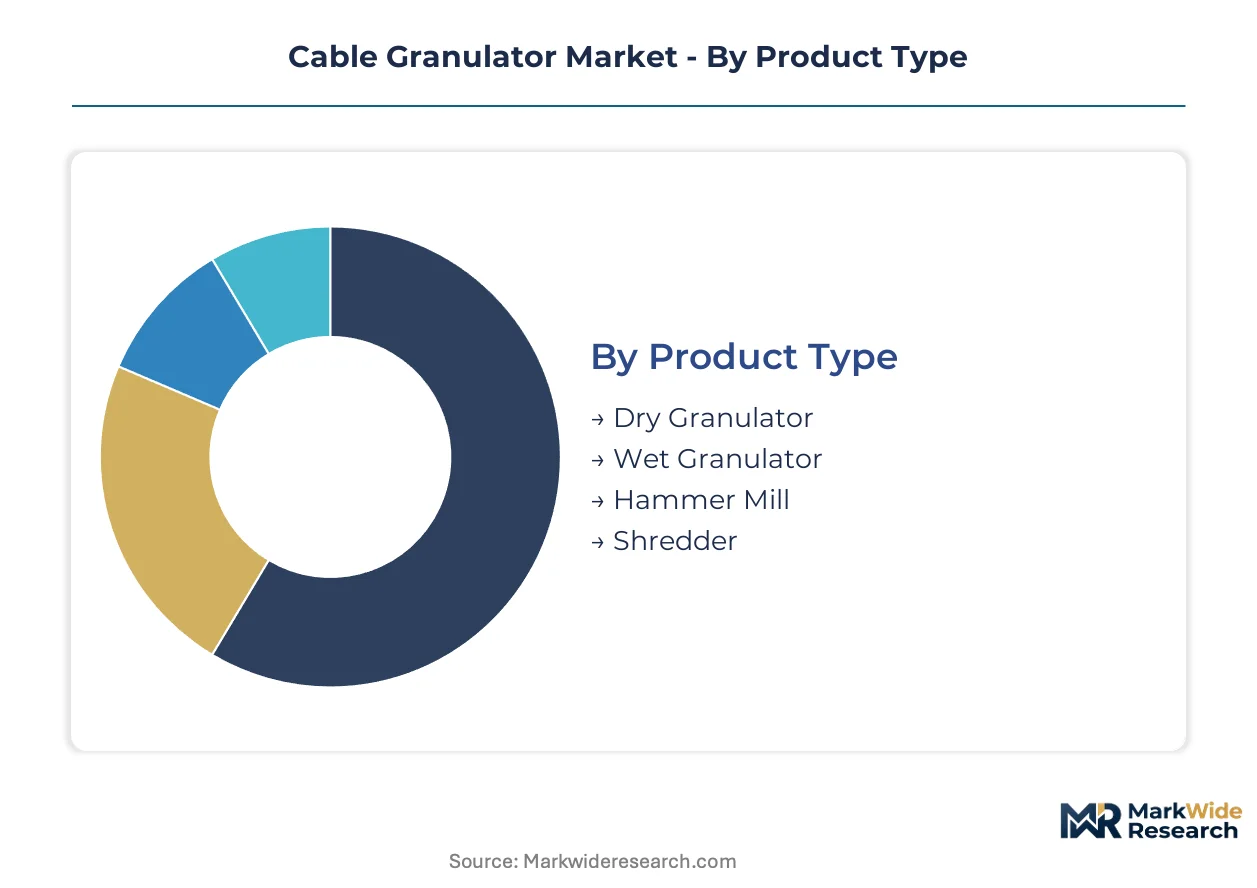
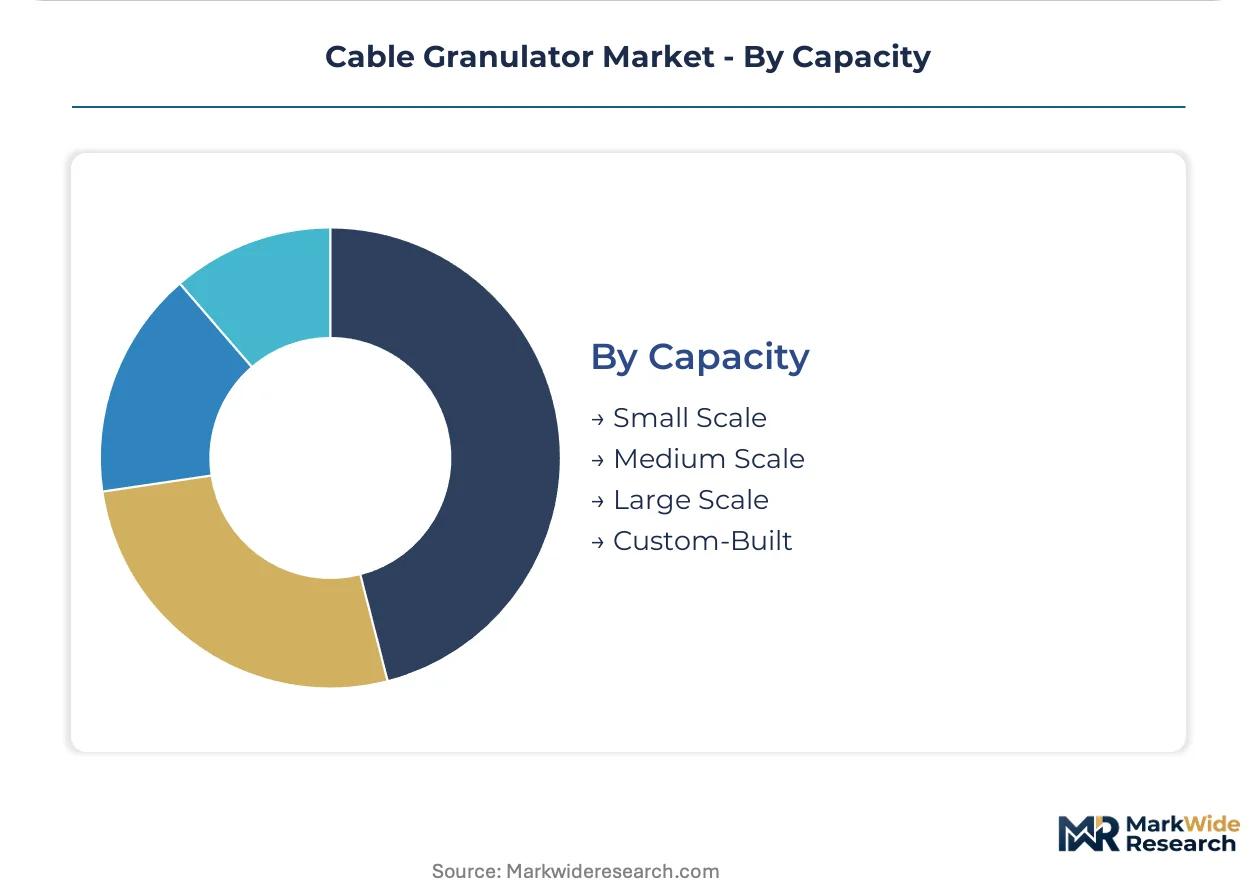
| Segmentation | Product Type: Dry Granulator, Wet Granulator, Hammer Mill, Shredder Technology: Mechanical, Electrostatic, Magnetism, Thermal End User: Recycling Facilities, Industrial Manufacturers, Waste Management Companies, Scrap Processors Capacity: Small Scale, Medium Scale, Large Scale, Custom-Built |
| Companies Covered | Herbold, WEIMA, Guidetti, Metso, Gruber Getriebe, Andritz, Vecoplan, ERDWICH, Cumberland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Granulator Market Strategic Shifts
Mechanical separation technologies are displacing thermal alternatives as emissions enforcement tightens across major recycling jurisdictions, while equipment intelligence and service unbundling reshape buyer-supplier relationships.
Electrostatic refinement is electrifying copper-plastic separation efficiency in Cable Granulator Market deployments. Chinese and Southeast Asian operators facing MEE emissions controls are retrofitting electrostatic stages to existing dry lines. This convergence is compressing payback periods for mechanical-only configurations and elevating electrostatic technology to default specification status for new installations.
REACH enforcement against phthalate plasticizers in European cable scrap is redirecting processing investment toward multi-stage density separation. Recyclers in Germany and France must now isolate contaminated polymer fractions rather than commingle outputs. Smelter acceptance protocols are tightening accordingly, with compounders demanding certified polymer streams that legacy single-stage granulators cannot deliver.
Service contracts are unbundling from equipment sales as scrap yard operators prioritize uptime guarantees over capital ownership. Chinese state-owned recyclers and European industrial processors alike are adopting performance-based maintenance agreements that shift technical risk to OEM service networks. This procurement evolution concentrates service capability with manufacturers possessing regional spare parts logistics, disadvantaging pure equipment vendors without field engineering presence.
Cable Granulator Market Segmentation
Cable granulator procurement patterns diverge sharply between standardized commodity units and engineered configurations tailored to specific feedstock compositions. Equipment buyers now segment their vendor evaluations across four distinct dimensions that determine capital allocation priorities and operational economics.
Product Type:
Customization intensity varies from off-the-shelf dry units to fully engineered wet systems with integrated water treatment loops.
- Dry Granulator:Mechanical cutting and air classification systems process insulated cables without liquid separation stages. Chinese provincial recycling hubs deploy these configurations under MEE emissions protocols that discourage thermal alternatives. Water treatment overhead elimination compresses payback periods for operators in water-scarce regions.
- Wet Granulator:Density-based separation using water baths achieves superior copper-plastic fractionation for complex multi-layer cable constructions. German industrial processors favor Herbold-engineered wet lines when handling automotive wiring harnesses with mixed copper-aluminum content. Closed-loop water treatment capex excludes smaller scrap yards from this tier.
- Hammer Mill:Impact pulverization systems pre-reduce bulk cable feedstock ahead of secondary granulation stages.
- Shredder:Primary size reduction equipment handles unprocessed cable bales and industrial wire collections.
Most installed capacity flows through Dry Granulator configurations. Expansion is steepest in Wet Granulator systems as effluent regulations tighten across Southeast Asian processing zones.
Technology:
Capital deployment intensity rises from basic mechanical stages through precision electrostatic refinement systems.
- Mechanical:Cutting mills, granulators, and vibrating screens form the baseline separation architecture. These systems dominate legacy installations across European scrap processors operating under REACH cable scrap frameworks. Operational simplicity sustains preference where technical labor pools remain shallow.
- Electrostatic:High-voltage corona discharge separates copper and plastic particles by conductive properties. Chinese operators retrofit electrostatic stages to existing dry lines as MEE enforcement eliminates thermal alternatives. Technician scarcity for high-voltage system operation constrains deployment velocity in emerging markets.
- Magnetism:Magnetic drums and eddy current separators extract ferrous contamination and aluminum fractions from mixed cable streams.
- Thermal:Pyrolytic and incineration-based separation faces regulatory phase-out across jurisdictions with tightening emissions controls.
Mechanical technology retains the largest installed base. Electrostatic systems are climbing the fastest as retrofit demand accelerates in China and Southeast Asia.
End User:
Margin capture potential separates integrated metal recovery operations from fee-for-service processing contractors.
- Recycling Facilities:Dedicated cable processors internalize both feedstock arbitrage and refined copper resale economics. These operators command the deepest margin pools by capturing value across the full recovery chain. German and French certified recyclers procure premium granulation lines under EU WEEE Directive financing mechanisms.
- Industrial Manufacturers:Captive cable waste generators deploy in-house granulation for process scrap from electrical equipment production. Chinese state-backed urban mining initiatives subsidize provincial hub deployments at manufacturing cluster locations. Volume certainty from internal feedstock streams justifies higher equipment specification.
- Waste Management Companies:Diversified environmental service providers add cable processing as ancillary revenue streams.
- Scrap Processors:Merchant operators selling granulated output to smelters face copper scrap import quota volatility that idles capacity unpredictably.
Recycling Facilities account for the dominant share of premium equipment procurement. Industrial Manufacturers are gaining share fastest as vertical integration into metal recovery deepens across Chinese manufacturing bases.
Capacity:
Scale economics determine whether operators pursue modular incremental expansion or single-line high-throughput systems.
- Large Scale:Integrated lines processing multiple tonnes hourly serve centralized provincial recycling hubs. China's Yangtze River Delta industrial symbiosis clusters co-locate these systems with copper smelters for just-in-time metal delivery. Logistics overhead reduction justifies concentrated capital deployment.
- Custom-Built:Engineered configurations address specialized feedstock requirements including submarine cable armor or aerospace wire constructions. WEIMA's modular architecture allows Southeast Asian operators to scale throughput incrementally without full line replacement. Specification flexibility commands 40-60 percent capital premiums over standard configurations.
- Medium Scale:Mid-tier systems balance throughput and capital efficiency for regional processing operations.
- Small Scale:Entry-level units serve localized scrap collection points with limited feedstock aggregation.
Large Scale systems carry the heaviest installed base weight. Custom-Built configurations show the steepest expansion trajectory as feedstock complexity diversifies across electric vehicle dismantling operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electrostatic technicians concentrate in German industrial clusters and Chinese provincial hubs, creating talent asymmetries that shape equipment deployment patterns across major recycling jurisdictions.
Germany
Automotive wiring harness dismantling and REACH plasticizer enforcement drive wet granulator procurement. The ECHA restricts phthalate contamination in cable scrap streams, compelling recyclers to upgrade density separation stages. The Rhine-Ruhr industrial corridor hosts certified processors under EU WEEE Directive financing mechanisms.
China
State-backed urban mining programs and copper scrap import restrictions accelerate high-capacity dry line deployment. The MEE enforces emissions controls that eliminate thermal separation alternatives across provincial processing hubs. The Yangtze River Delta industrial symbiosis clusters co-locate granulators with copper smelters for just-in-time metal delivery.
United States
End-of-life vehicle shredder operators seek specialized granulation for mixed copper-aluminum harnesses as EV production scales. The EPA classifies halogenated flame retardant insulation as hazardous waste, adding disposal cost pressures. Midwestern metal recycling corridors concentrate processing capacity near Detroit automotive dismantling operations.
France
Extended producer responsibility frameworks mandate manufacturer financing of cable collection infrastructure. The EU WEEE Directive compels electronics OEMs to fund certified recycler equipment procurement. The Île-de-France region concentrates premium wet granulation deployments for complex multi-layer cable processing.
Vietnam
Mid-tier scrap processors adopt modular equipment architectures to scale throughput incrementally. Tightening MEE-aligned effluent rules in Southeast Asian processing zones elevate electrostatic retrofit demand. The Red River Delta industrial zones attract Chinese equipment vendors establishing regional service networks.
Cable Granulator Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Cable Granulator Market, creating a tiered structure where German engineering houses anchor premium wet systems while Asian fabricators dominate standardized dry configurations. The vendor base separates into three strategic archetypes: integrated industrial conglomerates with full-line capabilities, specialized granulation engineering firms, and regional machinery fabricators serving price-sensitive procurement. Consolidation pressures concentrate among mid-tier European specialists facing Chinese cost competition. Dominant competitive moves include geographic expansion through regional service partnerships and portfolio diversification into modular equipment architectures.
Among German engineering specialists, Herbold Meckesheim GmbH and Gruber Getriebe GmbH exemplify the precision wet granulation tier anchored in Baden-Württemberg's industrial machinery corridor. WEIMA Maschinenbau GmbH occupies a position representing modular scalability architecture for scrap yard operators. Chinese fabricators including Zhengzhou Shuli Machinery Co., Ltd. sit within the high-volume dry system segment serving provincial urban mining initiatives. These named entities represent archetype positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Herbold |
| WEIMA |
| Guidetti |
| Metso |
| Gruber Getriebe |
| Andritz |
| Vecoplan |
| ERDWICH |
| Cumberland |
| Others |
Value Chain & Pricing Dynamics
Premium wet granulation systems and commodity dry configurations diverge sharply in both capital deployment and aftermarket service economics, with German-engineered lines commanding 40-60 percent premiums over Chinese standardized units while bundling performance-based maintenance agreements that shift technical risk to OEM networks.
Pricing Analysis
Equipment vendors now unbundle service contracts from capital sales as scrap yard operators prioritize uptime guarantees over ownership. Three-tier pricing stratifies across premium wet systems with integrated water treatment, standard dry mechanical configurations, and entry-level hammer mill pre-reduction units. Cost compression in the commodity dry tier intensifies as Chinese fabricators compete on provincial urban mining tenders. European certified recyclers under EU WEEE Directive financing show least price sensitivity, while Southeast Asian mid-tier scrap processors exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany's Baden-Württemberg machinery corridor and China's Yangtze River Delta industrial clusters anchor spare parts logistics for premium and commodity tiers respectively. Component sourcing draws from Italian cutting mill specialists, German high-voltage transformer suppliers, and Chinese steel fabrication hubs. Single-source vulnerability concentrates in electrostatic separation stage electronics subject to REACH and MEE compliance verification. Distribution runs through manufacturer-direct channels for large-scale installations and regional machinery distributors for standardized units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service bundling and electrostatic retrofit kits, as MEE emissions enforcement and REACH plasticizer restrictions force processor upgrades regardless of new equipment cycles.
For Market Incumbents: Anchor defensive positioning through backward integration into electrostatic component supply and certified technician training programs. German engineering houses should expand regional service partnerships in Vietnam's Red River Delta to counter Chinese cost competition. Capacity addition in wet granulation systems serving automotive wiring harness recovery protects against modular dry system commoditization.
For New Entrants and Emerging Players: Enter via modular equipment architecture targeting Southeast Asian mid-tier scrap processors facing MEE-aligned effluent rule tightening. Vietnam and Indonesia present the most penetrable geographies where incumbent service networks remain underdeveloped. A leasing-plus-maintenance go-to-market angle reduces capital barrier-to-entry for price-sensitive operators.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier European specialists lack Chinese cost competitiveness and electrostatic service capability. Long-term viability favors vendors with captive technician training pipelines and smelter certification relationships. Acquisition target archetypes include regional service-heavy distributors with spare parts logistics density. The signal to watch is copper scrap import quota volatility triggering distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrostatic Retrofit Program | MEE emissions enforcement in China eliminates thermal separation alternatives, accelerating retrofit demand. |
| Modular Equipment Architecture | WEIMA's scalable configurations let Southeast Asian operators expand throughput without full line replacement. |
| Regional Service Network Expansion | Chinese vendors establishing Vietnam-based logistics capture mid-tier scrap processor procurement. |
| Technician Certification Pipeline | Electrostatic system operation requires specialized training that outpaces vocational program output. |
| Smelter Co-location Partnership | Yangtze River Delta industrial symbiosis clusters enable just-in-time metal delivery with reduced logistics overhead. |
Study Parameters
Multiple input streams — equipment procurement databases, regulatory filing repositories, and smelter acceptance protocol documentation — were reconciled against primary interviews with granulator OEM technical directors, certified recycler operations managers, and copper smelter procurement leads. Secondary validation drew from MEE emissions enforcement records, EU WEEE Directive implementation reports, REACH restriction updates, and customs trade data on copper scrap flows. Bottom-up unit economics from recycling facility deployments and top-down market sizing from equipment vendor shipment aggregates underwent cross-triangulation.
Data-stream reconciliation across the projection horizon applied segmentation modeling by product type (dry, wet, hammer mill, shredder), technology tier (mechanical, electrostatic, magnetic, thermal), end-user category (recycling facilities, industrial manufacturers, waste management companies, scrap processors), and capacity scale (large, custom-built, medium, small). CAGRs were derived from installed base replacement cycles and greenfield deployment trajectories. Industry-specific forecast inputs included copper scrap import quota volatility patterns and MEE enforcement intensity indices.
The model holds under sustained regulatory enforcement of mechanical separation mandates; deviation in copper price collapse or smelter certification timeline extensions would shift equipment payback assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Camera Tripods Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Machine Tool Cooling System Market