
 Global Abrasive Waterjet Cutting Machine Market | 2026-2036
Global Abrasive Waterjet Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Abrasive Waterjet Cutting Machine Market Analysis
High-pressure precision-tier specifications above 90,000 psi is reorganizing competitive dynamics across the Global Abrasive Waterjet Cutting Machine Market. Flow International Corporation leverages proprietary intensifier pump technology to dominate ultra-high-pressure system supply. OMAX Corporation anchors its position through linear drive precision tables optimized for tight-tolerance aerospace work. KMT Waterjet Systems differentiates via global service density and aftermarket consumables control.
An abrasive waterjet cutting machine accelerates a pressurized water stream mixed with garnet abrasive through a sapphire or diamond orifice to cut metals, composites, stone, and glass without heat-affected zones, typically operating at pressures between 40,000 and 90,000 psi with kerf widths under 1 mm for precision fabrication. 3D robotic waterjet configurations lead capital expenditure growth as multi-axis cutting heads penetrate aerospace turbine component and automotive composite trimming applications where five-axis motion eliminates secondary machining steps. Abrasive waterjet technology commands the largest installed base among technology categories, though hybrid waterjet systems integrating plasma or laser assist show the fastest specification upgrade rate in heavy metal fabrication shops seeking throughput gains on thick plate.
EPA effluent guidelines restrict spent abrasive disposal from waterjet operations in the United States, while CE marking under the EU Machinery Directive mandates interlocked guarding and emergency stop protocols on systems sold in Europe. Japan's METI industrial efficiency standards incentivize closed-loop water recycling and abrasive recovery systems that reduce operating cost profiles. Stakeholders must monitor evolving ISO 12100 machinery safety harmonization and regional carbon border adjustments that could reshape total cost of ownership calculations for imported cutting systems.
Market Dynamics
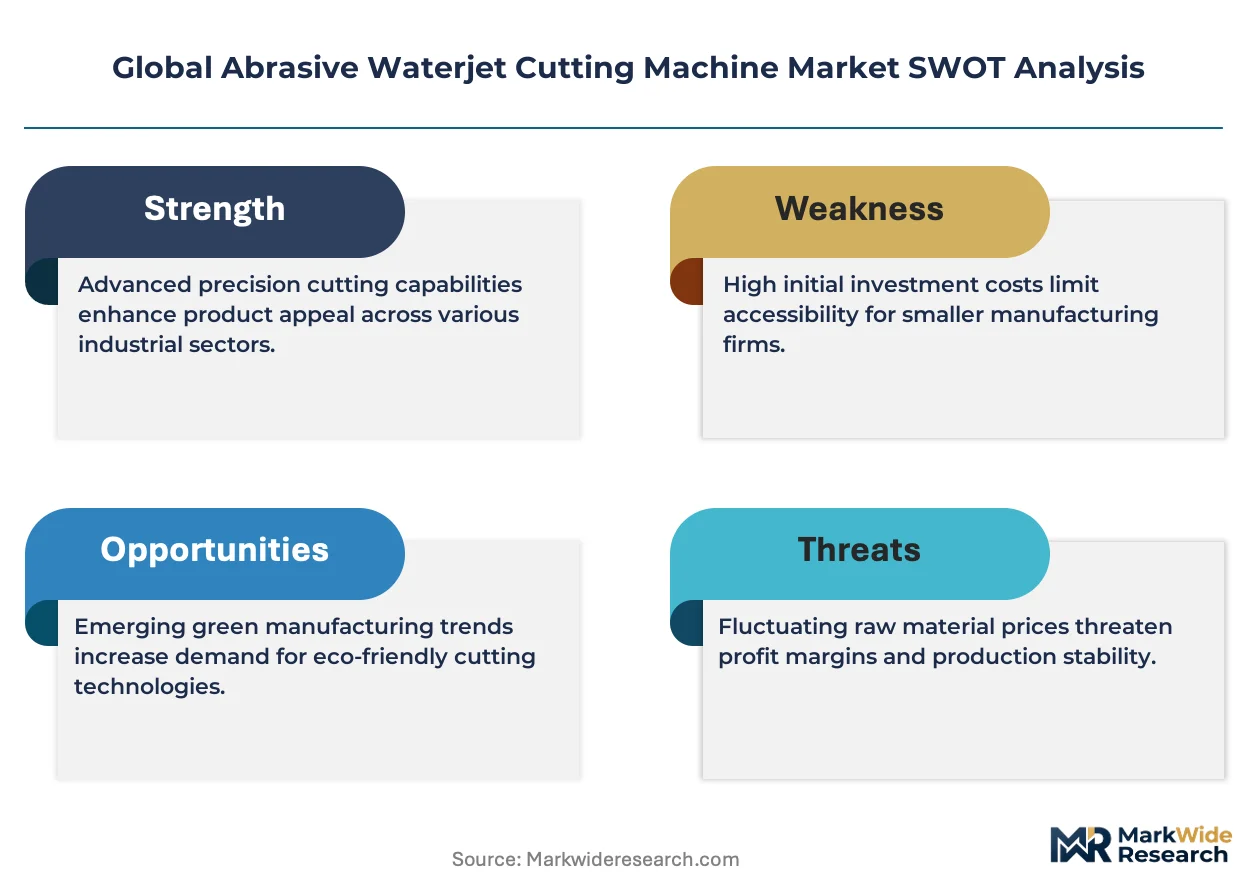
Ultra-high-pressure intensifier pump technology above 90,000 psi is compressing machining tolerances across aerospace and automotive fabrication, forcing OEMs to retool legacy mechanical cutting infrastructure or cede precision-tier contracts to equipped competitors.
Growth Catalysts
- Titanium aerospace component demand:German and Japanese turbine manufacturers specify abrasive waterjet for heat-sensitive superalloy machining, eliminating thermal distortion risks inherent in plasma cutting.
- EPA effluent guideline enforcement:Spent garnet disposal restrictions in the United States accelerate closed-loop abrasive recycling system upgrades, extending machine utilization rates.
- Five-axis robotic integration:Multi-axis cutting heads eliminate secondary trimming operations in automotive composite manufacturing, reducing part-to-part cycle times.
Market Restraints
- Pump seal and orifice consumable costs:Sapphire and diamond orifice replacement cycles impose recurring operating expenditure burdens on job shop operators.
- High-pressure intensifier supply concentration:Proprietary pump technology remains concentrated among a narrow supplier base, limiting buyer negotiation leverage.
- Plasma-laser hybrid substitution:Thick steel plate fabricators increasingly specify plasma assist for carbon steel above 50 mm, constraining pure waterjet penetration.
Strategic Opportunities
- India precision metalworking corridor:Automotive component clusters in Pune and Chennai remain underpenetrated by 3D robotic waterjet systems, presenting first-mover equipment placement potential.
- EU Machinery Directive CE marking:Interlocked guarding mandates create aftermarket retrofit demand for safety system integration across installed European machine bases.
- Waterjet-additive hybrid workflows:Near-net-shape additive manufacturing followed by waterjet finishing is displacing conventional subtractive machining in medical implant production.
Industry Challenges
- Multi-axis programming competency gaps:Five-axis toolpath generation requires CAM expertise scarce in traditional waterjet operator labor pools.
- CE certification timeline compression:Machinery Directive conformity assessment delays product launch schedules for OEMs targeting European aerospace Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Abrasive Waterjet Cutting Machine Market |
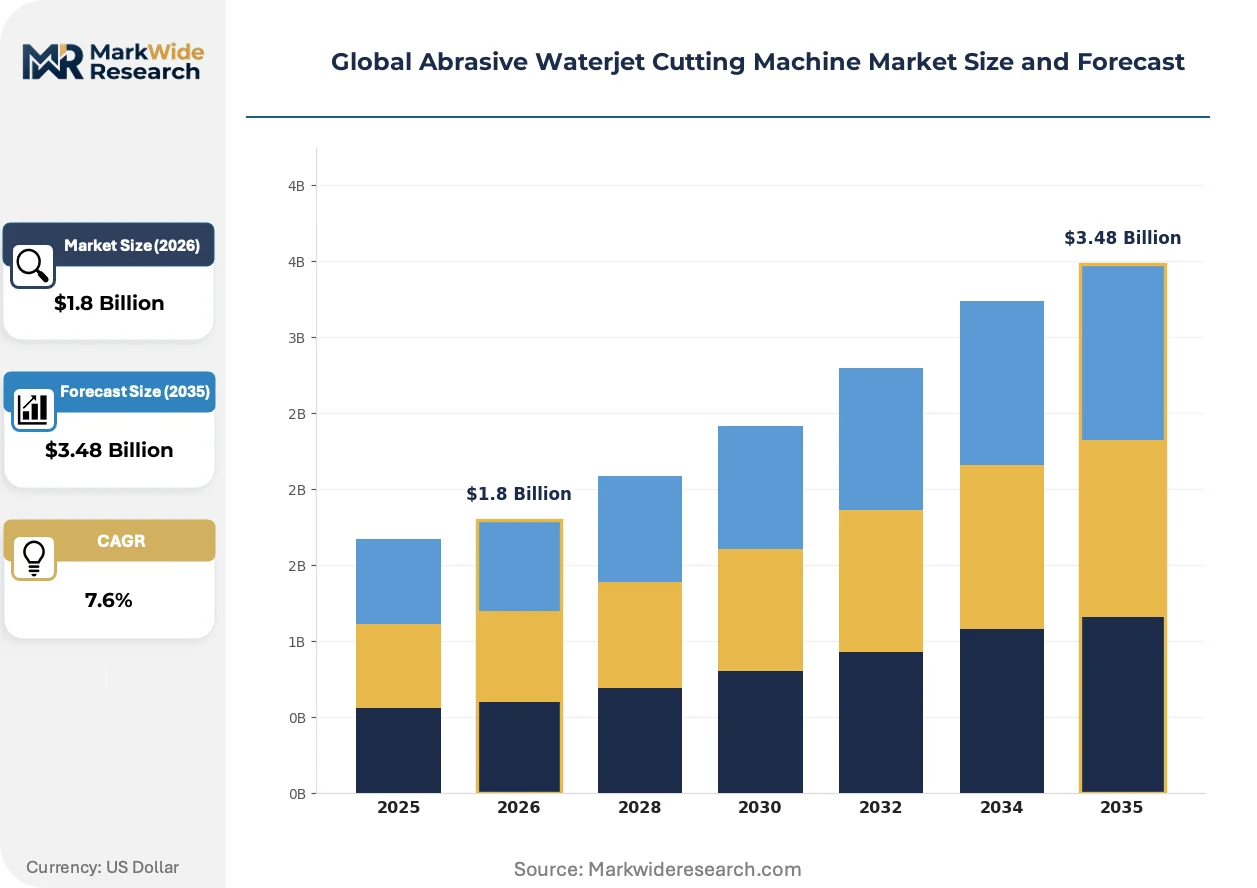
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Waterjet, 3D Waterjet, Portable Waterjet, Robotic Waterjet End User: Aerospace, Automotive, Metal Fabrication, Stone Cutting Technology: Pure Waterjet, Abrasive Waterjet, Hybrid Waterjet, CNC Waterjet Size: Small, Medium, Large, Custom |
| Companies Covered | Flow International Corporation, OMAX Corporation, KMT Waterjet Systems, WARDJet, Dardi International Corporation, Jet Edge, Inc., Koike Aronson, Inc., Colfax Corporation, Techni Waterjet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Abrasive Waterjet Cutting Machine Market Emerging Trajectories
Precision fabrication requirements across aerospace turbine and automotive composite segments are accelerating specification upgrades in cutting system architectures, with pressure thresholds and motion control sophistication becoming primary competitive differentiators.
Closed-loop abrasive recovery systems are displacing open-loop disposal configurations in high-volume production environments. Automotive stamping plants in Germany and the United States specify these systems to eliminate spent garnet hauling costs. The technology is displacing conventional waste management service contracts while reducing raw abrasive procurement volumes by half.
Japan's METI industrial efficiency standards now mandate water recycling ratios above 85 percent for new cutting equipment installations. This regulatory pressure forces OEMs to integrate filtration and reclamation modules as standard rather than optional configurations. Precision metalworking shops in Nagoya and Osaka corridors are retrofitting legacy systems to maintain operational permits.
After-sales service unbundling is fragmenting traditional OEM revenue models. Aerospace maintenance contractors in the U.S. Gulf Coast now procure spare orifices and high-pressure seals through independent distributors rather than captive supply agreements. This channel shift compresses margin capture for equipment manufacturers while expanding price transparency for end-users.
Global Abrasive Waterjet Cutting Machine Market Segmentation
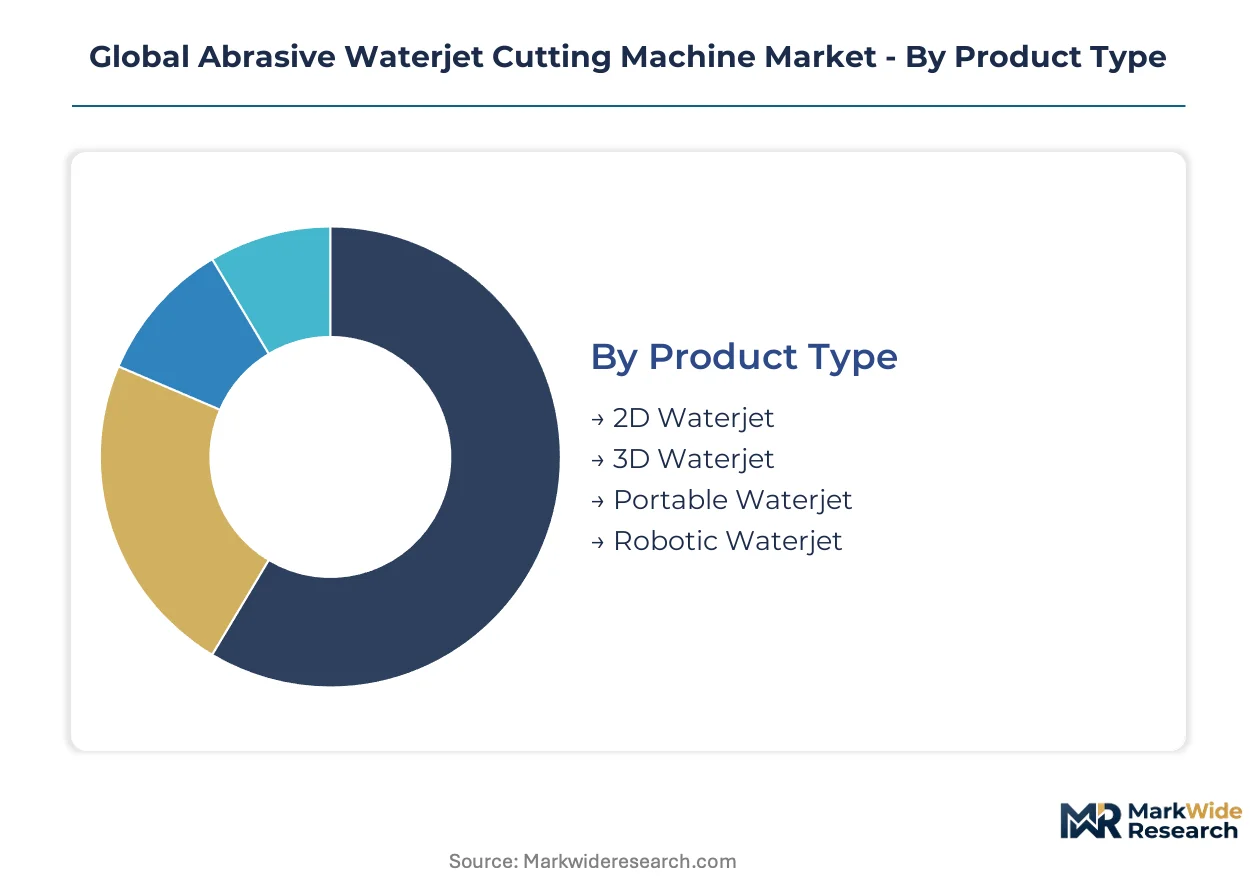
Segmentation in the abrasive waterjet market reveals distinct procurement patterns across equipment configurations, end-use verticals, and control architectures. Channel preferences vary sharply between job shops seeking portable flexibility and aerospace integrators demanding precision-tier robotic systems.
Product Type:
Distributor and direct sales channels bifurcate sharply across product configurations, with capital-intensive robotic systems flowing through manufacturer-direct relationships while portable units move through industrial equipment dealers.
- 2D Waterjet:Flat-bed cutting tables with X-Y gantry motion dominate entry-level metal fabrication and stone processing installations. German automotive stamping plants and U.S. Gulf Coast energy fabricators concentrate demand here for high-volume sheet and plate work where three-dimensional contouring is unnecessary.
- 3D Waterjet:Five-axis cutting heads enable bevel and contour machining in aerospace turbine component production. Japanese precision metalworking corridors and German aerospace clusters drive specification upgrades as multi-axis capability eliminates secondary trimming operations on titanium and composite aerostructures.
- Portable Waterjet:Compact, field-deployable units serve on-site maintenance and repair applications in shipbuilding and infrastructure sectors.
- Robotic Waterjet:Articulated arm configurations integrate with production lines for complex geometry processing in automotive composite trimming.
2D Waterjet dominates installed base. Robotic Waterjet is where expansion concentrates.
End User:
Margin profiles diverge dramatically across vertical applications, with aerospace and automotive commanding premium pricing for precision-tier specifications while metal fabrication operates on volume-driven equipment economics.
- Aerospace:Heat-sensitive superalloy and composite machining requirements mandate abrasive waterjet for turbine discs, fan blades, and airframe components. Japanese and German Tier-1 suppliers specify ultra-high-pressure systems above 90,000 psi to eliminate thermal distortion risks inherent in conventional machining.
- Automotive:Carbon fiber reinforced polymer trimming and prototype metal forming drive adoption in Germany's component manufacturing belt and U.S. electric vehicle production corridors.
- Metal Fabrication:General job shops process mixed material streams including aluminum, stainless steel, and exotic alloys for industrial equipment and architectural applications.
- Stone Cutting:Granite and marble processors in Italy and India utilize waterjet for intricate inlay work and large-format slab cutting where diamond blade alternatives generate excessive dust and chipping.
Aerospace commands premium pricing tiers. Automotive represents the steepest expansion trajectory for 3D robotic configurations.
Technology:
Specification complexity determines aftermarket revenue potential, with abrasive and hybrid systems generating recurring consumable streams that pure waterjet configurations cannot match.
- Pure Waterjet:Pressurized water without abrasive addition cuts soft materials including rubber, foam, and food products. Applications concentrate in gasket manufacturing and industrial insulation processing where material purity requirements prohibit garnet contamination.
- Abrasive Waterjet:Garnet-entrained streams cut hardened metals, ceramics, and composites without heat-affected zones. This technology commands the largest installed base among all categories, with closed-loop abrasive recovery systems now standard in high-volume German and U.S. automotive plants.
- Hybrid Waterjet:Plasma or laser assist modules accelerate thick plate cutting above 50 mm in carbon steel fabrication.
- CNC Waterjet:Computer numerical control integration enables automated nesting and path optimization across all pressure tiers.
Abrasive Waterjet anchors revenue scale. Hybrid Waterjet is gaining share fastest in heavy fabrication shops seeking throughput gains.
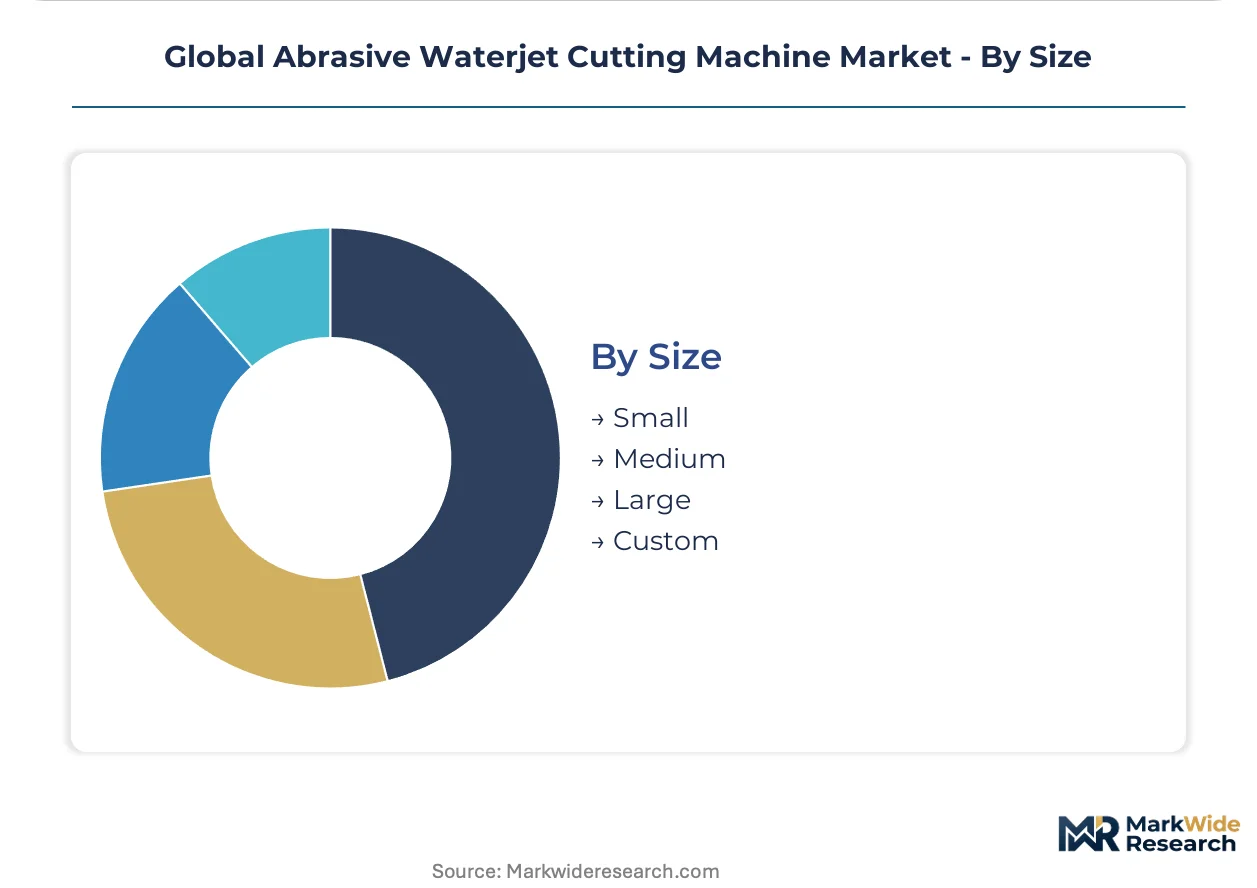
Size:
Footprint and power requirements shape regional manufacturing feasibility, with compact systems penetrating dense industrial corridors and custom configurations serving specialized aerospace and energy applications.
- Small:Benchtop and compact floor-standing units serve prototyping laboratories, educational institutions, and specialty jewelry manufacturing.
- Medium:Mid-scale tables dominate independent job shops in India's Pune and Chennai automotive clusters where space constraints and capital budgets limit large-format acquisition.
- Large:Extended bed configurations process full-sheet materials in high-volume stone cutting and shipbuilding applications.
- Custom:Bespoke machine architectures accommodate oversized aerospace wing sections and pressure vessel components exceeding standard dimensional limits.
Medium size configurations dominate unit volume. Custom size systems concentrate margin capture in aerospace and energy fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing bases with deep aerospace and automotive supply chains. Germany and Japan maintain consistent equipment surpluses through precision-tier system exports. India's precision metalworking corridor attracts capital placement as domestic automotive production scales.
United States
Gulf Coast energy fabricators and aerospace maintenance contractors drive demand for 3D robotic configurations. EPA effluent guidelines restrict spent garnet disposal, accelerating closed-loop abrasive recycling retrofits. Houston and New Orleans industrial clusters concentrate heavy fabrication capacity where ultra-high-pressure systems process pressure vessel components.
Germany
Automotive stamping plants and turbine manufacturers specify precision-tier waterjet systems for titanium and composite machining. CE marking under the EU Machinery Directive mandates interlocked guarding and emergency stop protocols on new installations. Bavaria's aerospace component cluster and Stuttgart's automotive belt lead capital expenditure on five-axis robotic integration.
Japan
Precision metalworking shops in turbine disc and fan blade production favor abrasive waterjet for heat-sensitive superalloys. METI industrial efficiency standards mandate water recycling ratios above 85 percent for new equipment installations. Nagoya and Osaka corridors retrofit legacy systems to maintain operational permits under tightening environmental compliance.
India
Automotive component clusters in Pune and Chennai remain underpenetrated by 3D robotic waterjet systems despite expanding production capacity. BIS certification requirements and state-level industrial efficiency incentives shape procurement specifications. Domestic metal fabrication job shops increasingly specify medium-size CNC tables for mixed-material processing.
China
Heavy fabrication shops in Yangtze River Delta and Pearl River Delta regions adopt hybrid waterjet-plasma systems for thick carbon steel plate. GB standards and MIIT industrial upgrading programs influence equipment specification requirements. Shipbuilding clusters in Dalian and Shanghai drive demand for large-format cutting tables.
Global Abrasive Waterjet Cutting Machine Market Vendor Landscape
Listed leaders compete with private specialists across technology tiers and geographic reach. The vendor base organizes around three structural positions: intensifier pump technology proprietors, precision motion control specialists, and integrated robotic system providers. Strategic moves concentrate on aftermarket consumables control and regional service density expansion.
Within the premium technology tier, Flow International Corporation exemplifies proprietary intensifier pump positioning. OMAX Corporation and KMT Waterjet Systems occupy complementary positions in precision motion and global service infrastructure. These three anchors represent distinct competitive archetypes rather than overlapping capability sets.
| Leading Market Players |
|---|
| Flow International Corporation |
| OMAX Corporation |
| KMT Waterjet Systems |
| WARDJet |
| Dardi International Corporation |
| Jet Edge, Inc. |
| Koike Aronson, Inc. |
| Colfax Corporation |
| Techni Waterjet |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for high-pressure intensifier pump assemblies concentrate supply leverage among German and U.S. component specialists, compressing margin capture for downstream OEMs while amplifying pricing power at the technology origin. This inventory constraint feeds directly into tiered equipment quotations where abrasive recycling bundling and regional service density separate premium robotic configurations from standard gantry tables.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. CE marking certification and METI efficiency compliance separate premium robotic systems from uncertified portable units. Pricing pressure stems from independent aftermarket distributors undermining captive consumables revenue. Job shop operators exhibit highest price sensitivity, while aerospace Tier-1 suppliers prioritize specification adherence over unit cost.
Supply Chain Analysis
Germany and the United States anchor intensifier pump manufacturing and precision motion control production. Sapphire and diamond orifice sourcing draws from synthetic crystal growers in Japan and specialized ceramics producers in the United States. Single-source vulnerability concentrates in ultra-high-pressure seal compounds. Distribution runs through manufacturer-direct channels for capital-intensive robotic systems and industrial equipment dealers for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fabrication demand fragmentation across aerospace turbine and automotive composite segments creates viable entry niches for specialists targeting underpenetrated technology tiers and geographic corridors.
For Market Incumbents: Shield aftermarket revenue streams by tightening captive supply agreements for sapphire orifices and high-pressure seals against independent distributor encroachment. Deepen backward integration into garnet abrasive recovery systems to offset margin compression from unbundled service contracts. Prioritize CE marking pre-certification investments to compress European launch timelines for aerospace Tier-1 supplier qualification. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission enables European aerospace corridor penetration before legacy OEMs retrofit installed bases. Target India's Pune and Chennai automotive clusters where 3D robotic waterjet penetration remains below German and Japanese benchmarks. Lead with waterjet-additive hybrid workflow demonstrations for medical implant finish-machining applications. For Investors and Strategic Acquirers: Long-term, this sits as a precision automation play because closed-loop abrasive recycling and five-axis robotic integration are displacing conventional subtractive machining in heat-sensitive superalloy applications. Target mid-scale OEMs with intensifier pump technology licenses but underdeveloped global service infrastructure. Monitor EPA effluent guideline enforcement intensity as inflection signal for aftermarket retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intensifier Pump Technology | Proprietary pump control secures margin capture in ultra-high-pressure tier specifications above 90,000 psi. |
| CE Marking Pre-Certification Investment | Machinery Directive conformity compresses product launch schedules for European aerospace Tier-1 supplier targeting. |
| Closed-Loop Abrasive Recovery System Bundling | German automotive stamping plants specify integrated recycling to eliminate spent garnet hauling cost exposure. |
| Five-Axis Robotic Integration Partnership | Multi-axis cutting head capability eliminates secondary trimming operations in Japanese turbine disc production. |
| Regional Service Density Expansion | After-sales unbundling by Gulf Coast maintenance contractors demands localized spare orifice inventory positioning. |
Methodological Framework
Cross-validation between OEM procurement director interviews and customs trade data anchors the qualitative findings on distributor-direct channel bifurcation. Primary fieldwork engaged maintenance directors at Gulf Coast energy fabricators, plant engineers in Germany's automotive stamping belt, and aftermarket service heads at Japanese precision metalworking corridors. Secondary sources included EPA effluent guideline filings, METI industrial efficiency standard updates, CE marking conformity assessment databases, and equipment registration records from aerospace Tier-1 supplier qualification programs. Bottom-up unit shipment estimates triangulate against top-down capital expenditure tracking across named regional clusters.
Sensitivity analysis across pressure tier adoption curves and abrasive recycling penetration rates tests forecast robustness over the projection horizon. Segmentation dimensions span product configuration, end-use vertical, control architecture, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and greenfield capacity addition tracking. Industry-specific inputs include METI water recycling ratio mandates and EPA enforcement intensity indices for spent garnet disposal restrictions.
Underlying assumptions cover stable intensifier pump technology concentration and sustained EPA effluent guideline enforcement, with deviation risk concentrated in plasma-laser hybrid substitution acceleration and carbon border adjustment implementation timing. Recalibration cycles align with material shifts in aerospace composite specification upgrades and regional environmental compliance tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Industrial Magnetrons Market