
 Air Bearings Market | 2026-2036
Air Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Air Bearings Market Analysis
Semiconductor equipment buyers are rotating capital toward air bearing solutions that deliver sub-nanometer positioning stability for extreme ultraviolet lithography systems. New Way Air Bearings dominates the North American installed base for wafer stage applications, while SKF Group leverages its cross-continental manufacturing footprint to serve European precision machinery builders. Physik Instrumente (PI) SE & Co. KG specializes in nanopositioning stages that integrate custom air bearing spindles for research instrumentation.
Air bearings are non-contact support devices that suspend a load on a thin film of pressurized gas, typically achieving motion accuracies below 100 nanometers and friction coefficients near zero, primarily serving applications where mechanical contact would introduce contamination, wear, or thermal distortion. Journal bearings and thrust bearings together occupy the core product architecture, with journal configurations leading in rotating machinery while thrust variants capture the fastest growth in axial-load semiconductor stages. Hydrostatic technology anchors current revenue volumes due to its maturity in machine tool spindles, whereas magnetic levitation systems are displacing conventional options in the most demanding metrology and aerospace test rig applications.
FDA device quality system regulations in the United States and EU MDR conformity requirements in Europe both impose traceable motion accuracy validation on medical device manufacturing equipment, directly shaping air bearing specification thresholds for implantable device production lines. EPA and REACH frameworks further restrict perfluorinated lubricant chemistries, pushing OEMs toward gas-lubricated alternatives. Stakeholders must monitor how NMPA alignment with international metrology standards in China reshapes supplier qualification criteria for precision bearing imports.
Market Dynamics
Semiconductor lithography equipment manufacturers are consolidating procurement around sub-nanometer positioning systems, compressing supplier qualification timelines and elevating air bearing specifications as the binding constraint on wafer stage performance.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon lubricants is mandating gas-lubricated bearing architectures in precision machinery across German and French manufacturing clusters.
- Extreme ultraviolet lithography:EUV scanner OEMs are specifying air bearing stages to eliminate vibration-induced pattern distortion at 3-nanometer process nodes.
- Medical device traceability:FDA quality system regulations and EU MDR conformity requirements are validating motion accuracy claims for implantable device production equipment.
Market Restraints
- Pneumatic infrastructure dependency:Clean dry air generation systems add facility-level capital burdens that exclude smaller machine shops from air bearing adoption.
- Specialized manufacturing concentration:Precision grinding and lapping capabilities for ceramic bearing surfaces cluster in southern Germany and parts of Japan, creating single-source vulnerability.
- Active magnetic bearing substitution:Maglev systems are capturing axial-load applications above 50 kilonewtons in aerospace test rigs where zero friction is mandatory.
Strategic Opportunities
- Indian precision manufacturing:PLI scheme incentives for semiconductor packaging equipment are creating first-mover openings for air bearing spindle suppliers in Gujarat and Karnataka.
- Quantum research instrumentation:Cryogenic nanopositioning stages for dilution refrigerators are integrating specialized air bearings that operate at millikelvin temperatures.
- Cell therapy manufacturing:ISO 14644-1 cleanroom requirements for regenerative medicine production are specifying non-contact bearings to eliminate particulate contamination from mechanical wear.
Industry Challenges
- Aerostatic groove design expertise:Computational fluid dynamics modeling for custom bearing geometries requires scarce tribology specialists with gas film dynamics training.
- Legacy controller integration:Retrofitting air bearing stages onto existing CNC machine tools demands proprietary servo loop tuning that OEMs protect as intellectual property.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Bearings Market |
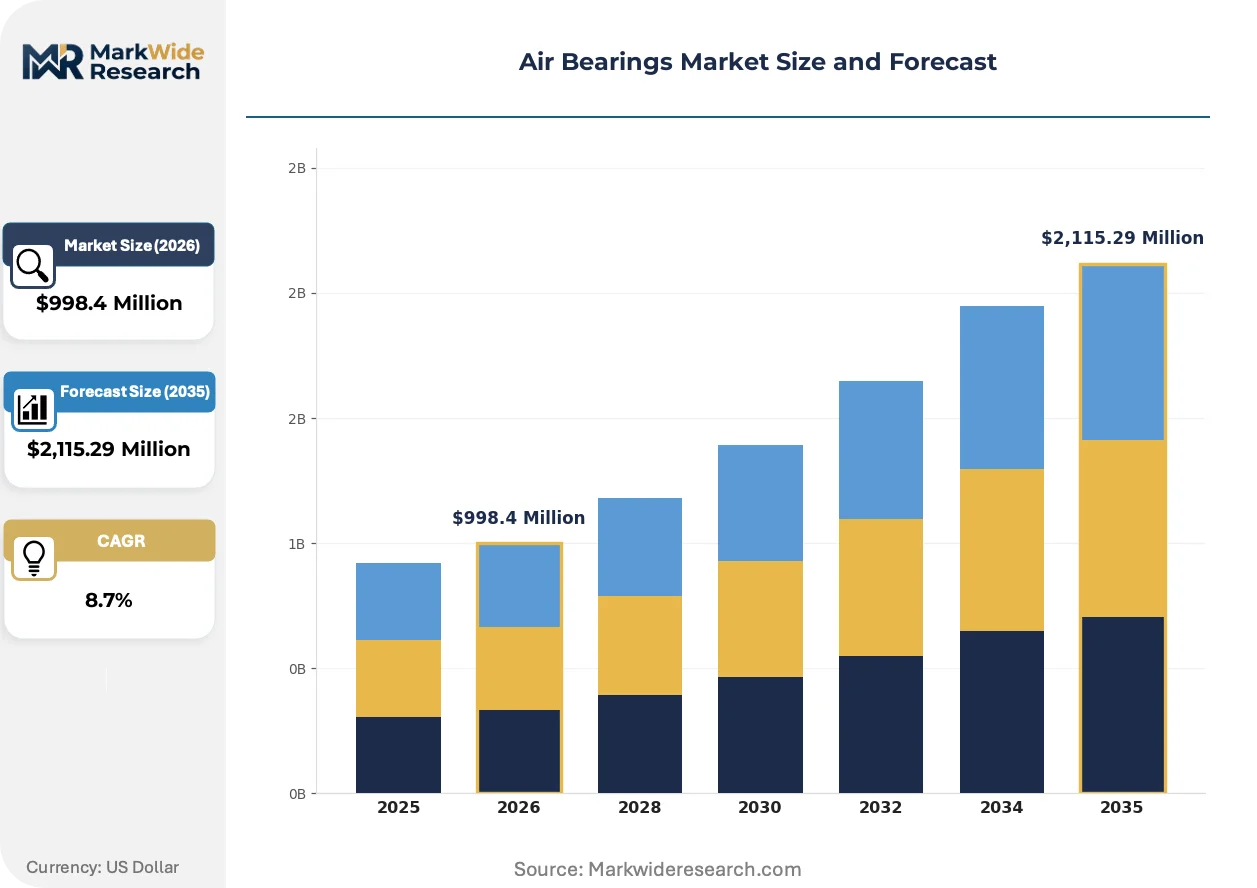
| Market Size in 2026 | $998.4 Million |
| Market Size in 2035 | $2,115.29 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Plain Bearings, Thrust Bearings, Journal Bearings, Radial Bearings Application: Semiconductor Manufacturing, Aerospace Systems, Precision Machinery, Medical Devices End User: Automotive OEMs, Research Institutions, Electronics Manufacturers, Manufacturing Equipment Providers Technology: Magnetic Levitation, Nanotechnology, Hydrostatic, Hydrodynamic |
| Companies Covered | The Timken Company, New Way Air Bearings, SKF Group, Oiles Corporation, Physik Instrumente (PI) SE & Co. KG, JTEKT Corporation, RBC Bearings Inc., Leuven Air Bearings NV, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Bearings Market Emerging Trajectories
Gas-bearing architectures are diverging along two paths: hydrostatic systems optimized for load capacity in machine tool spindles, and aerodynamic self-acting designs gaining traction in high-speed turbomachinery where external air supply is impractical.
Orifice-compensated air bearings with micro-machined inlet restrictors are supplanting porous graphite inserts in semiconductor wafer inspection stages. ASML and Nikon Precision Equipment are qualifying these architectures for next-generation overlay metrology systems. The shift is compressing acceptable pore size tolerances from ten micrometers to sub-micrometer specifications, filtering traditional sintered material suppliers from the supply base.
REACH restrictions on perfluoropolyether lubricants are forcing bearing manufacturers to validate alternative gas chemistries for high-temperature vacuum applications. The European Chemicals Agency's 2023 substance evaluation roadmap has accelerated R&D spending on nitrogen and helium-based lubrication schemes. Medical device OEMs in Ireland and Switzerland are now requiring gas-lubrication certificates as standard procurement documentation.
Buying committees at major semiconductor capital equipment firms are unbundling air bearing spindles from integrated stage assemblies, creating direct procurement relationships with specialized bearing houses. This disintermediation is displacing the historical captive supply model where stage integrators specified proprietary bearing designs. The pattern is most pronounced in South Korea, where Samsung and SK Hynix equipment engineering teams are publishing open specifications for air bearing performance envelopes.
Air Bearings Market Segmentation
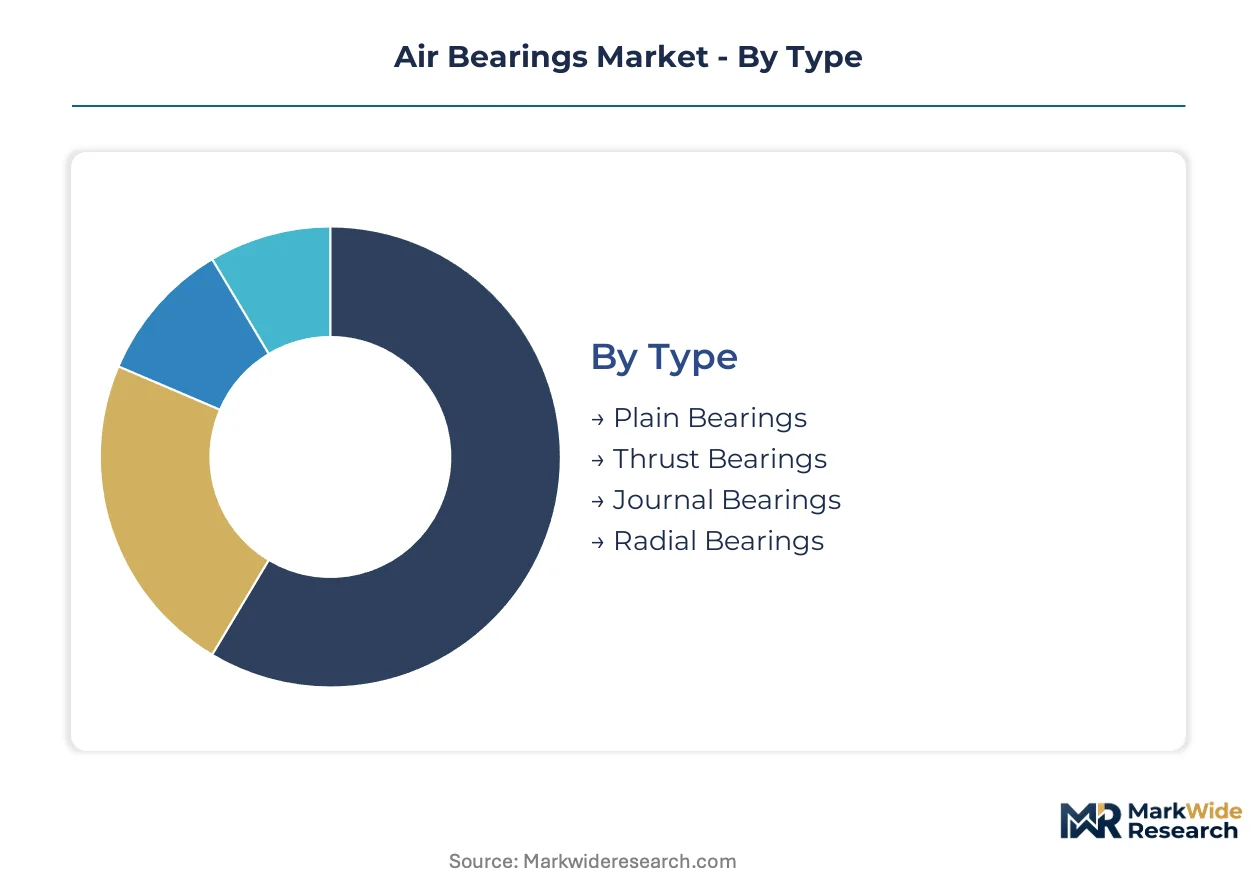
Air bearing procurement channels diverge sharply by technical complexity and end-use criticality. Semiconductor equipment buyers route high-precision stages through specialized motion control distributors, while machine tool OEMs source hydrostatic spindles via direct manufacturer relationships.
Type:
Journal bearings flow predominantly through machine tool OEM direct channels, whereas thrust variants reach semiconductor stage integrators via precision motion specialists.
- Journal Bearings:These rotating-shaft configurations suspend cylindrical loads on circumferential gas films, achieving runout below 50 nanometers in grinding spindle applications. German machine tool builders in Stuttgart and Dresden specify journal architectures for ceramic bearing surfaces in high-speed milling centers. EU F-Gas Regulation compliance is accelerating substitution of oil-lubricated alternatives in these precision metalcutting platforms.
- Thrust Bearings:Axial-load designs employ opposed pad arrays to constrain linear motion stages against vertical deflection. Semiconductor lithography OEMs in the Netherlands and Japan specify thrust configurations for EUV wafer positioning systems where sub-nanometer stability is mandatory. Clean dry air infrastructure requirements limit adoption to fabs with centralized compressed gas distribution.
- Plain Bearings:Simple orifice-compensated flat pads serve metrology and inspection equipment where load capacity exceeds precision requirements.
- Radial Bearings:Combined journal-thrust hybrids capture turbomachinery applications in aerospace test rigs requiring multi-axis constraint.
Journal bearings dominate installed base. Thrust bearings are where expansion concentrates.
Application:
Cost tier stratification separates million-dollar lithography stages from sub-hundred-thousand-dollar precision machinery retrofits.
- Semiconductor Manufacturing:EUV scanner wafer stages and overlay metrology systems demand the highest specification tier. ASML's procurement of orifice-compensated bearings with sub-micrometer restrictor tolerances is compressing supplier qualification to three specialized houses. FDA device quality system regulations indirectly shape these specifications through traceability requirements for medical chip production.
- Precision Machinery:Coordinate measuring machines and optical profilers occupy the mid-tier, where hydrostatic spindles balance accuracy against pneumatic infrastructure costs. Japanese CMM builders in Tokyo and Yokohama specify porous graphite inserts for their established supply base.
- Aerospace Systems:Cryogenic turbopump test rigs and satellite momentum wheel bearings require specialized helium or nitrogen chemistries.
- Medical Devices:Implantable device production lines specify ISO 14644-1 compliant non-contact bearings to eliminate particulate contamination from mechanical wear.
Semiconductor manufacturing commands premium pricing. Precision machinery is climbing the fastest.
End User:
Customer type determines specification authority and procurement cycle length.
- Electronics Manufacturers:Samsung and SK Hynix equipment engineering teams in South Korea publish open performance specifications, disintermediating traditional stage integrators. Direct bearing procurement relationships are compressing supplier margins while accelerating qualification timelines for orifice-compensated architectures.
- Research Institutions:National laboratories and university physics departments specify custom geometries for cryogenic nanopositioning in dilution refrigerators. Physik Instrumente supplies integrated air bearing stages for quantum computing research at millikelvin temperatures.
- Automotive OEMs:Electric motor test rigs and metrology stations for powertrain components specify hydrostatic spindles.
- Manufacturing Equipment Providers:Machine tool OEMs in southern Germany maintain captive air bearing production for proprietary spindle integration.
Electronics manufacturers drive specification evolution. Research institutions are where technology validation occurs.
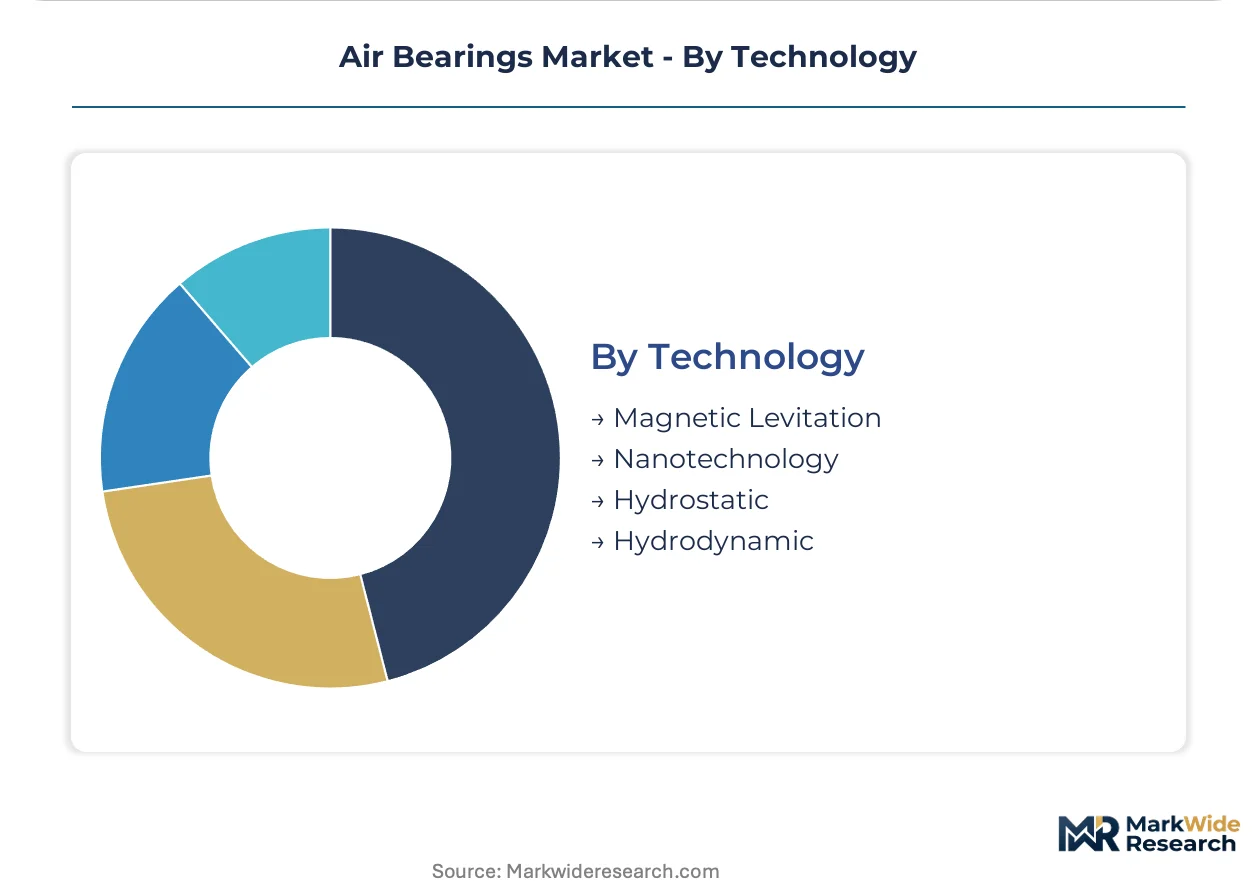
Technology:
Maturity curves separate proven hydrostatic architectures from emerging magnetic levitation displacement.
- Hydrostatic:Externally pressurized gas films anchor current revenue volumes through proven reliability in machine tool spindles. German and Japanese OEMs specify hydrostatic journal bearings for ceramic grinding applications where load capacity and thermal stability outweigh infrastructure costs.
- Magnetic Levitation:Active maglev systems displace air bearings in aerospace test rigs above 50 kilonewtons axial load. European Space Agency vibration isolation platforms and turbine blade spin pits specify zero-friction magnetic suspension where pneumatic supply is impractical.
- Hydrodynamic:Self-acting aerodynamic designs gain traction in high-speed turbomachinery without external compressed air.
- Nanotechnology:Surface texture engineering and micro-machined restrictor fabrication enable sub-micrometer pore tolerances.
Hydrostatic technology anchors installed base. Magnetic levitation is where displacement is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's integrated compressed gas distribution network underwrites Dutch leadership in precision machinery component logistics, while Germany's Rhine-Main corridor anchors continental supply chains for ceramic bearing surface fabrication.
Germany
Machine tool OEMs in Stuttgart and Dresden drive procurement of hydrostatic journal bearings for ceramic grinding spindles. The EU F-Gas Regulation mandates gas-lubricated architectures in precision manufacturing clusters across Baden-Württemberg. Research institutes in Aachen and Munich anchor advanced metrology development for sub-nanometer positioning systems.
United States
Semiconductor capital equipment firms in California and Arizona specify orifice-compensated bearings for EUV lithography stages. EPA phase-down rules on perfluorinated lubricants accelerate shifts toward non-contact bearing technologies. Boston-area quantum computing labs integrate cryogenic air bearings into dilution refrigerator systems.
Japan
Coordinate measuring machine builders in Tokyo and Yokohama specify porous graphite inserts for established precision machinery supply chains. METI industrial standards validate motion accuracy claims for medical device production equipment. Nagoya-area automotive test rig manufacturers specify hydrostatic spindles for electric motor validation.
South Korea
Samsung and SK Hynix equipment engineering teams publish open performance specifications for air bearing stages. The country's national semiconductor regulator aligns procurement standards with international metrology frameworks. Gyeonggi Province fabrication facilities centralize clean dry air infrastructure for lithography equipment.
Netherlands
ASML's procurement of sub-micrometer restrictor tolerances compresses supplier qualification timelines for wafer stage bearings. ECHA substance evaluation roadmaps accelerate R&D on nitrogen-based lubrication chemistries. Eindhoven's high-tech campus concentrates precision motion control engineering talent.
Air Bearings Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and geographic coverage dimensions. The vendor base separates into three tiers: multinational bearing conglomerates with cross-continental manufacturing footprints, regional precision motion specialists with captive air bearing production, and niche nanopositioning houses serving research instrumentation. Strategic moves concentrate on backward integration into ceramic surface grinding capabilities and direct procurement relationships with semiconductor equipment buyers.
Within the precision motion specialist tier, New Way Air Bearings and Physik Instrumente (PI) SE & Co. KG exemplify archetypes of regional dominance versus research-focused positioning. SKF Group represents the listed multinational structure with integrated manufacturing scale. These three occupy positions across the competitive spectrum without overlapping segment focus.
| Leading Market Players |
|---|
| The Timken Company |
| New Way Air Bearings |
| SKF Group |
| Oiles Corporation |
| Physik Instrumente (PI) SE & Co. KG |
| JTEKT Corporation |
| RBC Bearings Inc. |
| Leuven Air Bearings NV |
| Schaeffler AG |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between semiconductor equipment OEMs and precision bearing houses lock in both ceramic surface grinding access and price visibility across the analysis window. These arrangements tether procurement costs to clean dry air infrastructure commitments, compressing margin flexibility for machine tool retrofit segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EUV lithography stages from CMM retrofits from basic metrology spindles. Price differentiation rests on ISO 14644-1 cleanroom certification grade and sub-micrometer restrictor tolerance achievement. Pricing pressure stems from South Korean electronics manufacturers publishing open performance specifications that disintermediate traditional stage integrators. Machine tool OEMs in southern Germany exhibit lowest price sensitivity due to captive bearing production, while Indian precision machinery startups face acute cost compression.
Supply Chain Analysis
Precision grinding and lapping capabilities for ceramic bearing surfaces cluster in southern Germany and parts of Japan, creating single-source vulnerability for orifice-compensated architectures. Raw material dependencies draw from alumina ceramic substrates, porous graphite feedstock, and high-purity nitrogen gas chemistries. Supply chain risk centers on REACH restrictions forcing validation of alternative lubrication schemes. Distribution runs through specialized motion control distributors for semiconductor stages and direct manufacturer relationships for machine tool spindles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air bearings market tracks semiconductor capital expenditure cycles, with EUV lithography rollout schedules serving as the primary cyclical recovery driver.
For Market Incumbents: Shield ceramic surface grinding capabilities through backward integration into southern German precision machining clusters. Active magnetic bearing substitution above 50 kilonewtons in aerospace test rigs demands R&D investment in hybrid gas-magnetic architectures. Capacity reservation contract structures anchor pricing power against spot-market volatility. For New Entrants and Emerging Players: Lead with cryogenic nanopositioning stages for quantum computing dilution refrigerators, where millikelvin operation requirements filter established suppliers. Indian PLI scheme incentives for semiconductor packaging equipment in Gujarat and Karnataka offer first-mover procurement relationships. ISO 14644-1 certification investment unlocks cell therapy manufacturing white space. For Investors and Strategic Acquirers: Regional precision motion specialists with captive air bearing production and established semiconductor equipment direct procurement relationships represent prime acquisition targets. Long-term viability hinges on exposure to EUV lithography expansion rather than machine tool retrofit cyclicality. Monitor ASML supplier qualification timeline compression as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grinding | Captures orifice-compensated restrictor fabrication capabilities concentrated in Stuttgart and Dresden clusters. |
| Clean Dry Air Infrastructure Partnership | Locks in facility-level gas distribution commitments with Samsung and SK Hynix engineering teams. |
| Cryogenic Bearing Certification Program | Validates millikelvin operation for quantum research instrumentation at Physik Instrumente specification tiers. |
| Direct Procurement Relationship Establishment | Disintermediates traditional stage integrators per South Korean open specification publishing trends. |
| Alternative Gas Chemistry R&D Investment | Accelerates nitrogen and helium-based lubrication schemes ahead of ECHA substance evaluation roadmaps. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and METI industrial standard certifications. Interviews with semiconductor equipment procurement managers, precision machinery OEM engineering directors, and ceramic grinding facility operators informed demand-side validation. Top-down market sizing triangulates against bottom-up segment aggregation across hydrostatic and magnetic levitation technology categories.
Segmentation dimensions modeled include bearing type, application criticality tier, end-user specification authority, and technology maturity curve position. CAGRs derive from installed base replacement cycles and penetration rate assumptions across the projection horizon. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and EPA perfluorinated lubricant restrictions.
The analysis sits within stated boundaries; outcomes outside EUV lithography equipment procurement consolidation trajectories would require recalibration. Forecasts reflect assumptions on clean dry air infrastructure buildout rates and ceramic surface grinding capacity expansion. Practitioners should keep alternative scenarios live as NMPA alignment with international metrology standards in China evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Global Vacuum Furnaces Market