
 Industrial Linear Accelerator Market | 2026-2036
Industrial Linear Accelerator Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Linear Accelerator Market Outlook
Accelerator physicist and RF engineer scarcity is redrawing competitive boundaries for high-energy system suppliers. Varian Medical Systems leverages its installed base in radiation oncology to sustain service revenue density across mature markets. Siemens Healthineers anchors European demand through integrated imaging-accelerator platforms that dominate university hospital procurement. IBA differentiates via proton and carbon therapy specialization, competing against photon-centric portfolios with heavier particle capability.
An industrial linear accelerator is a device that propels charged particles through a linear beam tube using radio-frequency electromagnetic fields, typically achieving electron energies from 4 MeV to 25 MeV for industrial or therapeutic applications. These systems generate ionizing radiation for material penetration, surface modification, or isotope production, with beam stability and dose uniformity serving as critical performance parameters. Compact and modular product types are capturing expanded share as manufacturing plants and research institutions prioritize footprint reduction and scalable deployment. Electron beam technology leads in industrial processing applications such as polymer crosslinking and sterilization, while hybrid systems integrating advanced imaging represent the fastest-expanding margin pool for inspection and quality assurance workflows.
The FDA enforces 21 CFR Part 1020 performance standards that govern x-ray system emissions and beam quality, directly shaping product development timelines for US-market accelerators. In Europe, the MDR and CE marking frameworks classify therapeutic linear accelerators as Class IIb or III medical devices, raising clinical evidence requirements for new system introductions. The IEC 60601-2-1 standard for medical electron accelerators provides the baseline safety and performance benchmark that manufacturers must satisfy for international market access. Stakeholders must monitor how evolving cybersecurity annexes to medical device regulations reshape software architecture requirements for connected accelerator platforms.
Market Dynamics
Accelerator physicist scarcity and RF engineering talent gaps are compressing development timelines for high-energy systems while medical facilities demand compact, integrated platforms that reduce installation footprint and service complexity.
Growth Catalysts
- MDR clinical evidence pathways:The European Medical Device Regulation's Class IIb and III classification for therapeutic linear accelerators is elevating barrier-to-entry for new competitors, entrenching established suppliers with existing clinical data portfolios.
- Polymer crosslinking demand:Electron beam processing for industrial polymer modification is expanding as manufacturers seek solvent-free curing alternatives to thermal methods in packaging and automotive component production.
- University hospital procurement concentration:Germany's dense cluster of particle therapy centers around Heidelberg and Munich is generating sustained replacement demand for integrated imaging-accelerator platforms.
Market Restraints
- RF power component volatility:Klystron and magnetron supply chains concentrate among a handful of specialty manufacturers, exposing system integrators to lead-time fluctuations for critical microwave sources.
- Beam stability physics limits:Achieving sub-millimeter dose uniformity across 25 MeV electron energies requires precision engineering that extends factory acceptance testing cycles and inflates working capital requirements.
- FDA 21 CFR Part 1020 compliance friction:The agency's tightening diagnostic x-ray performance standards are lengthening 510(k) review timelines for systems with imaging integration, delaying US market entry for new platform introductions.
Strategic Opportunities
- Isotope production diversification:Cyclotron and linear accelerator convergence for medical radioisotope generation is opening new revenue streams as regional supply chains seek reduced dependence on centralized production facilities.
- Cybersecurity annex adaptation:Evolving software architecture requirements under MDR and FDA guidance documents for connected medical devices are creating service contract opportunities for qualified integrators.
- India industrial inspection penetration:Non-destructive testing infrastructure expansion in Mumbai and Chennai manufacturing corridors is generating first-time system demand from domestic quality assurance departments.
Industry Challenges
- Accelerator physicist recruitment:The specialized intersection of beam dynamics, RF engineering, and radiation safety expertise commands premium compensation that strains mid-tier system manufacturers' R&D staffing models.
- IEC 60601-2-1 certification complexity:Third-party testing for medical electron accelerator safety and performance benchmarks requires 12-18 month validation cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Linear Accelerator Market |
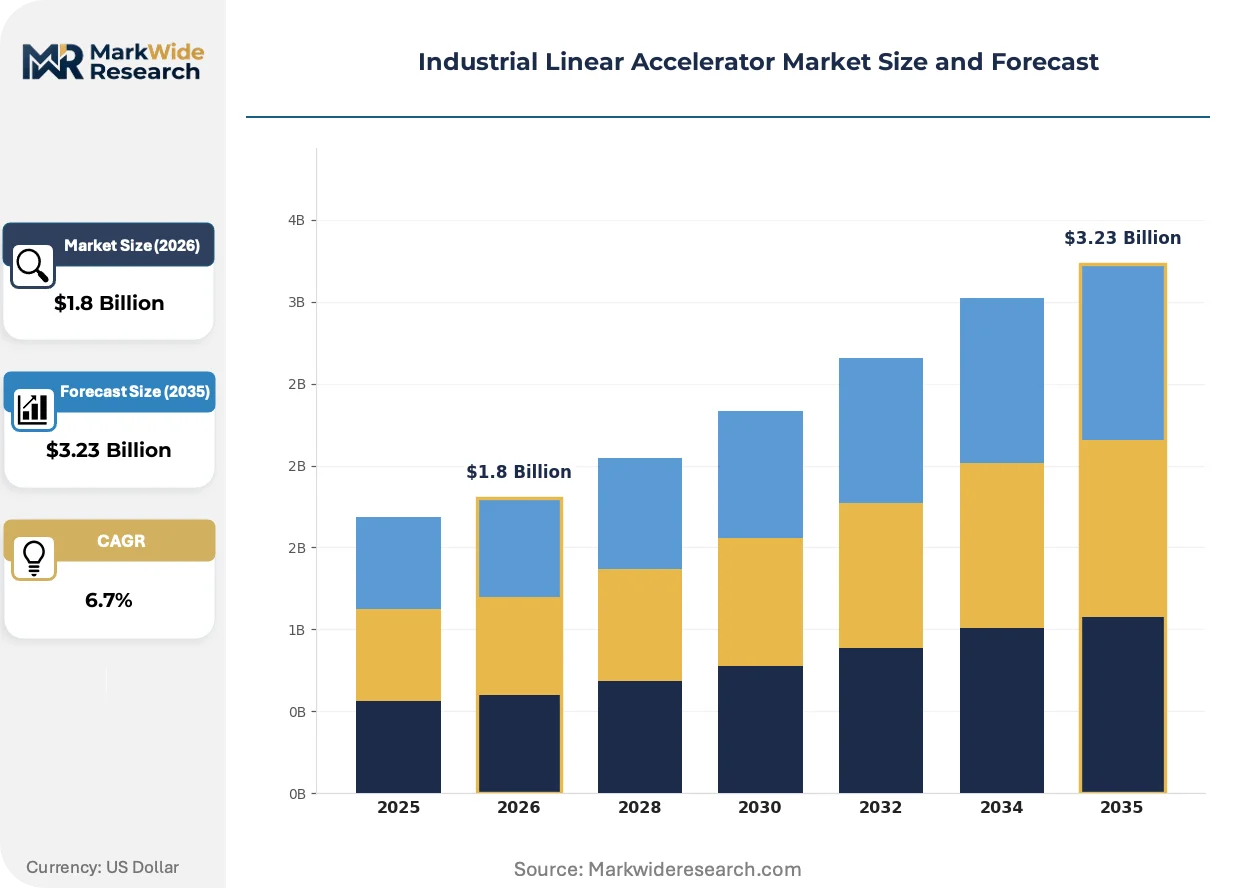
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Multi-Stage, Compact, Modular Technology: Electron Beam, Photon Beam, Hybrid System, Advanced Imaging End User: Manufacturing Plants, Research Institutions, Medical Facilities, Defense Application: Radiation Therapy, Material Inspection, Particle Acceleration, Industrial Processing |
| Companies Covered | Varian Medical Systems, Elekta, Accuray Incorporated, Siemens Healthineers, IBA, Iotron Industries, Mitsubishi Heavy Industries, High Voltage Engineering Europa, Wasik Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Linear Accelerator Market Strategic Shifts
System architectures are compressing physical footprints while software-defined beam control and service model unbundling are redrawing how buyers evaluate total cost of ownership across deployment lifecycles.
Superconducting radio-frequency cavity technology is miniaturizing. Research institutions and compact proton therapy centers are adopting these systems to achieve higher gradient acceleration in reduced physical envelopes. This compression is enabling installation in retrofit clinical spaces previously inaccessible to conventional warm-copper linac designs.
Europe's MDR cybersecurity annexes are mandating software bill of materials and vulnerability management protocols for connected accelerator platforms. Manufacturers must revalidate legacy system architectures or sunset non-compliant product lines. German university hospitals are prioritizing procurement from suppliers with demonstrated IEC 62304 medical device software lifecycle certification.
After-sales service unbundling is fragmenting traditional full-service contracts. Large hospital networks in the United States are separating hardware maintenance from physics support and software upgrades, pressuring OEM margin structures. This disaggregation is most pronounced in radiation oncology departments with in-house medical physics capabilities seeking à-la-carte spare parts and remote diagnostics access.
Industrial Linear Accelerator Market Segmentation
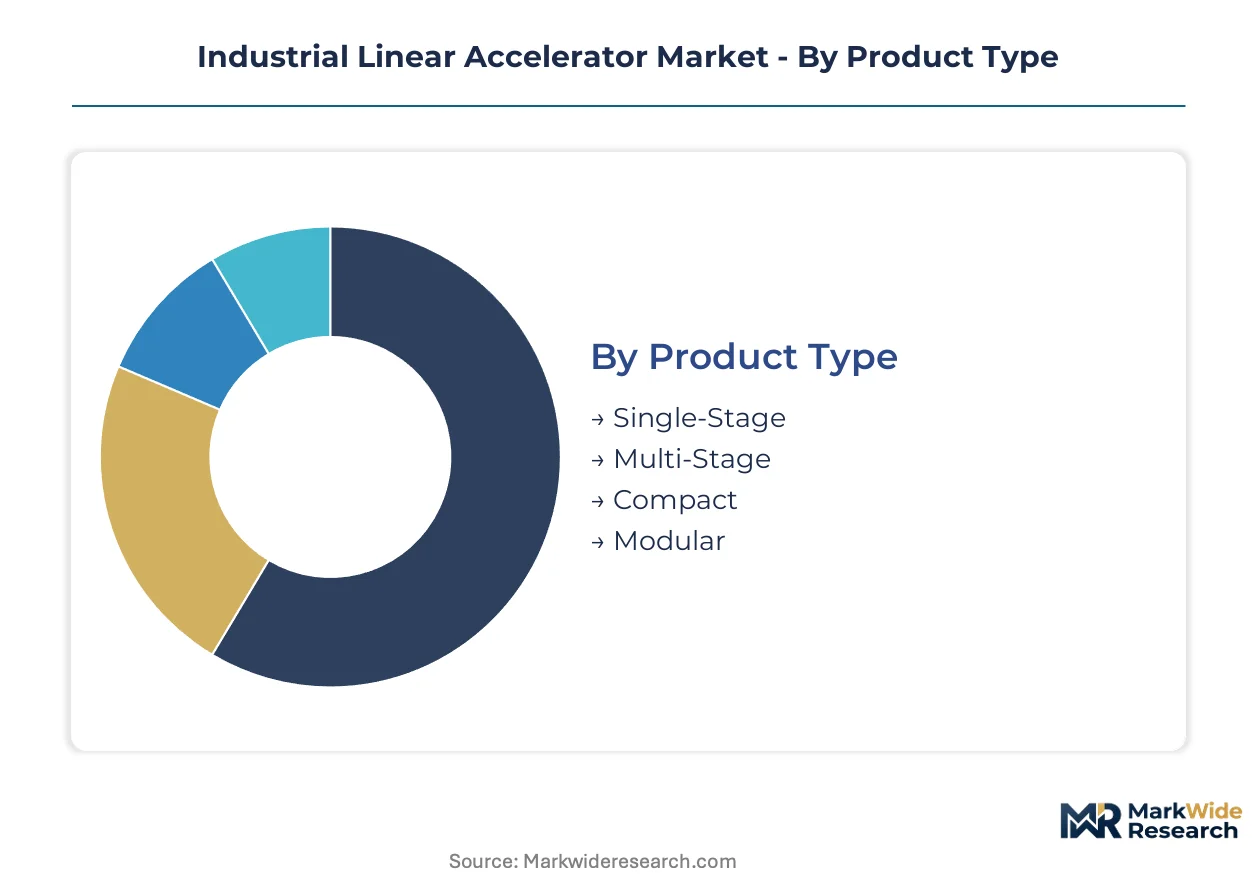
Accelerator system architecture fragments across four distinct product configurations, each commanding different service revenue density and installation complexity. Technology pathways diverge sharply between industrial processing and therapeutic applications, with hybrid platforms capturing premium positioning through integrated imaging capability.
Product Type:
Margin pools concentrate in compact and modular architectures as end-users prioritize footprint reduction and scalable deployment pathways over maximum energy output.
- Compact:These systems achieve electron energies up to 10 MeV within reduced physical envelopes, enabling retrofit installation in existing manufacturing plants and clinical suites where space constraints previously blocked accelerator deployment. Medical facilities in Germany and the United States are driving procurement concentration as radiation therapy departments seek to expand treatment capacity without structural renovation.
- Modular:Scalable beamline architectures permit field-upgradable energy tiers and auxiliary system integration, extending platform lifecycles through phased capital investment. Manufacturing plants across polymer processing and sterilization applications favor this flexibility to match throughput expansion without full system replacement.
- Single-Stage:Fixed-gradient designs deliver cost-efficient electron acceleration for standardized industrial inspection workflows with predictable throughput requirements.
- Multi-Stage:Cascaded acceleration architectures achieve higher terminal energies for specialized particle therapy and isotope production applications requiring beam energies beyond 20 MeV.
Compact systems hold installed capacity. Modular architectures are rotating up the share rankings.
Technology:
Volume leadership sits with electron beam platforms, though margin expansion concentrates in hybrid configurations that merge therapeutic delivery with real-time imaging verification.
- Electron Beam:Direct electron acceleration dominates industrial polymer crosslinking, sterilization, and surface modification applications where penetration depth requirements remain below 25 MeV. Manufacturing plants in automotive component and medical device packaging sectors anchor demand concentration for solvent-free curing alternatives.
- Hybrid System:Integrated accelerator-imaging platforms combine therapeutic beam delivery with cone-beam CT or MRI guidance, commanding premium pricing through reduced setup uncertainty and adaptive treatment capability. University hospital procurement in Germany and the United States is concentrating demand as facilities replace legacy photon-only systems.
- Photon Beam:Bremsstrahlung conversion of electron beams generates penetrating x-ray spectra for radiation therapy and non-destructive testing applications requiring deep material penetration.
- Advanced Imaging:Standalone imaging subsystems for beam verification and quality assurance represent a discrete technology tier with specialized regulatory pathways under FDA 21 CFR Part 1020 and MDR cybersecurity annexes.
Electron beam technology commands volume leadership. Hybrid systems are climbing the fastest through premium procurement channels.
End User:
Customer type determines service contract structure, with medical facilities demanding comprehensive physics support while manufacturing plants prioritize spare parts availability and remote diagnostics access.
- Medical Facilities:Radiation oncology departments and proton therapy centers require FDA 510(k) or MDR Class IIb/III certified systems with integrated quality assurance workflows. Procurement concentrates in German university hospitals and United States cancer center networks with established medical physics staffing.
- Manufacturing Plants:Polymer processing, sterilization, and non-destructive testing operations demand high-uptime systems with rapid spare parts turnaround. Quality assurance departments in Mumbai and Chennai manufacturing corridors are generating first-time system demand as domestic inspection infrastructure expands.
- Research Institutions:National laboratories and university physics departments prioritize beam parameter flexibility and experimental access over production throughput metrics.
- Defense:Specialized applications in materials testing and radiation effects simulation operate under distinct procurement and security classification protocols.
Medical facilities hold installed capacity. Manufacturing plants are rotating up the share rankings.
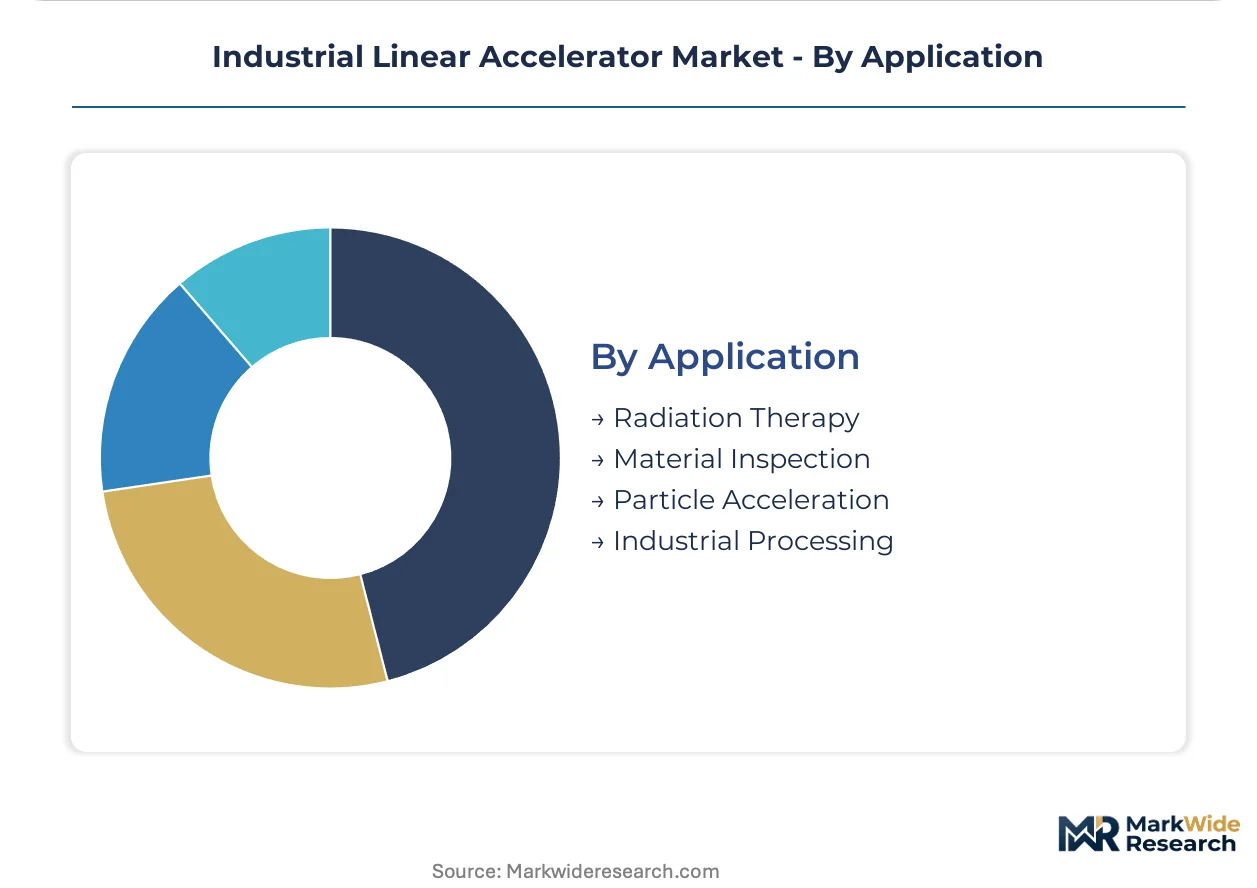
Application:
Revenue stability varies across application types, with radiation therapy delivering predictable replacement cycles while industrial processing tracks macroeconomic manufacturing investment patterns.
- Radiation Therapy:External beam delivery for oncological treatment requires precise dose uniformity and sub-millimeter positioning accuracy, driving specification intensity and extended factory acceptance testing. Demand concentrates in markets with aging installed bases and expanding public reimbursement for advanced modalities.
- Industrial Processing:Electron beam polymer crosslinking, grafting, and sterilization applications prioritize throughput reliability and energy efficiency over beam parameter flexibility. Packaging and automotive component manufacturers are expanding adoption as environmental regulations tighten restrictions on solvent-based thermal curing methods.
- Material Inspection:Non-destructive testing for weld integrity, casting quality, and composite structure verification serves aerospace, energy, and infrastructure sectors with cyclical capital equipment investment patterns.
- Particle Acceleration:Fundamental research and isotope production applications represent specialized demand with custom system specifications and extended development timelines.
Radiation therapy holds installed capacity. Industrial processing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 1020 performance standards anchor the United States as the dominant geography for regulatory-driven accelerator development. Beam quality requirements are tightening across diagnostic x-ray systems, extending 510(k) review timelines for integrated imaging platforms. Germany's dense supplier ecosystem around Heidelberg and Munich generates sustained replacement demand for particle therapy systems.
United States
Cancer center networks in Texas and California are expanding radiation therapy capacity through compact system procurement. FDA 510(k) pathways for therapeutic linear accelerators require extensive clinical evidence portfolios that entrench established suppliers. The Greater Boston corridor hosts concentrated medical physics research institutions driving adaptive therapy algorithm development.
Germany
University hospitals in Bavaria and Baden-Württemberg dominate European procurement for integrated imaging-accelerator platforms. MDR Class IIb and III classifications elevate clinical evidence requirements, compressing market entry opportunities for new competitors. The Heidelberg cancer research cluster sustains demand for proton and carbon therapy specialization.
India
Quality assurance departments in Mumbai and Chennai manufacturing corridors are generating first-time system demand for non-destructive testing infrastructure. CDSCO medical device regulations are aligning with international standards for radiation-emitting equipment. Domestic polymer processing plants in Gujarat are adopting electron beam sterilization to replace solvent-based thermal curing.
Japan
Metropolitan Tokyo and Osaka medical centers prioritize hybrid accelerator-imaging platforms with real-time beam verification. PMDA pharmaceutical and medical device agency reviews emphasize software lifecycle documentation under IEC 62304 protocols. Heavy industrial manufacturers in Nagoya are integrating electron beam systems into automotive component surface modification workflows.
China
Provincial hospital networks in Jiangsu and Guangdong are expanding radiation oncology departments with domestically manufactured compact accelerators. NMPA medical device registration pathways are streamlining for Class III therapeutic equipment with established international safety benchmarks. Research institutions in the Yangtze River Delta are piloting superconducting radio-frequency cavity technology for reduced-footprint proton therapy.
Industrial Linear Accelerator Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure. The upper tier commands premium positioning through installed base density and comprehensive service networks. The specialist tier competes on particle therapy specialization, industrial processing customization, and regional price positioning. Dominant competitive moves include portfolio diversification into isotope production and strategic partnerships for RF power component supply security.
Among diversified health technology conglomerates, Siemens Healthineers and Varian Medical Systems exemplify integrated platform strategies. IBA occupies a distinct position within the particle therapy specialization archetype, competing through heavier ion capability against photon-centric portfolios. Mitsubishi Heavy Industries represents the industrial-scale fabrication tier, leveraging heavy engineering heritage for high-energy system construction.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta |
| Accuray Incorporated |
| Siemens Healthineers |
| IBA |
| Iotron Industries |
| Mitsubishi Heavy Industries |
| High Voltage Engineering Europa |
| Wasik Associates |
| Others |
Value Chain & Pricing Dynamics
Klystron-to-solid-state RF power source substitution is redrawing procurement geography toward East Asian semiconductor fabrication clusters while compressing legacy tube-based system pricing premiums. This component transition simultaneously elevates capital requirements for next-generation architectures and erodes service contract margins tied to tube replacement cycles.
Pricing Analysis
Long-term service contracts dominate therapeutic system procurement, with full-service agreements bundling hardware maintenance, physics support, and software upgrades commanding premium positioning. Price differentiation rests on MDR Class III certification tier and installed base density for spare parts logistics. Cost compression in compact industrial systems is intensifying because domestic Chinese manufacturers are penetrating polymer processing segments with simplified electron beam platforms. Manufacturing plants in Gujarat and Maharashtra exhibit highest price sensitivity, while German university hospitals prioritize certification depth over acquisition cost.
Supply Chain Analysis
Magnetron and klystron manufacturing concentrates in the United States, Japan, and Germany, creating concentrated chokepoints for microwave source procurement. System integrators draw from specialized ceramic insulator foundries in Austria, precision machining clusters in Switzerland, and RF power semiconductor fabrication in South Korea. Single-source vulnerability in superconducting niobium cavity supply exposes proton therapy system builders to raw material allocation risk. Distribution runs through direct OEM sales for medical facilities and regional distributor networks for industrial inspection equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in compact accelerator deployment for retrofit clinical spaces and industrial sterilization infrastructure justifies capacity positioning ahead of MDR compliance deadlines and FDA 510(k) backlog clearance.
For Market Incumbents: Consolidate service revenue density through physics support contract renewal lock-in and backward integration into RF power component refurbishment. Varian Medical Systems' installed base maintenance model demonstrates how captive service networks neutralize price competition from emerging compact system suppliers. Prioritize MDR clinical evidence portfolio expansion to elevate regulatory barriers against photon-centric challengers. For New Entrants and Emerging Players: Anchor in Mumbai and Chennai manufacturing corridor quality assurance departments where first-time non-destructive testing system demand outpaces established service infrastructure. Industrial polymer crosslinking applications in Gujarat offer penetrable entry points with lower certification friction than radiation oncology. Pursue equipment-as-a-service positioning to circumvent capital budget constraints at mid-tier manufacturing plants. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial inspection specialists holding regional distributor networks but lacking integrated imaging capability. Five-to-ten year viability hinges on convergence toward hybrid accelerator-imaging platforms and isotope production diversification. Monitor FDA 510(k) review timeline compression as inflection signal for new platform market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| RF Power Component Backward Integration | Captive magnetron refurbishment capacity insulates margin from supply chain volatility. |
| MDR Clinical Evidence Portfolio Expansion | Class III certification depth entrenches positioning against photon-centric competitors. |
| Compact System Platform Launch | Retrofit clinical space penetration captures replacement demand without structural renovation. |
| Isotope Production Joint Venture | Cyclotron-linear accelerator convergence opens regional supply chain independence revenue. |
| Cybersecurity Service Contract Development | IEC 62304-compliant software architecture support captures MDR annex adaptation demand. |
Study Parameters
Cross-validation between accelerator physicist interviews and FDA 510(k) filing analysis anchors the qualitative findings on regulatory pathway friction. Primary engagement with radiation oncology department heads, biomedical engineers at German university hospitals, polymer processing plant managers in Gujarat, and RF component procurement leads at system integrators combined with secondary validation through IEC 60601-2-1 standard documentation, MDR guidance annexes, and NMPA registration databases. Bottom-up segmentation modeling triangulates against top-down macroeconomic manufacturing investment indicators.
Sensitivity analysis across beam energy tier, end-use certification requirement, and regional regulatory cluster shapes the analytical framework over the projection horizon. CAGRs derive from installed base replacement cycle analysis and first-time system penetration modeling in emerging manufacturing corridors. Superconducting cavity adoption curves and electron beam processing capacity expansion plans feed industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable FDA review timeline and MDR implementation assumptions; material deviation in regulatory enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as cybersecurity annex evolution and RF power source technology transition mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Portable Laser Cleaning Machine Market