
 Europe Ceramic Roller Bearings Market | 2026-2036
Europe Ceramic Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ceramic Roller Bearings Market Intelligence
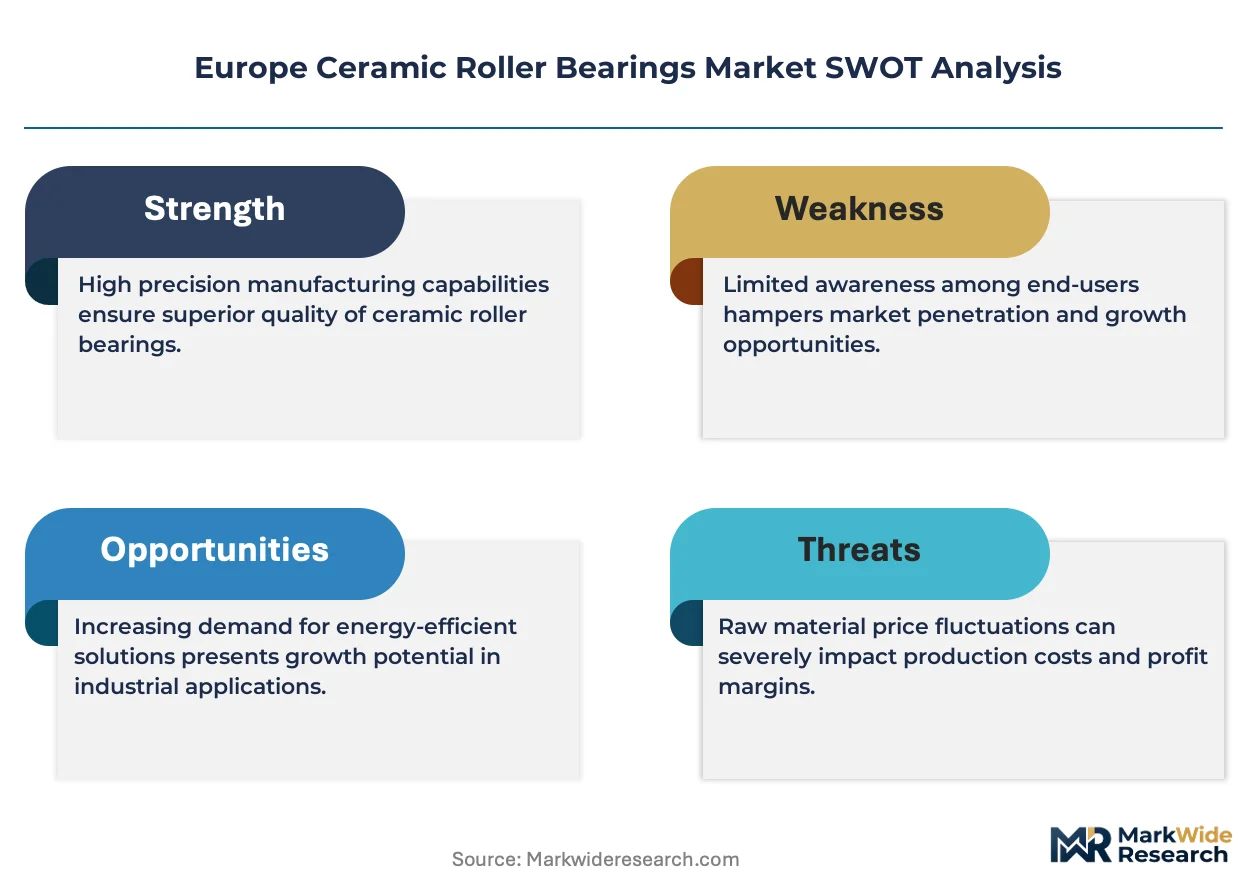
Hybrid-grade specification upgrades is bifurcating the Europe ceramic roller bearings landscape into performance-differentiated supply tiers. SKF Group leverages its Nordic manufacturing footprint to sustain premium positioning across aerospace and renewable energy channels. Schaeffler Group anchors German industrial demand through specialized ceramic-to-steel hybrid architectures. CeramTec GmbH differentiates via captive silicon nitride powder production, controlling upstream material consistency for medical and precision robotics applications.
Europe ceramic roller bearings are precision-engineered rolling elements fabricated from silicon nitride, zirconia, or alumina ceramics, typically operating at temperatures exceeding 300°C with corrosion resistance unattainable by conventional steel alloys. Their primary purpose is to eliminate lubrication dependency and extend service intervals in extreme environments spanning jet engines, vacuum pumps, and electric drivetrains. Silicon nitride formulations lead material selection due to fracture toughness and thermal shock resistance, while zirconia grades command margin pools in dental and medical spindle applications where biocompatibility governs specification. Angular contact configurations are gaining share in renewable energy installations, particularly wind turbine main shaft arrangements where electrical insulation properties prevent bearing current damage.
EMA medical device directives and REACH chemical substance restrictions shape material certification pathways for ceramic bearings entering European healthcare and industrial channels. The EU Green Deal's decarbonization mandates accelerate steel-to-ceramic substitution in automotive electrification programs, with CE marking requirements enforcing dimensional and load-capacity traceability. Germany's KBA vehicle type-approval framework extends these standards into automotive bearing supply chains. Stakeholders must monitor evolving EU AI Act implications for smart bearing condition-monitoring systems and assess whether in-house ceramic powder synthesis or qualified external sourcing better protects margin structures against raw material volatility.
Market Dynamics
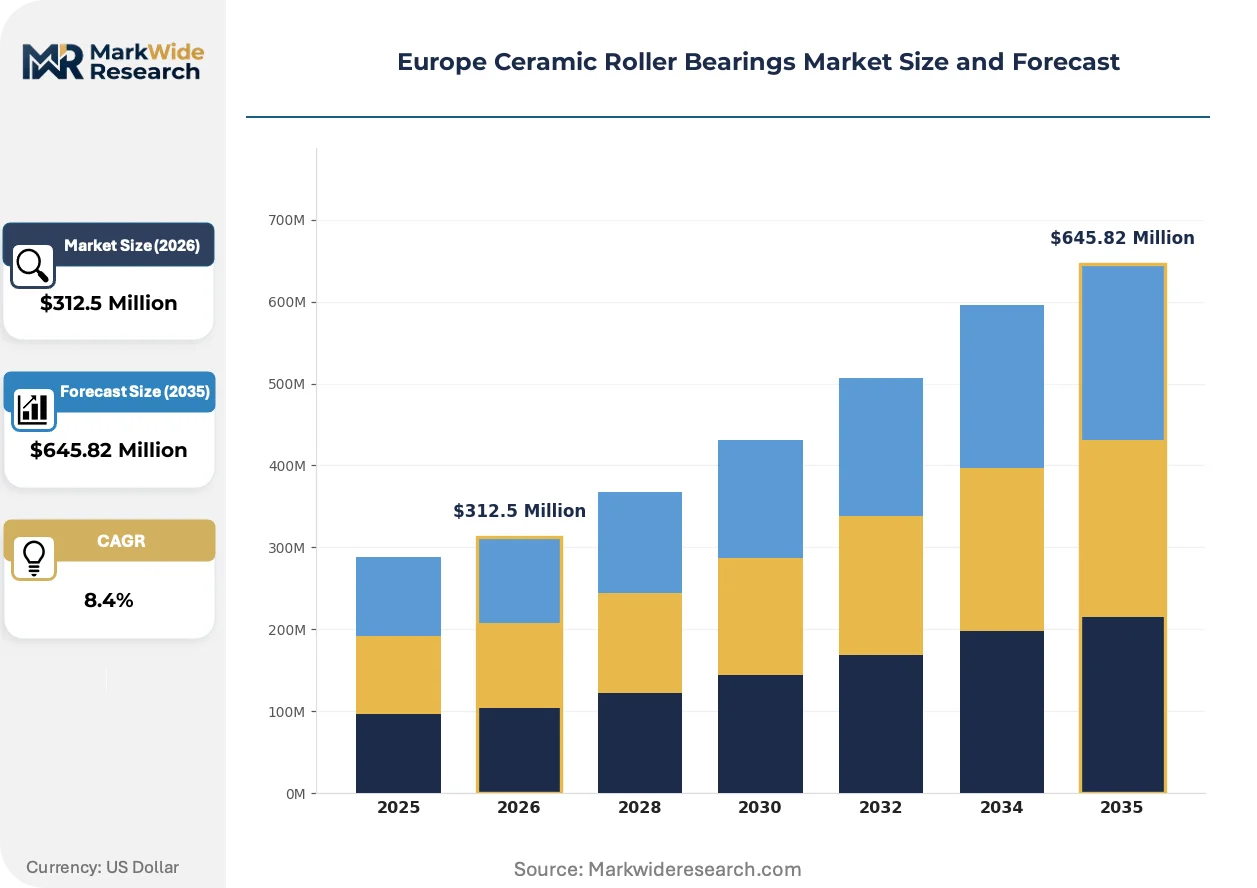
The EU Green Deal's decarbonization mandates are compressing steel-to-ceramic substitution timelines across automotive and industrial applications, while REACH compliance requirements are elevating material certification barriers that favor incumbent ceramic suppliers with established ECHA dossiers.
Growth Catalysts
- EMA Medical Device Regulation:MDR compliance deadlines are accelerating ceramic bearing qualification for surgical robotics and imaging equipment, creating captive demand for biocompatible zirconia grades.
- Wind turbine OEMs:Main shaft electrical insulation requirements in North Sea offshore installations are displacing steel hybrid configurations with full-ceramic angular contact arrangements.
- Bavaria-Baden-Württemberg industrial belt:Precision manufacturing cluster density is concentrating specialized bearing procurement around Stuttgart and Munich metropolitan zones.
Market Restraints
- Silicon nitride powder supply:Upstream ceramic powder production concentrates among Japanese and Chinese suppliers, exposing European fabricators to input cost volatility and freight disruption.
- Fracture toughness ceiling:Ceramic material brittleness limits load-bearing capacity in heavy industrial gearboxes, constraining addressable market share against case-hardened steel alternatives.
- CE marking complexity:Multi-country notified body fragmentation extends certification timelines for cross-border medical device bearing shipments.
Strategic Opportunities
- Poland and Czech Republic:Automotive electrification supply chains are migrating eastward from Germany, creating greenfield demand for localized ceramic bearing fabrication capacity.
- EU AI Act compliance:Smart bearing condition-monitoring systems with embedded sensors qualify for preferential procurement in Industry 4.0 subsidization frameworks.
- Convergence of additive manufacturing with ceramic sintering:Near-net-shape production of complex bearing geometries is compressing material waste and lead times for low-volume precision applications.
Industry Challenges
- Ceramic metallization expertise:Hybrid bearing production requires rare bonding process knowledge between ceramic races and steel cages, constraining workforce scalability.
- ISO 492 dimensional certification:Precision tolerance verification for ABEC 7/9 grades demands capital-intensive coordinate measuring infrastructure that mid-tier fabricators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ceramic Roller Bearings Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Groove, Angular Contact, Thrust, Self-Aligning End User: Aerospace, Automotive, Industrial Equipment, Renewable Energy Material: Silicon Nitride, Zirconia, Alumina, Others Application: Motorcycles, Electric Motors, Pumps, Robotics |
| Companies Covered | SKF Group, Schaeffler Group, NSK Ltd., CeramTec GmbH, NTN Corporation, JTEKT Corporation, Timken Company, CeramicSpeed, Ortech Advanced Ceramics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ceramic Roller Bearings Market Strategic Shifts & Innovations
Material science advances and regulatory pressure are reshaping how ceramic bearings are specified, manufactured, and integrated into European industrial systems. Three convergent developments are restructuring competitive advantage.
Silicon nitride formulations with enhanced fracture toughness are bifurcating the performance spectrum between commodity hybrid bearings and aerospace-grade full-ceramic assemblies. Jet engine OEMs in Germany and France are qualifying these materials for turbine auxiliary systems at accelerated schedules. The technology is bifurcating supplier tiers into powder-synthesis-integrated specialists versus assembly-only fabricators.
REACH substance restriction expansions are compelling reformulation of bearing lubricants and surface treatments used in ceramic-steel hybrid architectures. ECHA's candidate list updates are disqualifying traditional PTFE-based coatings from food-contact and medical applications. Wind turbine and vacuum pump manufacturers are responding by specifying dry-running ceramic configurations that eliminate lubrication dependency entirely.
Buyer consolidation among European wind energy OEMs is compressing supplier qualification cycles and unbundling aftermarket service contracts from initial equipment procurement. Vestas and Siemens Gamesa are centralizing bearing sourcing through framework agreements that displace distributor intermediaries. This pattern is most visible in Denmark and northern Germany, where offshore turbine assembly concentrates procurement leverage among three dominant buyers.
Europe Ceramic Roller Bearings Market Segmentation
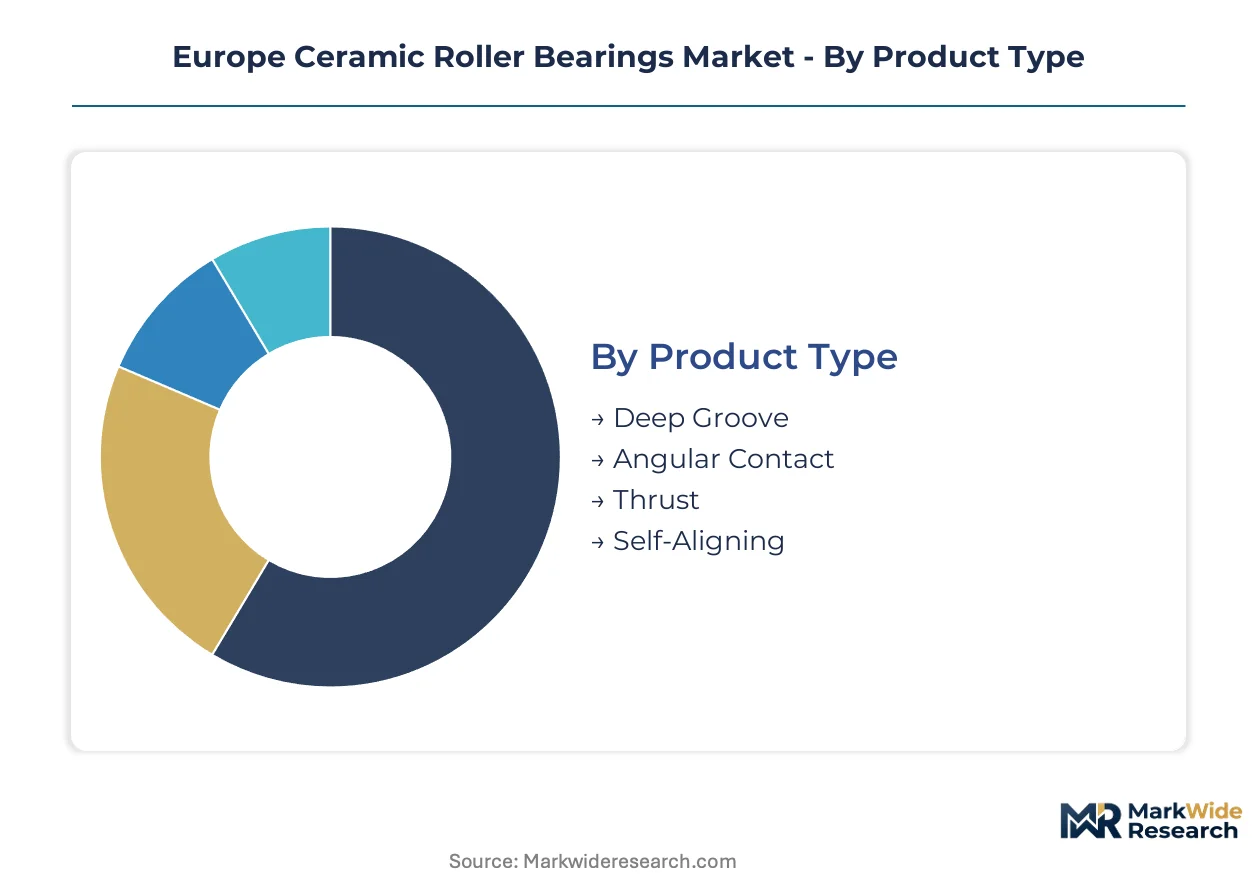
Ceramic roller bearing procurement in Europe flows through distinct channel architectures that vary by technical complexity and end-use criticality. Aerospace and medical applications route through direct OEM partnerships with certified fabricators, while industrial volumes move via specialized distributor networks concentrated in Germany's manufacturing belt.
Product Type:
Channel access for ceramic bearing types correlates with precision grade — angular contact and deep groove configurations reach end-users through authorized technical distributors, while thrust and self-aligning variants flow through industrial supply houses serving maintenance-repair-operations demand.
- Deep Groove:Full ceramic and hybrid deep groove bearings accommodate combined radial and axial loads in high-speed electric motor applications. Demand concentrates in Bavaria's industrial automation cluster, where REACH-compliant dry-running specifications are displacing steel alternatives in food processing equipment.
- Angular Contact:These configurations manage simultaneous radial and thrust loads with precise contact angle control, essential for wind turbine main shaft arrangements. North Sea offshore installations in Denmark and northern Germany specify full-ceramic angular contact bearings for electrical insulation properties that prevent bearing current damage.
- Thrust:Axial-load specialists serve vertical pump and compressor applications across Europe's chemical processing infrastructure.
- Self-Aligning:Compensating bearing housings address misalignment in heavy industrial gearboxes with limited ceramic penetration due to fracture toughness constraints.
Angular contact dominates installed base in renewable energy. Deep groove is where expansion concentrates.
End User:
Cost tier stratification separates aerospace qualification programs requiring EASA certification from automotive electrification procurement governed by KBA type-approval frameworks.
- Aerospace:Jet engine auxiliary systems and landing gear applications demand silicon nitride bearings with fracture toughness exceeding 7 MPa·m½. German and French OEMs are compressing supplier qualification cycles for turbine applications.
- Automotive:Electric drivetrain bearings must satisfy KBA vehicle type-approval while eliminating rare earth magnet corrosion risks through ceramic electrical isolation.
- Industrial Equipment:Vacuum pumps and semiconductor manufacturing equipment in Baden-Württemberg specify dry-running ceramic configurations to eliminate hydrocarbon contamination.
- Renewable Energy:Wind turbine OEM procurement centralization through framework agreements is displacing distributor intermediaries in Denmark and northern Germany.
Industrial equipment dominates installed base. Renewable energy is climbing the fastest.
Material:
Volume concentration in silicon nitride contrasts with margin concentration in specialized ceramic formulations serving medical biocompatibility requirements.
- Silicon Nitride:Leading fracture toughness and thermal shock resistance above 300°C operating temperatures make this the default for aerospace and industrial applications. Powder supply concentrates among Asian suppliers, exposing European fabricators to input volatility.
- Zirconia:Transformation-toughened zirconia grades command premium positioning in dental and medical spindle applications where EMA MDR biocompatibility governs specification.
- Alumina:Cost-competitive alumina bearings serve lower-load industrial applications with adequate corrosion resistance at reduced material cost.
- Others:Emerging silicon carbide and composite formulations address niche high-temperature applications beyond standard nitride capabilities.
Silicon nitride dominates installed base. Zirconia is where margin expansion concentrates.
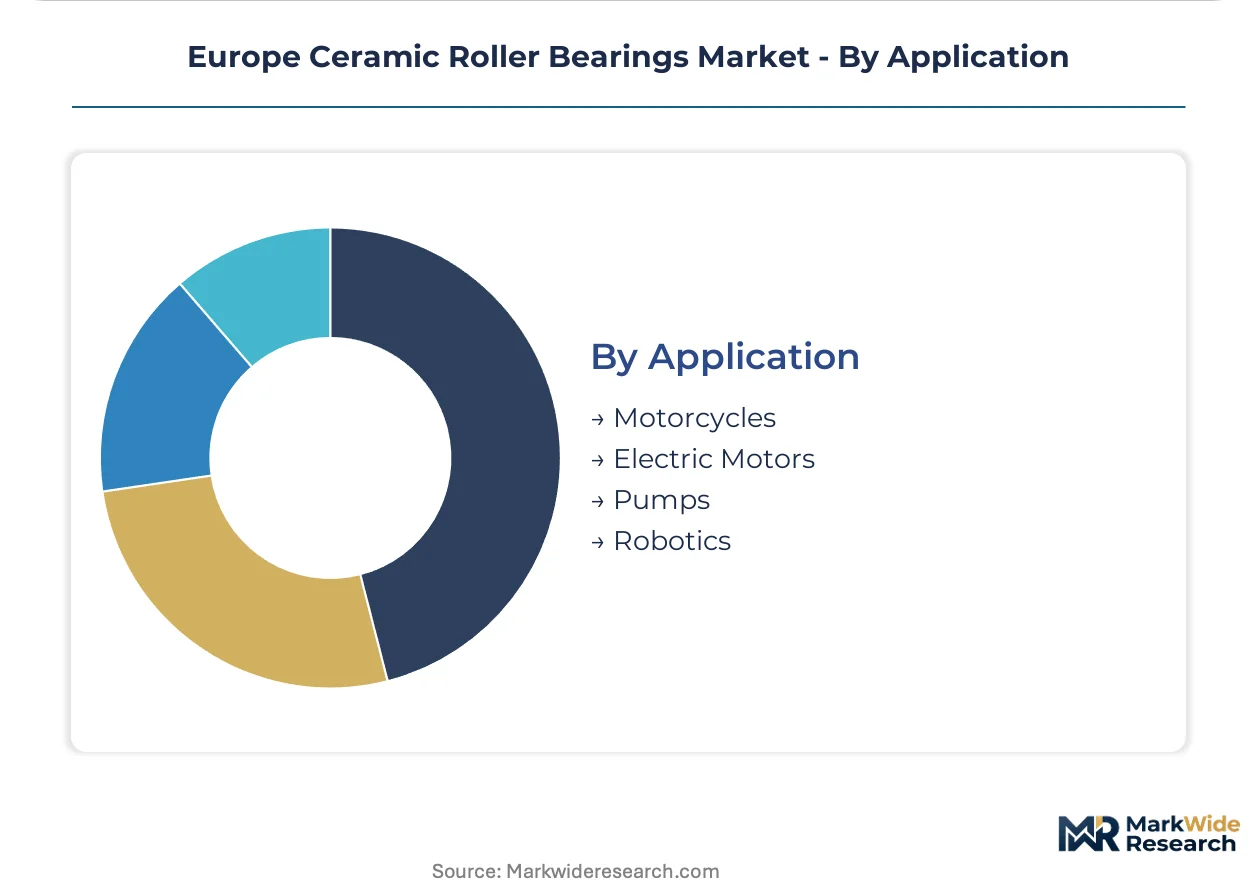
Application:
Customer type segmentation separates OEM specification teams designing new equipment from aftermarket procurement focused on maintenance interval extension.
- Motorcycles:High-performance racing and premium street applications in Italy and Germany specify hybrid ceramic bearings for reduced friction and extended service intervals.
- Electric Motors:Industrial motor OEMs in Stuttgart and Munich metropolitan zones are standardizing ceramic insulation to prevent bearing currents in variable frequency drive applications.
- Pumps:Chemical and pharmaceutical pump manufacturers specify corrosion-resistant ceramic bearings for aggressive fluid handling.
- Robotics:Surgical robotics and precision automation in Germany's medical technology cluster demand zirconia bearings with MDR-compliant biocompatibility certification.
Electric motors dominate installed base. Robotics is where specification intensity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's ceramic roller bearings trade flows reveal a structural deficit in upstream silicon nitride powder, forcing fabricators to import raw materials from Asian suppliers while exporting finished precision bearings to aerospace and medical OEMs worldwide.
Germany
KBA vehicle type-approval frameworks and EU Green Deal electrification mandates are accelerating ceramic bearing adoption across Stuttgart and Munich industrial zones. Bavaria's precision manufacturing cluster concentrates demand for electric drivetrain insulation solutions, while Baden-Württemberg's vacuum pump manufacturers specify dry-running configurations to eliminate hydrocarbon contamination risks.
France
ANSM medical device oversight and EASA aerospace certification requirements are compressing supplier qualification timelines for turbine auxiliary systems. The Île-de-France aerospace corridor around Paris hosts jet engine OEMs expanding silicon nitride procurement for landing gear and auxiliary power unit applications.
Italy
High-performance motorcycle OEMs in the Emilia-Romagna motor valley specify hybrid ceramic bearings for racing and premium street applications. CE marking enforcement through notified bodies in Milan and Turin extends certification timelines for cross-border medical device bearing shipments.
Denmark
Offshore wind turbine assembly concentration in Copenhagen and Aarhus metropolitan zones is centralizing procurement leverage among Vestas and Siemens Gamesa. Framework agreements are displacing distributor intermediaries and specifying full-ceramic angular contact bearings for main shaft electrical insulation in North Sea installations.
Poland
Automotive electrification supply chains migrating eastward from Germany are creating greenfield demand for localized fabrication capacity. The country's national industrial regulator is aligning certification pathways with EU REACH and MDR requirements to attract bearing manufacturers serving German OEMs.
Europe Ceramic Roller Bearings Market Key Industry Players
Concentration sits with diversified industrial conglomerates possessing captive powder synthesis capabilities and established ECHA dossiers. The vendor base separates into three strategic archetypes: Nordic-based precision specialists with aerospace certification depth, German industrial conglomerates leveraging automotive supply chain integration, and ceramic material scientists controlling upstream silicon nitride production. Capacity expansion and strategic partnerships dominate competitive moves, with fabricators securing qualified powder supply agreements and medical device OEMs locking in long-term qualification programs.
Among Nordic-based precision specialists, SKF Group anchors premium positioning across renewable energy and aerospace channels. Schaeffler Group occupies a position within the German industrial conglomerate tier, while CeramTec GmbH exemplifies the material science archetype through captive silicon nitride powder production. These three represent distinct competitive vectors: geographic certification advantage, automotive supply chain density, and upstream material control.
| Leading Market Players |
|---|
| SKF Group |
| Schaeffler Group |
| NSK Ltd. |
| CeramTec GmbH |
| NTN Corporation |
| JTEKT Corporation |
| Timken Company |
| CeramicSpeed |
| Ortech Advanced Ceramics |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Japanese and Chinese silicon nitride powder producers shapes both supply concentration and price floors for European fabricators, compressing margin structures when freight disruption elevates landed input costs. REACH compliance investments and CE marking complexity further stratify pricing power between incumbent suppliers with established ECHA dossiers and assembly-only fabricators lacking upstream integration.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across the European ceramic roller bearings market. Price differentiation rests on certification grade — EASA aerospace tiers command substantial premia over standard industrial ABEC ratings — and volume scale, with wind turbine OEM framework agreements extracting double-digit discounts from distributor channels. Cost compression in hybrid-grade bearings is intensifying because powder supply volatility exposes mid-tier fabricators to margin erosion. Aftermarket procurement teams at maintenance-repair-operations distributors exhibit highest price sensitivity, while aerospace qualification programs demonstrate least sensitivity due to captive specification requirements.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals fluctuate with Asia-Europe trade lane congestion, elevating working capital requirements for powder-dependent fabricators. Upstream supply concentrates in Japan, China, and Germany — the latter hosting captive synthesis at CeramTec while others import feedstock. Raw material dependencies span silicon nitride powder, zirconia precursors, and specialized steel for hybrid cages. Single-source vulnerability pervades the powder tier, where three Asian suppliers control fracture-toughened formulations. Distribution runs through authorized technical distributors for precision grades and industrial supply houses for maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel-to-ceramic substitution timelines are compressing, yet advanced case-hardened alloys and magnetic bearing technologies threaten to capture load-bearing applications where ceramic brittleness constrains penetration. Incumbents must navigate this substitution defense while securing powder supply and certification moats.
For Market Incumbents: Fortify upstream control through qualified powder supply agreements with Japanese suppliers or in-house synthesis investment, and deepen EASA certification depth to lock out second-tier competitors from aerospace procurement cycles. The threat of magnetic bearing displacement in heavy industrial gearboxes demands preemptive positioning in electrical insulation applications where ceramics retain irreplaceable advantage.
For New Entrants and Emerging Players: Anchor in Poland's emerging automotive electrification corridor, where German OEM supply chain migration creates greenfield demand for localized fabrication capacity without incumbent distributor entrenchment. The most penetrable white-space sits in medical robotics zirconia bearings, where EMA MDR compliance barriers deter generalist competitors and specialized qualification programs command sustainable margin pools.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material-science specialists with captive powder synthesis and established healthcare certification pathways over assembly-only fabricators exposed to input volatility. Long-term viability hinges on substitution durability against magnetic alternatives and steel advances. The signal to watch is wind turbine OEM consolidation velocity — framework agreement expansion accelerates supplier shakeout, while qualification cycle extension indicates durable pricing power for certified incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Nitride Powder Synthesis | Eliminates freight disruption exposure and secures fracture toughness consistency for aerospace qualification. |
| EASA Certification Depth Investment | Creates procurement lock-in with Safran and MTU turbine auxiliary system programs. |
| Poland Manufacturing Footprint Expansion | Captures automotive electrification supply chain migration from Stuttgart and Munich zones. |
| Smart Bearing Sensor Integration | Qualifies for EU AI Act subsidization frameworks in Industry 4.0 procurement channels. |
| Medical Robotics Zirconia Qualification | Locks in MDR-compliant biocompatibility certification ahead of surgical automation deployment waves. |
Research Approach
Desk research of ECHA REACH dossiers, EASA certification databases, and wind turbine OEM procurement disclosures preceded structured interviews with ceramic bearing plant managers, aerospace procurement leads at German and French OEMs, medical device R&D directors, and industrial distributor category managers. Primary fieldwork combined with secondary validation across SEC filings of listed bearing manufacturers, customs trade data for silicon nitride powder imports, and hospital procurement databases for medical spindle applications. Bottom-up fabrication capacity estimates triangulated against top-down end-use demand segmentation.
Variance decomposition across product type, material grade, end-use industry, and regional production cluster shaped the analytical framework over the projection horizon. CAGRs derived from regression analysis against industrial production indices, electrification penetration curves, and aerospace delivery backlogs. Modeled inputs incorporated REACH substance restriction timelines, EMA MDR compliance deadlines, and wind turbine installation forecasts for North Sea markets.
Material uncertainties — powder supply disruption, EASA qualification cycle extension, and magnetic bearing technology advancement — sit outside the modeled envelope. Forecasts reflect assumptions about substitution elasticity and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Global Special Purpose Machines Market