
 Sorter Machines Market | 2026-2036
Sorter Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Sorter Machines Market Analytics
Equipment leasing and pay-per-ton service contracts is reconfiguring competitive entry barriers for mid-sized processors. TOMRA Systems ASA leverages its vertical integration into sensor manufacturing to sustain margin control across optical sorting lines. Bühler Group anchors its position through deep specialization in food-grade sorting systems for grain and pulse processors. STEINERT competes primarily on electromagnetic and sensor-based metal recovery systems for recycling streams.
Sorter machines are automated material handling systems that use optical sensors, electromagnetic arrays, or mechanical grippers to classify objects by size, shape, color, density, or chemical composition at throughput rates exceeding multiple tons per hour. These systems execute real-time defect rejection, grade separation, and foreign-object removal to protect downstream product quality and equipment integrity. Optical sorters occupy the largest installed base due to mature vision-system technology and broad applicability across food and recycling operations. Robotic sorters represent the fastest-expanding category as articulated-arm platforms with machine-vision guidance penetrate irregular-object handling tasks in logistics and pharmaceutical packaging. Vision Systems technology leads R&D investment intensity, though infrared and laser sorting command premium pricing in high-value pharmaceutical and specialty food segments.
FDA food safety modernization requirements and EU REACH chemical compliance standards shape equipment design specifications for contact surfaces and sensor housing materials in regulated applications. EPA waste-stream classification rules and EU Green Deal circular-economy targets are accelerating capital deployment into automated recycling sortation infrastructure across North American and European processing facilities. Stakeholders must evaluate sensor technology roadmaps against pending regulatory shifts in food-contact approvals and extended-producer-responsibility frameworks before committing to multi-year capital cycles.
Market Dynamics
Optical sensor technology and AI-driven defect detection are systematically displacing legacy mechanical sorting systems across food processing and recycling facilities. This technology transition concentrates competitive advantage among suppliers with captive sensor manufacturing capabilities.
Growth Catalysts
- EU Green Deal circular-economy targets:Extended-producer-responsibility frameworks mandate automated recycling sortation infrastructure deployment across European processing facilities.
- Food-grade pulse processors:Grain and legume handlers expand optical line capacity to meet stricter contamination thresholds under evolving food safety mandates.
- Near-infrared spectroscopy:Chemical composition detection capabilities unlock premium pricing in pharmaceutical and specialty food segments.
Market Restraints
- Specialized sensor supply concentration:High-performance CMOS image sensor fabrication concentrates among Asian semiconductor foundries, creating input vulnerability.
- Capital intensity barrier:Multi-ton-per-hour optical sorting lines require seven-figure upfront investment, excluding smaller processors from technology access.
- Legacy mechanical installed base:Depreciation cycles on existing density-separation equipment delay replacement demand in mature recycling markets.
Strategic Opportunities
- India food processing modernization:FSSAI enforcement expansion and PLI scheme incentives create first-mover advantage for automated sorting deployment.
- Logistics irregular-object handling:Articulated-arm robotic platforms with machine-vision guidance penetrate e-commerce returns processing and pharmaceutical packaging.
- Pay-per-ton service contracting:Equipment leasing models reconfigure competitive entry barriers for mid-sized processors without capital access.
Industry Challenges
- Machine-vision engineering talent scarcity:Shortage of specialists capable of training convolutional neural networks for real-time defect classification limits deployment velocity.
- Legacy system integration complexity:Retrofitting optical sensors into existing mechanical conveying infrastructure requires custom mechanical engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorter Machines Market |
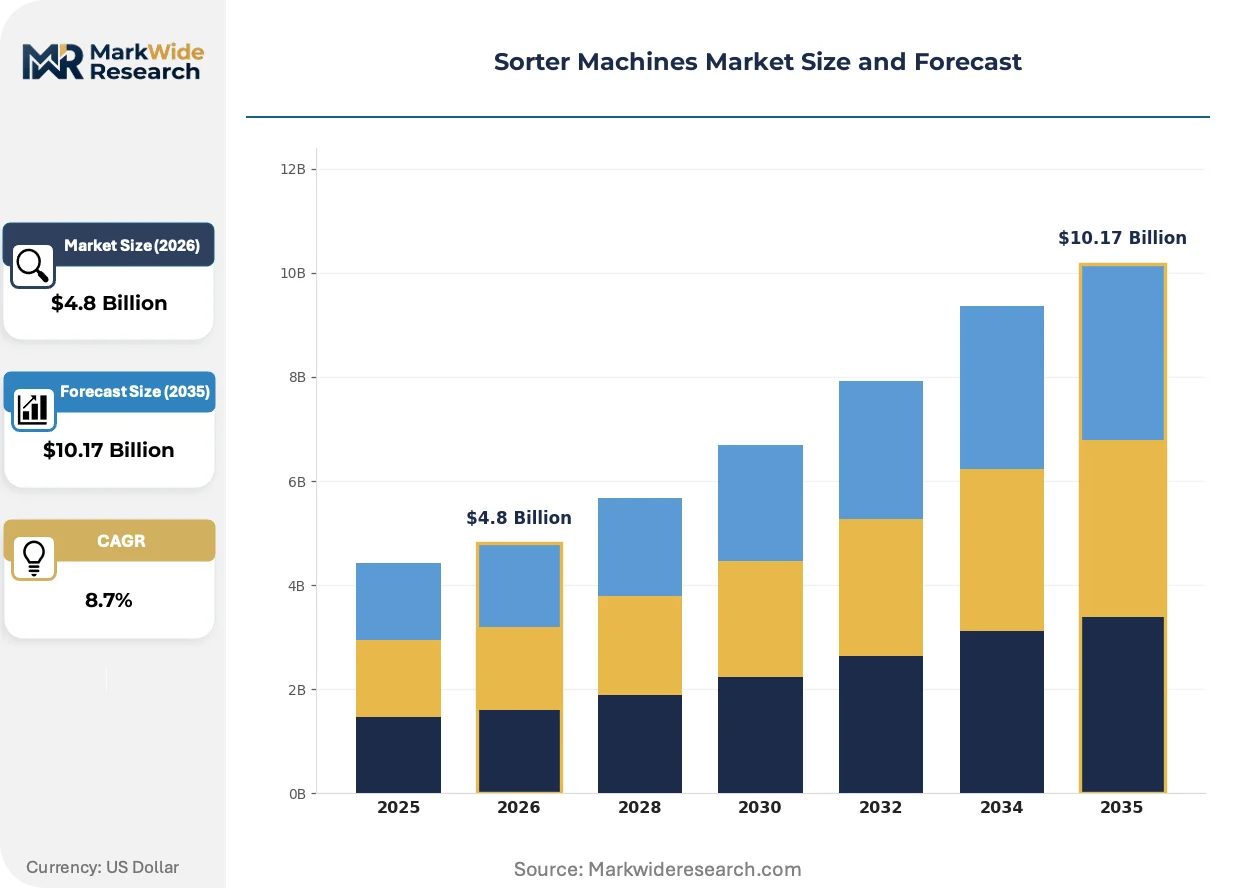
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Sorters, Electronic Sorters, Optical Sorters, Robotic Sorters Technology: Vision Systems, Infrared Sorting, Laser Sorting, Electromagnetic Sorting Application: Food & Beverages, Recycling, Pharmaceuticals, Logistics End User: Manufacturers, Distributors, Retailers, Wholesalers |
| Companies Covered | TOMRA Systems ASA, Bühler Group, STEINERT, Key Technology, Sesotec, Satake Corporation, Barco Vision, Daewon GSE, Concept Engineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorter Machines Market Evolving Landscape
Sensor fusion architectures and edge-computing inference engines are compressing classification latency while expanding sortable material categories. Equipment manufacturers compete on algorithm training dataset depth rather than hardware specifications alone.
Hyperspectral imaging is hybridizing visible-light and near-infrared detection into single-sensor platforms for simultaneous color, shape, and chemical analysis. Pharmaceutical manufacturers adopt these systems for tablet coating uniformity verification. The technology is hybridizing quality control and raw-material sorting into unified processing lines, eliminating intermediate handling stages.
EU REACH chemical compliance standards now govern sensor housing materials and contact surfaces in food-grade applications. Equipment redesign cycles accelerate as manufacturers validate alternative polymers against migration limits. German and Swiss processing facilities lead compliance investment, creating specification advantages for EU-certified equipment exports.
Service unbundling separates hardware ownership from algorithm maintenance and retraining obligations. Food processors in the United States increasingly contract third-party vision specialists for seasonal crop model updates rather than building in-house AI capabilities. This pattern concentrates most visibly in California and Pacific Northwest tree-nut handling facilities with high product-mix volatility.
Sorter Machines Market Segmentation
Sorter machines segment across four dimensions that determine technology selection and procurement economics. Product type defines capital intensity and throughput capability. Technology choice governs defect detection precision and applicable material categories. Application context dictates regulatory compliance requirements and integration complexity. End-user category shapes service model preferences and financing structures.
Product Type:
Cost tier separates the four product categories, with mechanical systems anchoring the entry level and robotic platforms commanding premium positioning.
- Optical Sorters:These systems deploy CMOS image sensors and LED illumination arrays to classify objects by color, shape, and surface texture at speeds exceeding five tons per hour. Demand concentrates in German grain processing facilities and California tree-nut handlers upgrading to meet FDA food safety modernization requirements for contamination detection.
- Robotic Sorters:Articulated-arm platforms with machine-vision guidance execute pick-and-place operations on irregular objects that defy conventional conveyor-based sorting. Logistics operations in the United States and pharmaceutical packaging lines in Switzerland are deploying these systems for e-commerce returns processing and tablet handling tasks.
- Mechanical Sorters:Density-separation and size-classification equipment using screens, air knives, or vibrating decks serves budget-constrained recycling facilities with legacy infrastructure.
- Electronic Sorters:Sensor-based systems without full optical capability occupy mid-market positions in basic foreign-object detection applications.
Optical sorters command the established base. The steepest expansion runs through robotic sorters.
Technology:
Application requirements determine which detection modality delivers acceptable classification accuracy against target material properties.
- Vision Systems:Visible-light cameras with convolutional neural network inference engines process color and geometric features for defect classification in food-grade applications. Grain processors in the United States and pulse handlers in India deploy these systems to meet evolving contamination thresholds under FSSAI and FDA enforcement expansion.
- Infrared Sorting:Near-infrared spectroscopy detects chemical composition and moisture content invisible to standard cameras. Pharmaceutical manufacturers in Germany and specialty food processors in Switzerland pay premium pricing for these systems to verify tablet coating uniformity and detect internal defects in high-value products.
- Laser Sorting:Structured-light and time-of-flight sensors measure three-dimensional shape profiles for foreign-object detection in high-speed recycling streams.
- Electromagnetic Sorting:Eddy-current and induction sensors recover ferrous and non-ferrous metals from shredded waste streams in European recycling infrastructure funded by EU Green Deal circular-economy targets.
Vision systems hold the dominant installed footprint. Infrared sorting is climbing the fastest as chemical detection capabilities penetrate quality-critical segments.
Application:
Volume scale and regulatory stringency vary sharply across the four application domains, shaping equipment specification and vendor selection criteria.
- Food & Beverages:Optical sorting lines protect downstream product quality in grain milling, dairy processing, and beverage bottling operations. Processors in Germany, China, and the United States are expanding automated capacity to satisfy stricter contamination mandates under evolving food safety regimes.
- Recycling:Automated sortation infrastructure separates mixed waste streams into commodity-grade fractions for reprocessing. EU Green Deal extended-producer-responsibility frameworks and EPA waste-stream classification rules are accelerating capital deployment across North American and European material recovery facilities.
- Pharmaceuticals:Hyperspectral and laser-based systems verify dosage form integrity and packaging accuracy in tablet and injectable production.
- Logistics:Robotic platforms with machine-vision guidance handle irregular parcels and returns in e-commerce fulfillment centers.
Food and beverage applications anchor current revenue concentration. Recycling infrastructure is gaining share fastest as circular-economy policy enforcement tightens.
End User:
Customer type determines capital access, technical staffing depth, and preferred commercial arrangements for equipment acquisition.
- Manufacturers:Food processors, pharmaceutical producers, and recycling plant operators with in-house engineering capabilities purchase equipment outright and maintain internal maintenance teams. These buyers in Germany and the United States drive specification standards that propagate through supplier product roadmaps.
- Distributors:Equipment resellers and system integrators aggregate demand from fragmented processor bases and provide localized service coverage. Their procurement concentrates on modular optical platforms with standardized mechanical interfaces.
- Retailers:Grocery chains and general merchandise operators deploy compact sorting systems for reverse logistics and food waste diversion in distribution centers.
- Wholesalers:Agricultural commodity handlers and scrap metal traders operate seasonal or variable-volume operations favoring pay-per-ton service contracts over capital purchase.
Manufacturers command the dominant procurement volume. Distributors are expanding fastest as equipment leasing and service unbundling reconfigure competitive entry barriers for mid-sized processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal extended-producer-responsibility frameworks and FDA food safety modernization requirements are accelerating capital deployment into automated sorting infrastructure across major processing economies.
Germany
Bavarian grain processors and Baden-Württemberg recycling facilities drive optical sorter procurement to meet EU REACH chemical compliance standards for food-contact surfaces. The country's central bank supports equipment financing through green lending facilities. Stuttgart and Munich industrial clusters anchor European demand for hyperspectral pharmaceutical sorting systems.
China
Dual carbon goals and MIIT smart manufacturing mandates propel recycling sortation investments across Yangtze River Delta material recovery facilities. SAMR enforcement of stricter food contamination thresholds forces processor upgrades. Shanghai and Jiangsu province processing plants deploy high-throughput optical lines for grain and legume handling.
United States
California tree-nut handlers and Pacific Northwest dairy processors expand automated capacity under FDA food safety modernization enforcement. EPA waste-stream classification rules accelerate recycling infrastructure spending. Central Valley agricultural clusters and Texas petrochemical recycling corridors concentrate equipment deployment.
India
FSSAI enforcement expansion and PLI scheme incentives create first-mover opportunity for optical sorting deployment in grain and pulse processing. Maharashtra and Gujarat food processors modernize to meet export contamination standards. Mumbai-Pune and Ahmedabad industrial belts anchor domestic equipment demand growth.
Switzerland
Swissmedic pharmaceutical manufacturing standards and specialty food export requirements sustain premium pricing for near-infrared sorting systems. Basel and Zurich pharmaceutical clusters verify tablet coating uniformity through hyperspectral inspection lines. The country's precision engineering base supports sensor technology R&D for high-value applications.
Sorter Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where captive sensor manufacturing confers margin protection. The vendor base separates into three archetypes: vertically integrated optical specialists, food-grade application experts, and recycling-focused electromagnetic system providers. M&A activity targets machine-vision engineering talent and algorithm training dataset assets. Strategic partnerships between equipment manufacturers and semiconductor foundries secure CMOS sensor supply commitments.
Within the vertically integrated tier, TOMRA Systems ASA anchors Scandinavian positioning through in-house sensor production capabilities. Bühler Group exemplifies food-grade specialization with deep heritage in grain and pulse processing applications. STEINERT occupies the recycling-system archetype through electromagnetic and sensor-based metal recovery platforms. These three entities represent distinct competitive vectors rather than direct substitutes across application domains.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler Group |
| STEINERT |
| Key Technology |
| Sesotec |
| Satake Corporation |
| Barco Vision |
| Daewon GSE |
| Concept Engineers |
| Others |
Value Network & Pricing Analysis
Asian semiconductor foundries controlling high-performance CMOS image sensor fabrication capture disproportionate margin pools in optical sorting lines, forcing equipment OEMs to absorb input volatility or pass through cost adjustments to food processors and recycling operators.
Pricing Analysis
Certification level (FDA-grade, EU REACH-compliant, standard industrial) creates the primary spread across equipment tiers, with pharmaceutical-grade systems commanding substantial premiums over food-grade lines. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and algorithm retraining obligations. Cost compression in mid-market optical platforms is intensifying because contract manufacturers in China and Taiwan are expanding capacity. Small-scale grain processors in India exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers demonstrate lowest.
Supply Chain Analysis
Hon Hai Precision Industry and select Taiwanese EMS providers hold dominant contract-manufacturing capacity for sensor assembly and optical module integration. Component sourcing draws from Japan for precision optics, Germany for industrial control systems, and South Korea for advanced CMOS sensors. Single-source vulnerability concentrates in specialized infrared detector arrays. Distribution runs through authorized system integrators in processing clusters and direct OEM relationships for large-scale facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-sized processors as equipment leasing and pay-per-ton contracting fragments capital commitment requirements across the installed base.
For Market Incumbents: Harden algorithm training dataset depth as the primary defensive moat against emerging vision-system specialists. Secure captive supply commitments with Taiwanese semiconductor foundries to buffer CMOS sensor price volatility. Accelerate EU REACH-compliant material validation to preempt regulatory redesign cycles. For New Entrants and Emerging Players: Mid-market pulse processors in Maharashtra and Gujarat represent the most penetrable entry point given FSSAI enforcement expansion and limited incumbent service coverage. Logistics irregular-object handling in Southeast Asian e-commerce fulfillment centers offers secondary white-space. Lead with pay-per-ton service contracting to bypass capital intensity barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed food-grade sorting specialists lacking AI capabilities. Five-to-ten-year viability hinges on algorithm retraining infrastructure rather than hardware manufacturing scale. Monitor CMOS sensor foundry utilization rates as inflection indicator for input cost pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Hyperspectral platforms unify quality control and raw-material sorting for pharmaceutical manufacturers. |
| Algorithm Training Dataset Acquisition | Convolutional neural network depth determines competitive positioning in defect classification accuracy. |
| EU REACH Compliance Certification | German and Swiss processing facilities prioritize REACH-validated equipment for export qualification. |
| Pay-per-Ton Service Model Expansion | Leasing contracts reconfigure entry barriers for mid-sized processors in India and Southeast Asia. |
| Strategic Foundry Partnership | CMOS sensor supply commitments with Taiwanese manufacturers buffer input cost volatility. |
Research Methodology
Operator-level perspectives from plant engineers at grain processing facilities, maintenance directors at recycling material recovery facilities, and procurement leads at pharmaceutical manufacturers anchored the qualitative base. Primary interviews combined with secondary validation from FDA food safety modernization guidance documents, EU Green Deal circular-economy implementation reports, FSSAI enforcement circulars, and SEC equipment manufacturer filings. Bottom-up equipment deployment tracking and top-down processing capacity analysis provided triangulation.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeled across product type, technology modality, application domain, and end-user category. CAGRs derived from installed base expansion rates and replacement cycle analysis. Forecast inputs incorporated FSSAI enforcement timelines, EU extended-producer-responsibility rollout schedules, and semiconductor foundry capacity expansion plans.
Macroeconomic conditions sit as an overlay; deviation in food commodity price cycles, capital equipment financing costs, or trade policy affecting CMOS sensor flows would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution rates. Quarterly review of foundry utilization indicators and food safety mandate implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Global Safety Relays and Timers Market