
 India Construction Equipment Market | 2026-2036
India Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Construction Equipment Market Insights
Equipment-as-a-service and predictive maintenance contracts is hardening into a core revenue stream for Indian construction equipment vendors. JCB India Limited leverages its dealership density to sustain aftermarket revenue across tier-2 and tier-3 cities. Tata Hitachi Construction Machinery anchors its position through captive component sourcing and integrated fabrication. Komatsu India Pvt Ltd differentiates via telematics-enabled fleet management solutions.
India construction equipment encompasses earthmoving, material handling, and lifting machinery typically powered by diesel engines rated between 75-500 horsepower, designed for mobility across unpaved terrain and operation in ambient temperatures exceeding 45 degrees Celsius. Excavators dominate volume due to versatility across trenching, demolition, and mining applications. Hydraulic technology still commands the installed base, though electric drive trains are gaining share in urban infrastructure zones with emission restrictions. The rental deployment channel is expanding fastest as contractors prioritize capital flexibility amid project-cycle volatility.
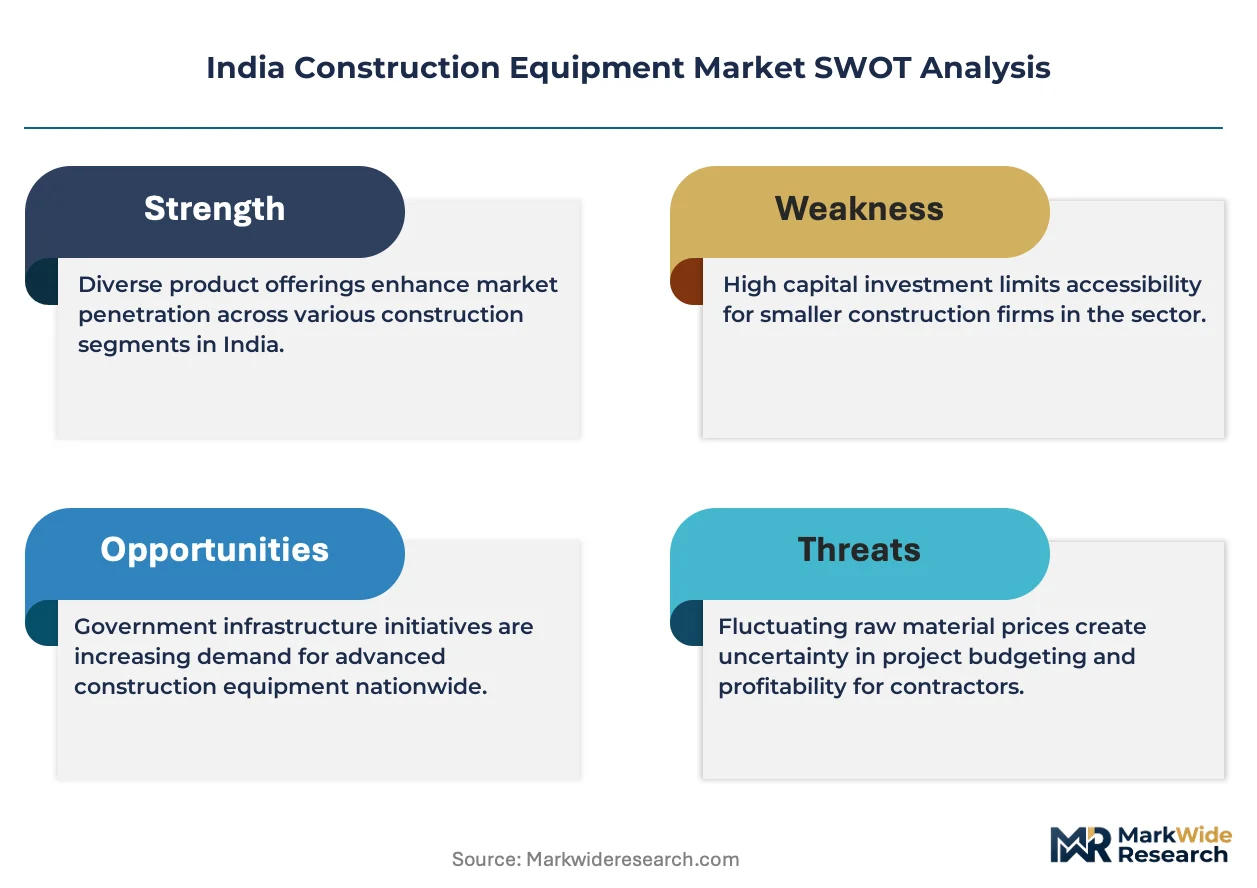
BIS safety standards, CEA electrical equipment rules, and state-level RERA compliance frameworks collectively dictate equipment certification, operator training mandates, and worksite inspection protocols across Indian states. The central PLI scheme for manufacturing is reshaping domestic sourcing requirements and localization timelines for multinational assemblers. Stakeholders must track how state-level infrastructure tendering shifts between purchase and rental models, as this determines fleet ownership concentration and service revenue pools.
Market Dynamics
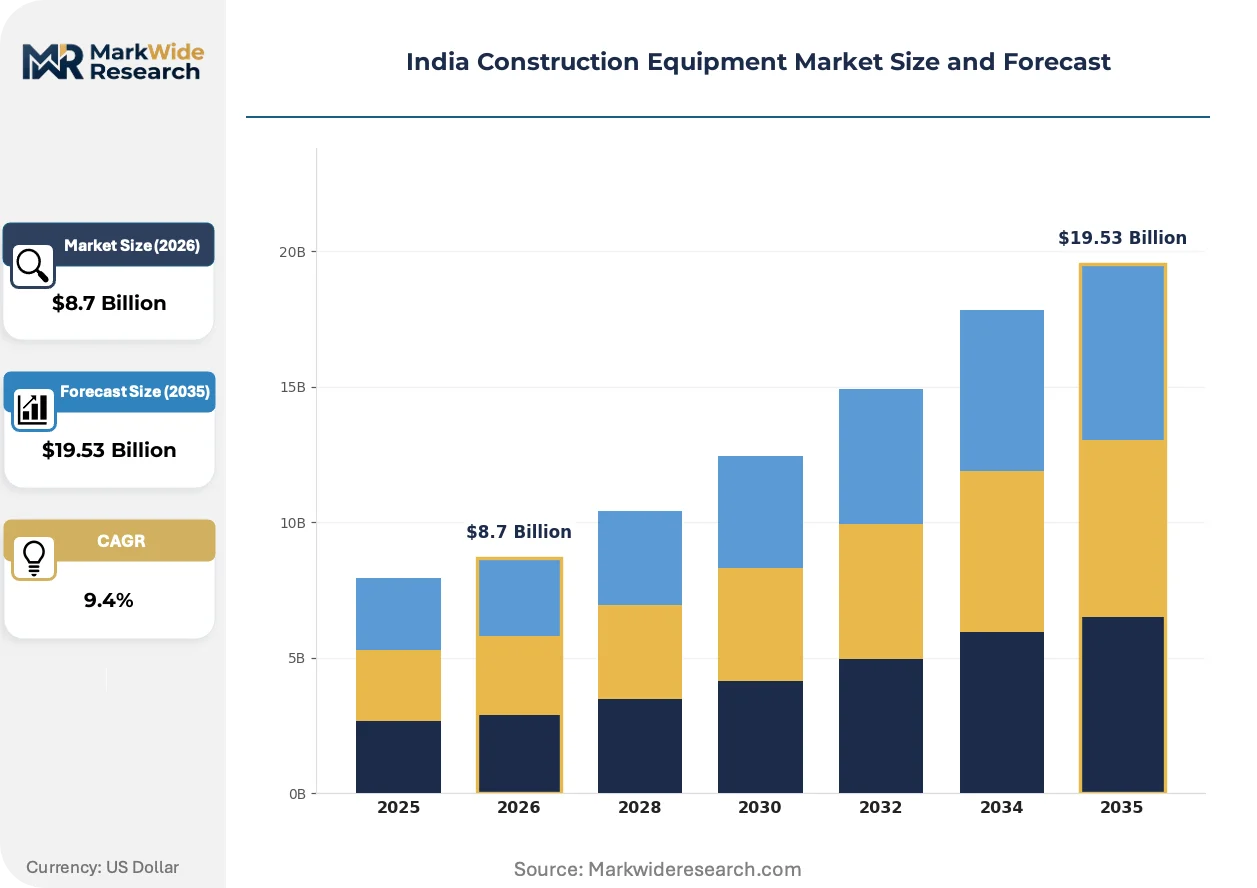
Equipment-as-a-service contracts are compressing capital deployment cycles across Indian construction fleets. BIS safety mandates and state-level infrastructure tendering are simultaneously reshaping vendor revenue models and compliance burdens.
Growth Catalysts
- PLI scheme localization:Domestic component sourcing requirements under India's production-linked incentive scheme are accelerating indigenization timelines for hydraulic systems and engine assemblies.
- NHAI highway expansion:National Highways Authority of India road and highway projects are pulling excavator and motor grader demand into continuous deployment cycles.
- Telematics penetration:Fleet management platforms are enabling predictive maintenance revenue streams and uptime guarantees for rental operators.
Market Restraints
- Steel price volatility:Structural steel and high-grade alloy input costs swing unpredictably, compressing fabrication margins for domestic equipment assemblers.
- Diesel engine dependency:Tier-4 emission upgrade costs and imported powertrain concentration create technical and forex exposure for hydraulic excavator manufacturers.
- BIS certification timelines:Safety standard testing queues and documentation requirements extend product launch windows by quarters.
Strategic Opportunities
- Electric drive convergence:Battery-electric powertrains paired with regenerative hydraulics are opening urban infrastructure zones with municipal emission ceilings.
- Tier-3 city rental penetration:Contractor capital flexibility priorities are expanding equipment-as-a-service reach into Madhya Pradesh and Rajasthan secondary markets.
- CEA electrical integration:Construction machinery electrification aligns with Central Electricity Authority grid-interconnection standards for charging infrastructure.
Industry Challenges
- Certified operator scarcity:RERA-mandated worksite training requirements outpace technical institute output for hydraulic system diagnostics and telematics operation.
- Legacy fleet integration:Telematics retrofits and hybrid control systems face compatibility friction with pre-2020 hydraulic architectures in contractor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Construction Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Dumpers End User: Residential, Commercial, Infrastructure, Mining Deployment: Rental, Purchase, Leasing, Import Technology: Electric, Hydraulic, Pneumatic, Autonomous |
| Companies Covered | Komatsu India Pvt Ltd, Larsen & Toubro Construction & Mining Machinery, JCB India Limited, BEML Ltd, Hyundai Construction Equipment India Pvt Ltd, Tata Hitachi Construction Machinery Company Pvt Ltd, Volvo Construction Equipment India Pvt Ltd, Action Construction Equipment Ltd, Caterpillar Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Construction Equipment Market Trends and Innovations
Digital fleet management and powertrain electrification are restructuring how Indian contractors access and deploy machinery. Regulatory pressure on emissions and safety is accelerating technology substitution timelines.
Telematics-enabled predictive maintenance is absorbing service revenue from traditional breakdown-repair models. Municipal corporations and large infrastructure developers are adopting these platforms fastest. The technology is absorbing aftermarket margin pools previously captured by unorganized spare parts networks.
BIS construction machinery safety standards are tightening operator protection and stability testing protocols. Equipment assemblers must redesign cab structures and hydraulic control systems to comply. Excavator and crane categories face the steepest recertification burdens under these mandates.
Rental channel preference is displacing direct equipment ownership among mid-tier contractors. Capital-light project execution is replacing balance-sheet-heavy fleet accumulation in Maharashtra and Gujarat infrastructure markets. State-level tendering authorities are explicitly accommodating rental-based deployment in highway and urban construction contracts.
India Construction Equipment Market Segmentation
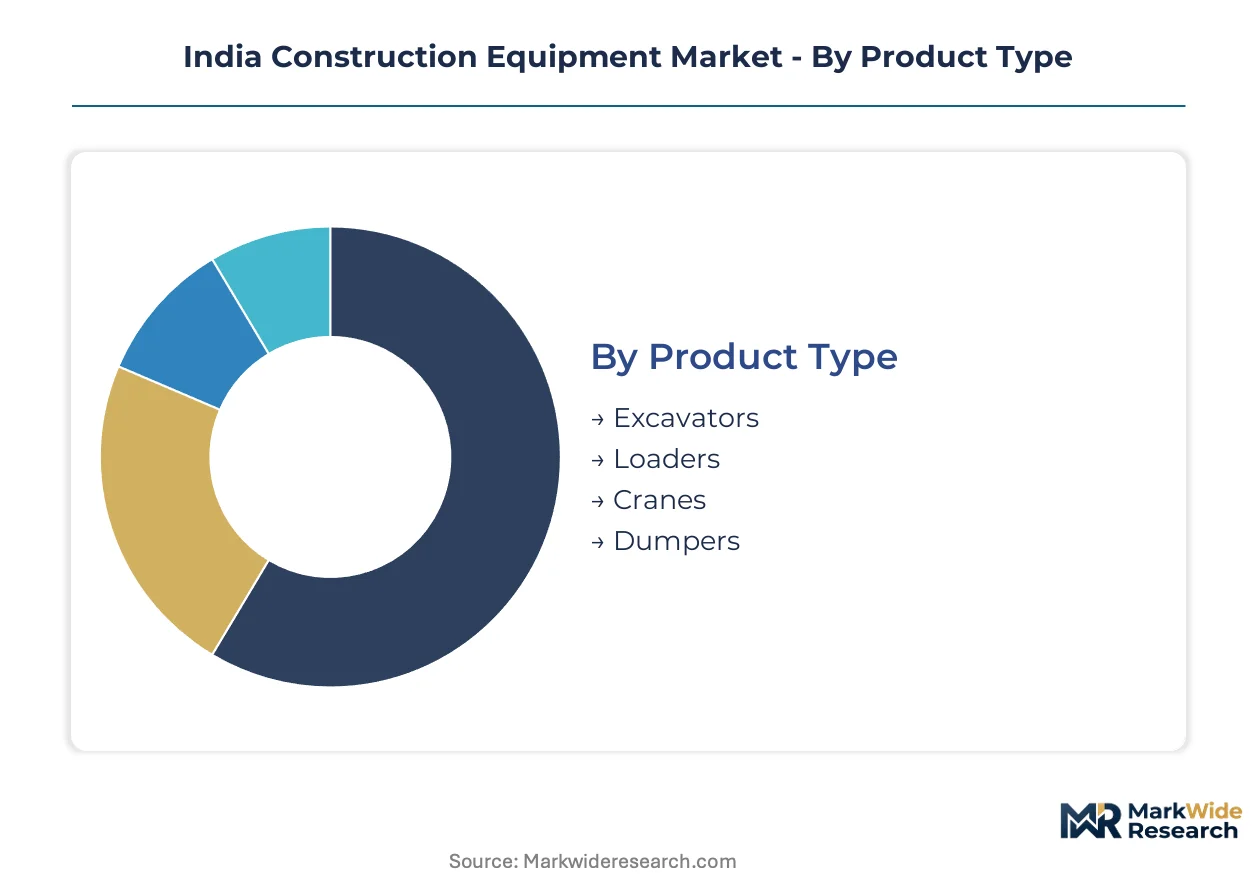
Construction equipment segmentation in India tracks how contractors balance capital intensity against project-cycle volatility. Product type and deployment mode decisions increasingly hinge on NHAI tendering structures and state-level rental penetration.
Product Type:
Volume concentration favors earthmoving categories, while premium pricing attaches to specialized lifting machinery.
- Excavators:Hydraulic-powered machines rated 75-500 horsepower dominate fleet deployment across trenching, demolition, and mining applications. Maharashtra and Gujarat infrastructure contractors deploy these continuously on NHAI highway corridors where multi-phase earthwork demands versatility.
- Loaders:Articulated wheel loaders with bucket capacities from 2-7 cubic meters handle aggregate movement and site preparation. Tamil Nadu commercial construction clusters favor mid-size units for urban material handling where maneuverability constrains larger equipment.
- Cranes:Mobile and tower configurations serve vertical lifting requirements.
- Dumpers:Rigid and articulated haul trucks move bulk materials across unpaved terrain.
Today's leader: Excavators. Tomorrow's challenger: Cranes.
End User:
Application concentration splits between cyclical residential investment and state-backed infrastructure continuity.
- Infrastructure:NHAI road projects, state highway authorities, and urban development authorities drive non-discretionary equipment demand. National Highways Authority of India awards pull excavators and motor graders into multi-year deployment cycles with rental operators capturing recurring revenue.
- Mining:Coal India Limited and private mineral extraction operations require heavy-duty excavators and dumpers rated for 45-degree ambient temperatures. Odisha and Jharkhand mineral belts concentrate fleet ownership among large contractors with captive maintenance infrastructure.
- Residential:Individual housing developers and small contractors access equipment through rental channels.
- Commercial:Office, retail, and hospitality construction projects.
Infrastructure commands current fleet deployment. Mining offers the steepest expansion trajectory as mineral output targets rise.
Deployment:
Capital flexibility priorities are restructuring how contractors access machinery across tier-2 and tier-3 markets.
- Rental:Equipment-as-a-service contracts compress capital deployment cycles and transfer maintenance burden to fleet operators. Madhya Pradesh and Rajasthan secondary markets are expanding fastest as mid-tier contractors prioritize balance-sheet flexibility.
- Purchase:Direct ownership concentrates among large contractors with multi-project pipelines and in-house service capabilities. Maharashtra and Gujarat infrastructure specialists accumulate excavator fleets to secure NHAI tender eligibility.
- Leasing:Financial lease structures with buyout options.
- Import:Direct procurement of non-indigenized machinery.
Rental is gaining share fastest. Purchase retains margin concentration among established fleet owners.
Technology:
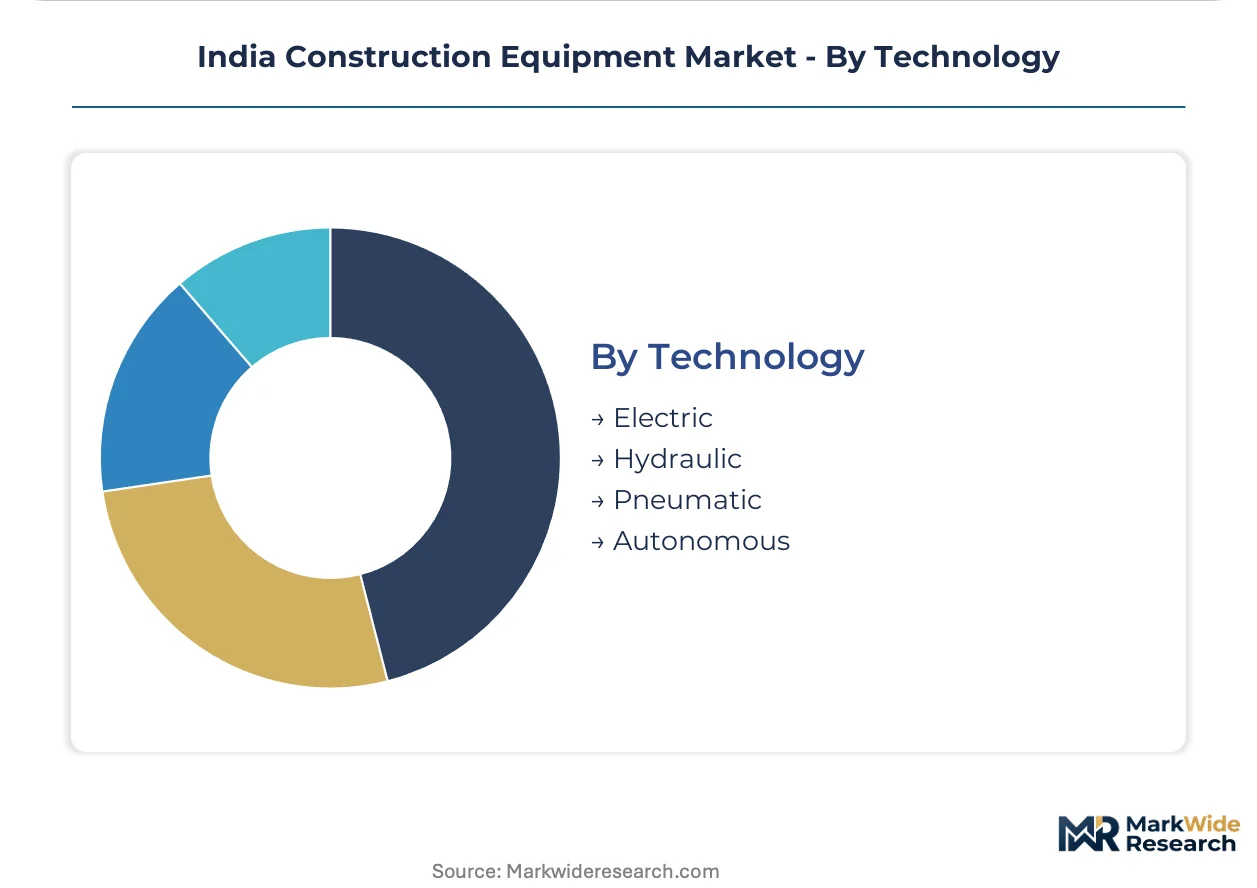
Powertrain evolution splits between proven hydraulic dominance and emerging electric penetration in emission-restricted zones.
- Hydraulic:Conventional fluid-power systems command the installed base with proven reliability in 45-degree ambient conditions. BIS certification mandates for safety and stability testing apply most stringently to hydraulic excavator and crane categories.
- Electric:Battery-electric powertrains paired with regenerative hydraulics open urban infrastructure zones with municipal emission ceilings. CEA grid-interconnection standards for charging infrastructure align with construction machinery electrification roadmaps.
- Pneumatic:Compressed-air systems for specialized material handling.
- Autonomous:GPS-guided and telematics-enabled operation for controlled environments.
Hydraulic systems anchor current deployment. Electric drive trains are climbing the fastest as urban emission restrictions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of construction machinery globally, while India exhibits steeper growth velocity in fleet expansion. Equipment deployment patterns diverge sharply between mature replacement markets and infrastructure-led expansion zones.
Maharashtra
NHAI highway corridors and Mumbai-Pune expressway expansion pull excavators and motor graders into continuous deployment cycles. State-level tendering authorities accommodate rental-based equipment contracts under Maharashtra Public Works Department guidelines. Pune and Nagpur industrial clusters concentrate JCB India Limited and Tata Hitachi service infrastructure for aftermarket coverage.
Gujarat
Dholera Special Investment Region and Delhi-Mumbai Industrial Corridor projects sustain non-discretionary demand for earthmoving fleets. Gujarat Infrastructure Development Board mandates BIS-certified machinery for all state highway contracts above specified value thresholds. Ahmedabad and Surat construction markets exhibit the densest rental operator penetration outside Maharashtra.
Tamil Nadu
Chennai Metro expansion and port modernization drive articulated loader deployment for urban material handling. State-level urban development authorities enforce CEA electrical equipment rules for construction machinery electrification pilots. Coimbatore and Tiruchirappalli manufacturing belts anchor domestic component sourcing for hydraulic system assemblers.
Karnataka
Bengaluru suburban infrastructure and Bangalore-Mysore expressway construction compress equipment utilization cycles. Karnataka Industrial Areas Development Board coordinates with BIS for expedited safety certification of locally assembled machinery. Hubli-Dharwad and Mangalore secondary markets expand rental channel penetration for mid-tier contractors.
Telangana
Hyderabad Metro Phase II and regional ring road projects generate concentrated demand for crane and dumper categories. Telangana State Industrial Infrastructure Corporation aligns equipment procurement with PLI scheme localization timelines for hydraulic component manufacturing. Warangal and Karimnagar districts emerge as rental fleet staging points for hinterland infrastructure contracts.
India Construction Equipment Market Competitive Landscape
Top-tier vendors anchor the premium equipment segment, while mid-scale fabricators and rental operators occupy distinct competitive tiers. The vendor base stratifies across integrated manufacturers with captive component sourcing, multinational assemblers leveraging global technology platforms, and domestic specialists serving price-sensitive procurement. Three archetypes dominate: full-line manufacturers with dealership density, technology licensors with telematics-enabled service models, and state-affiliated producers with defense and mining anchor contracts. Consolidation pressures concentrate around aftermarket service networks and BIS certification compliance capabilities.
Within the multinational tier, Komatsu India Pvt Ltd and Volvo Construction Equipment India Pvt Ltd exemplify technology-forward positioning through fleet management platform deployment. JCB India Limited anchors the dealership-density archetype with service reach extending into tier-3 urban centers. Tata Hitachi Construction Machinery Company Pvt Ltd represents integrated fabrication models with captive sourcing advantages under PLI scheme localization requirements.
| Leading Market Players |
|---|
| Komatsu India Pvt Ltd |
| Larsen & Toubro Construction & Mining Machinery |
| JCB India Limited |
| BEML Ltd |
| Hyundai Construction Equipment India Pvt Ltd |
| Tata Hitachi Construction Machinery Company Pvt Ltd |
| Volvo Construction Equipment India Pvt Ltd |
| Action Construction Equipment Ltd |
| Caterpillar Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators with multi-generational dealership networks anchor supply-side discipline across Maharashtra and Gujarat, translating localized component sourcing into pricing power that resists steel volatility. Their captive relationships with state Public Works Departments create contract pricing floors that insulate against rental-channel margin compression.
Pricing Analysis
Capacity additions in Tamil Nadu and Karnataka are reshaping price floors for hydraulic excavators and motor graders. Three-tier pricing structure across premium telematics-enabled, standard BIS-certified, and economy pre-owned tiers separates NHAI contractors from municipal developers from small residential builders. Price differentiation hinges on BIS certification grade and bundled predictive maintenance contracts. Cost compression in the economy tier is intensifying because unorganized spare parts networks undercut authorized service rates. Municipal corporations exhibit lowest price sensitivity due to emission-mandate compliance budgets; tier-3 rental operators face highest sensitivity amid project-cycle volatility.
Supply Chain Analysis
PLI scheme domestic-content mandates are reshaping sourcing patterns for hydraulic systems and engine assemblies. Manufacturing concentrates in India, Japan, and South Korea for precision hydraulic components and powertrain subsystems. Raw material dependencies span high-grade structural steel from domestic mills, imported alloy forgings for undercarriage components, and specialized hydraulic seals. Single-source vulnerability persists for Tier-4 emission powertrains concentrated among Japanese suppliers. Distribution runs through authorized dealership networks for original equipment, with unorganized channels capturing aftermarket spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India construction equipment market represents a late-cycle quality story. Infrastructure tendering authorities are mandating BIS-certified machinery with telematics integration, shifting contractor procurement toward premium specification tiers.
For Market Incumbents: To counter rental-operator margin compression and unorganized spare parts competition, deepen backward integration into hydraulic component manufacturing under PLI scheme incentives. Anchor dealership density in Madhya Pradesh and Rajasthan secondary markets to capture equipment-as-a-service recurring revenue pools. For New Entrants and Emerging Players: Digital fleet management platforms offer the most penetrable entry vector. Target municipal corporation electrification pilots in Tamil Nadu and Karnataka where CEA grid-interconnection standards create compliant demand. White-space exists in tier-3 city rental penetration and telematics retrofit services for legacy hydraulic fleets. For Investors and Strategic Acquirers: Construction-focused private equity funds are the most active acquirer in this space, rolling up regional rental operators and authorized service centers. Long-term viability centers on aftermarket service network density and BIS certification compliance capabilities. The signal to watch is state-level tendering authority shifts between purchase and rental deployment models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Systems | PLI scheme localization requirements reward captive component sourcing with tender eligibility advantages. |
| Telematics Platform Deployment | Predictive maintenance contracts absorb aftermarket margin from unorganized spare parts networks. |
| Tier-3 City Rental Expansion | Madhya Pradesh and Rajasthan secondary markets prioritize capital flexibility over fleet ownership. |
| Electric Drive Train Development | CEA grid-interconnection standards align with municipal emission ceiling compliance requirements. |
| BIS Certification Investment | Safety standard recertification creates compliance barriers against unorganized equipment imports. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Tamil Nadu, Karnataka, and Telangana, with primary inputs from each state-level infrastructure authority. The approach combines primary interviews with NHAI project directors, state Public Works Department procurement officers, OEM aftermarket service heads, and rental fleet operators with secondary validation from BIS certification databases, CEA electrical equipment rule filings, and state tendering authority contract awards. Bottom-up equipment deployment estimates triangulate against top-down infrastructure spending allocations.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation dimensions modeled include product type, deployment mode, end-use sector, and powertrain technology. CAGRs derive from equipment replacement cycles, infrastructure tendering pipeline analysis, and rental penetration trajectory assumptions. Industry-specific inputs incorporate NHAI highway award schedules and PLI scheme localization compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for battery-electric powertrains would alter the outlook if charging infrastructure deployment lags CEA grid-interconnection standards. Forecasts reflect assumptions regarding steel price stability, diesel emission upgrade cost trajectories, and certified operator training institute output. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Drilling Market
Construction Equipment
Piles Turner Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Baler Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market