
 Cerumen Removal Market | 2026-2036
Cerumen Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Cerumen Removal Market Intelligence
Germany is narrowing its position as a European manufacturing hub for precision-manual cerumen instruments, with domestic toolmakers scaling output to serve clinic networks across the continent. Medline leverages extensive hospital distribution contracts to sustain volume leadership in North America. Henry Schein anchors its competitive position through dedicated ENT specialty catalogs that target otolaryngology practices. Cardinal Health competes on procurement scale, bundling cerumen removal SKUs into broader physician-office supply contracts.
Cerumen removal encompasses the mechanical, chemical, and hydrodynamic extraction of earwax from the external auditory canal, employing devices and formulations typically operating at body-temperature irrigation pressures below 12 psi to prevent tympanic membrane trauma. The primary purpose is to restore auditory acuity, prevent conductive hearing loss, and reduce infection risk in both clinical and domestic settings. Manual instruments retain the highest margin pools due to stainless-steel durability and sterilization reuse protocols, while irrigation devices represent the fastest-expanding category as rechargeable electric models displace bulb syringes in home treatment. Ear wax removal kits occupy a mature, price-sensitive tier where retail pharmacy placement determines volume turnover.
FDA regulation of otologic drops and irrigation devices as Class I or II medical devices shapes product labeling, contraindication warnings, and pediatric use restrictions that manufacturers must navigate for market access. CE marking under the EU MDR imposes biocompatibility testing and clinical evaluation requirements on manual instruments sold into European clinic networks. Stakeholders must monitor evolving home-use device classifications, as regulators weigh self-administration risks against the cost burden of professional extraction services.
Market Dynamics
Rechargeable electric irrigation devices are compressing the addressable market for professional extraction services by shifting procedure volume into domestic settings where bulb syringes once dominated. This technology migration is restructuring margin pools across the value chain.
Growth Catalysts
- Aging demographics:Expanded Medicare coverage for hearing-related services in the United States drives diagnostic volumes that include cerumen clearance as a prerequisite procedure.
- EU MDR harmonization:Streamlined CE marking pathways for Class I manual instruments reduce time-to-market for stainless-steel curette manufacturers serving European clinic networks.
- Self-administration preference:Elderly patients with mobility constraints increasingly favor home-based irrigation protocols over outpatient otolaryngology appointments.
Market Restraints
- Stainless-steel input volatility:Surgical-grade 316L steel price fluctuations compress margin stability for reusable instrument manufacturers dependent on metal sourcing.
- FDA pediatric restrictions:Labeling limitations on over-the-counter drops for patients under twelve years constrain addressable population for home-use chemical formulations.
- Professional substitution ceiling:Microsuction systems in ENT practices retain preference for impacted cerumen cases, capping irrigation device penetration in complex presentations.
Strategic Opportunities
- Telehealth integration:Remote visual otoscopy combined with guided self-irrigation protocols opens reimbursement pathways for virtual cerumen management services.
- Retail pharmacy expansion:Dedicated ear-care aisle placement in drugstore chains captures impulse purchase behavior distinct from clinical prescription flows.
- Rechargeable battery convergence:Lithium-ion cell cost curves enable premium electric irrigator price points accessible to mass-market demographics previously served by disposable bulbs.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing requirements for polymer irrigation tips extend product development cycles by eight to fourteen months.
- Cross-contamination protocols:Reusable instrument sterilization validation creates compliance burden for outpatient clinics without autoclave infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerumen Removal Market |
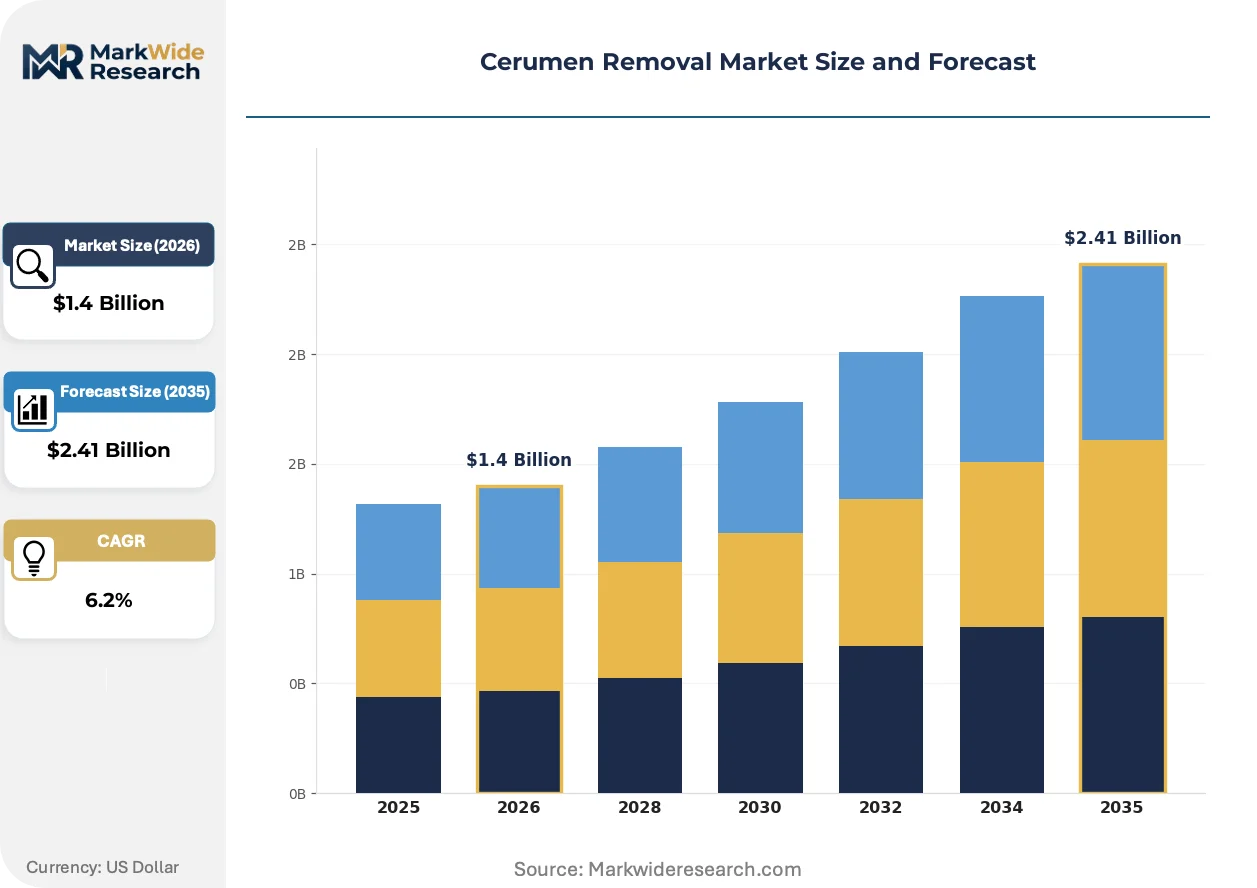
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ear Wax Removal Kits, Hydrogen Peroxide Drops, Irrigation Devices, Manual Instruments End User: Patients, Healthcare Professionals, Clinics, Home Care Sales Channel: Retail Pharmacies, Online Stores, Hospitals, Medical Distributors Application: Routine Care, Medical Procedure, Emergency Care, Home Treatment |
| Companies Covered | Medline, Henry Schein, McKesson Medical-Surgical Inc, Cardinal Health, Johnson & Johnson, GlaxoSmithKline Plc, Eosera Inc, Debrox, NeilMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerumen Removal Market Strategic Shifts & Innovations
Connected health architectures are embedding diagnostic capabilities directly into consumer irrigation hardware, transforming cerumen management from a reactive clearance procedure into a monitored auditory wellness routine with embedded compliance tracking.
Camera-equipped smartphone otoscopes paired with irrigation devices are digitizing the patient journey by enabling visual confirmation of canal clearance without clinical visitation. Home users in the United States and Germany are adopting these integrated systems at rates exceeding standalone bulb syringe replacement cycles. The technology is digitizing documentation standards for self-administered procedures, creating data streams that insurers increasingly reference for remote care reimbursement validation.
CE marking under the EU MDR is tightening clinical evaluation requirements for manual instruments, mandating biocompatibility documentation that previously applied only to implantable devices. German and French manufacturers face extended notified body review timelines that compress first-mover advantages for product line extensions. Stainless-steel curette suppliers are responding by consolidating testing protocols across SKU families to amortize regulatory overhead across higher production volumes.
Retail pharmacy buyers are consolidating shelf space around private-label ear-care kits, displacing branded formulations that historically commanded premium placement. This concentration is visible in United States drugstore chains where store-brand hydrogen peroxide drops now occupy prime positioning formerly reserved for established otologic brands. The shift pressures manufacturer margin structures while rewarding suppliers with direct distribution infrastructure bypassing traditional wholesale intermediaries.
Cerumen Removal Market Segmentation
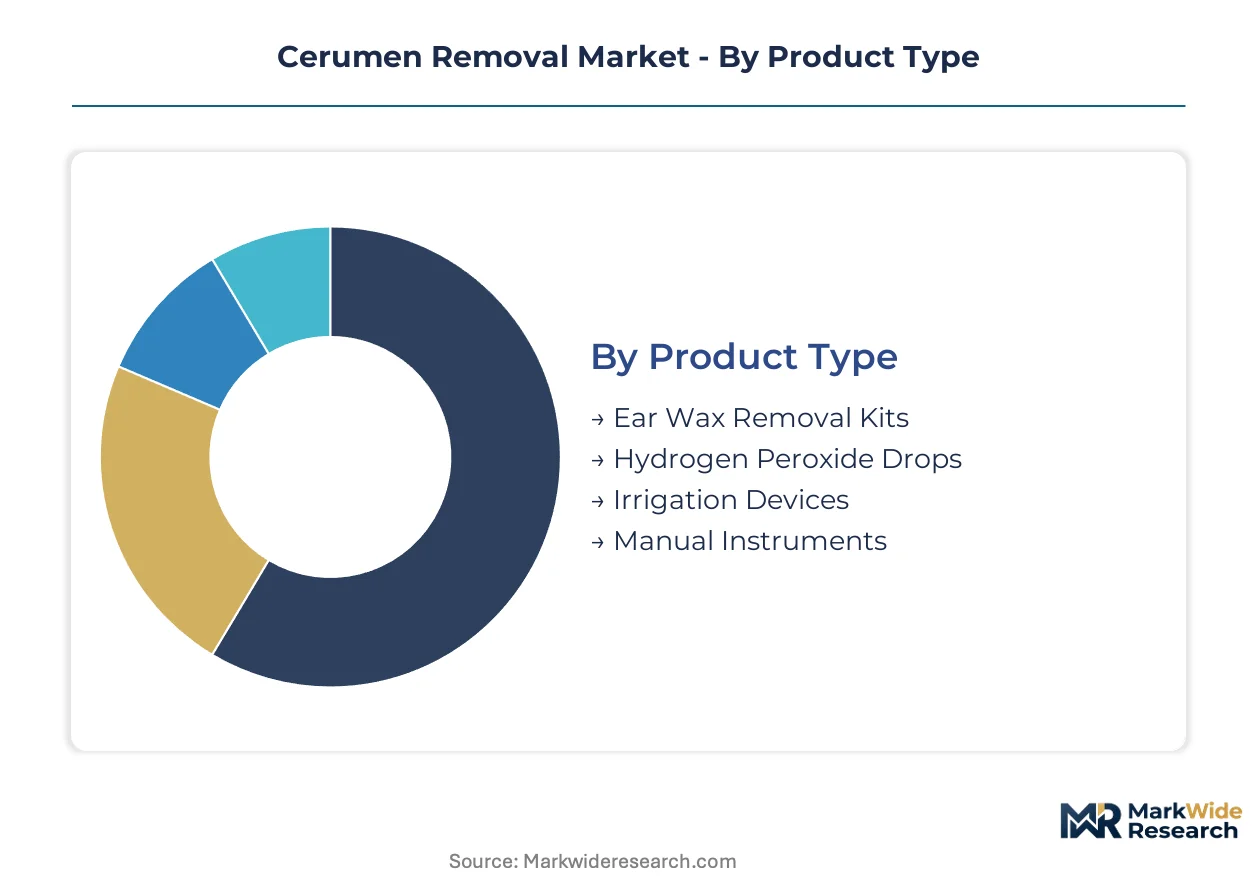
Cerumen removal markets fragment across product maturity, end-user sophistication, and channel accessibility. Each dimension reveals distinct margin structures and regulatory exposure that shape competitive positioning.
Product Type:
Mature commodity formats coexist with emerging rechargeable technologies, creating a tiered innovation landscape.
- Irrigation Devices:Rechargeable electric models operating below 12 psi dominate home treatment evolution. United States retail pharmacy networks drive volume for lithium-ion powered units as Medicare-eligible patients seek alternatives to outpatient ENT visits.
- Manual Instruments:Surgical-grade 316L stainless-steel curettes and loops withstand autoclave sterilization cycles for repeated clinical use. German manufacturers concentrate production for European clinic networks where EU MDR biocompatibility documentation now extends to Class I instruments.
- Ear Wax Removal Kits:Bundled bulb syringe and drop combinations occupy price-sensitive retail tiers.
- Hydrogen Peroxide Drops:OTC chemical formulations face FDA pediatric labeling restrictions under twelve years.
Manual instruments handle the majority of throughput; irrigation devices are expanding most quickly on share.
End User:
Professional settings demand instrument durability while home environments prioritize safety-engineered simplicity.
- Home Care:Self-administered irrigation protocols gain preference among mobility-constrained elderly patients. United States telehealth reimbursement pathways increasingly validate remote visual otoscopy combined with guided self-treatment.
- Healthcare Professionals:ENT practices and primary care physicians require precision-manual tools and microsuction systems for impacted cerumen cases. Clinic procurement bundles cerumen removal SKUs into broader physician-office supply contracts.
- Patients:Direct-purchase consumers navigate OTC labeling for unsupervised chemical application.
- Clinics:Outpatient facilities without autoclave infrastructure face sterilization validation burdens for reusable instruments.
Healthcare professionals capture the highest procedure value; home care is gaining share fastest among addressable populations.
Sales Channel:
Channel concentration determines price realization and brand visibility across mass-market and institutional segments.
- Retail Pharmacies:Dedicated ear-care aisle placement captures impulse purchase behavior distinct from clinical prescription flows. United States drugstore chains consolidate shelf space around private-label kits, displacing branded formulations from prime positioning.
- Online Stores:Camera-equipped smartphone otoscopes paired with irrigation devices digitize the patient journey through direct-to-consumer distribution. German and United States home users adopt these integrated systems at rates exceeding standalone replacement cycles.
- Hospitals:Acute care settings prioritize single-use or validated sterile instruments for infection control.
- Medical Distributors:Hospital distribution contracts sustain volume leadership through consolidated procurement scale.
Retail pharmacies anchor mass-market volume; online stores show the steepest expansion trajectory in premium connected-device segments.
Application:
Clinical complexity stratifies from preventive maintenance to acute intervention requirements.
- Home Treatment:Routine self-administered irrigation protocols restore auditory acuity without clinical visitation. Rechargeable electric models displace bulb syringes as lithium-ion cost curves enable premium price points accessible to mass-market demographics.
- Medical Procedure:Professional extraction services retain preference for impacted cerumen cases where microsuction systems outperform hydrodynamic methods. Diagnostic volumes include cerumen clearance as prerequisite for hearing-related Medicare coverage in the United States.
- Routine Care:Preventive maintenance protocols reduce infection risk in both clinical and domestic settings.
- Emergency Care:Acute presentations requiring immediate tympanic membrane assessment drive specialized instrument demand.
Medical procedure applications command premium reimbursement; home treatment demonstrates the fastest volume migration from professional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of over-the-counter otologic products anchors the United States as the dominant geography, while CE marking under the EU MDR shapes European manufacturing standards. Distribution networks concentrate where retail pharmacy penetration and telehealth reimbursement pathways intersect.
United States
Medicare coverage expansion for hearing-related services drives diagnostic volumes requiring cerumen clearance as prerequisite procedures. FDA Class I and II device classifications tighten labeling requirements and pediatric use restrictions for home-use irrigation products. Retail pharmacy chains in the Northeast and California consolidate shelf space around private-label ear-care kits, displacing branded formulations from prime positioning.
Germany
Precision-manual instrument demand from European clinic networks scales domestic toolmaker output for stainless-steel curettes and loops. EU MDR biocompatibility documentation requirements now extend to Class I instruments, extending notified body review timelines. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia consolidate testing protocols across SKU families to amortize regulatory overhead.
United Kingdom
NHS procurement bundles for ENT practices sustain volume demand for reusable sterilizable instruments. MHRA alignment with EU MDR transitional provisions creates temporary regulatory flexibility for existing product registrations. London and Southeast England clinic networks pilot telehealth-integrated visual otoscopy protocols for remote cerumen management reimbursement.
Japan
Aging demographics and hearing-aid penetration rates elevate routine ear-care maintenance protocols among elderly populations. PMDA medical device classifications for home-use irrigation products impose pressure-threshold labeling standards below 12 psi. Manufacturing concentration in the Kanto region around Tokyo supplies precision polymer components for rechargeable electric irrigator assembly.
Australia
Remote rural healthcare access constraints accelerate adoption of self-administered irrigation devices among mobility-limited elderly patients. TGA medical device regulations harmonize with international standards for OTC otologic drops and irrigation hardware. Distribution networks in New South Wales and Victoria prioritize pharmacy-led ear-care aisle placement for impulse purchase capture.
Cerumen Removal Market Key Industry Players
Hospital distributors and retail pharmacy suppliers split the market into distinct procurement channels with divergent margin structures. The vendor base concentrates around consolidated medical supply contracts and dedicated specialty catalogs rather than fragmented point solutions. Three archetypes dominate: diversified health conglomerates with hospital distribution scale, ENT-focused specialty suppliers with dedicated instrument catalogs, and direct-to-consumer device manufacturers with rechargeable technology platforms. Competitive moves center on procurement bundling strategies and telehealth integration partnerships.
Among diversified health conglomerates, Medline and Cardinal Health exemplify the hospital-distribution archetype through consolidated physician-office supply contracts. Henry Schein occupies a distinct position within the ENT-specialty tier, anchoring competitive positioning through dedicated otolaryngology practice catalogs. These three entities represent the primary structural poles around which procurement relationships and channel access organize.
| Leading Market Players |
|---|
| Medline |
| Henry Schein |
| McKesson Medical-Surgical Inc |
| Cardinal Health |
| Johnson & Johnson |
| GlaxoSmithKline Plc |
| Eosera Inc |
| Debrox |
| NeilMed |
| Others |
Cost & Logistics Intelligence
Trans-Pacific container freight corridors linking Chinese lithium-ion cell manufacturers to United States assembly facilities transmit cost volatility that compresses margins for rechargeable electric irrigator producers while enabling tiered price positioning between premium connected devices and economy bulb syringes.
Pricing Analysis
United States retail pharmacy shelf prices for ear-care kits run 15-40 percent above equivalent German drugstore positioning, reflecting divergent reimbursement pathways and private-label penetration rates. Three-tier pricing structure across premium, standard, and economy levels separates camera-equipped smartphone otoscope bundles from rechargeable electric irrigators and disposable bulb syringe combinations. Price differentiation centers on FDA Class II certification status and telehealth integration capabilities. Cost compression in the economy tier is intensifying because retail pharmacy buyers consolidate shelf space around store-brand hydrogen peroxide drops. Direct-purchase consumers exhibit highest price sensitivity, while hospital procurement committees prioritize sterilization validation over unit cost.
Supply Chain Analysis
Export control regimes restricting precision polymer molding equipment shipments to certain jurisdictions constrain manufacturing scale-up for irrigation tip producers seeking ISO 10993 biocompatibility certification. Component sourcing concentrates in China for lithium-ion cells, Germany for surgical-grade 316L stainless-steel curettes, and Japan for pressure-regulated pump mechanisms. Raw material dependencies span surgical-grade steel, medical-grade polymers, and rechargeable battery cells. Single-source vulnerability persists for FDA-registered contract sterilization services serving outpatient clinic networks. Distribution runs through hospital distribution contracts for institutional volumes and retail pharmacy direct purchasing for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated visual otoscopy services represent a service-attach opportunity expanding faster than hardware unit sales, as remote reimbursement pathways validate recurring virtual consultation revenues alongside one-time device purchases.
For Market Incumbents: Entrench procurement relationships by bundling cerumen removal SKUs into broader physician-office supply contracts that lock in multi-year hospital distribution agreements. Invest in CE marking documentation consolidation across manual instrument SKU families to amortize EU MDR biocompatibility testing overhead. Counter rechargeable electric irrigator substitution by emphasizing microsuction system superiority for impacted cerumen cases. For New Entrants and Emerging Players: Build out direct-to-consumer channels for camera-equipped smartphone otoscope bundles targeting Medicare-eligible patients with mobility constraints in United States and German home care segments. Target private-label manufacturing contracts for retail pharmacy chains consolidating ear-care aisle placement around store-brand kits. Pursue lithium-ion cost curve advantages to undercut premium electric irrigator price points. For Investors and Strategic Acquirers: ENT-specialty catalog suppliers with dedicated otolaryngology practice relationships offer durable cash flow visibility through recurring instrument replacement cycles and sterilization consumable attach rates. Long-term viability hinges on telehealth integration capabilities and regulatory navigation expertise across FDA and EU MDR frameworks. Watch for reimbursement code expansions covering remote visual otoscopy as inflection indicator for virtual cerumen management service scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility documentation for Class I manual instruments unlocks European clinic network access. |
| Hospital System Partnership | Consolidated procurement contracts with GPOs anchor volume leadership against retail pharmacy competitors. |
| Software Companion Development | Telehealth-integrated visual otoscopy apps validate remote reimbursement pathways for virtual consultation services. |
| Reimbursement Strategy | Medicare coverage expansion for hearing-related services drives diagnostic prerequisite procedures including cerumen clearance. |
| Distribution Channel Expansion | Direct-to-consumer online stores bypass wholesale intermediaries for camera-equipped device bundles. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with ENT clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and retail pharmacy procurement records. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, end user, sales channel, and application dimensions.
Forecast inputs incorporated aging demographic trajectories, telehealth reimbursement policy evolution, lithium-ion battery cost curves, and EU MDR harmonization timelines across the analysis window. Segmentation modeling spanned product maturity tiers, end-user sophistication levels, channel accessibility patterns, and clinical complexity strata. CAGRs derived from regression analysis of historical procedure volumes, device replacement cycles, and pricing trend projections.
Stress conditions across steel input volatility, FDA pediatric labeling restrictions, and retail pharmacy private-label consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Medicare coverage expansion pace and EU MDR implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Nasal Splints Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Smear Mask Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Veterinary Suture Kit Market