
 Medical Gauze and Tapes Market | 2026-2036
Medical Gauze and Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Gauze and Tapes Market Intelligence
A capital-intensity divergence between automated weaving lines and manual finishing operations is bifurcating competitive economics in medical gauze and tapes. 3M Company leverages its polymer science infrastructure to dominate high-performance adhesive tape segments. Medline Industries anchors North American hospital supply contracts through extensive distribution networks. Mölnlycke Health Care AB differentiates via silicone-adhesive technology leadership in advanced wound care applications.
Medical gauze and tapes encompass woven and non-woven absorbent fabrics plus pressure-sensitive adhesive strips, typically comprising cotton, rayon, or synthetic fibers in thread counts ranging from 12 to 44 for gauze and acrylic or silicone adhesives on polyethylene or fabric backings for tapes, designed primarily for wound exudate management, surgical site protection, and device fixation. Absorbent gauze retains the largest volume share across wound care applications where cotton and rayon blends balance fluid capacity against skin adherence. Biodegradable materials represent the fastest-expanding material category as European and Asian hospitals phase out petroleum-derived synthetics under extended producer responsibility frameworks.
FDA enforces 21 CFR Part 820 quality system regulations for medical tape manufacturers while EMA's Medical Device Regulation mandates clinical evidence for adhesive products claiming extended wear duration, collectively elevating barrier-to-entry costs for new suppliers. ISO 10993 biocompatibility testing requirements further constrain material substitutions in direct-skin-contact applications. Stakeholders must monitor evolving sterilization validation protocols and polymer supply chain decarbonization commitments to preserve market access and contract eligibility.
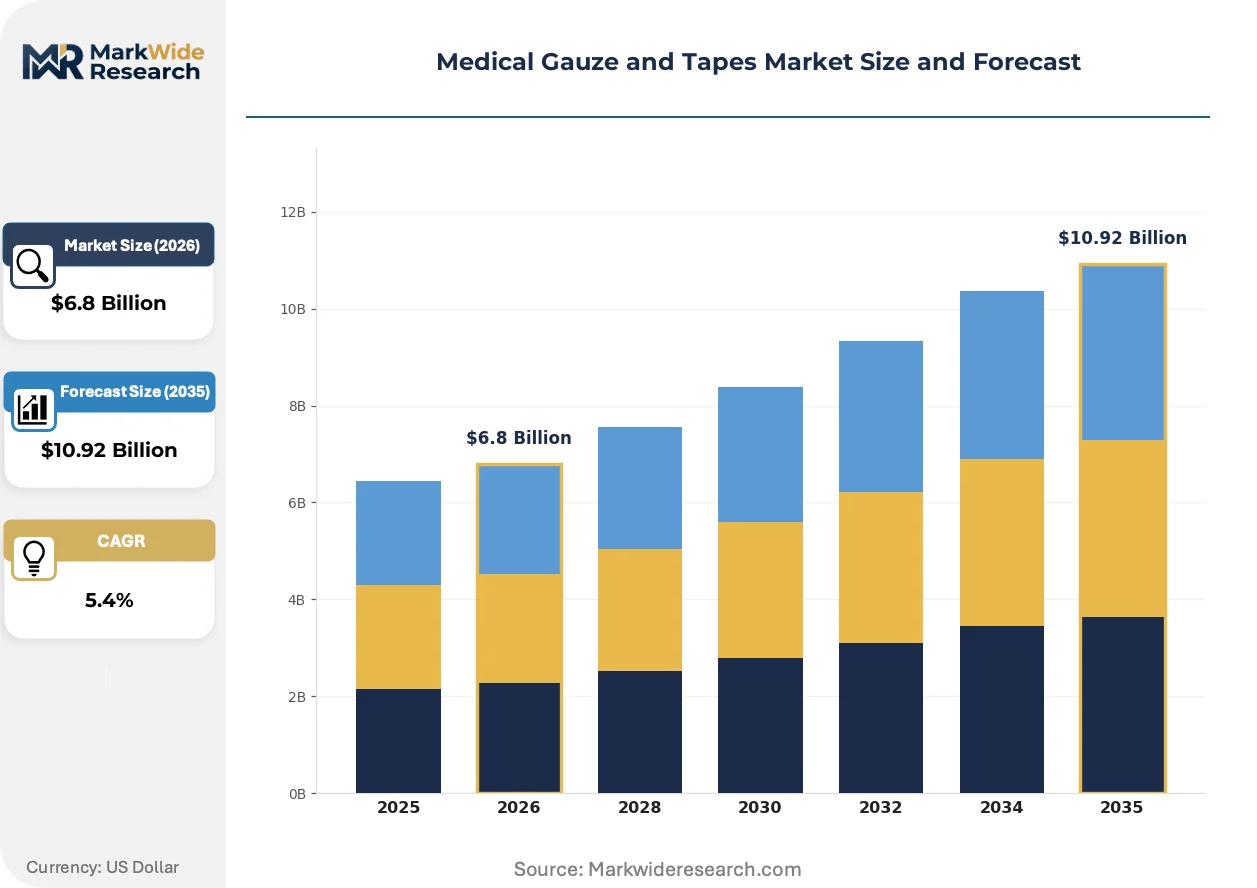
Market Dynamics
Automated weaving and coating lines are concentrating production economics among capital-rich suppliers while manual finishing operations fragment the long tail, creating a two-tier supply structure that rewards polymer science capabilities over commodity textile sourcing.
Growth Catalysts
- Outpatient Surgical Volume:Ambulatory surgery centers in the United States are expanding gauze and tape procurement as same-day procedure protocols reduce hospital admission rates.
- EMA MDR Clinical Evidence Requirements:Extended wear claims for adhesive products now demand biocompatibility documentation, accelerating replacement cycles for non-compliant legacy inventory.
- Silicone Adhesive Chemistry:Advanced wound care applications are adopting silicone-based tapes for reduced skin trauma, particularly among geriatric populations with fragile dermal tissue.
Market Restraints
- Cotton Fiber Price Volatility:Raw cotton futures and synthetic rayon feedstock costs swing with agricultural yields and petrochemical indices, compressing margin predictability for woven gauze manufacturers.
- Chinese Medical Textile Concentration:Spunlace non-woven substrate production clusters in Zhejiang and Jiangsu provinces, exposing buyers to concentrated geographic supply risk.
- Petroleum-Derived Synthetic Bans:Extended producer responsibility frameworks in Germany and France are phasing out polyethylene tape backings before cost-competitive bio-based alternatives achieve scale.
Strategic Opportunities
- India Tier-2 Hospital Expansion:Government health infrastructure programs are equipping district hospitals in Maharashtra and Tamil Nadu with standardized wound care protocols.
- Biodegradable Gauze Mandates:EU Green Deal procurement guidelines are creating preferential contracting channels for cellulose-based absorbent materials with verified compostability credentials.
- E-Commerce Direct-to-Patient Channels:Chronic wound patients in Japan are purchasing silicone tape refills through regulated pharmacy platforms, bypassing traditional hospital supply intermediaries.
Industry Challenges
- ISO 10993 Biocompatibility Testing Bottlenecks:Material substitutions for skin-contact layers face extended validation timelines at certified laboratories, delaying product launches.
- Sterilization Validation Complexity:Gamma and ethylene oxide protocol transitions for adhesive tapes require redundant facility qualifications, straining capex allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Gauze and Tapes Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Gauze, Adhesive Tapes, Non-Adhesive Tapes, Surgical Tapes Material: Cotton, Rayon, Polyester, Biodegradable Materials Application: Wound Care, Surgical Procedures, Sports Medicine, First Aid End User: Hospitals, Clinics, Home Care Settings, Rehabilitation Centers |
| Companies Covered | 3M Company, Johnson & Johnson, Cardinal Health, Medline Industries, B. Braun Melsungen AG, Smith & Nephew, Mölnlycke Health Care AB, Paul Hartmann AG, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Gauze and Tapes Market Strategic Shifts & Innovations
Material science advances and regulatory tightening are converging to redefine product specifications and procurement criteria across wound care applications.
Silicone-adhesive coated polyurethane films are displacing traditional acrylic tapes in extended-wear applications. Home healthcare nurses managing pressure ulcers are specifying seven-day wear durations. This chemistry shift is compressing commodity acrylic tape volumes while expanding premium coating capacity requirements.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of tape adhesives and backings. European manufacturers are substituting phthalate plasticizers with bio-based alternatives in polyethylene carriers. Wound care contract manufacturers in Germany report eighteen-month material qualification cycles to maintain CE marking.
Hospital procurement departments are consolidating SKU portfolios around standardized performance tiers. Group purchasing organizations are eliminating redundant gauze specifications in favor of universal cotton-rayon blends. This rationalization is most visible in United States health systems pursuing supply chain simplification under value-based care contracts.
Medical Gauze and Tapes Market Segmentation
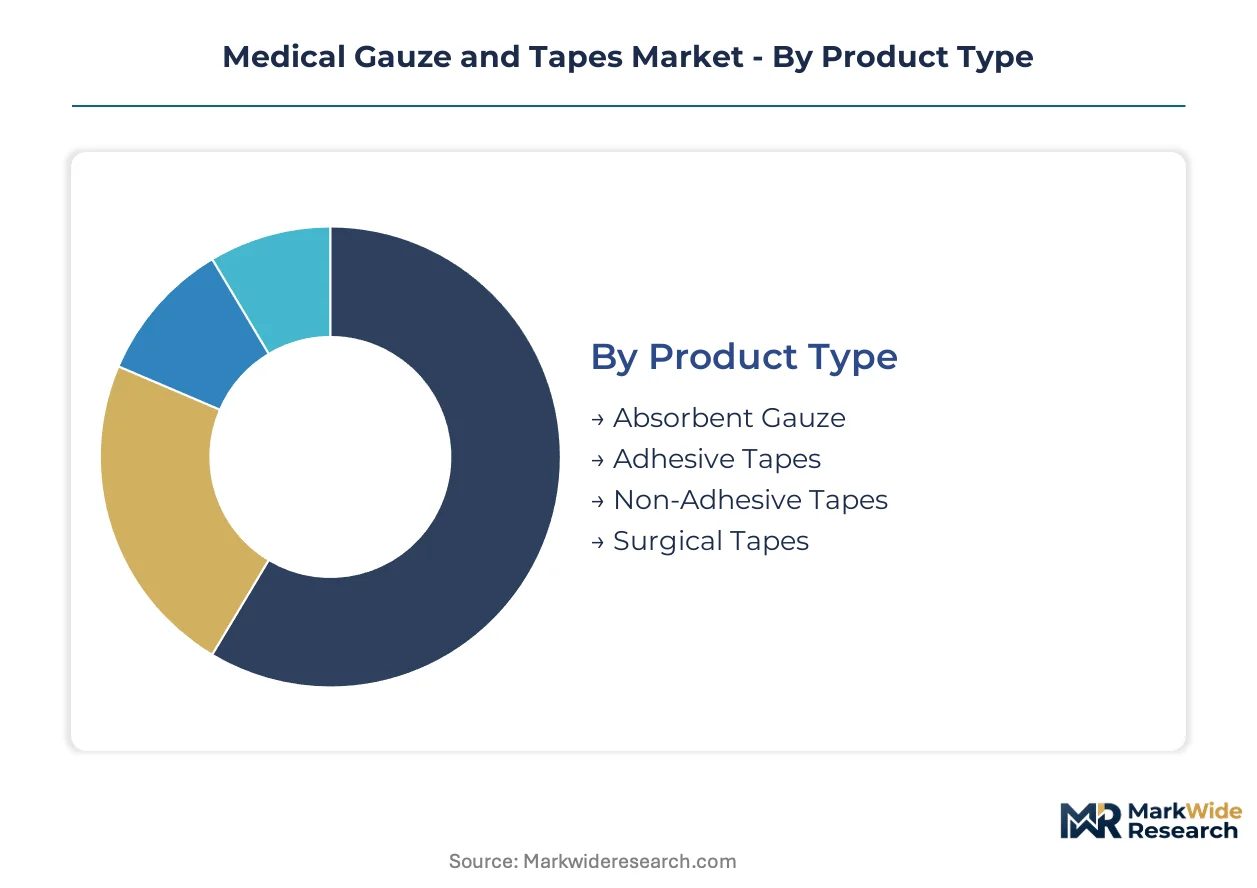
Product specifications in medical gauze and tapes diverge sharply across sterilization requirements, wear duration claims, and biocompatibility testing tiers. Procurement officers at hospital systems and ambulatory surgery centers weight these segment boundaries when consolidating supplier contracts under value-based care frameworks.
Product Type:
FDA 21 CFR Part 820 quality system regulations and EMA MDR clinical evidence mandates create divergent compliance burdens across adhesive versus non-adhesive categories, with extended-wear claims triggering biocompatibility documentation requirements that commodity gauze avoids.
- Absorbent Gauze:Woven and non-woven cotton or rayon fabrics in thread counts from 12 to 44, designed for exudate management in surgical sites and chronic wounds. Hospital surgical departments in the United States specify cotton-rayon blends for fluid capacity balance, though procurement consolidation is eliminating redundant SKU specifications under group purchasing organization rationalization programs.
- Adhesive Tapes:Pressure-sensitive strips with acrylic or silicone adhesives on polyethylene or fabric backings, securing dressings and medical devices to skin. Silicone chemistry variants are displacing acrylic formulations in geriatric wound care applications across Germany and Japan, where fragile dermal tissue demands reduced trauma upon removal.
- Non-Adhesive Tapes:Cohesive and elastic wraps that adhere to themselves without skin contact, used for compression and support. Sports medicine clinics in Australia specify these for athlete taping protocols where frequent reapplication cycles demand easy removal.
- Surgical Tapes:Specialized adhesive strips engineered for operating room sterilization compatibility and extended intraoperative fixation. EMA MDR extended wear claims now require clinical evidence documentation, accelerating replacement of legacy inventory across European hospital systems.
Established volume favors Absorbent Gauze; emerging adoption favors Adhesive Tapes.
Material:
Raw material cost tiers stratify competitive positioning, with petroleum-derived synthetics facing margin compression from agricultural commodity volatility and regulatory phase-out timelines.
- Cotton:Natural cellulose fibers processed into woven gauze with established absorbency profiles. Raw cotton futures volatility tied to agricultural yields in India and the United States compresses margin predictability for manufacturers dependent on spot market procurement.
- Rayon:Semi-synthetic regenerated cellulose offering consistent fiber diameter and controlled absorbency. Viscose production clusters in China expose buyers to concentrated geographic supply risk from Zhejiang and Jiangsu province manufacturing bases.
- Polyester:Petroleum-derived synthetic fibers providing dimensional stability and rapid wicking. Extended producer responsibility frameworks in Germany and France are phasing out polyethylene-derived tape backings before bio-based alternatives achieve cost-competitive scale.
- Biodegradable Materials:Cellulose-based and polylactic acid substrates with verified compostability credentials. EU Green Deal procurement guidelines are creating preferential contracting channels for these materials in French and Dutch hospital systems.
Cost-driven procurement anchors Cotton and Rayon; sustainability mandates accelerate Biodegradable Materials.
Application:
Clinical setting requirements dictate performance specifications, with inpatient surgical protocols demanding higher sterilization assurance than outpatient or consumer channels.
- Wound Care:Chronic and acute wound management spanning pressure ulcers, diabetic foot lesions, and post-surgical sites. Home healthcare nurses in Japan are specifying seven-day silicone tape wear durations, compressing commodity acrylic volumes while expanding premium coating demand.
- Surgical Procedures:Intraoperative site protection and instrument fixation requiring validated sterilization compatibility. Ambulatory surgery centers in the United States are expanding gauze and tape procurement as same-day procedure protocols reduce hospital admission rates.
- Sports Medicine:Athlete support and injury prevention applications prioritizing elasticity and moisture resistance. Rehabilitation centers in South Korea specify cohesive non-adhesive variants for repetitive taping cycles.
- First Aid:Consumer and occupational health applications with lower sterilization thresholds. E-commerce direct-to-patient channels in Japan are bypassing traditional hospital supply intermediaries for chronic wound patient refill purchases.
Institutional procurement concentrates in Surgical Procedures; patient-directed purchasing is expanding fastest in First Aid.
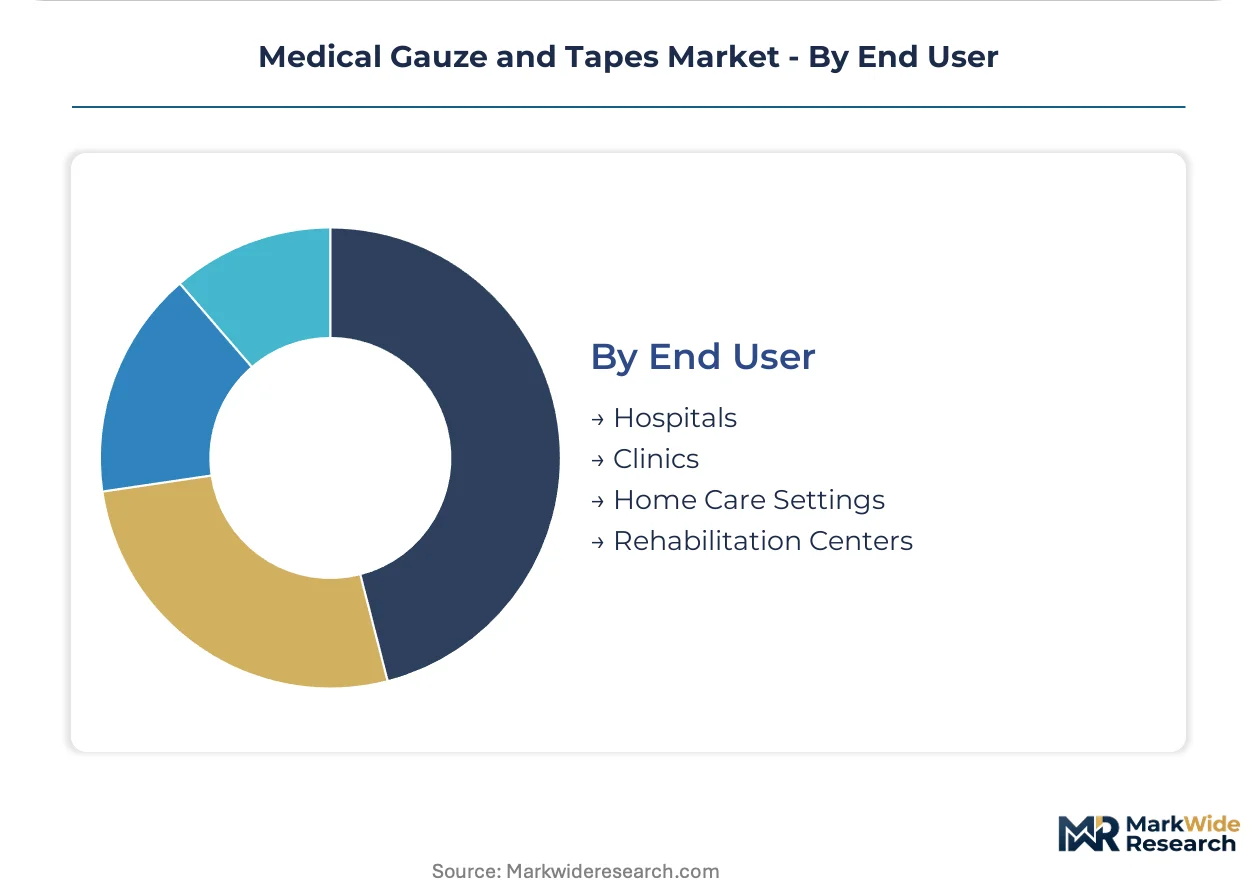
End User:
Facility type determines contract structure, with integrated health systems leveraging volume consolidation against fragmented independent practice purchasing.
- Hospitals:Acute care institutions with centralized supply chain management and group purchasing organization affiliation. United States health systems are pursuing SKU portfolio consolidation under value-based care contracts, eliminating redundant gauze specifications.
- Clinics:Outpatient facilities with decentralized procurement and higher price sensitivity. District hospitals in Maharashtra and Tamil Nadu under India's government health infrastructure programs are equipping standardized wound care protocols.
- Home Care Settings:Patient-directed care environments with pharmacy platform purchasing and caregiver training requirements. Silicone tape refills through regulated Japanese pharmacy platforms are establishing new distribution pathways.
- Rehabilitation Centers:Long-term recovery facilities with specialized compression and mobility support needs. German rehabilitation networks specify extended-wear silicone adhesives for geriatric populations with fragile skin integrity.
Contract concentration favors Hospitals; channel innovation favors Home Care Settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal divergent regional trajectories, with developed markets sourcing specialized silicone adhesives while emerging economies build woven gauze manufacturing capacity for regional supply security.
United States
Ambulatory surgery centers are expanding gauze and tape procurement volumes as same-day procedure protocols reduce hospital admission rates. FDA enforces 21 CFR Part 820 quality system regulations for medical tape manufacturers, elevating compliance costs for new market entrants. Zhejiang and Jiangsu province manufacturing clusters in China supply spunlace non-woven substrates to US distributors, exposing buyers to concentrated geographic supply risk.
Germany
Extended producer responsibility frameworks are phasing out polyethylene tape backings before bio-based alternatives achieve cost-competitive scale. EMA's Medical Device Regulation mandates clinical evidence for adhesive products claiming extended wear duration. REACH substance restrictions on persistent organic pollutants are forcing eighteen-month material qualification cycles at wound care contract manufacturers to maintain CE marking.
China
Government health infrastructure programs are equipping district hospitals with standardized wound care protocols, expanding domestic consumption. The country's national pharmaceutical regulator enforces sterilization validation protocols for medical device manufacturing. Spunlace non-woven substrate production concentrates in Zhejiang and Jiangsu provinces, creating supply chain vulnerability for international buyers dependent on Chinese rayon feedstock.
Japan
Chronic wound patients are purchasing silicone tape refills through regulated pharmacy platforms, bypassing traditional hospital supply intermediaries. METI oversees medical device quality standards including biocompatibility testing requirements for skin-contact applications. Home healthcare nurses managing pressure ulcers are specifying seven-day wear durations, compressing commodity acrylic tape volumes while expanding premium coating demand.
India
Government health infrastructure programs are equipping district hospitals in Maharashtra and Tamil Nadu with standardized wound care protocols. CDSCO regulates medical device manufacturing and import licensing for adhesive products. Raw cotton futures volatility tied to agricultural yields compresses margin predictability for domestic woven gauze manufacturers dependent on spot market procurement.
Medical Gauze and Tapes Market Key Industry Players
Concentration sits with diversified healthcare conglomerates possessing polymer science infrastructure and extensive distribution networks. Automated weaving and coating lines are concentrating production economics among capital-rich suppliers while manual finishing operations fragment the long tail. Three archetypes dominate: integrated healthcare suppliers with hospital supply contracts, specialized wound care technology developers, and regional textile converters. Competitive moves center on portfolio rationalization around standardized performance tiers and strategic partnerships for bio-based material sourcing.
Among diversified healthcare conglomerates, 3M Company exemplifies the polymer science-driven archetype through its adhesive technology capabilities. Medline Industries occupies a position representing the North American hospital supply contract anchor. Mölnlycke Health Care AB sits within the specialized wound care technology tier, with its Swedish corporate structure signaling advanced medical device positioning. Johnson & Johnson represents the integrated healthcare conglomerate archetype through its diversified medical device portfolio.
| Leading Market Players |
|---|
| 3M Company |
| Johnson & Johnson |
| Cardinal Health |
| Medline Industries |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Mölnlycke Health Care AB |
| Paul Hartmann AG |
| McKesson Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for spunlace non-woven substrates expose buyers to both cotton futures volatility and concentrated Chinese manufacturing, compressing margin predictability for distributors while amplifying pricing power among integrated polymer science suppliers with captive rayon feedstock.
Pricing Analysis
The customization-premium spread between configured-to-order silicone adhesive tapes and standard cotton-rayon gauze spans three performance tiers anchored by FDA 510(k) clearance status and ISO 10993 biocompatibility certification grade. Contract-based long-term offtake dominates hospital system procurement, though ambulatory surgery centers exhibit acute price sensitivity to spot cotton futures. Pricing pressure intensifies in commodity woven gauze as Indian spot market volatility feeds through to margin compression, while silicone chemistry variants command brand premiums from geriatric wound care specialists in Germany and Japan.
Supply Chain Analysis
Inbound logistics costs from Zhejiang and Jiangsu province ports to North American distributors hinge on container availability through Shanghai-Ningbo trade lanes, exposing buyers to congestion risk. Raw material dependencies center on Indian cotton futures, Chinese viscose rayon feedstock, and German silicone adhesive precursors. Single-source vulnerability concentrates in spunlace non-woven substrate production clusters. Distribution runs through group purchasing organizations consolidating hospital system contracts under value-based care frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical gauze and tapes sit in early-cycle expansion as silicone adhesive chemistry displaces legacy acrylic formulations across extended-wear wound care applications, with outpatient surgical volume growth accelerating premium product penetration.
For Market Incumbents: Shield market position by deepening backward integration into silicone polymer production and securing CE marking for extended-wear claims ahead of EMA MDR enforcement timelines. Prioritize certification investment to lock out commodity converters lacking clinical evidence documentation capabilities. For New Entrants and Emerging Players: E-commerce pharmacy platform fulfillment represents the most penetrable service-layer gap, with Japanese direct-to-patient channels bypassing traditional hospital supply intermediaries. Target home care settings in Maharashtra and Tamil Nadu district hospitals under India's infrastructure expansion programs. Pursue biodegradable gauze mandates as a go-to-market angle through EU Green Deal procurement channels. For Investors and Strategic Acquirers: Long-term, this sits as a materials science consolidation play because polymer chemistry capabilities are concentrating competitive economics among capital-rich suppliers with sterilization validation infrastructure. Watch silicone adhesive capacity expansion announcements as the inflection signal for premium tier supply-demand balance.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Adhesive Capacity Expansion | Captures extended-wear demand from geriatric wound care protocols in Germany and Japan. |
| Biodegradable Material Certification | Unlocks preferential EU Green Deal contracting channels in French and Dutch hospital systems. |
| Hospital System Partnership | Secures volume commitment under group purchasing organization rationalization programs in the United States. |
| Backward Integration into Rayon Feedstock | Insulates margin from Zhejiang and Jiangsu province supply concentration risk. |
| E-Commerce Pharmacy Platform Integration | Establishes direct-to-patient channel access for chronic wound refill purchases in Japan. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts directors, and wound care clinicians, validated against FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and spunlace non-woven trade flow records. Bottom-up demand modeling triangulated against top-down industry revenue estimates.
Across the analysis window, forecasts integrate product type, material chemistry, application setting, and end-user facility tier dimensions. CAGRs derive from procedure volume trajectories, regulatory compliance cost curves, and material substitution elasticity parameters. Silicone adhesive adoption rates and biodegradable mandate implementation timelines serve as key sensitivity inputs.
Underlying assumptions cover sterilization validation protocol stability and cotton futures mean-reversion, with deviation risk concentrated in EMA MDR enforcement timing and Chinese export license disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Foley Trays Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Emesis Bag Market
Medical Supplies
First Aid Kit Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Forensic Swabs Market