
 Americas Safety Lancet Market | 2026-2036
Americas Safety Lancet Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Safety Lancet Market Outlook
Preventive maintenance and device calibration services bundled with lancet systems is expanding the recurring revenue base for manufacturers serving integrated delivery networks. BD leverages its direct hospital contracting strength to sustain volume commitments across North American group purchasing organizations. HTL-STREFA specializes in precision-molded plastic components that anchor its position in the manual safety lancet segment. Abbott Laboratories competes through diagnostic ecosystem integration, extending its reach from glucose monitoring into complementary blood collection workflows.
Safety lancets are spring-loaded or pressure-activated puncture devices engineered to retract or shield the needle after a single use, typically manufactured from medical-grade polymers with stainless steel blades calibrated to penetration depths between 1.5 mm and 2.5 mm. Their primary purpose is to obtain capillary blood samples while eliminating needlestick injury risk to healthcare workers and patients. Self-acting lancets dominate hospital procurement due to zero-user-variability activation, while the homecare channel shows the fastest trajectory as diabetes management shifts beyond clinical settings. Material selection increasingly gravitates toward biocompatible plastics over metal alternatives, with margin pools concentrating in silver-coated and biodegradable variants that command premium positioning.
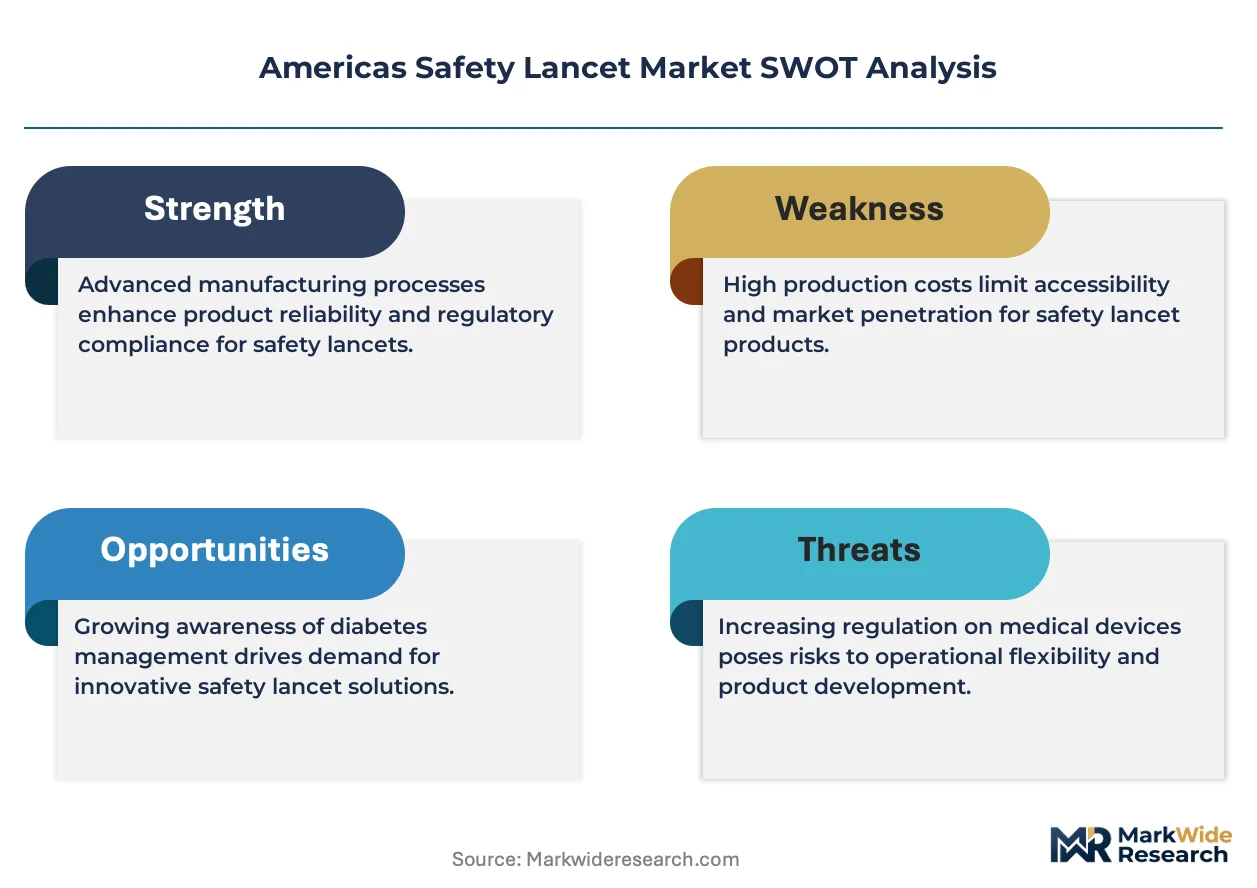
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement shape product design requirements and channel access across the United States, while Health Canada and ANVISA establish parallel compliance benchmarks in Canada and Brazil respectively. These frameworks mandate active safety mechanisms, creating barriers for non-compliant imports and accelerating replacement cycles. Stakeholders must monitor evolving state-level sharps injury reporting requirements and reimbursement coding changes that will determine competitive positioning in the homecare transition.
Market Dynamics
Homecare migration of chronic disease management is compressing hospital procurement volumes while expanding retail and direct-to-patient channels across the United States, Brazil, and Canada. This structural shift forces manufacturers to reconfigure distribution networks and service models around individual consumers rather than institutional buyers.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Active safety mechanism mandates in US healthcare settings accelerate replacement cycles for non-compliant devices and block import competition lacking certification.
- Capillary blood sampling:Point-of-care diagnostic expansion in Brazilian primary care clinics drives demand for single-use safety lancets calibrated for diverse skin types.
- Integrated delivery networks:Hospital system consolidation across the United States favors vendors offering bundled preventive maintenance and calibration services alongside device supply.
Market Restraints
- Medical-grade polymer supply concentration:Precision-molded plastic component sourcing clusters with specialized European and Asian suppliers, exposing manufacturers to input cost volatility and lead time extension.
- Biodegradable material performance gaps:Degradation rate variability in compostable lancet variants limits penetration depth consistency, constraining adoption in clinical settings requiring calibrated sampling.
- ANVISA import licensing timelines:Brazilian regulatory review periods for novel safety mechanisms extend market entry by 12-18 months versus FDA 510(k) pathways, delaying product launches.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled lancet readers converging with glucose monitoring apps create subscription revenue streams in US homecare channels.
- Canadian long-term care facilities:Underpenetrated institutional segment outside acute hospital networks offers volume growth as provincial health authorities consolidate procurement.
- Medicare reimbursement coding expansion:Policy momentum toward covering continuous glucose monitoring companion devices extends addressable market for safety lancet ecosystem partners.
Industry Challenges
- ISO 13485 quality management certification:Medical device quality system implementation requires 18-24 month timelines and specialized auditor access, slowing new entrant qualification.
- Legacy hospital inventory systems:ERP integration complexity with procurement platforms at merged US health systems demands customized API development and extended pilot periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Safety Lancet Market |
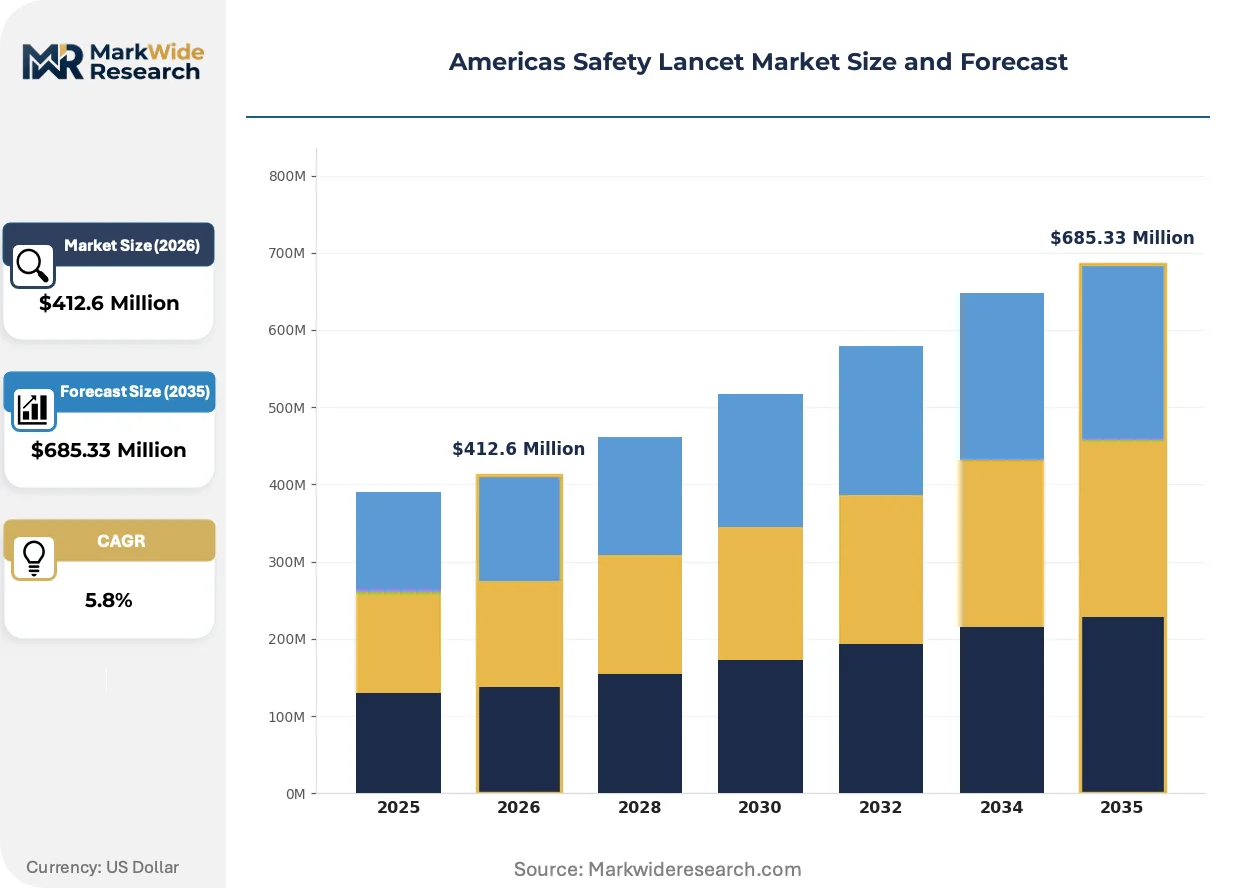
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Acting, Manual, Auto-Disable, Safety Pen End User: Hospitals, Clinics, Homecare, Diagnostics Laboratories Material: Plastic, Stainless Steel, Silver-coated, Biodegradable Application: Diabetes Management, Blood Screening, Vaccine Delivery, Blood Testing |
| Companies Covered | F. Hoffmann-La Roche AG, HTL-STREFA, BD, Terumo Corporation, B. Braun Melsungen AG, Abbott Laboratories, Medtronic, Cardinal Health, Roche Diagnostics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Safety Lancet Market Strategic Shifts
Pressure-activated self-acting mechanisms are overtaking manual activation designs as the dominant engineering approach, with material science advances enabling thinner-gauge stainless steel blades without structural compromise. This evolution reflects end-user demand for zero-variability performance.
Spring-loaded retraction systems with integrated needle shields is overtaking friction-based manual lancets in US hospital procurement. Self-acting devices eliminate user-dependent activation force, reducing failed punctures and needlestick incidents. Health system risk managers now specify active safety mechanisms as mandatory bid criteria, compressing margins for manual product lines.
FDA 510(k) clearance pathway refinements for blood collection devices are accelerating premarket review timelines for safety-engineered lancets with predicate device equivalence. Manufacturers submitting substantial equivalence claims for blade geometry modifications receive determinations within 90 days versus 150 days for novel mechanisms. This regulatory efficiency most benefits US-based suppliers with established predicate portfolios, pressuring foreign competitors to acquire or partner for faster market access.
Retail pharmacy channel expansion for diabetes management supplies is displacing traditional durable medical equipment distributors in the United States. CVS Health and Walgreens capture increasing lancet volume through prescription synchronization programs and cash-pay convenience offerings. This channel rotation concentrates pricing power with retail buyers and demands smaller pack sizes, direct-to-consumer branding, and loyalty program integration from manufacturers.
Americas Safety Lancet Market Segmentation
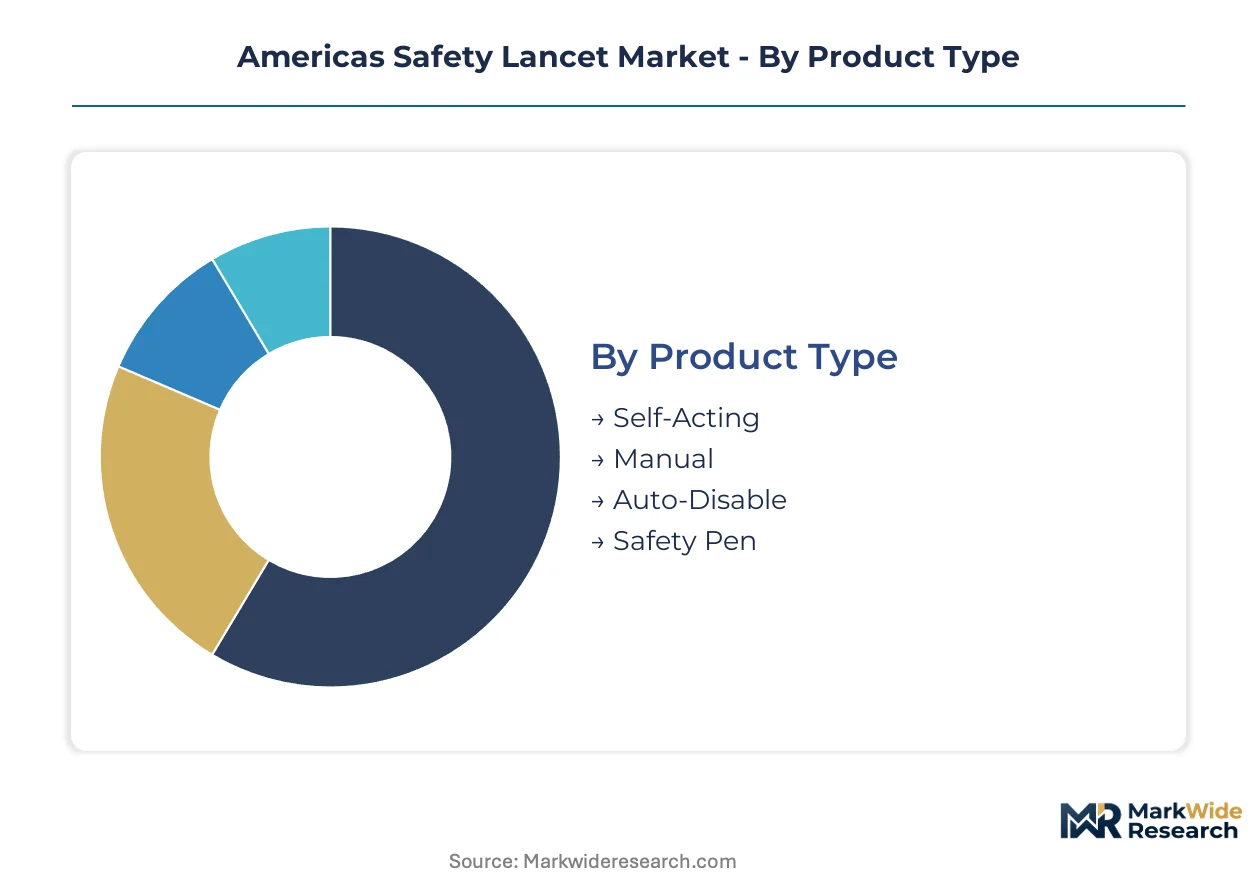
Segmentation in the Americas Safety Lancet Market reveals how procurement criteria diverge across institutional and consumer channels. Product design specifications, material selection, and activation mechanisms must align with distinct clinical workflows and regulatory compliance tiers.
Product Type:
The customization-to-standardization spectrum spans fully automated mechanisms requiring zero user training versus manual devices offering tactile control for specialized sampling.
- Self-Acting:Spring-loaded retraction systems activate upon pressure contact, eliminating user-dependent variability. Hospital procurement across the United States mandates these devices under OSHA Bloodborne Pathogens compliance, with integrated needle shields becoming standard bid criteria.
- Manual:Friction-based activation requires deliberate thumb pressure, appealing to clinicians needing precise penetration depth control for neonatal or geriatric patients with fragile capillary beds.
- Auto-Disable:Single-use locking mechanisms prevent reactivation after initial puncture, addressing sharps waste handling protocols in Canadian provincial health systems.
- Safety Pen:Pen-shaped housings with retractable blade cartridges target homecare patients prioritizing discretion and portability in diabetes management routines.
Most installed capacity flows through Self-Acting devices. Expansion is steepest in Safety Pen formats as retail pharmacy channels displace traditional durable medical equipment distribution.
End User:
Customer concentration shifts from consolidated hospital networks toward fragmented individual consumers, reshaping service models and pack configurations.
- Hospitals:Integrated delivery networks negotiate multi-year volume commitments tied to preventive maintenance and calibration service bundles. Consolidated procurement favors vendors with direct contracting strength across group purchasing organizations.
- Homecare:Direct-to-patient channels demand smaller pack sizes, subscription replenishment models, and Bluetooth-enabled readers converging with glucose monitoring applications.
- Clinics:Brazilian primary care facilities drive point-of-care diagnostic expansion, requiring lancets calibrated for diverse skin types and tropical climate storage stability.
- Diagnostics Laboratories:High-throughput processing centers prioritize bulk packaging and automated handling compatibility over individual device features.
Hospital systems still absorb the largest volume share. Homecare channels are climbing the fastest as chronic disease management migrates beyond clinical settings.
Material:
Margin pools concentrate in premium material variants commanding price premiums, while commodity plastics dominate volume production.
- Plastic:Medical-grade polymers enable precision-molded components at scale, though supply concentration with specialized European and Asian suppliers exposes manufacturers to input cost volatility.
- Silver-coated:Antimicrobial surface treatments reduce infection risk in immunocompromised patient populations, justifying reimbursement premiums in US Medicare coding frameworks.
- Stainless Steel:Calibrated blade geometry between 1.5 mm and 2.5 mm penetration depths remains the structural standard for consistent capillary flow.
- Biodegradable:Compostable variants face performance gaps in degradation rate consistency, limiting adoption where calibrated sampling depth is clinically mandatory.
Plastic formulations carry the majority of unit volume. Silver-coated variants are gaining share fastest as infection control protocols tighten across long-term care facilities.
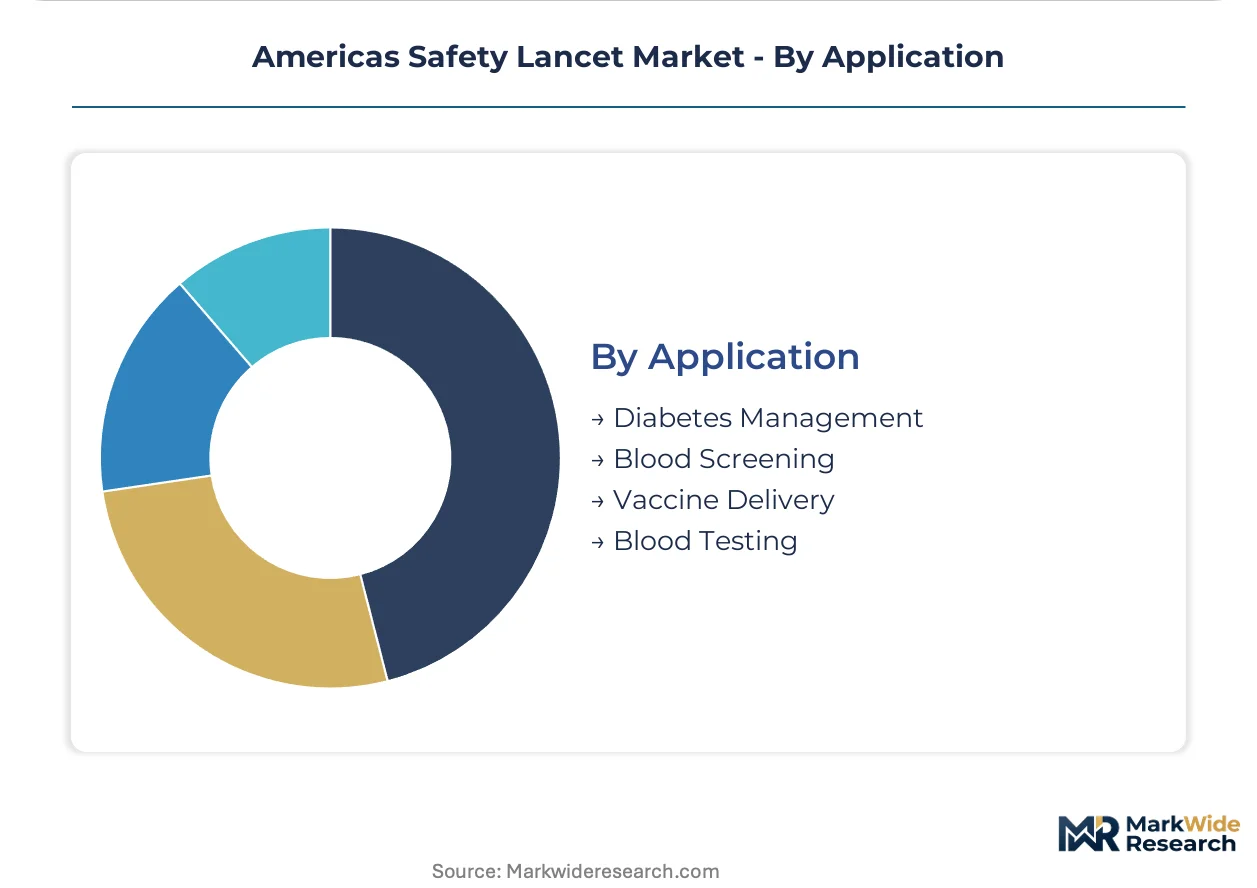
Application:
Clinical utility ranges from routine chronic monitoring to episodic screening programs with divergent device performance requirements.
- Diabetes Management:Daily self-monitoring blood glucose drives the largest addressable need, with patient adherence patterns favoring low-pain activation mechanisms and compact disposal systems.
- Blood Screening:Population-scale testing programs in Brazil require devices optimized for field conditions and minimal cold chain dependency.
- Vaccine Delivery:Intradermic priming applications demand specialized shallow penetration settings distinct from standard capillary sampling depths.
- Blood Testing:General diagnostic workflows span hematology panels to infectious disease markers, with laboratory information system integration becoming a procurement differentiator.
Diabetes applications anchor current demand. Blood screening programs show the steepest expansion trajectory as public health authorities scale preventive testing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's point-of-care diagnostic expansion contrasts with Canada's underpenetrated long-term care procurement, revealing divergent institutional maturity across the Americas safety lancet landscape.
United States
Hospital system consolidation and Medicare reimbursement policies concentrate demand within integrated delivery networks. OSHA Bloodborne Pathogens Standard enforcement mandates active safety mechanisms, blocking non-compliant imports. Boston and Minneapolis medical device clusters anchor manufacturing partnerships for precision-molded components serving group purchasing organizations.
Brazil
Primary care clinic expansion and tropical climate storage requirements drive demand for devices calibrated to diverse skin types. ANVISA import licensing timelines extend market entry by 12-18 months versus FDA pathways. São Paulo's diagnostic distribution hub channels volume into public health screening programs scaling preventive testing infrastructure.
Canada
Provincial health authority consolidation creates procurement concentration in underpenetrated long-term care facilities outside acute hospital networks. Health Canada establishes parallel compliance benchmarks to FDA standards. Ontario's healthcare procurement cooperative negotiates multi-year agreements favoring vendors with preventive maintenance service bundles.
Mexico
Cross-border manufacturing integration supplies precision-molded plastic components to US-based device assemblers. The country's national medical device regulator aligns certification requirements with FDA harmonization initiatives. Baja California's maquiladora corridor hosts contract manufacturing operations serving North American safety lancet assembly.
Americas Safety Lancet Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement favoring direct-contracting incumbents while retail channels fragment toward private-label suppliers. The vendor base organizes around three archetypes: diversified medtech conglomerates with diagnostic ecosystem integration, precision-component specialists with captive molding capabilities, and distribution-heavy intermediaries with group purchasing organization access. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure medical-grade polymer supply and integrate remote patient monitoring connectivity.
Among diversified healthcare conglomerates, F. Hoffmann-La Roche AG and Abbott Laboratories exemplify the diagnostic ecosystem archetype, anchoring positions through glucose monitoring platform integration. BD occupies a position within the hospital contracting tier, leveraging direct institutional relationships across North American procurement networks. HTL-STREFA represents the precision-component specialist model, with its naming convention indicating Polish origins and a focus on manual safety lancet manufacturing.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| HTL-STREFA |
| BD |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| Medtronic |
| Cardinal Health |
| Roche Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between OSHA-compliant active safety mechanisms and non-certified manual alternatives manifests in both pricing premiums and supply chain tiering. US hospital procurement channels absorb the compliance premium, while retail homecare channels gravitate toward unbundled commodity pricing. Medical-grade polymer sourcing clusters in specialized European and Asian suppliers, creating input cost asymmetry that feeds through to margin structures.
Pricing Analysis
Capacity additions in Mexican maquiladora corridors are reshaping price floors for precision-molded plastic components serving North American assembly. Three-tier pricing structure across premium silver-coated variants, standard medical-grade polymers, and economy manual devices reflects differentiation by FDA 510(k) certification status and infection control performance. Cost compression in the economy tier intensifies as private-label retail pharmacy sourcing concentrates volume with CVS Health and Walgreens. Homecare patients exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Medical-grade polymer feedstock rests on German, Japanese, and South Korean specialty chemical producers with limited qualified alternatives. Stainless steel blade calibration equipment and precision injection molding tooling constitute critical component dependencies alongside antimicrobial silver coating applications. Single-source vulnerability concentrates in European suppliers of biocompatible resin formulations subject to REACH regulatory restriction. Distribution runs through group purchasing organization contracts for hospital channels, while retail pharmacy direct sourcing bypasses traditional durable medical equipment intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas Safety Lancet Market functions as a regulatory compounder where OSHA Bloodborne Pathogens Standard enforcement creates replacement-cycle demand independent of clinical volume growth. Each compliance milestone accelerates obsolescence of non-certified inventory.
For Market Incumbents: Extend preventive maintenance service bundling across merged US health system ERP platforms to deepen switching costs. Secure captive supply of medical-grade polymers through backward integration into Mexican component molding or long-term offtake agreements with European resin specialists. BD and Abbott Laboratories face margin compression from retail pharmacy channel rotation unless they consolidate GPO contracting strength into subscription-based homecare replenishment models. For New Entrants and Emerging Players: Launch via direct-to-patient subscription channels targeting underpenetrated Canadian long-term care facilities outside provincial hospital networks. Brazilian primary care clinics offer the most penetrable white space given ANVISA licensing delays that deter established competitors. Pursue Bluetooth-enabled lancet reader integration with glucose monitoring applications as the primary go-to-market angle, converting device sales into recurring software revenue. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification scarcity meets hospital procurement consolidation into multi-year volume commitments. Mid-cap precision molding specialists with captive polymer sourcing and existing FDA predicate portfolios represent the optimal acquisition archetype. Watch Medicare reimbursement coding expansion for continuous glucose monitoring companion devices as the inflection signal determining homecare channel addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct GPO contracting with integrated delivery networks secures multi-year volume commitments against retail channel erosion. |
| FDA 510(k) Submission | Predicate device equivalence claims accelerate premarket review timelines to 90 days versus 150 days for novel mechanisms. |
| Software Companion Development | Bluetooth-enabled lancet readers converging with glucose monitoring apps create subscription revenue in homecare channels. |
| Backward Integration | In-house production of precision-molded plastic components insulates margin from European and Asian supplier concentration. |
| Reimbursement Strategy | Medicare coding alignment for silver-coated antimicrobial variants captures infection control protocol premiums in long-term care. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with hospital purchasing committees, biomedical engineers, GPO contracts managers, and homecare diabetes educators with secondary validation. Hospital procurement databases, GPO contract repositories, CMS Medicare reimbursement filings, FDA 510(k) clearance records, and ANVISA import licensing timelines anchored the secondary architecture. Bottom-up unit volume modeling and top-down expenditure flow analysis triangulated market sizing across the projection horizon.
Segment-weighted forecasting applied product type, end user channel, material grade, and application dimensions across the modeling period. Activation mechanism adoption curves, homecare migration rates, and regulatory compliance replacement cycles fed the analytical framework. CAGRs derived from logistic diffusion modeling of safety-engineered device penetration against legacy manual install bases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA regulatory delay scenarios or medical-grade polymer supply disruption. Assumptions reflect OSHA enforcement continuity, Medicare reimbursement stability, and hospital consolidation trajectories. A small set of named triggers warrants ongoing watch: state-level sharps injury reporting requirement expansion, biodegradable material performance breakthroughs, and retail pharmacy private-label sourcing concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Soaker Pads Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Disposable Oxygen Masks Market