
 Tissue Embedding Center Market | 2026-2036
Tissue Embedding Center Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Embedding Center Market Insights
China is rewriting regional supply dynamics for tissue embedding equipment through expanded domestic manufacturing of precision temperature-control systems. Leica Biosystems leverages its European installed base to sustain service contract renewals across hospital laboratories. Thermo Fisher Scientific anchors North American demand through integrated workflow solutions that bundle embedding modules with adjacent histology instruments. Sakura Finetek competes aggressively in Asia-Pacific markets with localized production and region-specific distributor networks.
A tissue embedding center is a laboratory workstation that stabilizes processed tissue specimens in molten paraffin wax, typically operating at precise temperature ranges between 55°C and 65°C for optimal infiltration and block formation. The equipment enables subsequent microtome sectioning for histopathological diagnosis and research analysis. Embedding modules command the largest product type share due to universal deployment in clinical diagnostics, though cryostats are gaining traction in intraoperative frozen section applications where rapid turnaround overrides throughput volume. Among end users, diagnostic laboratories represent the fastest-growing demand pool as outsourced histopathology services expand, while hospitals retain the deepest margin pools through bundled capital equipment procurement.
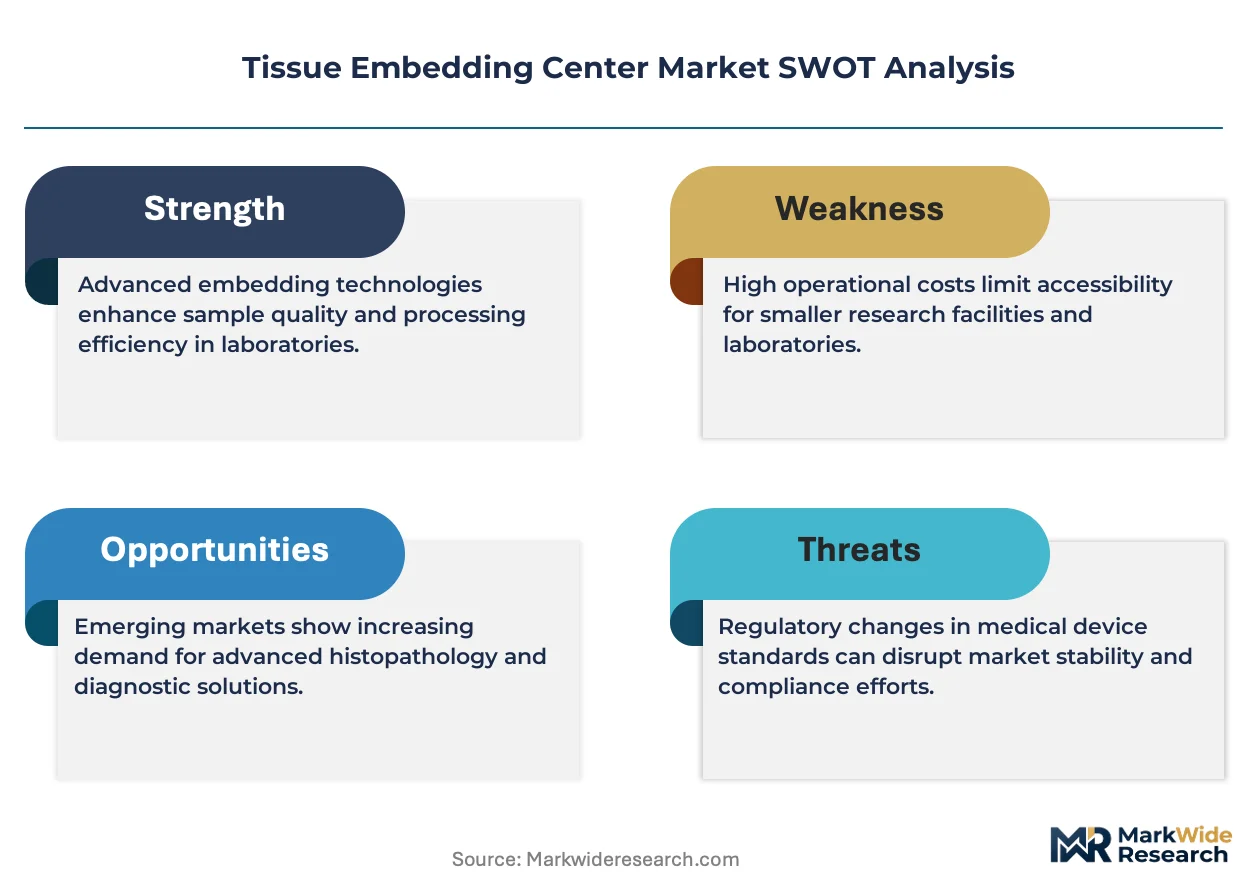
FDA oversight of in vitro diagnostic device quality systems and EU MDR requirements for clinical laboratory equipment traceability are elevating documentation and validation burdens for embedding center manufacturers. ISO 13485 certification has become a baseline market access requirement rather than a differentiator in regulated geographies. Stakeholders must monitor evolving harmonization between FDA 21 CFR Part 820 and EU quality management system standards to avoid duplicate compliance costs.
Market Dynamics
Automated temperature-control modules are compressing technician labor requirements in histopathology workflows while simultaneously elevating capital intensity thresholds for laboratory procurement decisions.
Growth Catalysts
- Rising Biopsy Volumes:Hospital pathology departments in Germany and the United States are expanding embedding station capacity to manage escalating cancer screening program throughput.
- EU MDR Traceability Mandates:Diagnostic device manufacturers must embed serialization and quality documentation systems, forcing equipment upgrades across clinical laboratories.
- Paraffin Formulation Advances:Low-melting-point polymer blends reduce thermal tissue artifact, accelerating replacement cycles for legacy embedding centers.
Market Restraints
- Specialized Component Concentration:Precision heating elements and PID controllers source predominantly from East Asian suppliers, exposing procurement to logistics volatility.
- ISO 13485 Certification Burden:Small regional manufacturers face extended timeline and documentation costs to access regulated European and North American markets.
- Cryostat Substitution:Frozen section systems are capturing intraoperative diagnostic volume that previously required rapid paraffin embedding turnaround.
Strategic Opportunities
- India Diagnostic Outsourcing:Commercial histopathology chains in Mumbai and Bangalore are consolidating fragmented laboratory networks, creating bundled equipment procurement demand.
- Integrated Workflow Convergence:Embedding modules paired with automated tissue processors and digital slide scanners are commanding premium positioning in greenfield laboratory construction.
- US CLIA Laboratory Expansion:Reference laboratory construction under Clinical Laboratory Improvement Amendments oversight is accelerating capital equipment deployment timelines.
Industry Challenges
- Histotechnician Talent Scarcity:Specialized certification programs for tissue processing and microtomy are producing insufficient graduates to staff expanded laboratory capacity.
- Legacy System Integration:New embedding centers must interface with existing laboratory information management systems, extending deployment timelines and validation costs.
- Dual Jurisdiction Validation:Manufacturers seeking simultaneous FDA 510(k) clearance and EU MDR conformity face divergent testing protocols and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Embedding Center Market |
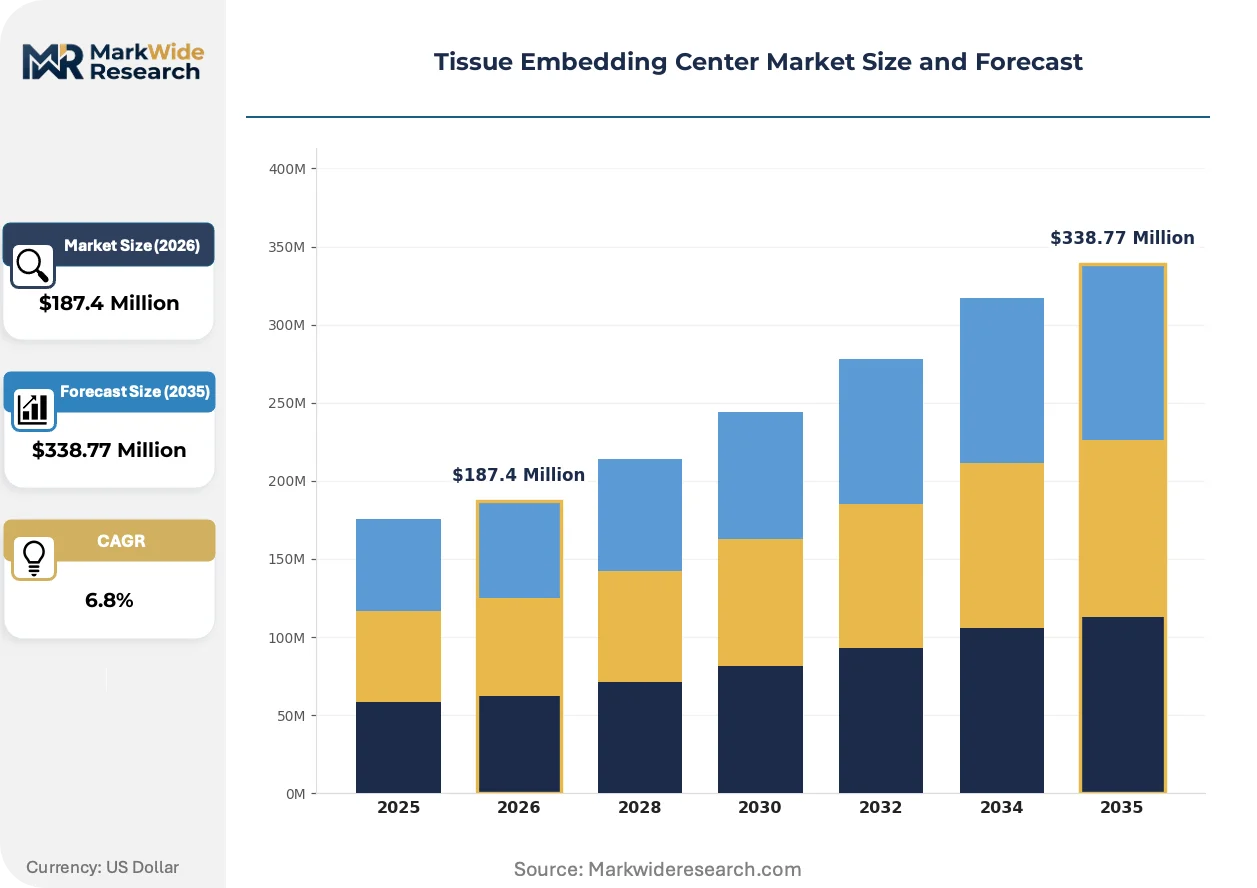
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedding Modules, Cryostats, Tissue Processors, Microtomes Application: Laboratory Research, Clinical Diagnostics, Pharmaceutical Development, Educational Training End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Facilities Delivery Mode: Direct Sales, Online Sales, Distributors, Service Contracts |
| Companies Covered | Leica Biosystems, Thermo Fisher Scientific, Sakura Finetek, Bio-Optica Milano, General Data Healthcare, Medite GmbH, Histo-Line Laboratories, SLEE Medical GmbH, Diapath S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Embedding Center Market Trends and Innovations
Digital temperature logging and remote diagnostic capabilities are transforming equipment service models while compressing the traditional boundaries between capital sale and recurring revenue streams.
Programmable thermal profiling with multi-stage ramp protocols is rendering obsolete fixed-temperature analog embedding stations that lack infiltration optimization. Academic medical centers in the United States and university hospitals in Germany are adopting these systems at replacement-cycle velocity. The technology is rendering obsolete manual wax-pouring workflows and reducing inter-technician variability in block quality.
EU MDR requirements for clinical laboratory equipment traceability are mandating embedded software documentation and cybersecurity validation for networked embedding centers. Manufacturers must now maintain technical files across the product lifecycle with notified body oversight. Diagnostic laboratories in France and Italy are prioritizing vendors with established EU MDR conformity assessment pathways to avoid procurement delays.
Service contract unbundling is separating preventive maintenance from corrective repair in laboratory equipment procurement. Independent service organizations are capturing aftermarket revenue previously retained by original equipment manufacturers through multi-vendor maintenance agreements. This pattern is most visible in Germany's centralized histopathology networks where procurement committees negotiate multi-site service aggregations.
Tissue Embedding Center Market Segmentation
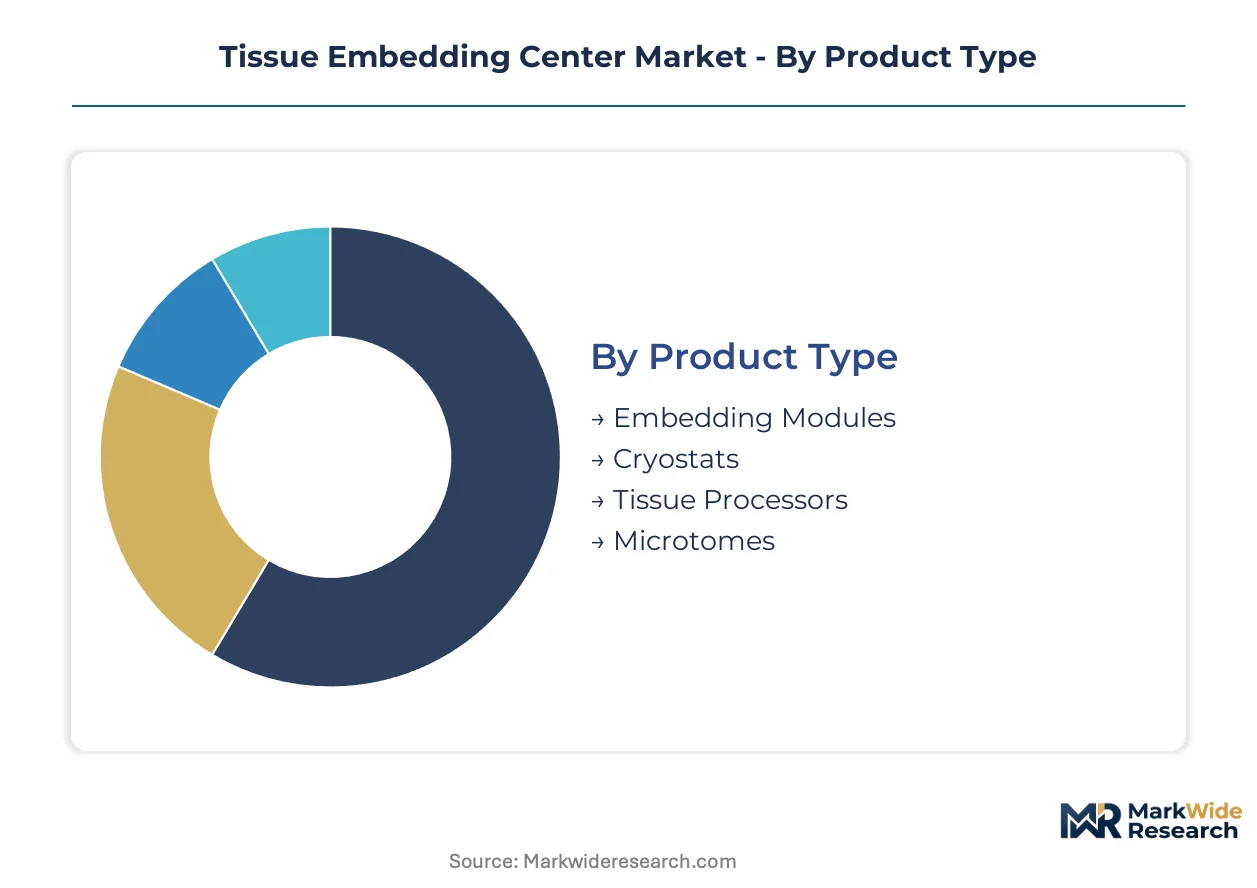
Tissue embedding center segmentation reveals distinct procurement patterns across equipment categories and customer workflows. Laboratory infrastructure investments diverge sharply between high-throughput clinical environments and precision research applications.
Product Type:
Equipment selection tracks directly against specimen volume requirements and turnaround constraints in histopathology operations.
- Embedding Modules:These workstations stabilize tissue specimens in molten paraffin wax through precision temperature control between 55°C and 65°C. Hospital pathology departments in Germany are replacing aging analog units with programmable thermal profiling systems to reduce inter-technician variability in block quality.
- Cryostats:Frozen section systems enable rapid intraoperative diagnosis by cutting tissue at temperatures near -20°C without paraffin infiltration. Demand concentrates in academic medical centers where intraoperative consultation volumes override throughput efficiency priorities.
- Tissue Processors:Automated dehydration and clearing instruments prepare specimens prior to embedding through reagent exchange protocols.
- Microtomes:Precision cutting instruments generate thin tissue sections from embedded blocks for mounting on glass slides.
Embedding modules command the established base. The steepest expansion runs through cryostats.
Application:
End-use context determines equipment specifications, regulatory validation requirements, and service contract structures.
- Clinical Diagnostics:High-throughput histopathology services for cancer screening and surgical pathology demand validated workflows with full traceability documentation. Commercial laboratory chains in India are consolidating procurement across Mumbai and Bangalore networks to capture volume pricing.
- Laboratory Research:Academic and pharmaceutical investigations prioritize experimental flexibility over standardization, driving demand for modular systems with customizable thermal protocols.
- Pharmaceutical Development:Toxicology studies and biomarker validation require GLP-compliant equipment with embedded software documentation for regulatory submissions.
- Educational Training:Histotechnology certification programs need durable, simplified systems that withstand repetitive student use without precision degradation.
Clinical diagnostics anchors revenue concentration. Laboratory research is climbing the fastest.
End User:
Customer type shapes capital deployment cycles, bundling preferences, and aftermarket service arrangements.
- Diagnostic Laboratories:Outsourced histopathology providers are expanding embedding capacity to capture hospital outsourcing trends. Reference laboratory construction under US CLIA oversight is accelerating equipment deployment timelines.
- Hospitals:Integrated health systems leverage bundled capital procurement across pathology, surgery, and oncology departments to extract vendor concessions.
- Academic Institutions:University hospitals in Germany and the United States are adopting multi-stage ramp protocol systems at replacement-cycle velocity.
- Research Facilities:Government and private research institutes prioritize equipment interoperability with existing laboratory information management systems.
Hospitals retain the deepest margin pools. Diagnostic laboratories are gaining share fastest.
Delivery Mode:
Channel structure reflects equipment complexity, geographic concentration of demand, and service integration requirements.
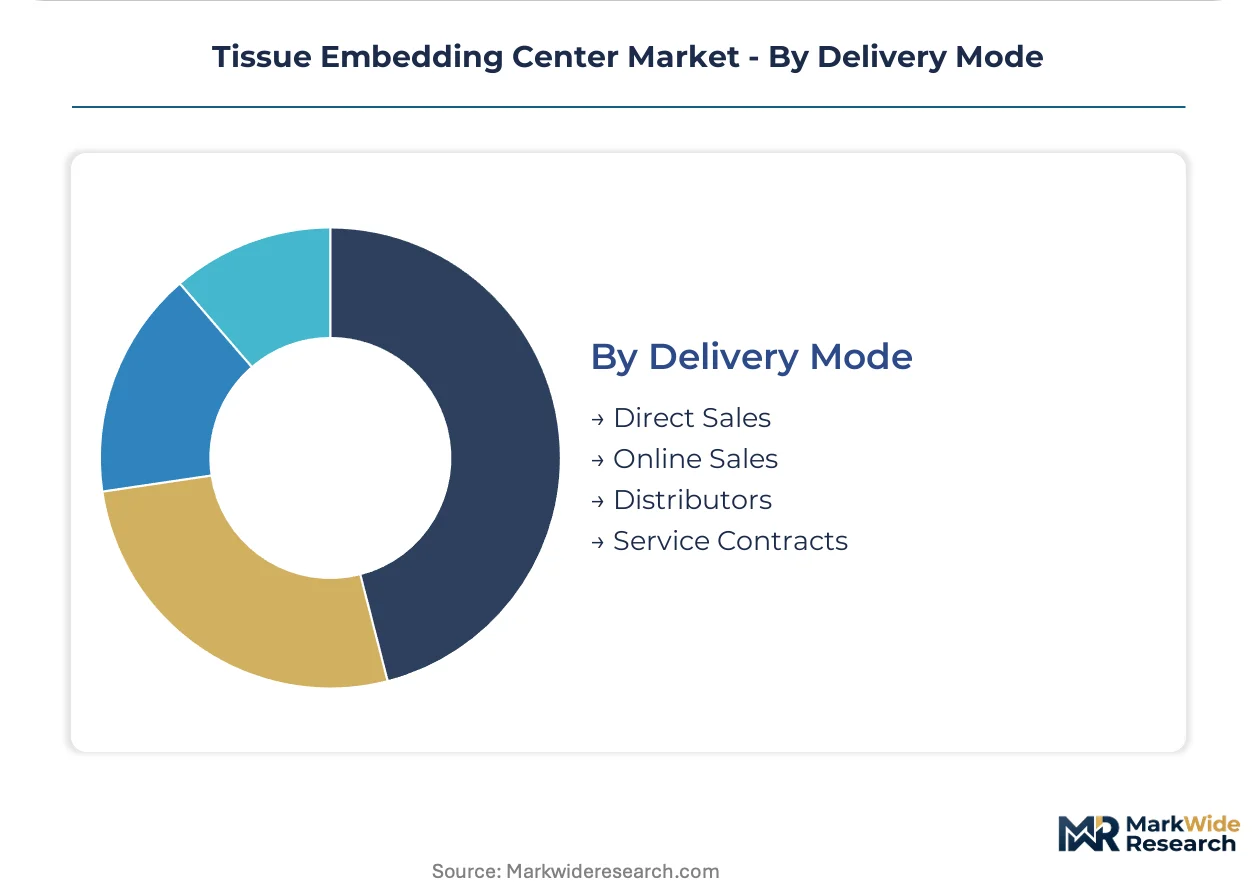
- Direct Sales:Original equipment manufacturers maintain field organizations for complex system integration and validation support in major metropolitan clusters.
- Distributors:Regional networks capture fragmented demand across secondary cities and emerging markets through localized technical support.
- Service Contracts:Preventive maintenance and corrective repair agreements are unbundling from equipment sales, with independent service organizations capturing aftermarket revenue through multi-vendor arrangements.
- Online Sales:Consumables and replacement components migrate to digital channels for standardized catalog items with predictable specifications.
Direct sales commands premium system placements. Service contracts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision laboratory equipment distribution, connecting Central European histopathology networks to East Asian component suppliers. Frankfurt Airport's pharma cargo hub accelerates diagnostic device validation cycles across the continent.
United States
Reference laboratory construction under CLIA oversight is accelerating embedding center deployment timelines in Texas and North Carolina. FDA 21 CFR Part 820 quality system regulations mandate extensive documentation for equipment validation. The Research Triangle Park cluster concentrates toxicology testing facilities that demand GLP-compliant thermal processing systems.
Germany
Centralized histopathology networks in Bavaria and North Rhine-Westphalia are driving replacement cycles for aging analog embedding stations. EU MDR traceability requirements force equipment upgrades with embedded serialization systems. The Tübingen-Stuttgart medical technology corridor hosts validation laboratories serving hospital procurement consortia.
China
Domestic manufacturing of precision temperature-control systems is expanding through Yangtze River Delta suppliers serving clinical diagnostics chains. NMPA medical device registration rules are tightening software documentation requirements for networked laboratory equipment. Shanghai's Zhangjiang Hi-Tech Park concentrates embedding module assembly operations targeting hospital pathology departments.
India
Commercial histopathology chains in Mumbai and Bangalore are consolidating fragmented laboratory networks into bundled equipment procurement programs. CDSCO medical device rules are harmonizing with international standards for diagnostic device traceability. The Hyderabad medical devices cluster is attracting component sourcing for temperature-control module assembly.
Japan
Academic medical centers in Kansai and Kanto regions are adopting programmable thermal profiling systems at replacement-cycle velocity. PMDA quality management system inspections enforce rigorous software lifecycle documentation for networked laboratory equipment. The Osaka pharmaceutical corridor concentrates toxicology testing facilities requiring precision embedding workflows.
Tissue Embedding Center Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision heating elements and PID controllers to multiple downstream brands. The vendor base concentrates around three to five integrated diagnostic equipment conglomerates with established service infrastructures, while regional fabricators compete on localized support and price positioning. Strategic archetypes include workflow bundlers pairing embedding modules with adjacent histology instruments, component aggregators sourcing temperature-control systems from East Asian suppliers, and service unbundlers capturing aftermarket maintenance through multi-vendor agreements. Dominant competitive moves include geographic expansion through distributor network establishment and technology licensing for programmable thermal profiling capabilities.
Among European-based platform integrators, Leica Biosystems and Thermo Fisher Scientific exemplify the workflow bundler archetype, while Sakura Finetek represents the Asia-Pacific regional specialist model with localized production strategies. These three anchors demonstrate how scale-driven service contract renewal rates and integrated system positioning create defensive moats against component-level competition.
| Leading Market Players |
|---|
| Leica Biosystems |
| Thermo Fisher Scientific |
| Sakura Finetek |
| Bio-Optica Milano |
| General Data Healthcare |
| Medite GmbH |
| Histo-Line Laboratories |
| SLEE Medical GmbH |
| Diapath S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on precision heating elements and PID controllers sourced from East Asian suppliers determines both the three-tier pricing spread across premium, standard, and economy equipment levels and the geographic configuration of final assembly operations. Laboratory procurement committees in Germany and the United States absorb elevated landed costs through extended service contract bundling, compressing margin pools for regional distributors serving price-sensitive diagnostic chains in India.
Pricing Analysis
Volume-discount tiering structures separate high-throughput hospital pathology departments from mid-scale commercial laboratories and small research facilities. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because CDSCO and NMPA registration requirements force documentation investments previously reserved for regulated geographies. Diagnostic laboratories in Mumbai and Bangalore exhibit the highest price sensitivity, while academic medical centers in Germany and Japan demonstrate the lowest.
Supply Chain Analysis
Contract manufacturing concentration for temperature-control modules rests with Yangtze River Delta suppliers serving Shanghai's Zhangjiang Hi-Tech Park assembly operations. Precision heating elements and PID controllers draw from China, South Korea, and Japan, with paraffin formulation chemicals anchored in German and US specialty chemical production. Single-source vulnerability concentrates in advanced thermal sensor procurement, exposing lead times to semiconductor foundry allocation cycles. Distribution runs through hospital procurement consortia in Germany, GPO contracts in the United States, and regional distributor networks across Asia-Pacific secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue embedding center market sits in a cyclical recovery phase driven by replacement demand from aging analog installations in European hospital networks. Equipment upgrade cycles accelerate as EU MDR traceability mandates force embedded serialization system adoption.
For Market Incumbents: Build switching-cost moats through multi-site service contract aggregations across Germany's centralized histopathology networks. Deepen backward integration into precision temperature-control module production to reduce East Asian component dependency. Cryostat substitution for intraoperative diagnostics threatens paraffin embedding volumes; counter through programmable thermal profiling R&D investments that reduce block-quality variability.
For New Entrants and Emerging Players: Establish a beachhead in India's consolidating commercial histopathology chains through localized assembly partnerships in Hyderabad's medical devices cluster. The diagnostic laboratory segment offers the most penetrable entry point given fragmented incumbent service coverage. A go-to-market angle anchored to CDSCO registration pathway expertise accelerates hospital pathology department access.
For Investors and Strategic Acquirers: EU MDR full implementation reshapes the acquisition landscape toward vendors with established notified body conformity assessment pathways. Long-term viability centers on service contract renewal rates rather than capital equipment placement velocity. Target acquisition archetypes include independent service organizations with multi-vendor maintenance capabilities. The signal to watch is CLIA laboratory construction permit issuance velocity in Texas and North Carolina.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway Investment | Notified body technical file maintenance secures hospital procurement committee prioritization in France and Italy. |
| Programmable Thermal Profiling Development | Multi-stage ramp protocols displace fixed-temperature analog systems in German university hospital replacement cycles. |
| India Localization Partnership | Hyderabad assembly operations reduce landed cost exposure for Mumbai and Bangalore diagnostic chains. |
| Service Contract Unbundling | Preventive maintenance separation captures aftermarket revenue from OEM-retained corrective repair models. |
| Integrated Workflow Bundling | Embedding module pairing with automated tissue processors commands premium positioning in US CLIA greenfield construction. |
Research Methodology
The analysis maps embedding modules, cryostats, tissue processors, and microtomes, each validated through histotechnician supervisors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Primary interviews with equipment manufacturers and diagnostic laboratory operators combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and customs trade records. Bottom-up equipment placement tallies and top-down market sizing triangulate volume estimates.
Assumptions held fixed include regulatory harmonization timelines between FDA 21 CFR Part 820 and EU MDR quality management standards, while tariff exposure on East Asian components and cryostat substitution rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, application context, end-user category, and regional regulatory cluster. CAGRs were derived from replacement cycle velocity analysis and greenfield laboratory construction permit tracking, with biopsy volume growth from cancer screening programs and EU MDR equipment upgrade mandates serving as core demand inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or East Asian logistics disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pacing and component supply stability. Quarterly review of CLIA permit issuance, EU notified body capacity allocation, and precision heating element lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Medical Pendant Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Syringeless Injector Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Global Keratometers Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Alpha Emitter Market