
 Europe Surface Analysis Market | 2026-2036
Europe Surface Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surface Analysis Market Foresight
Germany's precision instrumentation corridor is fragmenting as domestic and foreign vendors expand service centers and application labs. Thermo Fisher Scientific Inc. leverages its mass spectrometry portfolio to dominate pharmaceutical surface characterization workflows. Bruker Corporation anchors its position through atomic force microscopy systems tailored to semiconductor failure analysis. Oxford Instruments plc differentiates via plasma etch and deposition metrology integrated with surface science solutions.
Europe Surface Analysis encompasses the instrumental examination of material surfaces and interfaces to determine elemental composition, chemical state, topographic structure, and thin-film properties at nanometer to micrometer resolution. Techniques such as X-ray photoelectron spectroscopy operate under ultra-high vacuum conditions below 10⁻⁹ mbar to detect binding energy shifts of surface atoms. Spectroscopy commands the largest installed base across European industrial labs due to its versatility in elemental and molecular identification. Microscopy segments grow fastest in semiconductor and battery material applications where nanoscale defect mapping determines product yields. Chromatography paired with surface desorption methods captures expanding margin pools in environmental and food safety testing where regulatory traceability requirements intensify.
EMA documentation standards for drug-device combination products mandate surface chemistry verification, while REACH enforcement through ECHA drives substitution testing for restricted substances in coatings and adhesives. CE marking under the EU MDR compels medical device manufacturers to validate surface biocompatibility through accredited analytical protocols. Stakeholders must monitor how the EU AI Act's risk classification framework affects automated surface inspection systems deployed in critical manufacturing environments.
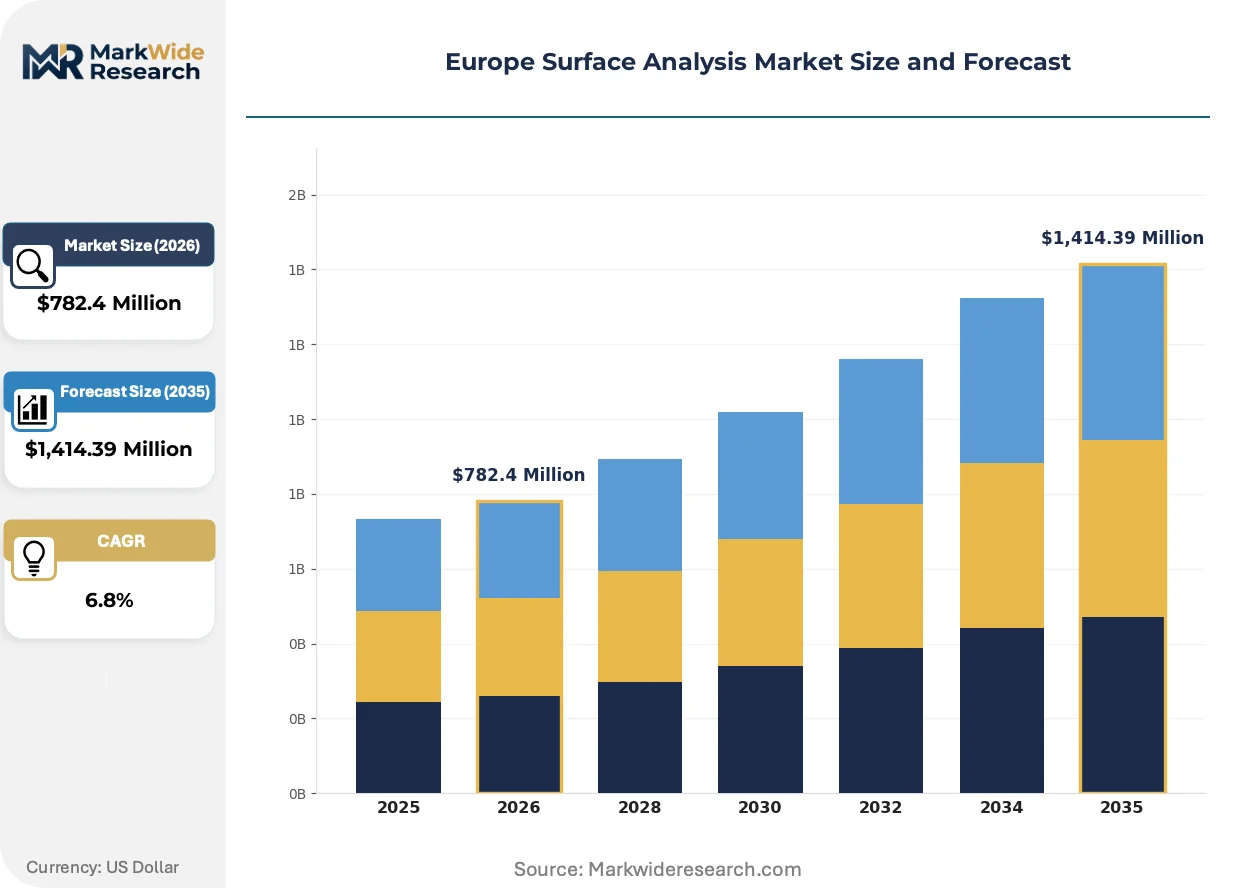
Market Dynamics
REACH enforcement through ECHA is compressing substitution timelines for restricted substances, forcing coatings and adhesive manufacturers to accelerate surface chemistry verification while semiconductor fabs in Germany expand metrology capacity to capture yield-critical defect data.
Growth Catalysts
- EMA Documentation Standards:Drug-device combination products now mandate surface chemistry verification, pulling pharmaceutical manufacturers toward accredited analytical protocols and expanding contract lab volumes.
- EU Green Deal Material Mandates:Circular economy requirements intensify material characterization for recycled content verification, driving X-ray photoelectron spectroscopy adoption in polymer and composite processing.
- Toulouse Aerospace Cluster Concentration:France's satellite and aircraft manufacturing hub generates concentrated demand for thin-film analysis supporting thermal barrier coating qualification.
Market Restraints
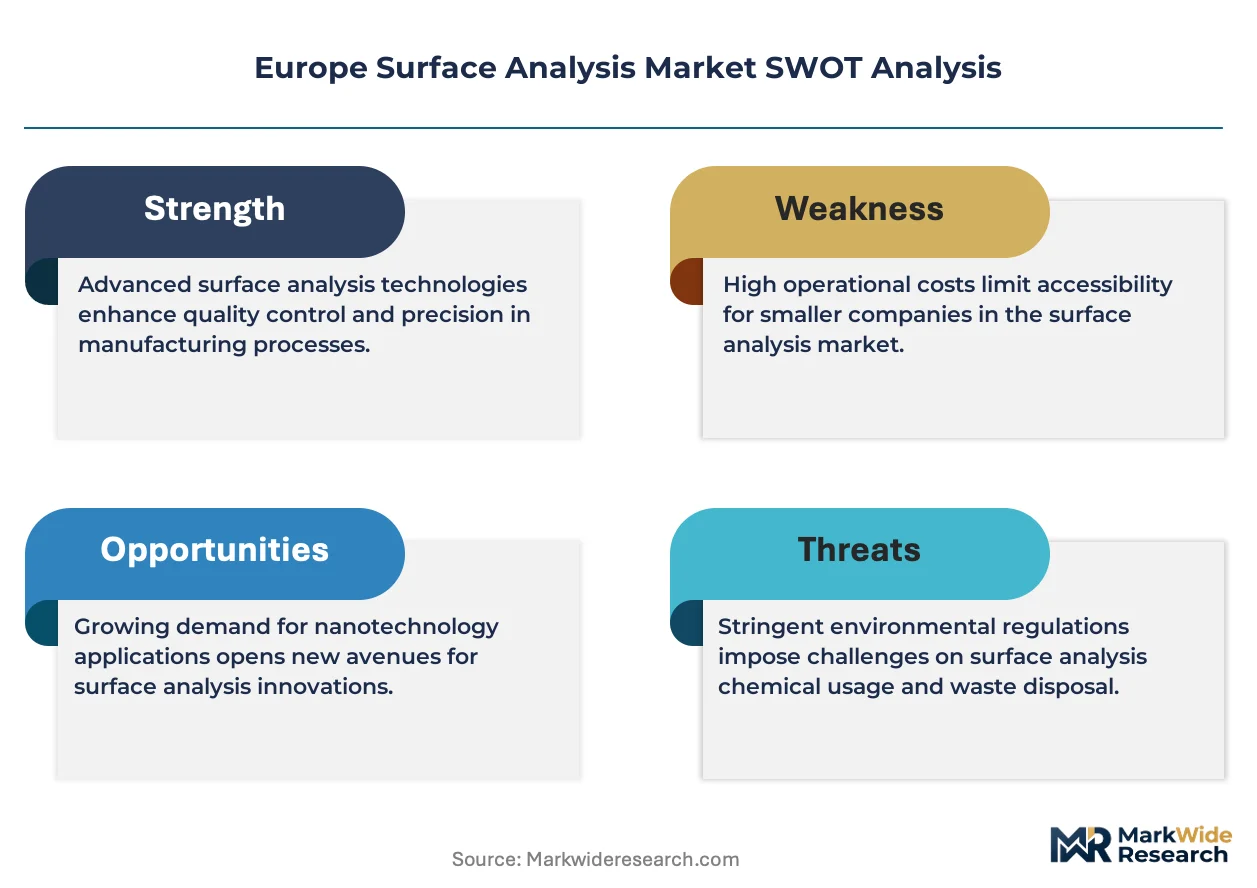
- Ultra-High Vacuum Infrastructure Costs:XPS and SIMS systems require facility investments exceeding standard analytical lab budgets, concentrating capability among well-capitalized industrial users and national research centers.
- Helium Supply Concentration Risk:Leak detection and cryogenic sample preparation depend on helium sourcing from Algeria and Qatar, exposing European operators to geopolitical supply interruptions.
- Technical Limitation in Hydrated Samples:UHV conditions preclude direct analysis of biological tissues and hydrogels, restricting pharmaceutical and medical device applications to dried or frozen preparations.
Strategic Opportunities
- Poland and Czech Republic Manufacturing Expansion:Automotive battery cell production in Central Europe creates greenfield demand for electrode surface analysis supporting solid-electrolyte interphase characterization.
- Ambient Pressure XPS Convergence:Integration of differential pumping systems with traditional spectrometry opens pharmaceutical and food packaging applications previously excluded by vacuum constraints.
- EU AI Act Automated Inspection Pathway:Risk classification frameworks for manufacturing AI create compliance-driven demand for validated surface inspection algorithms in critical device production.
Industry Challenges
- Surface Science Talent Pipeline:Vacuum technology and electron optics expertise concentrates among aging specialists in Germany and the Netherlands, constraining service center expansion and training throughput.
- CE Marking Timeline Compression:EU MDR technical documentation requirements extend surface biocompatibility validation cycles, delaying product launches for mid-sized device manufacturers without captive analytical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surface Analysis Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,414.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectroscopy, Microscopy, Chromatography, X-Ray Diffraction Technology: Atomic Force, Scanning Electron, Water Contact Angle, Induced Coupled Plasma End User: Aerospace, Consumer Electronics, Pharmaceuticals, Material Science Application: Quality Control, Research & Development, Process Improvement, Failure Analysis |
| Companies Covered | Thermo Fisher Scientific Inc., Bruker Corporation, Agilent Technologies, Inc., Horiba, Ltd., JEOL Ltd., Oxford Instruments plc, Shimadzu Corporation, Carl Zeiss AG, KLA Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surface Analysis Market Shifts & Advancements
Digital twin architectures are virtualizing instrument control and data interpretation, compressing the expertise barrier that historically concentrated surface analysis within elite technical centers.
Time-of-flight secondary ion mass spectrometry is virtualizing molecular imaging workflows through automated spectral library matching and machine-learning-based fragmentation prediction. Battery material suppliers in Scandinavia are adopting these systems at accelerated procurement cycles to map lithium distribution across electrode cross-sections. This capability is virtualizing the traditional electron microscopy bottleneck for nanoscale chemical mapping, enabling faster iteration on electrolyte formulations.
REACH authorization procedures through ECHA are tightening data requirements for substances of very high concern in surface coatings. Industrial paint and adhesive formulators must now submit analytical evidence of surface composition and leaching behavior. Automotive OEMs in Stuttgart and Wolfsburg are responding by integrating XPS and ToF-SIMS into incoming material qualification protocols, shifting compliance burden upstream to coating suppliers.
Service unbundling is fragmenting traditional capital-intensive purchasing models. Pharmaceutical and aerospace buyers now procure surface analysis through regional application laboratories rather than acquiring captive instrumentation. This pattern concentrates most visibly in France's medical device corridor around Lyon, where contract analytical services absorb validation work previously performed in-house by manufacturers seeking to preserve capital for core production assets.
Europe Surface Analysis Market Segmentation
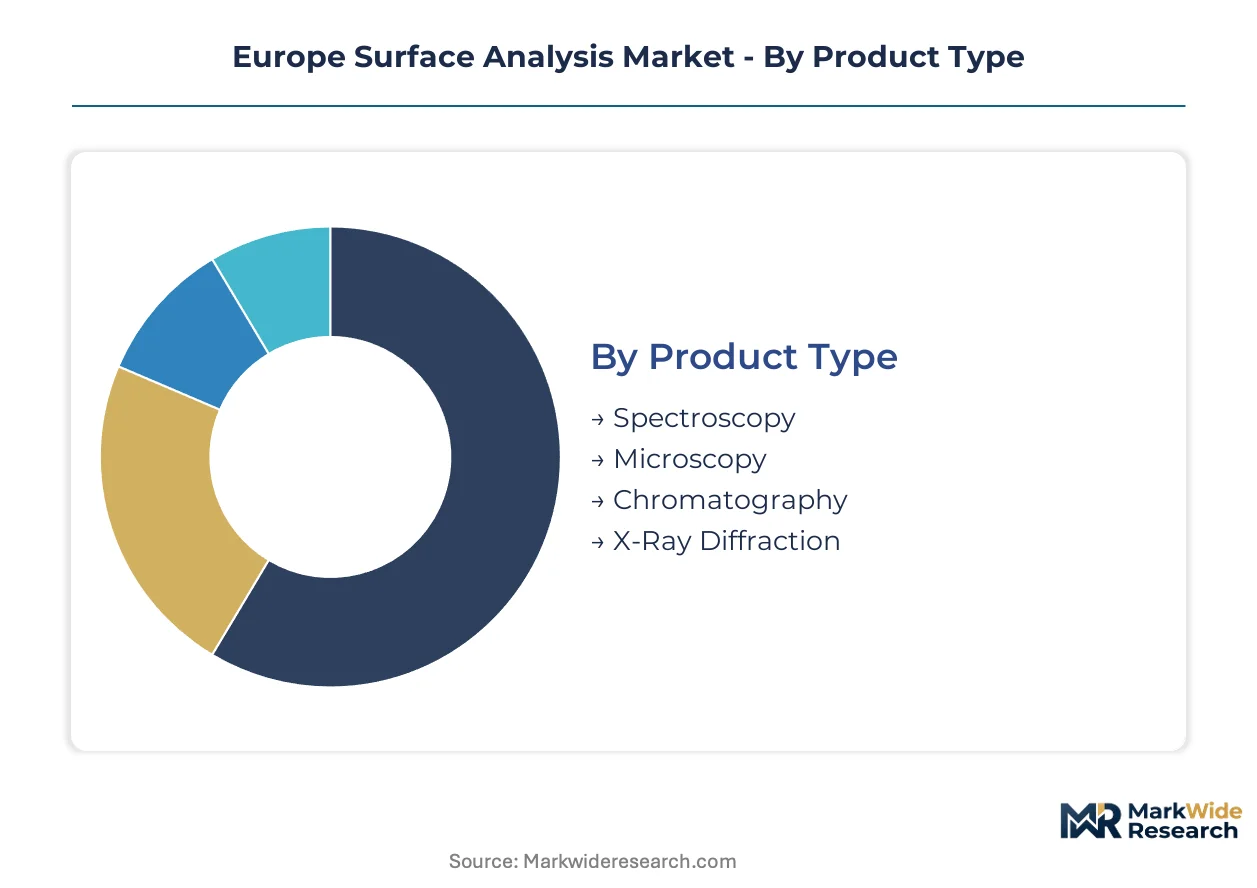
Surface analysis instrumentation serves distinct technical workflows across European industrial and research environments. Segment boundaries reflect capital intensity, vacuum infrastructure requirements, and regulatory compliance burdens that reshape procurement patterns.
Product Type:
Cost tiers separate laboratory-grade systems from portable or benchtop configurations, with vacuum infrastructure demands driving the steepest price stratification.
- Spectroscopy:X-ray photoelectron and time-of-flight secondary ion mass spectrometry systems operate below 10⁻⁹ mbar vacuum. German semiconductor fabs and French aerospace qualification labs concentrate demand for binding energy analysis of thin-film coatings.
- Microscopy:Atomic force and scanning probe variants map nanoscale topography without electron beam damage. Battery electrode manufacturers in Scandinavia drive fastest expansion for solid-electrolyte interphase characterization.
- Chromatography:Surface desorption methods paired with mass detection serve environmental compliance testing. ECHA REACH enforcement expands contract lab volumes for restricted substance verification.
- X-Ray Diffraction:Phase identification and residual stress measurement in metallic components. Czech and Polish automotive suppliers adopt for quality assurance of heat-treated powertrain parts.
Spectroscopy commands the established base. The steepest expansion runs through Microscopy.
Technology:
Application requirements dictate resolution, sample preparation burden, and ambient versus vacuum operating conditions.
- Atomic Force:Sub-nanometer height resolution maps surface roughness and defect morphology. Bruker Corporation anchors European positioning through semiconductor failure analysis workflows.
- Scanning Electron:Secondary and backscattered electron imaging with energy-dispersive X-ray attachment for elemental mapping. Toulouse aerospace cluster drives thermal barrier coating qualification demand.
- Water Contact Angle:Goniometric measurement of surface wettability for biocompatibility validation. Lyon medical device corridor concentrates outsourcing to contract analytical services.
- Induced Coupled Plasma:Bulk elemental analysis of surface residues and leachates. REACH substitution testing requirements expand adoption among coatings and adhesive formulators.
Atomic Force retains the deepest penetration in failure analysis. Scanning Electron gains share fastest in coating qualification.
End User:
Customer type determines capital availability, captive versus outsourced analytical capacity, and regulatory documentation intensity.
- Aerospace:Thermal barrier coating and turbine blade qualification mandates surface chemistry verification. France's satellite manufacturing hub concentrates demand for thin-film analysis.
- Consumer Electronics:Miniaturization drives nanoscale defect mapping for yield protection. German precision manufacturing corridor fragments across domestic and foreign vendor service centers.
- Pharmaceuticals:EMA documentation standards for drug-device combinations mandate surface characterization. Service unbundling shifts validation work to regional application laboratories.
- Material Science:Polymer and composite processing for recycled content verification under EU Green Deal circular economy requirements. X-ray photoelectron spectroscopy adoption accelerates for contamination detection.
Pharmaceuticals anchors the revenue base. Material Science expands most quickly on circular economy compliance.
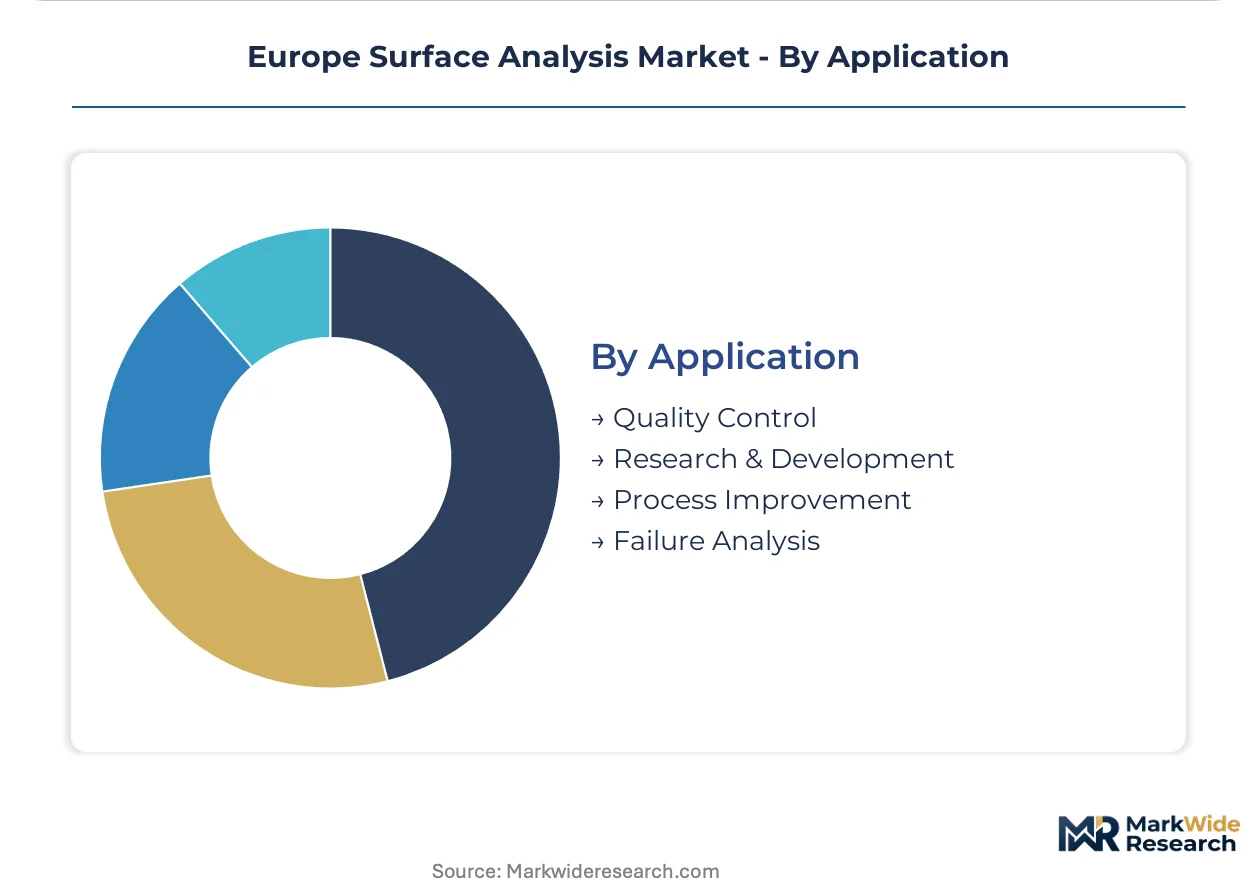
Application:
Volume and margin profiles diverge between routine quality assurance and high-value failure investigation or regulatory submission work.
- Quality Control:Incoming material qualification and production lot release testing. Stuttgart and Wolfsburg automotive OEMs integrate XPS into supplier coating verification protocols.
- Research & Development:Formulation iteration and new product introduction support. Battery material suppliers in Scandinavia accelerate procurement for electrolyte development.
- Process Improvement:Manufacturing yield enhancement through defect root cause analysis. Digital twin architectures compress expertise barriers for distributed technical centers.
- Failure Analysis:Warranty claim investigation and litigation support. CE marking under EU MDR extends surface biocompatibility validation cycles for mid-sized device manufacturers.
Quality Control captures the largest transaction volume. Failure Analysis delivers the highest margin per sample.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors and service providers cluster along Germany's precision manufacturing corridor, with application laboratories multiplying in France and Central European battery production zones drawing new analytical capacity.
Germany
Semiconductor fabs in Dresden and Munich expand metrology budgets for yield-critical defect detection. REACH enforcement through ECHA accelerates substitution testing for restricted substances in automotive coatings. Stuttgart and Wolfsburg automotive OEMs integrate XPS verification into supplier qualification protocols.
France
Toulouse's satellite and aircraft manufacturing hub concentrates demand for thermal barrier coating analysis. ANSM documentation requirements for drug-device combinations mandate surface biocompatibility validation. Lyon's medical device corridor shifts validation work to contract analytical services, unbundling traditional capital-intensive purchasing models.
United Kingdom
CE marking under the EU MDR extends surface validation cycles for mid-sized device manufacturers. Oxford and Cambridge research clusters maintain national center status for electron optics expertise. London-based contract labs absorb pharmaceutical surface characterization outsourcing from continental European manufacturers.
Poland
Automotive battery cell production in Silesia and Lower Silesia creates greenfield demand for electrode surface analysis. EU Green Deal circular economy requirements drive recycled content verification in polymer processing. Kraków and Wrocław technical universities feed vacuum technology training pipelines for regional service center expansion.
Sweden
Battery material suppliers accelerate ToF-SIMS procurement for solid-electrolyte interphase characterization. ECHA authorization procedures tighten data requirements for coating substances of very high concern. Scandinavia's electrolyte formulation R&D clusters adopt automated spectral library matching for faster iteration cycles.
Europe Surface Analysis Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in vacuum technology and electron optics. The vendor landscape organizes around three archetypes: diversified analytical conglomerates with mass spectrometry portfolios, dedicated surface science houses with atomic force microscopy specialization, and metrology-integrated plasma processing vendors. Consolidation pressure runs through service center expansion and application laboratory multiplication rather than horizontal mergers.
Among US-based diversified analytical conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. represent the platform-integrator archetype with broad spectroscopy portfolios. Bruker Corporation and Oxford Instruments plc exemplify the dedicated instrumentation specialist model, with the former anchoring atomic force microscopy positioning and the latter occupying plasma etch-integrated metrology. These four entities collectively illustrate how competitive positioning fragments across technology specialization rather than geographic coverage.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| Agilent Technologies, Inc. |
| Horiba, Ltd. |
| JEOL Ltd. |
| Oxford Instruments plc |
| Shimadzu Corporation |
| Carl Zeiss AG |
| KLA Corporation |
| Others |
Supply & Pricing Matrix
Helium sourcing from Algeria and Qatar concentrates margin risk for European surface analysis operators, pushing procurement costs toward ultra-high vacuum system tiers where captive gas recovery systems command premium positioning.
Pricing Analysis
REACH authorization through ECHA dictates the pricing tier structure across European surface analysis markets, separating validated compliance-grade services from standard analytical offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with CE-marked biocompatibility validation capturing the highest margins. Price differentiation hinges on vacuum infrastructure grade and ECHA documentation depth. Cost compression in mid-tier spectroscopy services is intensifying because automotive OEMs are pushing coating verification burdens upstream to suppliers. Small contract laboratories in Central Europe exhibit the greatest price sensitivity, while Toulouse aerospace qualification labs show minimal elasticity for thermal barrier coating analysis.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for electron optics and vacuum pump components, forcing European vendors to diversify sourcing. Manufacturing concentrates in Germany, Japan, and the United States for precision ionization sources and detector assemblies. Raw material dependencies span high-purity aluminum for vacuum chambers, rare-earth magnets for electron beam focusing, and specialized ceramics for sample stages. Single-source vulnerability persists for cryogenic cooling systems used in SIMS sample preparation. Distribution runs through authorized service centers and direct OEM relationships, with application laboratories increasingly procuring through regional rental and service contracts rather than capital purchase.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin architectures are transforming surface analysis into a platform ecosystem where instrument control, spectral interpretation, and compliance documentation interoperate through cloud-native middleware.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance algorithms into installed XPS and ToF-SIMS bases, locking in multi-year service contracts before ambient pressure spectrometry commoditizes traditional vacuum-dependent workflows. Expand application laboratory footprints in Poland and the Czech Republic to capture battery electrode analysis demand before regional competitors establish vacuum technology training pipelines. Vertical integration into helium recovery and recycling systems addresses supply concentration risk while creating captive margin pools. For New Entrants and Emerging Players: Build out ambient pressure XPS capabilities targeting pharmaceutical and food packaging verticals excluded by ultra-high vacuum constraints, where EMA and EFSA documentation requirements create greenfield demand. Concentrate initial deployment in Lyon's medical device corridor, where service unbundling has shifted validation work away from captive instrumentation. Pursue partnership-based go-to-market models with existing contract analytical networks rather than direct capital sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed analytical service platforms that consolidated regional laboratories during the previous decade. Five-to-ten-year viability hinges on successful transition from project-based revenue to recurring platform subscriptions. Target acquisition archetypes combine established ECHA compliance workflows with nascent AI-driven spectral interpretation capabilities. Monitor EU AI Act implementation timelines as the critical inflection signal for automated inspection system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Application Laboratory Multiplication | Service unbundling in France and Central Europe shifts capital burdens from manufacturers to regional analytical providers. |
| Helium Recovery System Integration | Captive gas recycling addresses Algeria-Qatar supply concentration while creating differentiated service tier pricing. |
| Ambient Pressure XPS Development | Differential pumping expansion opens pharmaceutical and food packaging segments previously excluded by vacuum constraints. |
| Digital Twin Architecture Deployment | Virtualized instrument control compresses expertise barriers and enables distributed technical center expansion. |
| AI-Validated Inspection Algorithm Certification | EU AI Act risk classification creates compliance-driven demand for automated surface inspection in critical device production. |
Research Methodology
Initial hypotheses were tested against primary input from vacuum technology specialists, semiconductor metrology directors, pharmaceutical regulatory affairs leads, and contract analytical laboratory managers and refined through secondary validation against ECHA authorization databases, EMA drug-device combination guidance documents, EU Green Deal circular economy implementation reports, and SEC filings from listed analytical instrumentation vendors. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital expenditure disclosures ensured convergence.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user industry, and application workflow, with additional granularity on vacuum infrastructure tier and regulatory documentation intensity. CAGRs were derived from weighted average growth rates across segment-level drivers. Industry-specific forecast inputs incorporated semiconductor fab metrology budget trajectories and REACH substitution timeline compression.
Stress conditions across helium supply interruption scenarios, EU AI Act implementation delays, and ambient pressure technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Macroeconomic contraction, regulatory enforcement deviation, or breakthrough ambient pressure resolution advances would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
ICP-MS System Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Abbe Refractometers Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Portable Chromatography Systems Market