
 Failure Analysis Market | 2026-2036
Failure Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Failure Analysis Market Intelligence
Market Overview
Multi-source procurement of electron microscopy and spectroscopy services is shifting toward captive in-house laboratories at large semiconductor foundries. Thermo Fisher Scientific leverages its dual-source instrument and reagent portfolio to anchor long-term service contracts with memory chip producers. JEOL Ltd. competes through specialized transmission electron microscopy platforms optimized for atomic-resolution defect imaging. Bruker differentiates via X-ray fluorescence and mass spectrometry systems that sustain recurring consumable revenue streams.
Failure analysis encompasses the systematic investigation of component, material, or system malfunctions using electron microscopy, spectroscopy, and simulation tools to identify physical defects, contamination sources, or design flaws at resolutions approaching single-angstrom precision. Its primary purpose centers on preventing recurrence in safety-critical applications across aerospace propulsion systems, automotive battery packs, and sub-10nm integrated circuits. Root cause analysis techniques command the largest technique share due to mandatory deployment in aviation accident investigations under FAA and EASA protocols, while fault tree analysis grows fastest in automotive functional safety assessments aligned with ISO 26262. Electronics industry verticals generate the highest absolute spending on failure analysis services, though aerospace applications retain the strongest margin pools given certification-driven pricing tolerance and limited qualified laboratory capacity.
FDA medical device reporting requirements, EPA toxic substance release obligations, and EU MDR post-market surveillance mandates collectively expand the documentary burden for analytical traceability in regulated industries. China's NMPA and SAMR have tightened GB standards for lithium-ion battery failure documentation, redirecting supplier investment toward domestic analytical capacity. Stakeholders must monitor whether export control expansions on electron beam lithography and plasma etching equipment constrain instrument availability for failure analysis laboratories serving defense-adjacent supply chains.
Market Dynamics
Semiconductor node shrinkage below 3nm is forcing foundries to rebuild analytical infrastructure around atomic-resolution defect detection, compressing equipment refresh cycles and concentrating procurement power among Taiwan and South Korean memory producers.
Growth Catalysts
- Aviation Safety Mandates:FAA and EASA protocols mandate root cause analysis deployment for all commercial aircraft accident investigations, creating institutional demand for certified analytical capacity.
- Battery Traceability Requirements:China's NMPA and SAMR tightened GB standards for lithium-ion battery failure documentation, redirecting supplier investment toward domestic analytical laboratories.
- Automotive Functional Safety:ISO 26262 alignment drives fault tree analysis adoption across electric vehicle battery pack and autonomous system validation programs.
Market Restraints
- Helium Supply Concentration:Cryogenic electron microscopy depends on helium-3 and helium-4 sourced primarily from Qatar and Russia, exposing operators to geopolitical price volatility and allocation constraints.
- Instrument Import Controls:Expanding export restrictions on electron beam lithography and plasma etching equipment constrain instrument availability for defense-adjacent failure analysis laboratories.
- Consumable Cost Structure:X-ray fluorescence and mass spectrometry systems require proprietary reagent streams that lock operators into single-source supply relationships with limited pricing leverage.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component production are creating demand for localized failure analysis capacity serving contract manufacturers in Karnataka and Tamil Nadu.
- EU Green Deal Alignment:CSRD reporting requirements and REACH material traceability obligations expand documentary burden for analytical traceability in regulated European industries.
- AI-Assisted Defect Recognition:Machine learning convergence with transmission electron microscopy is automating atomic-resolution image interpretation, compressing analysis timelines for high-volume memory production.
Industry Challenges
- Specialized Technician Scarcity:Operation of cryo-EM and atom probe tomography systems requires hybrid skill sets spanning materials science, vacuum physics, and computational imaging that outpace current training pipeline output.
- Certification Timeline Compression:FAA DER and EASA Part 21J designee qualifications for analytical laboratories face 18-24 month approval windows that constrain capacity expansion for aviation safety investigations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Failure Analysis Market |
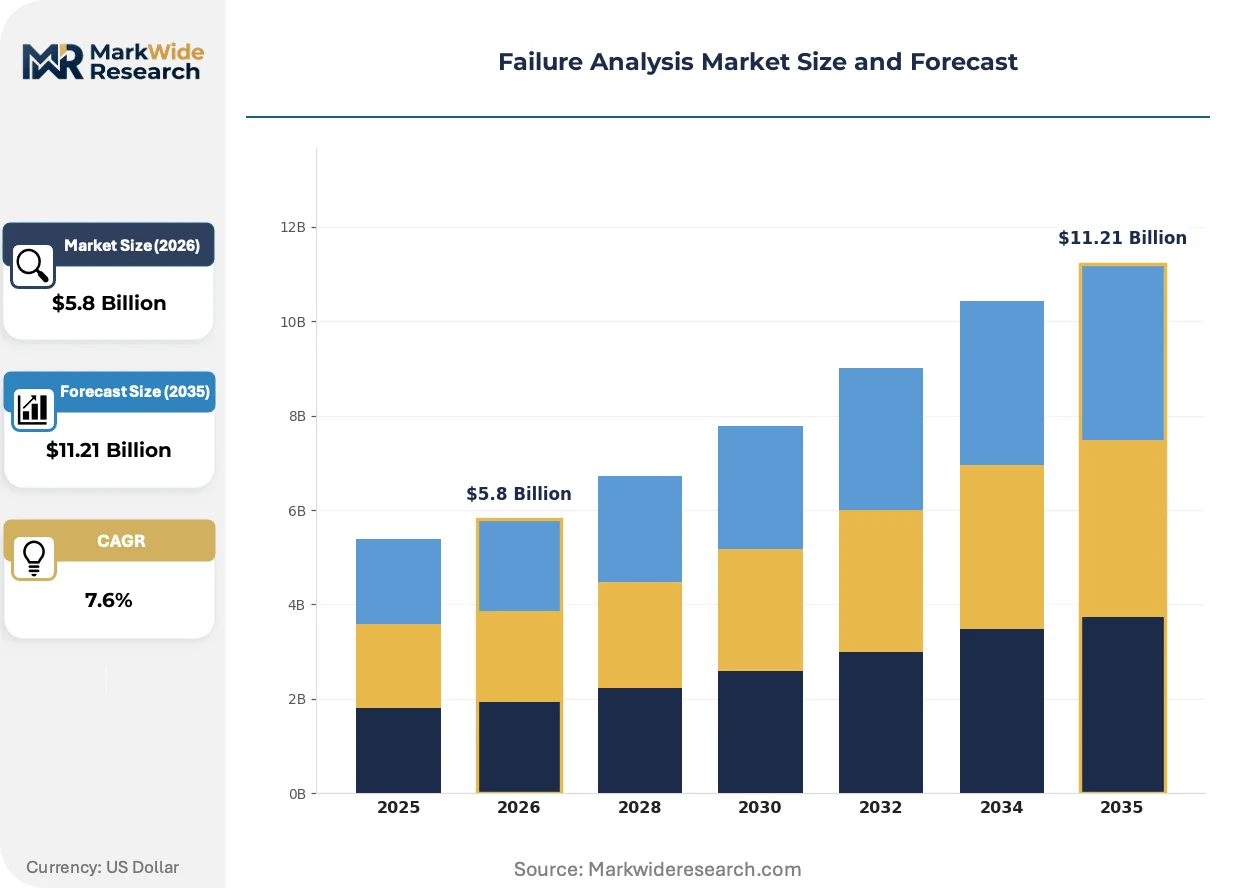
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technique: Root Cause Analysis, Fault Tree Analysis, Fishbone Diagram, Pareto Analysis Industry: Aerospace, Automotive, Electronics, Manufacturing Application: Quality Control, Product Development, Process Improvement, Compliance Component: Hardware, Software, Systems, Services |
| Companies Covered | Thermo Fisher Scientific, Hitachi High-Technologies Corporation, JEOL Ltd., Bruker, HORIBA Ltd., Carl Zeiss, TESCAN ORSAY HOLDING, Agilent Technologies, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Failure Analysis Market Strategic Shifts & Innovations
Atomic-scale imaging capabilities are compressing the boundary between physical failure analysis and computational simulation, enabling predictive defect modeling before fabrication rather than post-mortem investigation.
Cryogenic electron microscopy is overtaking room-temperature transmission electron microscopy for sub-2nm node defect characterization. Samsung and TSMC have deployed cryo-EM workflows for gate-all-around transistor failure isolation. The technology is overtaking established thermal protocols because beam-induced specimen damage at atomic resolution renders conventional methods unreliable for next-generation architectures.
REACH substance restriction expansions are forcing electronics manufacturers to requalify solder alloys, underfill materials, and die-attach compounds for analytical compatibility. ECHA's 2024 candidate list updates added two brominated flame retardants commonly used in PCB substrates. Aerospace cable harness producers in Germany and France face reformulation costs exceeding analytical revalidation budgets.
Captive laboratory buildouts at foundry operators are consolidating previously fragmented service procurement. Memory chip producers in Hsinchu and Pyeongtaek now operate multi-instrument suites that internalize 60-70% of analytical volume previously outsourced to third-party laboratories. Taiwan's semiconductor cluster exhibits the most pronounced vertical integration of analytical capacity.
Failure Analysis Market Segmentation
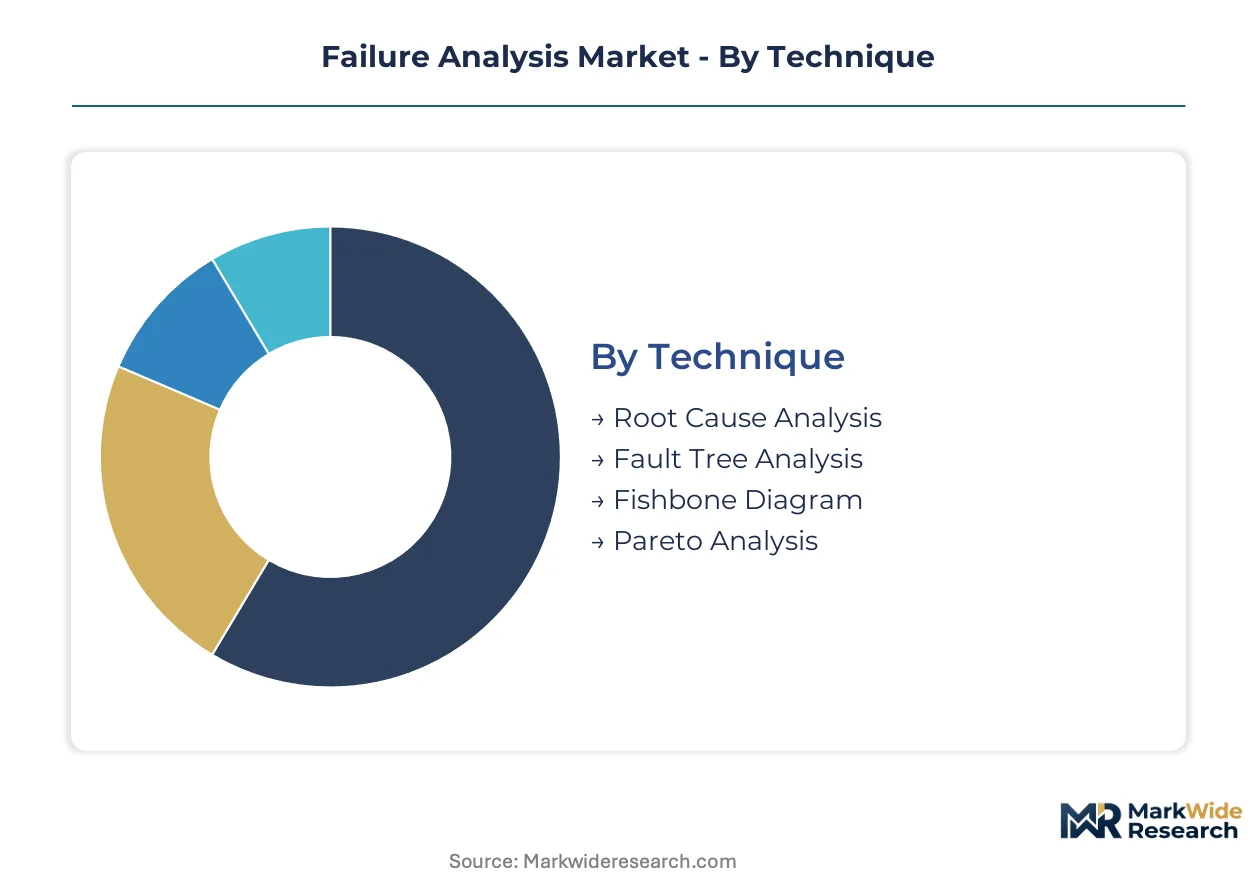
Semiconductor foundries, battery pack producers, and aviation OEMs deploy distinct analytical protocols based on regulatory exposure and defect resolution requirements. Segmentation reveals how procurement patterns diverge between captive laboratories at memory chip manufacturers and third-party service providers serving fragmented industrial supply chains.
Technique:
Regulatory mandates and resolution requirements differentiate buyer investment intensity across analytical methodologies.
- Root Cause Analysis:Systematic investigation tracing failure origins through physical inspection, material characterization, and process documentation. FAA and EASA protocols mandate deployment for commercial aviation accident investigations, institutionalizing demand at certified laboratories with DER-qualified personnel. Volume sits with root cause analysis; growth tilts toward fault tree analysis.
- Fault Tree Analysis:Boolean logic-based methodology mapping component-level failures to system-level malfunctions using probabilistic risk assessment. ISO 26262 functional safety assessments for electric vehicle battery management systems and autonomous driving platforms are accelerating adoption at automotive tier-1 suppliers in Germany and Japan.
- Fishbone Diagram:Cause-and-effect visualization categorizing failure sources across manpower, method, material, machine, measurement, and environment dimensions. Electronics contract manufacturers in Taiwan employ this technique for rapid yield excursion response during high-volume memory production.
- Pareto Analysis:Statistical prioritization identifying the vital few defect categories driving majority failure rates. Industrial equipment producers apply this for resource allocation in preventive maintenance programs.
Adoption concentrates where regulatory documentation requirements intersect with high-volume production environments.
Industry:
Margin structure and certification burden shape procurement decisions across vertical applications.
- Electronics:Sub-3nm node characterization demands atomic-resolution imaging infrastructure at captive foundry laboratories. TSMC and Samsung internalize 60-70% of analytical volume previously outsourced, compressing third-party service pricing in Hsinchu and Pyeongtaek clusters. Electronics commands the highest absolute spending; aerospace retains the strongest margin pools.
- Aerospace:Propulsion system and airframe investigations require FAA DER and EASA Part 21J laboratory qualifications with 18-24 month approval timelines. Limited certified capacity supports certification-driven pricing tolerance for accident investigation and airworthiness directive compliance.
- Automotive:Battery pack thermal runaway investigations and functional safety validation drive fault tree analysis adoption. China's NMPA and SAMR tightened GB standards for lithium-ion failure documentation, redirecting supplier investment toward domestic analytical capacity.
- Manufacturing:Process equipment and industrial automation failure investigations emphasize rapid turnaround for production line restoration. Metal fabrication and chemical processing facilities prioritize cost-efficient third-party service relationships.
Electronics generates the largest procurement volume; aerospace sustains the highest service premiums.
Application:
Timing within product lifecycle determines analytical methodology selection and budget allocation.
- Quality Control:In-line inspection and lot release testing using X-ray fluorescence and mass spectrometry for material verification. Memory chip producers deploy automated defect recognition to compress analysis timelines for high-volume gate-all-around transistor validation.
- Product Development:Pre-production failure mode identification through accelerated life testing and design of experiments. Cryogenic electron microscopy enables atomic-resolution defect isolation for next-generation node qualification before volume manufacturing commitment.
- Process Improvement:Yield enhancement initiatives correlating analytical findings to fabrication parameter optimization. Foundry operators rebuild analytical infrastructure around atomic-resolution detection as node shrinkage compresses equipment refresh cycles.
- Compliance:Regulatory documentation for FDA medical device reporting, EPA toxic substance release obligations, and EU MDR post-market surveillance. REACH substance restriction expansions force solder alloy and PCB substrate requalification for analytical compatibility.
Quality control absorbs the largest analytical volume; compliance applications are expanding most quickly.
Component:
Physical versus intangible failure modes dictate instrumentation requirements and technician skill profiles.
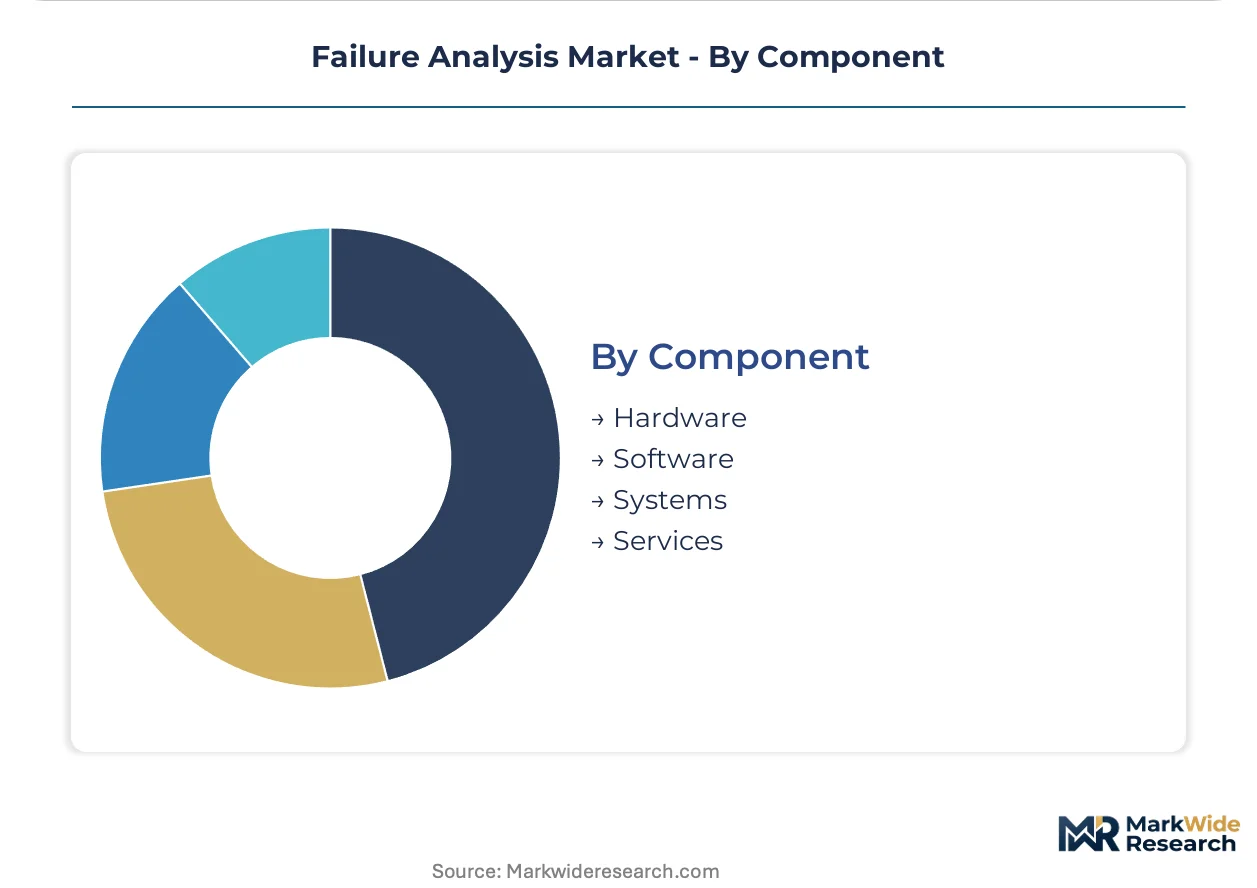
- Hardware:Physical component inspection using electron microscopy, spectroscopy, and mechanical testing. Atomic-scale imaging capabilities compress the boundary between physical analysis and computational simulation for predictive defect modeling.
- Software:Code-level failure tracing and algorithmic validation for autonomous system decision logic. ISO 26262 alignment drives analytical investment across electric vehicle perception and planning software stacks.
- Systems:Integrated hardware-software interaction analysis for complex electromechanical assemblies. Battery pack failures require simultaneous electrical, thermal, and mechanical characterization.
- Services:Third-party analytical capacity provision including instrument operation, interpretation, and regulatory documentation. Captive laboratory buildouts at foundry operators consolidate previously fragmented procurement patterns.
Hardware analysis commands the largest installed instrument base; software failure investigation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium-3 and helium-4 sourcing from Qatar and Russia anchors cryogenic electron microscopy operations worldwide, concentrating analytical capacity near semiconductor fabrication clusters in East Asia, North America, and Western Europe.
United States
FAA DER-qualified laboratories in Arizona and Texas handle commercial aviation accident investigations under mandatory protocols. EPA toxic substance release obligations tighten documentary requirements for analytical traceability in industrial applications. Greater Boston and Silicon Valley clusters concentrate captive electron microscopy infrastructure serving defense-adjacent supply chains facing export control constraints.
Taiwan
TSMC and memory producers in Hsinchu internalize 60-70% of failure analysis volume previously outsourced, compressing third-party service pricing. The country's national semiconductor regulator aligns GB standards with international node shrinkage timelines. Hsinchu Science Park exhibits the most pronounced vertical integration of atomic-resolution analytical capacity globally.
South Korea
Samsung's Pyeongtaek complex deploys cryo-EM workflows for gate-all-around transistor failure isolation below 3nm nodes. SAMR-equivalent standards for lithium-ion battery documentation redirect supplier investment toward domestic analytical laboratories. Seoul Capital Area foundries operate multi-instrument suites that anchor regional procurement power.
Germany
Automotive tier-1 suppliers in Bavaria and Baden-Württemberg adopt fault tree analysis for ISO 26262 functional safety validation of electric vehicle battery packs. REACH substance restriction expansions force solder alloy and PCB substrate requalification for analytical compatibility. Stuttgart and Munich industrial corridors concentrate aerospace cable harness producers facing reformulation cost pressures.
China
NMPA and SAMR tightened GB standards for lithium-ion battery failure documentation, redirecting supplier investment toward domestic analytical capacity. Dual carbon goals accelerate localized electron microscopy infrastructure buildouts. Yangtze River Delta semiconductor clusters in Shanghai and Suzhou expand captive laboratory capacity serving memory and logic chip production.
Failure Analysis Market Key Industry Players
Global majors compete with regional champions across instrument portfolios and service contract structures. The vendor base separates into consolidated instrument manufacturers, diversified analytical service providers, and specialized microscopy platform developers. Three archetypes dominate: dual-source portfolio operators anchoring long-term foundry contracts, atomic-resolution specialists competing on technical specifications, and consumables-driven systems vendors sustaining recurring revenue streams. Competitive moves concentrate on captive laboratory partnerships and AI-assisted defect recognition technology licensing.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Agilent Technologies exemplify dual-source portfolio strategies spanning instruments and reagents. JEOL Ltd. occupies a position among atomic-resolution specialists optimized for transmission electron microscopy platforms. Bruker sits within the systems-driven archetype, differentiating via X-ray fluorescence and mass spectrometry configurations that generate proprietary consumable dependencies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hitachi High-Technologies Corporation |
| JEOL Ltd. |
| Bruker |
| HORIBA Ltd. |
| Carl Zeiss |
| TESCAN ORSAY HOLDING |
| Agilent Technologies |
| Keysight Technologies |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FAA DER-qualified aviation laboratories and commodity electronics service providers manifests simultaneously in pricing premiums and supply chain isolation. Aviation accident investigation capacity commands three-to-five-fold service multiples over industrial third-party providers, while helium-3 sourcing constraints for cryogenic electron microscopy tether analytical infrastructure to Qatar and Russian supply corridors.
Pricing Analysis
Warranty and service bundling separates captive foundry laboratories from third-party service relationships. Project-based pricing dominates aviation and automotive safety investigations where ISO 26262 and FAA documentation requirements mandate dedicated analyst assignment. Price differentiation rests on certification tier and geographic proximity to semiconductor clusters. Cost compression in memory chip foundry services intensifies as TSMC and Samsung internalize analytical volume. Contract manufacturers in Taiwan exhibit highest price sensitivity; aerospace OEMs in Arizona and Texas show lowest sensitivity given mandatory procurement protocols.
Supply Chain Analysis
Logistics and freight costs for liquid helium-3 and helium-4 constrain cryogenic electron microscopy deployment to regions with established cold chain infrastructure. Instrument manufacturing concentrates in Japan, the United States, and Germany. Consumable dependencies include proprietary reagent streams for mass spectrometry and specialized specimen preparation materials. Single-source vulnerability runs through Qatar and Russian helium supply. Distribution feeds from instrument manufacturers through regional service hubs to captive foundry laboratories and third-party providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited FAA DER and EASA Part 21J laboratory capacity props pricing premiums across aviation safety investigations. This supply constraint creates durable margin pools for certified analytical providers.
For Market Incumbents: Cement long-term service contracts with memory chip producers through dual-source instrument and reagent portfolios. Lock in helium supply agreements before allocation constraints intensify. Threat of captive laboratory buildouts at TSMC and Samsung demands accelerated certification investment in automotive functional safety credentials. For New Entrants and Emerging Players: Contract research organizations in India represent the most penetrable channel partner type for localized failure analysis capacity. Target Karnataka and Tamil Nadu electronics manufacturing clusters where PLI scheme incentives create demand without established incumbent relationships. Pursue AI-assisted defect recognition licensing as differentiated entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with atomic-resolution microscopy specialists given cryo-EM displacement of room-temperature protocols. Long-term viability favors laboratories with hybrid FAA-ISO 26262 certification spanning aerospace and automotive verticals. Watch helium supply allocation announcements as inflection indicator for operational cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Agreement | Secures cryo-EM operational continuity against Qatar and Russian allocation volatility. |
| FAA DER Certification Investment | Unlocks aviation accident investigation premiums under mandatory EASA protocols. |
| AI Defect Recognition Licensing | Compresses analysis timelines for TSMC and Samsung gate-all-around transistor validation. |
| India Laboratory Buildout | Captures PLI-driven demand from Karnataka and Tamil Nadu contract manufacturers. |
| Automotive Functional Safety Credentials | Enables ISO 26262 fault tree analysis for German and Japanese tier-1 suppliers. |
Research Approach
Independent corroboration across laboratory operations directors, semiconductor foundry procurement leads, and aviation safety investigators underwrites the qualitative findings. Primary fieldwork engaged electron microscopy technicians, vacuum physics specialists, and regulatory documentation officers at certified facilities in Taiwan, South Korea, Germany, and the United States. Secondary validation drew from FAA accident investigation reports, EASA Part 21J certification databases, NMPA lithium-ion battery standards filings, and SEC instrument manufacturer disclosures. Bottom-up service provider revenue estimates and top-down semiconductor capital expenditure allocations were triangulated to anchor market sizing.
Comparable-period anchoring to historical equipment refresh cycles and node shrinkage timelines structured the projection horizon. The analytical framework modeled technique adoption, industry vertical, application timing, and component type as core segmentation dimensions. CAGRs were derived from correlating foundry capital expenditure trajectories with analytical intensity per wafer layer. Forecast inputs included helium supply allocation patterns and cryo-EM displacement rates for sub-3nm characterization.
Several conditions sit outside the modeled scope, including unforeseen export control expansions on electron beam equipment and abrupt helium supply disruptions. Forecasts reflect assumptions about node shrinkage continuity and regulatory certification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Receptacle Tester Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Mechanical Testing Equipment Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Dosimeter Market
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Humidity Testers Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Coaxial Profile Projectors Market