
 High-Vacuum Gauge Market | 2026-2036
High-Vacuum Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
High-Vacuum Gauge Market Foresight
Digital telemetry integration is reconfiguring how vacuum measurement systems interface with fab control architectures. INFICON Holding AG leverages its ionization gauge portfolio to anchor European semiconductor equipment supply chains. MKS Instruments, Inc. dominates North American pressure measurement through backward integration into sensor fabrication. Pfeiffer Vacuum Technology AG specializes in compact Pirani designs for space-constrained coating systems.
A high-vacuum gauge measures absolute pressure below atmospheric conditions, typically operating in the range of 10⁻³ to 10⁻¹² torr using thermal conductivity, ionization, or capacitive displacement principles. These instruments enable process control in semiconductor etching, thin-film deposition, and particle acceleration by providing real-time feedback to vacuum system controllers. Capacitance manometers command premium positioning due to their gas-independent accuracy in critical semiconductor process steps. Ionization gauges compete aggressively on cost in research laboratory settings where absolute precision requirements are less stringent. Wireless connectivity variants are gaining traction in distributed vacuum networks across pharmaceutical freeze-drying operations.
ISO 3567 calibration protocols and the EU F-Gas Regulation shape gauge design requirements for hermetic sealing integrity and refrigerant containment compatibility. The EPA's NESHAP standards for semiconductor manufacturing impose leak-rate thresholds that directly influence gauge selection in US-based fabs. China's SAMR enforces GB/T national standards for vacuum measurement equipment used in domestic chip fabrication investments. Stakeholders must monitor how regional certification divergence affects cross-border equipment procurement strategies.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are expanding gauge procurement for EUV lithography chambers, creating demand concentration that reshapes supplier allocation and technical roadmaps.
Growth Catalysts
- EU F-Gas Regulation:Hermetic sealing mandates for refrigerant containment are accelerating replacement cycles in European coating facilities, pulling demand for next-generation capacitance manometers.
- EUV lithography chambers:Taiwan and South Korean fabs are scaling ionization gauge deployments to maintain process stability at sub-10⁻⁹ torr operating pressures.
- Digital telemetry integration:Wireless connectivity variants are penetrating pharmaceutical freeze-drying networks, enabling distributed vacuum monitoring without hardwired infrastructure.
Market Restraints
- Tungsten filament supply concentration:Ionization gauge cathode production clusters in Chinese rare-earth processing regions, exposing buyers to export restriction volatility.
- Capacitive displacement cost structure:Ceramic sensor substrates and precision electrode machining keep capacitance manometers priced at multiples of thermal conductivity alternatives.
- REACH material purity thresholds:European compliance requirements for gauge housing alloys are disqualifying legacy suppliers lacking certified supply chains.
Strategic Opportunities
- China domestic chip fabrication:SAMR enforcement of GB/T vacuum measurement standards is creating captive demand for locally certified gauge manufacturers.
- Space-constrained coating systems:Compact Pirani designs are penetrating automotive headlamp metallization lines where chamber footprint limits conventional sensor placement.
- ISO 3567 calibration convergence:Unified protocols across semiconductor and aerospace verticals are enabling gauge platform standardization that reduces SKU complexity.
Industry Challenges
- Vacuum metrology talent scarcity:Specialized calibration technicians with ISO 3567 certification command premium wages, constraining service network expansion.
- Legacy system integration friction:Digital telemetry retrofits face protocol incompatibilities with 1990s-era fab control architectures still operating in mature facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Vacuum Gauge Market |
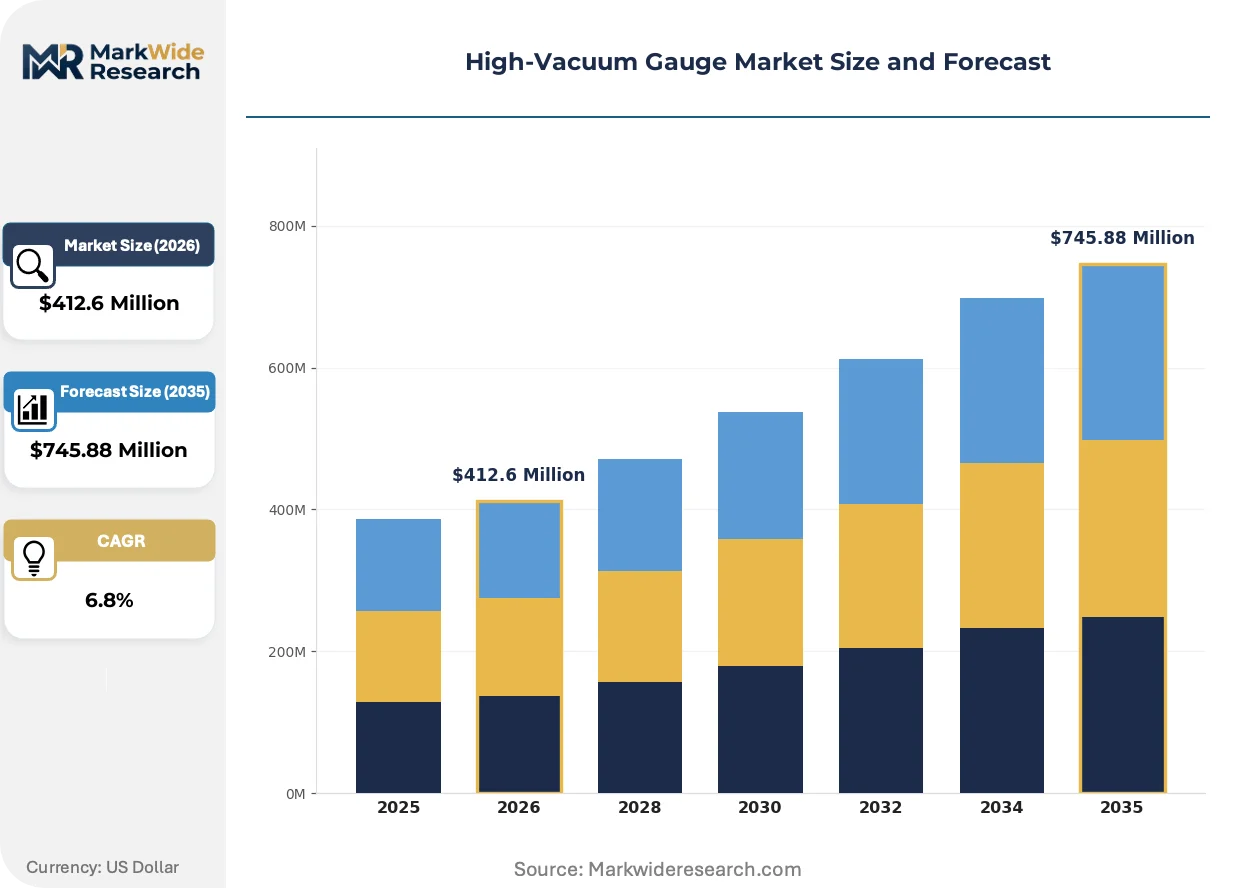
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pirani Gauge, Capacitance Manometer, Ionization Gauge, Thermocouple Gauge Technology: Digital, Analog, Wireless, Semi-Conductor End User: Semiconductor Manufacturing, Research Laboratories, Vacuum Coating, Medical Equipment Application: Pressure Measurement, Leak Detection, System Monitoring, Process Control |
| Companies Covered | MKS Instruments, Inc., INFICON Holding AG, Pfeiffer Vacuum Technology AG, Agilent Technologies, Inc., Edwards Vacuum, LLC, Leybold GmbH, Kurt J. Lesker Company, Brooks Instrument, Thyracont Vacuum Instruments GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Vacuum Gauge Market Shifts & Advancements
Sensor fusion architectures and predictive maintenance algorithms are compressing the functional boundary between vacuum gauges and fab-wide process control systems.
MEMS-based Pirani sensors are virtualizing thermal conductivity measurement by embedding heating and temperature-sensing elements on silicon substrates. Deposition equipment OEMs in Japan and Germany are qualifying these devices for production environments. The technology is virtualizing the traditional glass-envelope gauge supply chain, enabling wafer-scale manufacturing economics.
REACH compliance deadlines for restricted substance thresholds are forcing gauge manufacturers to reformulate brazing alloys and ceramic feedthrough materials. European coating system builders now require full material disclosure documentation upstream of procurement decisions. Ionization gauge suppliers with certified supply chains are capturing specification lock-in from risk-averse buyers.
Service contract unbundling is separating calibration and recertification from original equipment purchases. Pharmaceutical freeze-dryer operators in North America are contracting third-party metrology labs for on-site ISO 3567 verification rather than factory returns. This pattern concentrates gauge ownership with end-users while fragmenting aftermarket revenue across specialized service providers.
High-Vacuum Gauge Market Segmentation
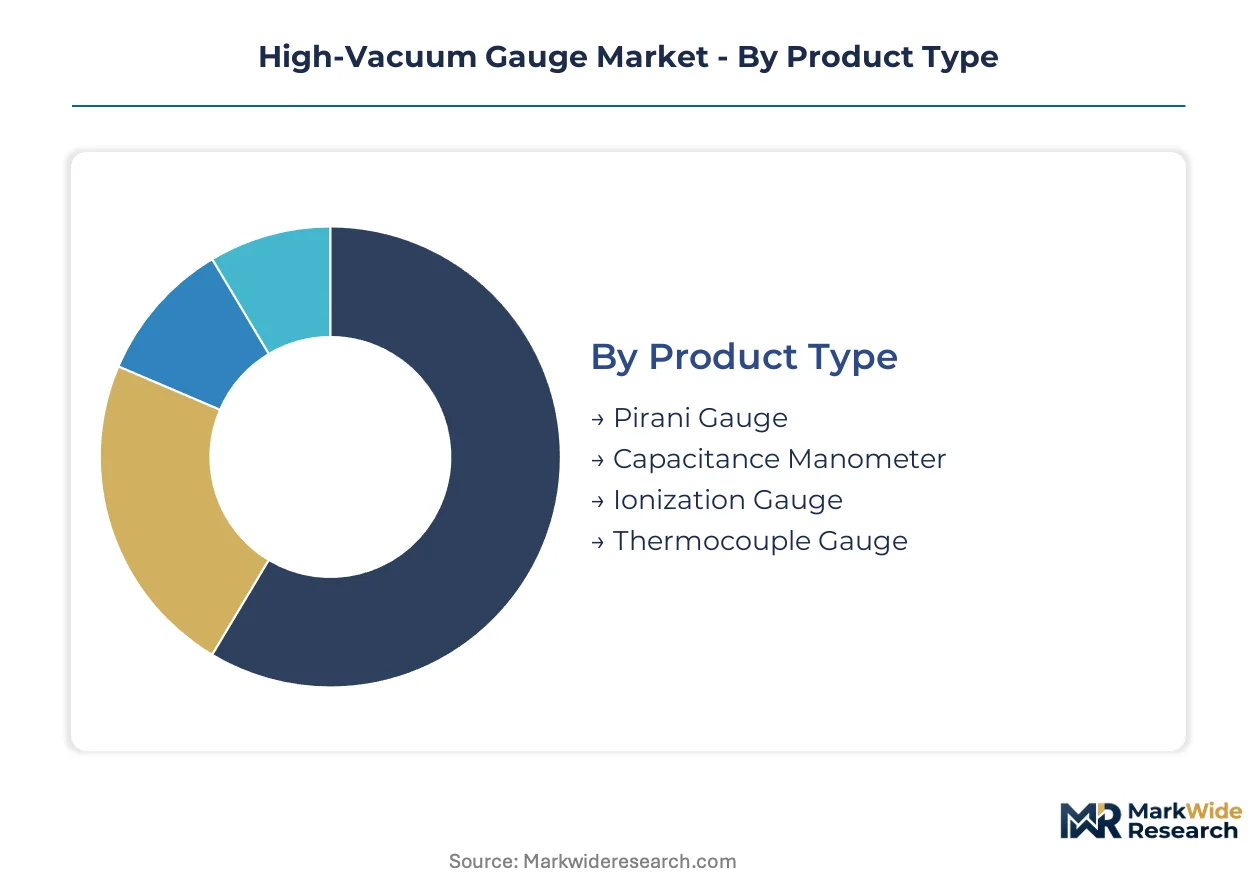
High-vacuum gauge segmentation reveals distinct performance-price tradeoffs across measurement principles. Each product category serves specific pressure regimes and contamination tolerances that determine equipment selection in semiconductor fabs, research facilities, and coating operations.
Product Type:
The use-case spectrum spans rough vacuum monitoring in coating lines to ultra-high vacuum characterization in EUV lithography chambers.
- Capacitance Manometer:Ceramic diaphragm sensors with capacitive displacement transducers deliver gas-independent accuracy across six orders of magnitude. Taiwan and South Korean EUV lithography fabs specify these for critical process steps where helium backstreaming contamination risks disqualify thermal alternatives.
- Ionization Gauge:Hot-cathode and cold-cathode variants measure pressures below 10⁻⁴ torr through electron-impact ionization currents. Research laboratories in Germany and Japan deploy these extensively where absolute precision matters less than cost efficiency in large experimental arrays.
- Pirani Gauge:Thermal conductivity sensors utilizing heated tungsten filaments dominate automotive headlamp metallization lines with compact form factors.
- Thermocouple Gauge:Simpler thermal transduction suits rough vacuum applications in legacy pharmaceutical freeze-drying equipment.
The dominant share belongs to Capacitance Manometer, while Ionization Gauge is closing the gap fastest.
Technology:
Signal processing architectures differentiate offerings across cost tiers and integration complexity.
- Digital:Microprocessor-based linearization and temperature compensation enable direct Ethernet integration with fab control systems. Semiconductor equipment OEMs in Japan specify these for predictive maintenance algorithms that compress downtime windows.
- Wireless:Battery-powered telemetry variants eliminate conduit installation in distributed pharmaceutical freeze-drying networks. North American operators favor these for retrofits where hardwired infrastructure would trigger facility shutdowns.
- Analog:Voltage-output sensors persist in mature facilities with 1990s-era control architectures.
- Semi-Conductor:MEMS-fabricated thermal elements on silicon substrates enable wafer-scale manufacturing economics.
Digital platforms command the installed base, yet Wireless is expanding most quickly in greenfield pharmaceutical installations.
End User:
Customer concentration patterns mirror regional manufacturing specialization and capital expenditure cycles.
- Semiconductor Manufacturing:EUV lithography chamber requirements drive specification intensity for sub-10⁻⁹ torr measurement stability. Taiwan and South Korean fabs account for disproportionate procurement volumes as domestic capacity expansion accelerates.
- Research Laboratories:Academic and government facilities prioritize cost efficiency over absolute precision in large experimental arrays. European synchrotron facilities maintain steady replacement demand for ionization gauge fleets.
- Vacuum Coating:Automotive headlamp and architectural glass metallization lines specify compact Pirani designs.
- Medical Equipment:Pharmaceutical freeze-dryer OEMs require ISO 3567 calibration traceability for regulatory submissions.
Semiconductor Manufacturing holds the dominant position, though Research Laboratories maintain resilient replacement demand through grant-funded equipment cycles.
Application:
Functional deployment patterns reflect integration depth with process control architectures.
- Process Control:Real-time pressure feedback loops in semiconductor etching and deposition equipment demand sub-millisecond response times. Taiwan-based EUV lithography tool builders specify capacitance manometers with dedicated analog outputs for plasma stability regulation.
- Leak Detection:Helium mass spectrometer systems rely on auxiliary vacuum gauges for chamber evacuation verification. Automotive battery cell manufacturing lines in Germany deploy these for electrolyte filling station integrity testing.
- Pressure Measurement:General-purpose monitoring accounts for baseline gauge deployment across all verticals.
- System Monitoring:Distributed sensor networks in pharmaceutical operations track pump-down curves and baseline pressure trends.
Process Control generates the highest value per installation, while Leak Detection is gaining share fastest through battery manufacturing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor equipment buyers concentrate procurement decisions in East Asian manufacturing clusters, with European research facilities and North American pharmaceutical operators representing secondary demand poles. Gauge specification intensity varies sharply across these buyer archetypes, creating divergent technical roadmaps and certification requirements.
United States
Pharmaceutical freeze-dryer OEMs and mature semiconductor fabs drive steady replacement demand. EPA NESHAP standards for semiconductor manufacturing impose leak-rate thresholds that filter gauge selection in domestic fabrication investments. The Pacific Northwest hosts distributed vacuum networks where wireless connectivity variants penetrate retrofit installations.
Germany
Automotive battery cell manufacturing lines and European synchrotron facilities anchor ionization gauge procurement. REACH compliance deadlines for restricted substance thresholds force reformulation of brazing alloys and ceramic feedthrough materials. Bavarian coating system builders now require full material disclosure documentation upstream of procurement decisions.
China
SAMR enforcement of GB/T vacuum measurement standards creates captive demand for locally certified gauge manufacturers serving domestic chip fabrication investments. The Yangtze River Delta concentrates EUV lithography chamber deployments where sub-10⁻⁹ torr measurement stability commands specification intensity. Tungsten filament supply concentration in rare-earth processing regions exposes buyers to export restriction volatility.
South Korea
Memory and logic fab expansion drives disproportionate procurement volumes for capacitance manometers and ionization gauges. MFDS-equivalent standards for pharmaceutical equipment traceability shape medical device applications. Seoul Capital Area fabs scale gauge deployments to maintain process stability at extreme high-vacuum operating pressures.
Japan
Deposition equipment OEMs qualify MEMS-based Pirani sensors for production environments, virtualizing traditional glass-envelope gauge supply chains. METI industrial standards influence vacuum measurement equipment specifications across automotive and electronics verticals. Chubu-Nagoya industrial corridors concentrate compact sensor demand for space-constrained coating systems.
High-Vacuum Gauge Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Semiconductor equipment OEMs in Japan and Taiwan exert specification authority that filters down to gauge selection, while research laboratory distributors aggregate fragmented demand across academic and government facilities. Three archetypes dominate: ionization gauge specialists competing on cost efficiency, capacitance manometer vendors commanding premium positioning through gas-independent accuracy, and MEMS-fabrication entrants leveraging wafer-scale manufacturing economics. Consolidation pressure operates through backward integration into sensor fabrication and strategic partnerships with deposition equipment builders.
Within the premium-tier vector, MKS Instruments, Inc. and INFICON Holding AG occupy positions shaped by their geographic origins and corporate structures. Pfeiffer Vacuum Technology AG exemplifies the compact-design specialist archetype. These three entities anchor competitive dynamics without exhausting the vendor landscape, as regional certification requirements and service network density sustain mid-tier specialists with localized compliance capabilities.
| Leading Market Players |
|---|
| MKS Instruments, Inc. |
| INFICON Holding AG |
| Pfeiffer Vacuum Technology AG |
| Agilent Technologies, Inc. |
| Edwards Vacuum, LLC |
| Leybold GmbH |
| Kurt J. Lesker Company |
| Brooks Instrument |
| Thyracont Vacuum Instruments GmbH |
| Others |
Supply & Pricing Matrix
Tungsten filament production clusters in Chinese rare-earth processing regions concentrate cathode supply for ionization gauges, anchoring margin pools with gauge assemblers who command specification authority over Taiwan and South Korean fabs. This upstream concentration forces downstream buyers into long-term offtake contracts indexed to rare-earth oxide benchmarks, while capacitance manometer vendors capture premium positioning through captive ceramic substrate fabrication.
Pricing Analysis
Cost-plus contracts with rare-earth oxide indexation dominate ionization gauge procurement, insulating suppliers from tungsten price volatility while transferring margin risk to buyers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 3567-certified capacitance manometers from uncertified thermal alternatives. Cost compression in economy-tier Pirani gauges intensifies as MEMS fabrication scales wafer-level production. Research laboratories exhibit highest price sensitivity due to grant-funded budget constraints, whereas EUV lithography fabs prioritize measurement stability over unit cost.
Supply Chain Analysis
Contract manufacturing for gauge sensor substrates concentrates with specialized ceramic foundries in Japan, Germany, and the United States. Precision electrode machining draws from tungsten wire drawn in China, alumina ceramic substrates sourced from Japanese suppliers, and capacitive displacement electronics fabricated in South Korean foundries. Single-source vulnerability in Chinese rare-earth processing exposes ionization gauge cathode supply to export restriction risk. Distribution runs through semiconductor equipment OEMs in Japan and Taiwan who specify gauge integration requirements upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-vacuum gauge demand is accelerating through EUV lithography chamber deployments, with REACH compliance deadlines and SAMR GB/T enforcement creating regulatory moats around certified suppliers. This technological-regulatory inflection compresses the window for capability building.
For Market Incumbents: Insulate specification lock-in by deepening backward integration into ceramic sensor substrate fabrication and securing ISO 3567 calibration network density ahead of talent scarcity. Counter MEMS Pirani disruption through service contract bundling that anchors replacement revenue. Prioritize certification investment for REACH-compliant brazing alloys to disqualify legacy competitors from European coating system procurement. For New Entrants and Emerging Players: Build out wireless connectivity variants for pharmaceutical freeze-drying retrofits where hardwired infrastructure constraints create white-space penetration. Target North American distributed vacuum networks with battery-powered telemetry solutions. Pursue calibration-as-a-service unbundling to fragment aftermarket revenue without competing on gauge manufacturing scale. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MEMS-based Pirani fabrication as wafer-scale manufacturing economics displace traditional glass-envelope supply chains. Long-term viability favors gauge specialists with certified supply chains and regional compliance capabilities rather than undifferentiated component assemblers. Monitor tungsten export license issuance patterns as inflection indicator for ionization gauge margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captures margin pools from Japanese alumina suppliers while securing REACH-compliant material traceability. |
| ISO 3567 Calibration Network Expansion | Addresses technician scarcity constraining service revenue capture in Taiwan and South Korean fab clusters. |
| MEMS Pirani Platform Qualification | Enables wafer-scale manufacturing economics that virtualize traditional glass-envelope gauge supply chains. |
| Wireless Telemetry Product Line Launch | Eliminates conduit installation barriers in North American pharmaceutical freeze-drying retrofit applications. |
| SAMR GB/T Certification Pathway | Unlocks captive demand from domestic chip fabrication investments in China's Yangtze River Delta. |
Research Methodology
Operator-level perspectives from vacuum system engineers, semiconductor equipment procurement leads, calibration technicians, and coating system builders anchored the qualitative base. These primary insights combined with secondary validation from SEMI equipment market data, EPA NESHAP regulatory filings, SAMR GB/T standard documentation, and customs trade records. Bottom-up gauge shipment triangulation against top-down fab capital expenditure patterns ensured cross-verification.
Scenario-bracketing around EUV lithography deployment timelines and rare-earth export restriction probabilities bounded the projection horizon. Segmentation dimensions modeled include measurement principle, signal processing architecture, end-user vertical, and regional regulatory cluster. CAGRs derived from equipment procurement cycle analysis and replacement rate assumptions across semiconductor, pharmaceutical, and research laboratory verticals. Forecast inputs incorporated REACH compliance deadline phasing and SAMR enforcement intensity variations.
Stress conditions across tungsten supply disruption severity, EUV lithography adoption velocity, and MEMS Pirani qualification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and equipment OEM specification authority. Quarterly review of rare-earth export license issuance and EUV tool shipment data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Precision Balances Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Disintegration Analyzer Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Vapor Pressure Analyzer Market