
 Potentiometric Titrators Market | 2026-2036
Potentiometric Titrators Market Size, Share, and Industry Trends Forecast 2026-2036
Potentiometric Titrators Market Outlook
Software-defined titration protocols with remote monitoring capabilities is realigning how laboratories procure and operate potentiometric systems. Mettler Toledo leverages its automation expertise to anchor premium positions in pharmaceutical quality control workflows. Metrohm sustains competitive density through specialized ion-selective electrode configurations for environmental compliance testing. Hanna Instruments differentiates via accessible price-performance ratios that extend penetration into educational and small-laboratory settings.
Potentiometric titrators measure electrochemical potential between electrodes to determine analyte concentration, typically achieving resolution to 0.1 millivolt and supporting dynamic equivalence-point detection through automated burette dispensing. These instruments serve primarily as standardized tools for quantitative chemical analysis in regulated industries where traceable accuracy is mandatory. Automatic titrators command the dominant installed base due to throughput advantages in high-volume pharmaceutical and food safety laboratories, while software-integrated systems with data logger connectivity represent the fastest-expanding technology tier as audit-trail requirements intensify. Manual titrators retain niche utility in resource-constrained educational institutions and field metallurgy applications where capital constraints outweigh speed imperatives.
EPA methods and ISO 17025 accreditation frameworks govern instrument validation protocols in North American environmental and industrial testing facilities, compelling vendors to embed compliant firmware and calibration routines. REACH substance restrictions and EMA pharmaceutical quality guidelines in Europe shape electrode material selections and disposal pathways for mercury-containing reference systems. Stakeholders must evaluate how emerging green chemistry mandates and digital traceability standards will reshape hardware design priorities and aftermarket service obligations.
Market Dynamics
Automated titration protocols with embedded compliance firmware are compressing replacement cycles for legacy manual systems in pharmaceutical quality control laboratories.
Growth Catalysts
- EPA water quality standards:Stringent monitoring mandates for drinking water and wastewater treatment facilities are mandating traceable analytical methods that only automated potentiometric systems can deliver at required throughput.
- Pharmaceutical purity verification:Active pharmaceutical ingredient manufacturers in Germany and Switzerland are deploying high-precision titrators to meet EMA stability testing protocols and accelerate batch release timelines.
- Electrode miniaturization:Solid-state ion-selective electrode architectures are eliminating mercury-containing reference systems, enabling compliance with REACH substance restrictions while reducing hazardous waste disposal costs.
Market Restraints
- Platinum electrode cost volatility:Precious metal price fluctuations in South African mining supply chains are squeezing margins for high-precision reference electrode manufacturers and their OEM customers.
- Calibration consumables concentration:Certified reference material production clusters in Germany and the United States create geographic supply risk for laboratories requiring ISO 17025-traceable buffer solutions.
- Optical titration substitution:Photometric endpoint detection systems are capturing share in food safety applications where colorimetric indicators suffice and electrochemical precision is unnecessary.
Strategic Opportunities
- India pharmaceutical contract manufacturing:CDMO expansion under PLI scheme incentives is creating first-time demand for automated titration systems in quality control laboratories previously reliant on manual methods.
- Cloud-connected audit trails:Integration of titration data with LIMS and ELN platforms via API architectures is enabling remote method validation and reducing on-site technical service dependency.
- Green chemistry mandates:California Safer Consumer Products regulations and EU Green Deal chemistry roadmaps are accelerating replacement of mercury-based reference electrodes with solid-state alternatives.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in ion-selective electrode maintenance and method development is concentrating in aging workforces at German and Swiss analytical instrument manufacturers.
- Legacy LIMS integration complexity:Pharmaceutical laboratories running 1990s-era laboratory information management systems face protracted validation timelines when connecting modern titrators requiring 21 CFR Part 11-compliant data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potentiometric Titrators Market |
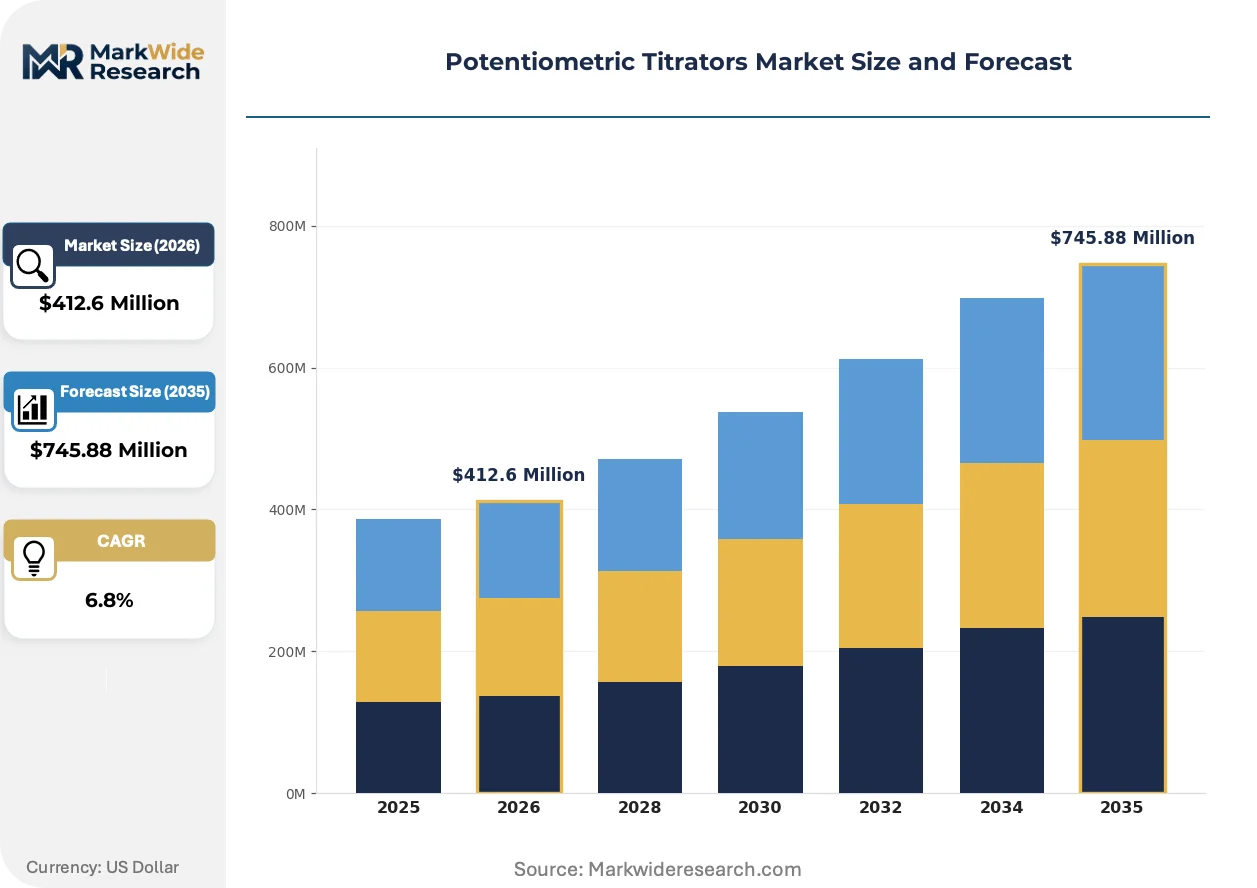
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Titrators, Manual Titrators, Hybrid Titrators, Lab-Scale Titrators End User: Pharmaceutical Industry, Food & Beverage Industry, Environmental Testing Labs, Educational Institutions Technology: Ion-Selective Electrode, pH Meters, Data Loggers, Software Solutions Application: Acid-Base Analysis, Metallurgy, Quality Control, Research & Development |
| Companies Covered | Xylem, Hanna Instruments, Mettler Toledo, Hiranuma, KEM, Metrohm, Hach, DKK-TOA, Hitachi High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potentiometric Titrators Market Strategic Shifts
Digital traceability requirements and modular hardware architectures are redefining how analytical laboratories specify, procure, and validate potentiometric titration systems across regulated industries.
Microfluidic flow-cell titration platforms with integrated conductivity detection are electrifying routine water hardness and alkalinity testing workflows. Municipal water utilities in the Netherlands and Denmark are deploying these systems for continuous monitoring stations. The technology is compressing capital expenditure thresholds for multi-parameter analysis while eliminating separate sample preparation steps.
REACH authorization requirements for mercury compounds are forcing electrode manufacturers to accelerate solid-state reference system development timelines. Industrial laboratories in Germany and France face 2025 deadlines for phasing out mercury-containing calomel electrodes. The regulation is redirecting R&D investment toward polymer membrane and crystal-based reference architectures that maintain millivolt stability without hazardous material handling protocols.
Service unbundling is fragmenting traditional instrument procurement patterns in North American environmental testing chains. Third-party ISO 17025-accredited calibration providers are displacing manufacturer-performed annual maintenance contracts. Contract laboratories in Texas and California are adopting this model to reduce total cost of ownership while maintaining EPA method compliance documentation.
Potentiometric Titrators Market Segmentation
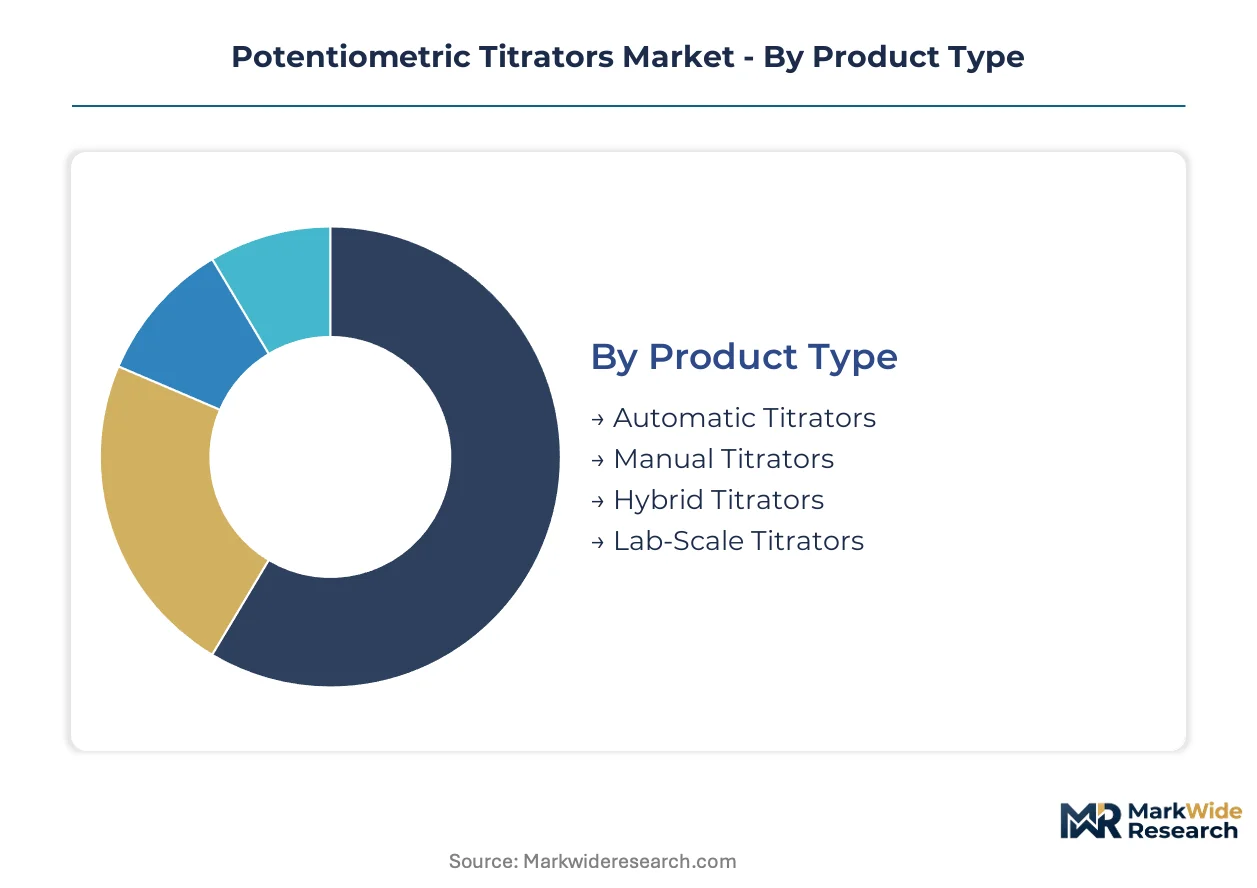
Potentiometric titrator procurement patterns diverge sharply across certification tiers. Pharmaceutical manufacturers demand ISO 17025-traceable systems with embedded 21 CFR Part 11 firmware, while educational buyers prioritize capital efficiency over compliance documentation.
Product Type:
Automatic titrators carry the heaviest validation burden, requiring EPA method compliance and FDA software qualification for pharmaceutical deployments. Manual systems face lighter regulatory loads but must still meet basic ISO accuracy specifications.
- Automatic Titrators:These systems integrate automated burette dispensing with dynamic equivalence-point detection algorithms. German pharmaceutical quality control laboratories are replacing legacy units to meet EMA batch release acceleration mandates.
- Manual Titrators:Hand-operated burette systems with visual or basic potentiometric endpoint detection. Resource-constrained educational institutions in India retain these for undergraduate chemistry curricula where capital budgets limit automation adoption.
- Hybrid Titrators:Semi-automated platforms blending manual sample handling with automated data capture. Small contract laboratories in Switzerland deploy these for intermediate throughput needs.
- Lab-Scale Titrators:Compact benchtop units designed for limited sample volumes. University research departments in the Netherlands favor these for method development work.
Leading the category by volume: Automatic Titrators. Growing fastest: Hybrid Titrators.
End User:
Cost tiers stratify sharply across end-use segments, with pharmaceutical buyers absorbing premium pricing for compliance-embedded systems and educational purchasers driving commoditization at the entry level.
- Pharmaceutical Industry:Active pharmaceutical ingredient manufacturers require systems with audit-trail firmware and LIMS connectivity. CDMO expansion under India's PLI scheme is creating first-time automated titration demand in quality control laboratories previously reliant on manual methods.
- Food & Beverage Industry:Process control laboratories utilize titration for acidity and salt content verification. German dairy cooperatives are upgrading to automated systems to meet EU food safety authority documentation requirements.
- Environmental Testing Labs:Facilities monitoring drinking water and wastewater employ titration for alkalinity and hardness analysis. Dutch municipal utilities deploy continuous monitoring stations with microfluidic flow-cell platforms.
- Educational Institutions:Undergraduate chemistry departments prioritize accessible price-performance ratios. Indian technical universities represent expanding volume for basic manual and entry-level automatic systems.
Highest margin concentration sits with pharmaceutical deployments. Steepest expansion trajectory: environmental testing laboratories.
Technology:
Technology maturity curves diverge, with ion-selective electrodes facing REACH-mandated redesign while software layers attract disproportionate R&D investment.
- Ion-Selective Electrode:Solid-state architectures are displacing mercury-containing reference systems to meet ECHA authorization deadlines. German industrial laboratories face phase-out requirements for calomel electrodes.
- pH Meters:Integrated potentiometric detection modules with glass or ISFET sensor options. Swiss pharmaceutical manufacturers specify these for stability testing protocols requiring millivolt resolution.
- Data Loggers:Embedded storage systems capturing titration curves for audit compliance. US environmental laboratories require these for EPA method documentation.
- Software Solutions:Method development platforms with LIMS and ELN integration via API architectures. Cloud-connected systems are reducing on-site technical service dependency for North American contract laboratories.
Dominant installed base: Ion-Selective Electrode technology. Climbing the fastest: Software Solutions.
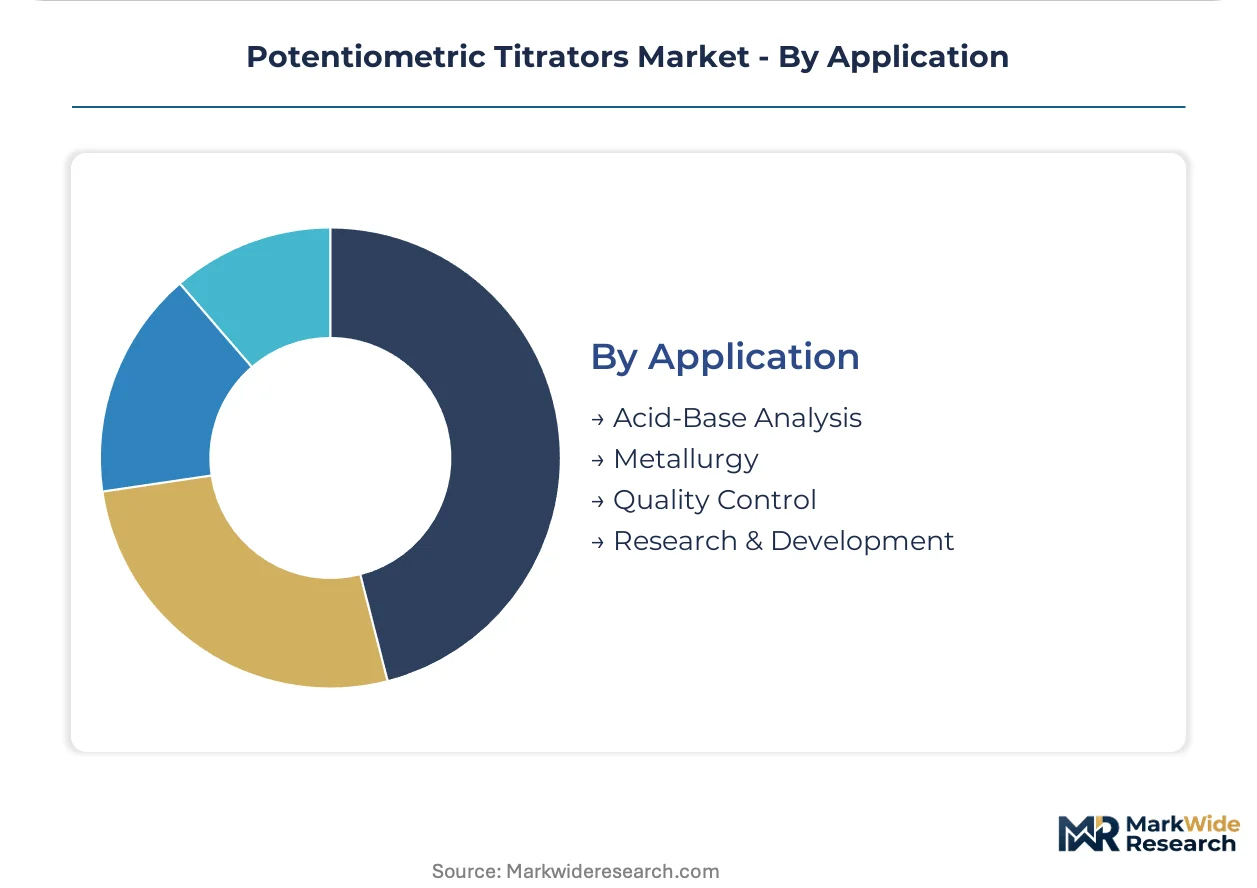
Application:
Application segments map directly to regulatory intensity, with quality control and R&D commanding compliance-embedded systems while metallurgy tolerates lower-specification alternatives.
- Acid-Base Analysis:Routine titration for pH and alkalinity determination in water and chemical samples. Danish municipal water utilities deploy automated systems for continuous monitoring stations.
- Metallurgy:Precipitation and complexometric titration for alloy composition verification. Field applications in South African mining operations retain manual systems due to remote location constraints.
- Quality Control:Batch release testing for pharmaceutical and food products. German chemical manufacturing clusters drive replacement cycles for high-precision analytical equipment.
- Research & Development:Method development and novel analyte characterization. Swiss research institutes specify premium systems with modular electrode configurations.
Quality Control commands the largest revenue share. Gaining share fastest: Research & Development applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision instrument manufacturing capacity while pharmaceutical laboratories in Switzerland and environmental testing facilities in the United States absorb the majority of high-end system deployments.
Germany
Chemical manufacturing clusters in North Rhine-Westphalia and Bavaria drive replacement cycles for automated titration systems. REACH authorization deadlines for mercury-containing electrodes are forcing industrial laboratories in Leverkusen and Ludwigshafen to accelerate solid-state reference system adoption. The ECHA phase-out requirements are redirecting procurement budgets toward compliant architectures before 2025 deadlines.
United States
EPA drinking water monitoring mandates and pharmaceutical quality control expansion are compressing replacement timelines for legacy manual systems. The Safe Drinking Water Act enforcement priorities are compelling municipal utilities in Texas and California to deploy continuous monitoring stations with automated alkalinity detection. Environmental testing chains in the Southwest are unbundling service contracts to reduce total cost of ownership.
Switzerland
Active pharmaceutical ingredient manufacturers and contract research organizations are absorbing premium-priced systems with embedded audit-trail firmware. Swissmedic stability testing protocols are mandating millivolt-resolution instrumentation for batch release documentation. Basel and Zurich pharmaceutical corridors are specifying modular electrode configurations for method development flexibility.
India
CDMO expansion under the PLI scheme is creating first-time demand for automated titration in quality control laboratories previously reliant on manual methods. CDSCO pharmaceutical manufacturing standards are tightening purity verification requirements for export-oriented facilities. Maharashtra and Gujarat pharmaceutical clusters are upgrading analytical infrastructure to meet EMA and FDA inspection readiness.
Netherlands
Municipal water utilities are deploying microfluidic flow-cell platforms for continuous hardness and alkalinity monitoring. EU Urban Waste Water Treatment Directive implementation is mandating traceable analytical methods for discharge compliance. Randstad region utilities are compressing capital expenditure thresholds through integrated multi-parameter analysis systems.
Potentiometric Titrators Market Competitive Environment
Capital-heavy precision instrument manufacturers compete with modular system integrators for placement in regulated laboratory environments. The vendor base stratifies across three tiers: premium automation specialists commanding pharmaceutical validation workflows, mid-market configurators serving environmental compliance testing, and accessible-price entrants penetrating educational procurement channels. Strategic differentiation concentrates on firmware compliance embedding, electrode architecture miniaturization, and cloud-connected service models. Competitive moves center on geographic expansion into Indian pharmaceutical manufacturing corridors and backward integration into solid-state electrode material supply.
Among Swiss and German precision instrumentation groups, Mettler Toledo and Metrohm occupy positions anchoring premium-tier pharmaceutical workflows. Hanna Instruments exemplifies the accessible-price archetype extending penetration into educational and small-laboratory settings. Japanese electrical measurement specialists including Hiranuma and DKK-TOA represent regional fabrication expertise serving Asia-Pacific environmental testing demand.
| Leading Market Players |
|---|
| Xylem |
| Hanna Instruments |
| Mettler Toledo |
| Hiranuma |
| KEM |
| Metrohm |
| Hach |
| DKK-TOA |
| Hitachi High-Tech |
| Others |
Value Chain & Pricing Dynamics
EMA batch release acceleration mandates in German pharmaceutical corridors are forcing electrode manufacturers to absorb certification costs and accelerate solid-state reference system development, compressing margins at the premium tier while widening price-performance gaps against manual alternatives.
Pricing Analysis
Margin tightening in pharmaceutical-grade systems reflects REACH compliance embedding costs and firmware validation burdens. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-traceable pharmaceutical units from environmental compliance systems and educational manual titrators. Cost compression in mid-market tiers intensifies as Indian CDMOs demand accessible automation without full 21 CFR Part 11 suites. Educational buyers exhibit highest price sensitivity, while Swiss API manufacturers absorb premium pricing for audit-trail embedded systems.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum supply chains feeding German and Swiss electrode manufacturers. Solid-state sensor substrates draw from Japanese ceramic foundries and German polymer membrane specialists. Logistics chokepoints concentrate in certified reference material production clusters located in Germany and the United States. Distribution runs through manufacturer-direct channels for pharmaceutical validation workflows and third-party laboratory distributors for environmental testing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The potentiometric titrators market sits in a technology-transition phase as solid-state ion-selective electrodes displace mercury-containing reference systems ahead of ECHA authorization deadlines.
For Market Incumbents: Deepen backward integration into solid-state electrode material supply to defend against platinum price volatility and accelerate REACH-compliant product pipelines. Anchor firmware development resources in pharmaceutical audit-trail capabilities to maintain premium positioning against optical titration substitution threats in food safety applications. For New Entrants and Emerging Players: Cloud-connected service platforms offer the most penetrable route for displacing incumbent annual maintenance contracts in North American environmental testing chains. Target Texas and California contract laboratories with unbundled ISO 17025-accredited calibration offerings that reduce total cost of ownership while maintaining EPA method compliance documentation. For Investors and Strategic Acquirers: The window for entry favors mid-market configurators with modular hardware architectures and established electrode miniaturization expertise. Solid-state reference system patent portfolios and API-enabled LIMS integration capabilities signal acquisition attractiveness. Watch for inflection when California Safer Consumer Products enforcement accelerates mercury electrode phase-out timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Materials | Captures margin from South African platinum supply volatility while securing REACH-compliant solid-state architectures. |
| Cloud-Connected Audit Trail Development | Enables remote method validation for North American contract laboratories reducing on-site technical service dependency. |
| Geographic Expansion into Indian Pharmaceutical Corridors | Captures first-time automated titration demand from CDMO quality control laboratories under PLI scheme incentives. |
| Firmware Compliance Embedding for 21 CFR Part 11 | Locks in pharmaceutical manufacturer procurement specifications for batch release documentation workflows. |
| Third-Party Calibration Service Unbundling | Displaces manufacturer-performed maintenance contracts in EPA-regulated environmental testing chains. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with quality control laboratory managers, analytical instrument procurement officers, electrode manufacturing engineers, and environmental testing compliance directors combined with EPA method documentation, ECHA authorization databases, and ISO 17025 accreditation registries. Bottom-up instrument shipment tracking and top-down end-use demand modeling provided triangulation across the analysis window.
Granularity-level modeling operated at product type, end user, technology, and application dimensions with regional regulatory cluster differentiation. CAGRs derived from weighted average of historical replacement cycle compression and emerging geography penetration rates across the projection horizon. Electrode miniaturization adoption curves and software-integrated system penetration served as analytical equipment-specific forecast inputs.
The model holds under stable REACH enforcement timelines and continued EPA drinking water monitoring mandate expansion; deviation in precious metal supply disruptions or optical titration technology advancement would shift trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Gas Chromatography Systems Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Microchip Electrophoresis Market