
 Global Terahertz and Infrared Spectroscopy Market | 2026-2036
Global Terahertz and Infrared Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Terahertz and Infrared Spectroscopy Market Foresight
A shift from single-source procurement toward dual-vendor strategies is recalibrating how semiconductor fabricators and pharmaceutical manufacturers acquire spectroscopy platforms. Bruker Corporation leverages its installed base in nuclear magnetic resonance to cross-sell FTIR and terahertz systems into existing accounts. Thermo Fisher Scientific anchors its position through service contracts and consumables revenue that extend instrument lifecycle value. Agilent Technologies differentiates via integrated software workflows that reduce method development time for quality control laboratories.
Terahertz and infrared spectroscopy encompasses non-destructive analytical techniques that probe molecular vibrations using electromagnetic radiation spanning 0.1–10 THz and 2.5–25 μm wavelengths respectively, with Fourier transform methods now dominating laboratory deployments for rapid spectral acquisition. FTIR spectrometers command the largest revenue share among product types due to decades of validated pharmacopeial methods, while time-domain terahertz systems represent the fastest-expanding technology segment as semiconductor manufacturers adopt them for non-contact wafer thickness mapping and package inspection. Pharmaceutical analysis generates the highest application revenue because regulatory submissions require compendial spectroscopic data, though semiconductor inspection is narrowing the gap as advanced packaging complexity intensifies.
FDA process analytical technology guidance and EMA quality-by-design frameworks mandate real-time spectroscopic monitoring for pharmaceutical manufacturing, directly shaping instrument specification requirements and vendor qualification protocols. EPA methods for environmental contaminant screening and ISO 17025 accreditation standards for testing laboratories further constrain permissible equipment configurations and calibration protocols. Stakeholders must monitor evolving pharmacopeial monograph revisions and semiconductor node roadmaps to anticipate which wavelength ranges and detection modalities will face stepped-up qualification demands.
Market Dynamics
Pharmaceutical manufacturers are consolidating quality control workflows around real-time spectroscopic monitoring, driven by FDA process analytical technology mandates that now extend to continuous manufacturing lines and in-process verification protocols.
Growth Catalysts
- EMA Quality-by-Design Framework:European pharmaceutical manufacturers must embed spectroscopic PAT tools into commercial manufacturing submissions, creating mandatory procurement pipelines for validated FTIR and terahertz systems in Germany and Switzerland.
- Semiconductor Advanced Packaging:3D chiplet architectures and heterogeneous integration are forcing non-contact metrology adoption, with time-domain terahertz systems penetrating wafer-level packaging inspection in Japan and South Korea.
- Raw Material Verification Mandates:Compendial spectroscopic identity testing requirements under USP and EP monographs are expanding beyond APIs to excipients and packaging materials across FDA-regulated facilities.
Market Restraints
- Detector Material Supply Concentration:Mercury-cadmium-telluride and deuterated triglycine sulfate detector manufacturing concentrates in limited geographies, exposing instrument OEMs to rare earth element price volatility and export licensing delays.
- Capital Intensity Barriers:Time-domain terahertz systems require femtosecond laser sources and precision delay stages that push unit economics beyond mid-sized pharmaceutical QC budgets in emerging markets.
- Method Validation Burden:ICH Q2(R1) and pharmacopeial spectroscopic method transfer protocols impose 12-18 month qualification timelines that delay instrument commissioning and revenue recognition for vendors.
Strategic Opportunities
- India Pharmaceutical Manufacturing Expansion:CDSCO's alignment with ICH guidelines and PLI scheme incentives for active pharmaceutical ingredient production are creating first-time spectroscopy adoption in Gujarat and Telangana cluster facilities.
- Terahertz-AI Convergence:Machine learning spectral deconvolution is reducing method development time for polymorph identification, enabling mid-tier CROs to enter spectroscopic testing services previously reserved for large pharma.
- Environmental Contaminant Screening:EPA Method 8270 and emerging PFAS monitoring protocols are opening industrial hygiene and remediation applications beyond traditional pharmaceutical and semiconductor verticals.
Industry Challenges
- Spectroscopist Talent Scarcity:Cross-functional expertise combining vibrational spectroscopy, chemometrics, and GMP compliance remains concentrated in Germany, the United States, and Japan, constraining facility expansion in lower-cost manufacturing geographies.
- Legacy LIMS Integration:Pharmaceutical manufacturers running 21 CFR Part 11 validated laboratory information management systems face middleware development costs and vendor qualification delays when connecting new spectroscopic instruments to existing data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Terahertz and Infrared Spectroscopy Market |
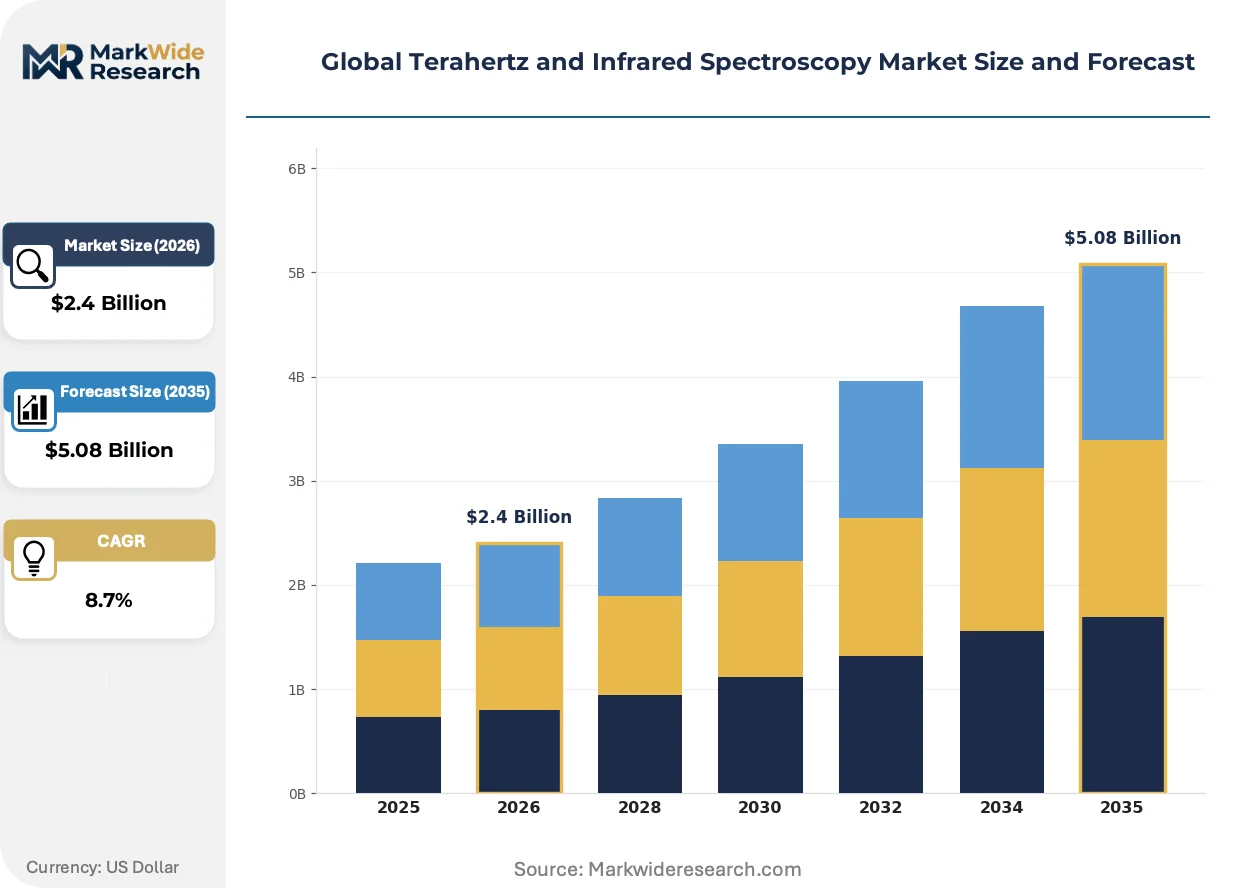
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terahertz Spectrometer, Infrared Spectrometer, FTIR Spectrometer, Raman Spectrometer, UV-Vis-NIR Spectrometer Technology: Time-Domain Spectroscopy, Frequency-Domain Spectroscopy, Dispersive Spectroscopy, Fourier Transform, Photoacoustic Spectroscopy Application: Pharmaceutical Analysis, Semiconductor Inspection, Food Safety, Material Characterization, Forensic Examination, Chemical Identification End User: Research Laboratories, Academic Institutions, Chemical Manufacturers, Semiconductor Fabricators, Food Processing Plants, Forensic Labs |
| Companies Covered | Bruker Corporation, Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, Shimadzu Corporation, TeraView, Menlo Systems GmbH, Advantest Corporation, HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Terahertz and Infrared Spectroscopy Market Shifts & Advancements
Portable and handheld spectroscopic platforms are compressing the boundary between laboratory and at-line testing, while quantum cascade laser sources and microelectromechanical system interferometers reshape instrument form factors and cost structures.
Quantum cascade laser-based mid-infrared systems are electrifying pharmaceutical raw material identification workflows by eliminating liquid nitrogen cooling requirements and enabling battery-operated handheld deployments. Generic API manufacturers in India and contract manufacturing organizations across Eastern Europe are adopting these platforms for warehouse receiving and incoming material quarantine. The technology is electrifying competitive dynamics by allowing mid-tier players to bypass centralized analytical services and deploy point-of-use verification without climate-controlled laboratory infrastructure.
REACH authorization restrictions on perfluorinated substances are forcing spectroscopic instrument manufacturers to reformulate optical coatings and seals used in FTIR interferometer assemblies. The European Chemicals Agency's 2023-2027 substance evaluation roadmap specifically targets fluoropolymers common in infrared beam splitters and detector windows. German and Swiss instrument OEMs are accelerating ceramic and silicon carbide alternative qualification programs to maintain CE marking compliance and avoid supply chain disruption.
Service contract unbundling is fragmenting how pharmaceutical manufacturers acquire lifecycle support for spectroscopic platforms. Large multi-site operators in the United States are consolidating instrument maintenance under independent third-party service providers, displacing OEM service revenue with ISO 17025-accredited regional specialists. This pattern concentrates in California and Massachusetts biotech clusters where instrument density supports dedicated on-site technician staffing models.
Global Terahertz and Infrared Spectroscopy Market Segmentation
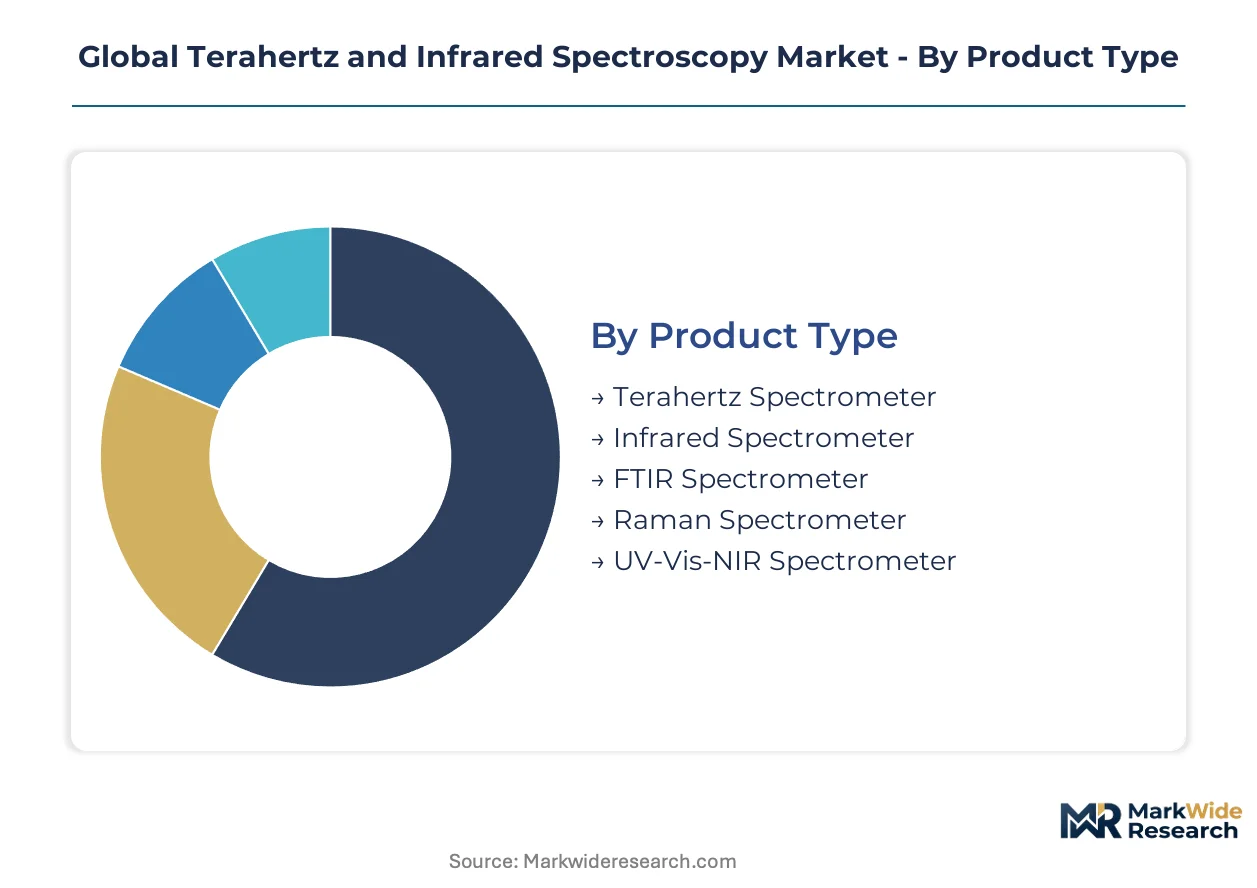
Segmentation in spectroscopy instrumentation reveals how technical specifications, regulatory requirements, and end-use workflows fragment procurement patterns across pharmaceutical, semiconductor, and industrial testing verticals. Buyers prioritize different performance thresholds, validation protocols, and integration capabilities based on their compliance environment and sample throughput demands.
Product Type:
Procurement budgets diverge sharply between established laboratory platforms and emerging portable configurations, with capital intensity and method validation timelines driving tiered acquisition strategies.
- FTIR Spectrometer:Fourier transform infrared systems dominate laboratory installations through decades of pharmacopeial method validation under USP and EP monographs. Pharmaceutical manufacturers in Germany and the United States specify these platforms for raw material identity testing and finished-product release, with regulatory submission requirements locking in multi-year replacement cycles.
- Terahertz Spectrometer:Time-domain and frequency-domain terahertz platforms enable non-contact, non-destructive analysis of opaque materials and layered structures. Semiconductor fabricators in Japan and South Korea deploy these systems for wafer-level packaging inspection, driven by 3D chiplet architectures that prohibit traditional contact metrology.
- Infrared Spectrometer:Dispersive and filter-based infrared systems serve routine quality control applications where FTIR spectral resolution exceeds operational requirements.
- Raman Spectrometer:Complementary vibrational technique using inelastic light scattering for aqueous samples and through-container analysis.
- UV-Vis-NIR Spectrometer:Broadband electronic spectroscopy platforms spanning ultraviolet through near-infrared for quantitative concentration determinations.
Volume sits with FTIR Spectrometer; growth tilts toward Terahertz Spectrometer.
Technology:
Detection modality selection hinges on sample matrix complexity, required spectral resolution, and compatibility with existing laboratory information management architectures.
- Fourier Transform:Interferometer-based multiplex detection delivers superior signal-to-noise ratios and rapid spectral acquisition across mid-infrared wavelengths. Pharmaceutical quality control laboratories in Switzerland and the United States standardize on FT methods to meet ICH Q2(R1) validation protocols for impurity profiling and polymorph screening.
- Time-Domain Spectroscopy:Femtosecond pulse generation and electro-optic sampling enable sub-picosecond temporal resolution for terahertz frequency characterization. Advanced packaging facilities in Taiwan and South Korea adopt time-domain systems for dielectric constant mapping and moisture ingress detection in molded compound structures.
- Frequency-Domain Spectroscopy:Continuous-wave terahertz generation using photomixing or multiplier chains for narrowband, high-resolution measurements.
- Dispersive Spectroscopy:Grating or prism-based wavelength separation for cost-sensitive educational and routine industrial applications.
- Photoacoustic Spectroscopy:Thermal expansion detection enabling depth-resolved analysis of strongly absorbing or scattering samples.
Deployment breadth favors Fourier Transform; capability expansion concentrates in Time-Domain Spectroscopy.
Application:
Regulatory mandate intensity and method standardization maturity create distinct specification requirements across analytical use cases.
- Pharmaceutical Analysis:Compendial identity, assay, and impurity testing under FDA process analytical technology and EMA quality-by-design frameworks. Manufacturing facilities in Germany and India require validated spectroscopic data for commercial batch release and regulatory submission packages.
- Semiconductor Inspection:Non-destructive metrology for wafer thickness, die attach voiding, and underfill cure verification. Packaging houses in Japan and the United States deploy terahertz systems to address heterogeneous integration complexity without destructive cross-sectioning.
- Food Safety:Adulterant detection and authenticity verification for supply chain integrity programs.
- Material Characterization:Polymer identification, coating thickness determination, and composite structure analysis for industrial R&D.
- Forensic Examination:Contraband identification and questioned document analysis for law enforcement laboratories.
- Chemical Identification:Unknown substance characterization for industrial hygiene and environmental monitoring applications.
Revenue concentration rests with Pharmaceutical Analysis; application development accelerates fastest in Semiconductor Inspection.
End User:
Organizational scale and regulatory exposure shape instrument specification, with multi-site pharmaceutical operators driving standardization demands.
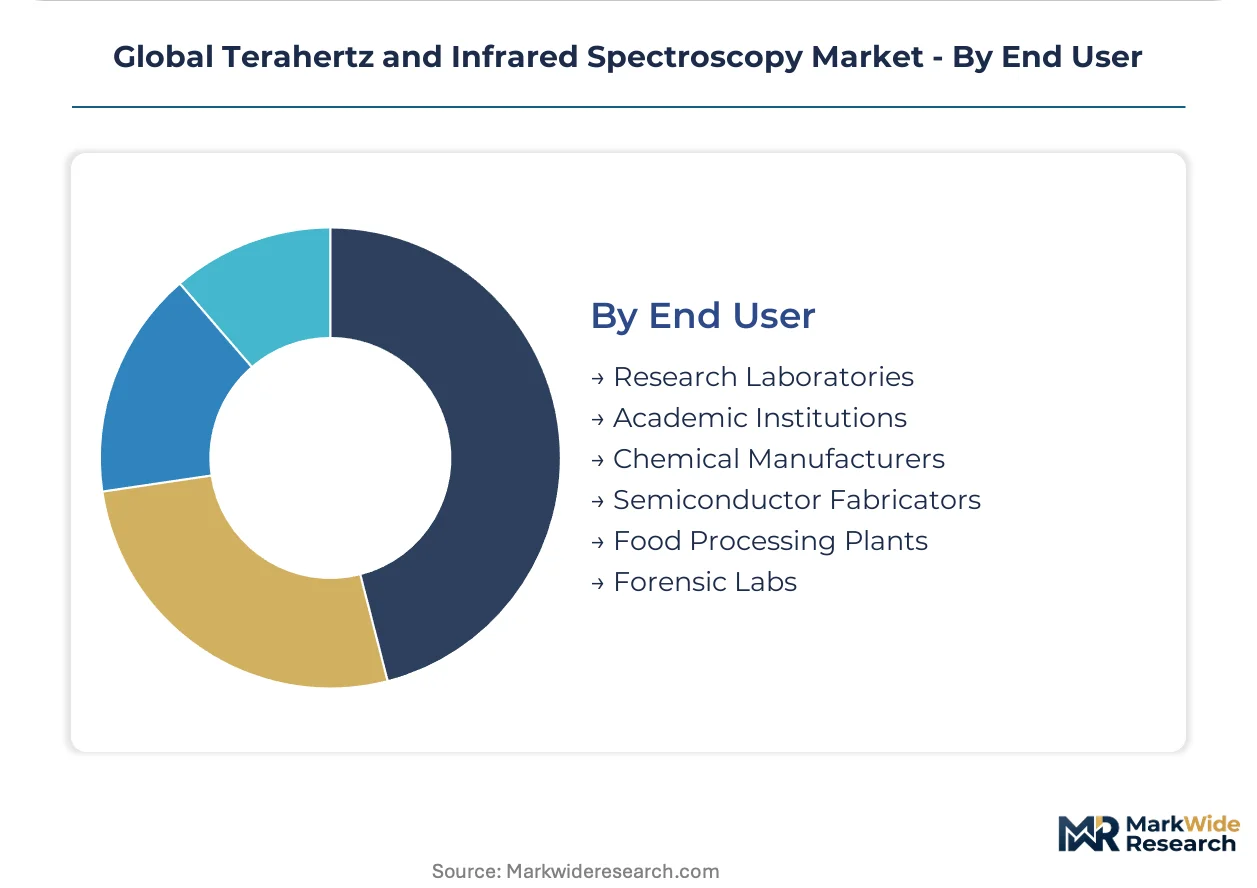
- Research Laboratories:Method development and fundamental spectroscopic investigation requiring broadband tunability and advanced sampling accessories. National laboratories in the United States and Germany specify configurable platforms supporting multiple detection modalities and cryogenic sample environments.
- Chemical Manufacturers:Incoming raw material verification and in-process monitoring under ISO 17025 accreditation requirements. Generic API producers in India adopt handheld infrared platforms for warehouse receiving operations, bypassing centralized analytical services.
- Semiconductor Fabricators:High-volume production metrology with automated wafer handling and statistical process control integration.
- Academic Institutions:Teaching and research applications prioritizing cost efficiency and multi-user accessibility.
- Food Processing Plants:At-line testing for contamination screening and ingredient authentication in manufacturing environments.
- Forensic Labs:Evidentiary analysis requiring chain-of-custody documentation and court-defensible method validation.
Instrument density peaks with Research Laboratories; procurement velocity strengthens most rapidly among Chemical Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical and semiconductor manufacturing clusters in Germany, the United States, and Japan concentrate over half of global instrument demand. Regulatory mandates from FDA, EMA, and PMDA drive procurement cycles, while emerging facilities in India and South Korea reshape geographic distribution.
United States
FDA process analytical technology mandates and continuous manufacturing adoption drive spectroscopy procurement across Massachusetts and California biotech corridors. EPA Method 8270 requirements for environmental contaminant screening expand industrial applications beyond pharma. Boston-Cambridge and San Francisco Bay Area clusters maintain dense installed bases of FTIR and terahertz systems for GMP compliance.
Germany
EMA quality-by-design frameworks and REACH authorization restrictions on fluoropolymers reshape instrument specifications for European manufacturers. Bavarian and Baden-Württemberg pharmaceutical clusters require validated spectroscopic data for commercial batch release. German OEMs accelerate ceramic alternative qualification programs to maintain CE marking compliance amid coating material restrictions.
Japan
METI semiconductor roadmaps and PMDA manufacturing guidelines drive non-contact metrology adoption for advanced packaging inspection. Tokyo-Osaka corridor fabricators deploy time-domain terahertz systems for 3D chiplet architectures and heterogeneous integration. Japanese instrument manufacturers leverage domestic semiconductor demand to develop next-generation detection modalities.
India
CDSCO alignment with ICH guidelines and PLI scheme incentives for active pharmaceutical ingredient production create first-time spectroscopy adoption. Gujarat and Telangana cluster facilities implement raw material verification protocols under evolving regulatory frameworks. Generic API manufacturers adopt handheld infrared platforms for warehouse receiving operations.
South Korea
MFDS pharmaceutical manufacturing standards and semiconductor advanced packaging complexity drive terahertz system penetration for wafer-level inspection. Busan-Ulsan and Seoul Capital Area packaging houses implement non-destructive metrology for die attach voiding and underfill cure verification. Domestic display and memory fabricators expand spectroscopic quality control workflows.
Global Terahertz and Infrared Spectroscopy Market Competitive Landscape
Cross-selling from adjacent analytical platforms dominates the current landscape, with nuclear magnetic resonance and chromatography vendors leveraging installed base relationships to penetrate spectroscopy accounts. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with service contract anchoring, specialized photonics firms with detector technology control, and analytical instrumentation pure-plays with software workflow differentiation. Portfolio diversification and strategic partnerships represent the dominant competitive moves, as vendors bundle spectroscopy platforms with adjacent quality control and research tools.
Among diversified analytical instrumentation providers, Bruker Corporation, Thermo Fisher Scientific, and Agilent Technologies occupy positions defined by cross-platform integration capabilities and service infrastructure scale. Bruker exemplifies the installed-base leverage archetype, converting nuclear magnetic resonance relationships into spectroscopy platform adoption. Thermo Fisher represents the lifecycle value model, anchoring positions through consumables revenue and extended service contracts. Agilent sits within the workflow integration tier, differentiating via software platforms that reduce method development burden for quality control laboratories. Specialized photonics firms including TeraView and Menlo Systems GmbH concentrate terahertz technology development, while Shimadzu Corporation and HORIBA anchor regional market presence through localized service networks and regulatory compliance expertise.
| Leading Market Players |
|---|
| Bruker Corporation |
| Thermo Fisher Scientific |
| Agilent Technologies |
| PerkinElmer |
| Shimadzu Corporation |
| TeraView |
| Menlo Systems GmbH |
| Advantest Corporation |
| HORIBA |
| Others |
Supply & Pricing Matrix
Performance-grade divergence between pharmacopeial-validated FTIR systems and portable quantum cascade laser platforms bifurcates procurement economics, with German and Swiss manufacturers commanding premium positions through EMA-mandated qualification protocols while Indian generic API producers absorb cost compression through handheld warehouse deployments. This tier split concentrates margin capture in detector technology and interferometer subassemblies sourced from limited geographies, forcing mid-tier buyers to trade spectral resolution against capital deployment flexibility.
Pricing Analysis
Volume concentration in FTIR laboratory platforms sustains manufacturer margins through service contract anchoring and consumables lock-in, while terahertz system pricing faces compression from femtosecond laser source commoditization and South Korean packaging house procurement consolidation. Price differentiation rests on pharmacopeial validation tier—FDA process analytical technology compliance adds substantial qualification overhead—and geographic delivery cost differentials between German OEMs and regional service networks. Pharmaceutical quality control laboratories in Massachusetts and Basel exhibit lowest price sensitivity due to regulatory submission requirements, whereas Indian CDSCO-regulated facilities prioritize capital efficiency over spectral performance.
Supply Chain Analysis
Freight cost escalation and customs clearance complexity for precision interferometer components concentrate supply risk in mercury-cadmium-telluride detector manufacturing, which draws from United States, German, and Japanese specialty semiconductor foundries. Instrument OEMs source femtosecond laser cavities from Austrian and Swiss photonics specialists, while ceramic beam splitter alternatives to fluoropolymer coatings hinge on Baden-Württemberg ceramic processing capacity. Single-source vulnerability in deuterated triglycine sulfate detector supply exposes vendors to rare earth element licensing delays. Distribution runs through authorized regional service partners with ISO 17025 accreditation, bypassing direct OEM channels in mature pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory qualification burden and capital intensity are forcing vendor consolidation, with pharmacopeial method validation timelines creating insurmountable barriers for undifferentiated instrument assemblers lacking installed base relationships or detector technology control.
For Market Incumbents: Deepen vertical integration into mercury-cadmium-telluride detector manufacturing or secure captive supply agreements with German and United States specialty foundries to insulate margins from export licensing volatility. Fortify service contract bundling against third-party ISO 17025-accredited competitors in California and Massachusetts biotech corridors by embedding predictive maintenance analytics and remote diagnostics into platform software. Quantum cascade laser commoditization threatens FTIR replacement cycle extension—accelerate terahertz-AI spectral deconvolution development to capture polymorph identification services from mid-tier CROs. For New Entrants and Emerging Players: Capture first-time spectroscopy adoption in Gujarat and Telangana pharmaceutical clusters where CDSCO alignment with ICH guidelines creates procurement windows for validated yet cost-competitive platforms. Target handheld infrared deployments for warehouse raw material verification, bypassing centralized analytical services through battery-operated quantum cascade laser configurations that eliminate liquid nitrogen infrastructure requirements. Partner with Indian PLI scheme beneficiaries for co-development of excipient screening protocols tailored to generic API manufacturing workflows. For Investors and Strategic Acquirers: Re-rating potential sits with specialized photonics firms controlling terahertz detector architectures given METI semiconductor roadmap acceleration and 3D chiplet packaging complexity in Japan and South Korea. Long-term viability favors vendors with backward integration into femtosecond laser sources or ceramic optical coating capabilities that satisfy REACH fluoropolymer restrictions. Monitor EMA quality-by-design framework expansion into continuous manufacturing submissions as inflection indicator for PAT tool procurement velocity in German and Swiss pharmaceutical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Technology Backward Integration | Captive mercury-cadmium-telluride supply insulates margins from rare earth licensing delays in United States and German foundries. |
| Terahertz-AI Spectral Deconvolution Platform | Machine learning method development compression enables mid-tier CRO entry into polymorph identification services. |
| Quantum Cascade Laser Handheld Certification | Battery-operated platforms bypass centralized labs for Indian generic API warehouse verification under CDSCO guidelines. |
| Ceramic Optical Coating Qualification | Fluoropolymer alternatives secure CE marking compliance amid ECHA REACH authorization restrictions on perfluorinated substances. |
| Third-Party Service Network Consolidation | ISO 17025-accredited regional specialists displace OEM service revenue in dense California and Massachusetts instrument clusters. |
Research Methodology
Independent corroboration across regulatory submission databases, instrument OEM technical documentation, and pharmaceutical manufacturing facility audits underwrites the qualitative findings in this study. Primary interviews with quality control laboratory directors, regulatory affairs specialists at EMA-notified bodies, semiconductor packaging metrology engineers, and analytical instrumentation procurement managers combined with secondary validation from FDA guidance documents, EMA quality-by-design framework publications, and METI semiconductor roadmap disclosures. Bottom-up triangulation across product type demand curves and top-down cross-check against national pharmaceutical production statistics anchored segmentation outputs.
Rate-of-change decomposition across technology adoption curves, regulatory mandate phase-in schedules, and capital expenditure cycle timing structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, detection modality, application vertical, end-user organizational scale, and regional regulatory cluster complexity. CAGRs derived from instrument replacement cycle analysis, greenfield facility commissioning rates, and method validation timeline compression. Forecast inputs incorporated semiconductor node roadmap acceleration, pharmacopeial monograph revision schedules, and PLI scheme incentive disbursement patterns.
The model holds under stable regulatory qualification protocols and detector material supply continuity; deviation in export licensing regimes or ECHA substance evaluation acceleration would shift instrument availability and procurement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market