
 Microplate Instrumentation and Systems Market | 2026-2036
Microplate Instrumentation and Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Microplate Instrumentation and Systems Market Foresight
High-sensitivity detection specifications is collapsing the gap between research-grade and clinical-grade microplate platforms. Thermo Fisher Scientific leverages its reagent-instrument bundling strategy to sustain installed-base loyalty across pharmaceutical accounts. Danaher Corporation anchors its position through Beckman Coulter's automated liquid-handling integration. Agilent Technologies differentiates via multimodal detection architectures that span absorbance, fluorescence, and luminescence channels.
Microplate instrumentation and systems comprise electromechanical devices that measure optical signals from 96-, 384-, or 1536-well arrays, typically resolving absorbance to 0.001 OD or fluorescence to femtomolar concentrations, for quantitative biological and chemical analysis in high-throughput workflows. Pharmaceutical companies represent the dominant end-user segment where drug discovery pipelines demand walkaway automation and LIMS-compatible data outputs. Multiplexing technology captures the fastest expansion as researchers compress multiple assay readouts into single-well measurements, reducing reagent consumption and plate handling steps.
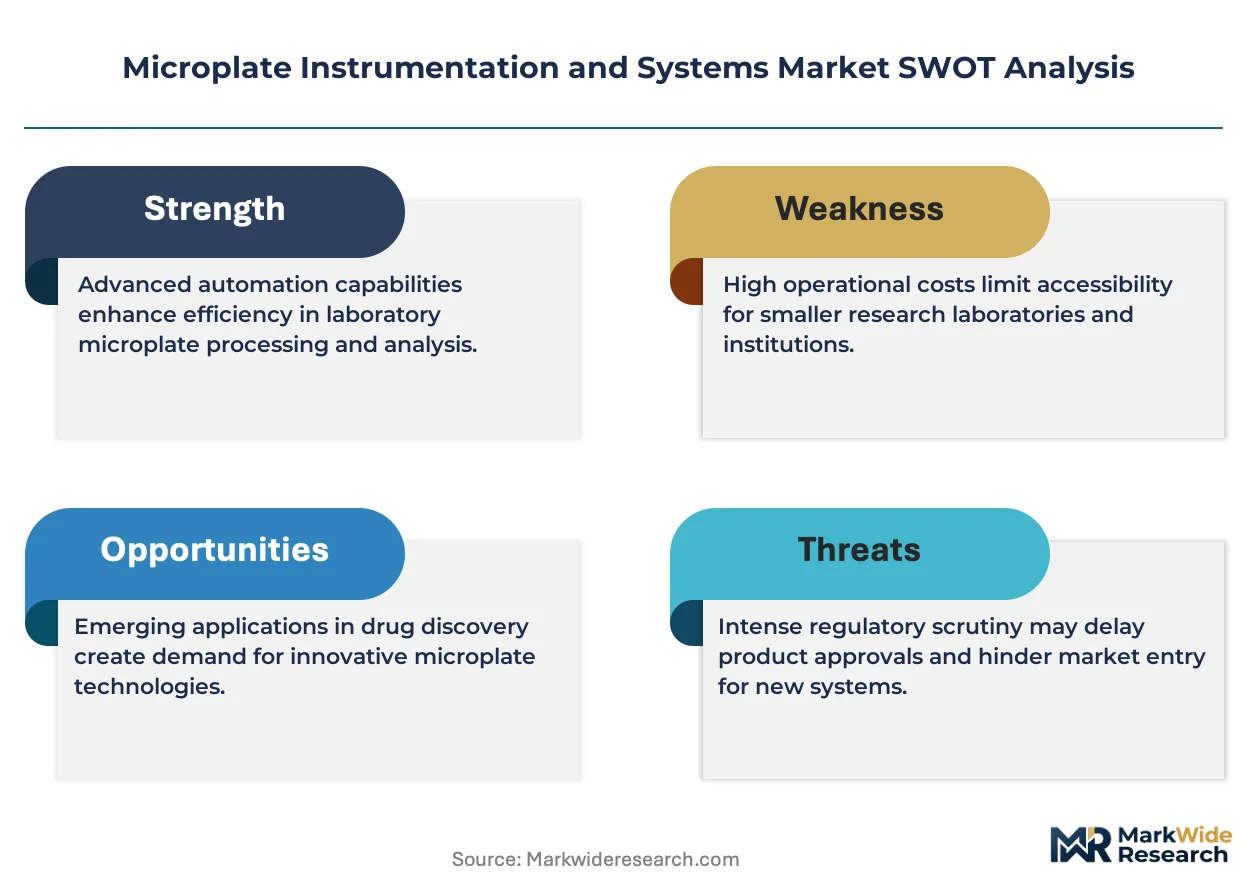
FDA enforces 21 CFR Part 11 electronic records standards for microplate systems deployed in GLP-compliant drug development environments, while ISO 17025 accreditation requirements shape instrument calibration protocols in contract research laboratories. EPA methods reference microplate-based toxicity assays for environmental compliance testing, extending regulatory demand beyond clinical and pharmaceutical domains. Stakeholders must weigh modular upgrade paths against full-platform replacement cycles as detection sensitivity thresholds and data integrity standards continue tightening.
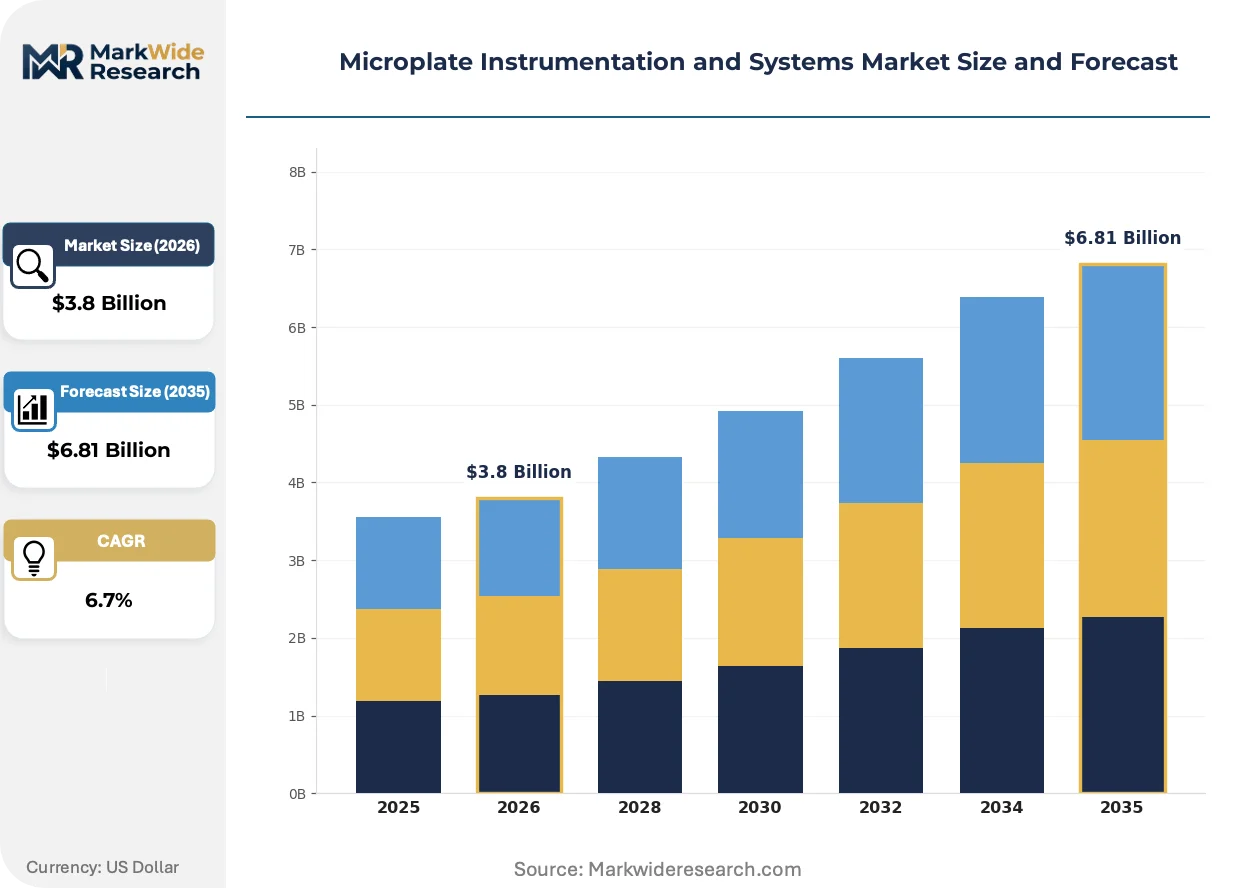
Market Dynamics
Multiplexing detection architectures are compressing assay timelines from sequential single-read workflows to simultaneous multi-parameter capture, forcing instrument manufacturers to recalibrate platform roadmaps around throughput density rather than sensitivity alone.
Growth Catalysts
- 21 CFR Part 11 Compliance Mandates:FDA electronic records requirements for GLP environments are accelerating replacement cycles of legacy microplate readers in United States pharmaceutical laboratories.
- Automated Liquid-Handling Integration:Drug discovery pipelines in Boston and San Diego are demanding walkaway automation that couples detection hardware with robotic sample preparation.
- Environmental Toxicity Testing Expansion:EPA reference methods for microplate-based assays are extending procurement demand beyond pharmaceutical accounts into contract environmental laboratories.
Market Restraints
- Precision Optics Supply Concentration:German and Japanese suppliers dominate photomultiplier tube and filter component manufacturing, creating single-source vulnerability for instrument builders.
- ISO 17025 Calibration Burden:Contract research laboratories face recurring accreditation costs that extend total cost of ownership beyond initial capital expenditure thresholds.
- Flow Cytometry Substitution:Single-cell analysis platforms are capturing applications previously routed to high-content microplate screening in immuno-oncology workflows.
Strategic Opportunities
- Point-of-Care Diagnostics Convergence:Miniaturized microplate formats are penetrating decentralized clinical testing sites in India and Brazil where laboratory infrastructure remains limited.
- Cellular Agriculture Screening:Cultivated meat producers in Singapore and Netherlands are adopting microplate-based nutrient optimization assays for bioreactor scaling.
- EU Green Deal Chemical Hazard Assessment:REACH registration requirements are mandating high-throughput toxicity screening that favors 1536-well density platforms.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Instrument manufacturers struggle to recruit engineers fluent in both electromechanical systems design and biological assay validation protocols.
- LIMS Integration Complexity:Pharmaceutical buyers demand seamless data flow into existing informatics architectures, extending sales cycles and implementation timelines.
- Patent Thicket Navigation:Detection modality intellectual property held by reagent suppliers creates licensing friction for independent hardware developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplate Instrumentation and Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microplate Readers, Microplate Washers, Automated Systems, Software End User: Pharmaceutical Companies, Research Laboratories, Diagnostic Centers, Academic Institutions Technology: Fluorescence, Luminescence, Absorbance, Multiplexing Application: Drug Discovery, Clinical Diagnostics, Environmental Testing, Quality Control |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, PerkinElmer, Bio-Rad Laboratories, Tecan Group, BMG LABTECH GmbH, Corning Incorporated, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplate Instrumentation and Systems Market Shifts & Advancements
Detection sensitivity thresholds and data integrity standards are tightening in parallel, compressing the acceptable gap between research-grade flexibility and clinical-grade validation that instrument architectures must bridge.
Label-free biosensor microplate platforms are supplanting fluorescence-dependent workflows in early-stage antibody screening. Biopharma discovery groups in Massachusetts and California are adopting these systems at replacement-cycle pace. The shift is compressing reagent spend per screening campaign while extending instrument utilization rates across 24-hour operations.
EMA's In Vitro Diagnostic Medical Devices Regulation is reclassifying certain microplate-based companion diagnostic platforms, triggering design-control documentation requirements previously limited to clinical analyzers. Manufacturers serving European oncology trials must now maintain quality management systems equivalent to MDR Article 10 standards. This regulatory elevation is favoring established instrument builders with existing notified body relationships over emerging entrants.
Service contract unbundling is fragmenting the traditional bundled sale model. Academic core facilities and mid-tier contract research organizations are separating hardware procurement from maintenance agreements, sourcing calibration and repair through third-party metrology specialists. This disaggregation is most pronounced in Germany and Switzerland where ISO 17025-accredited service providers have built regional density.
Microplate Instrumentation and Systems Market Segmentation
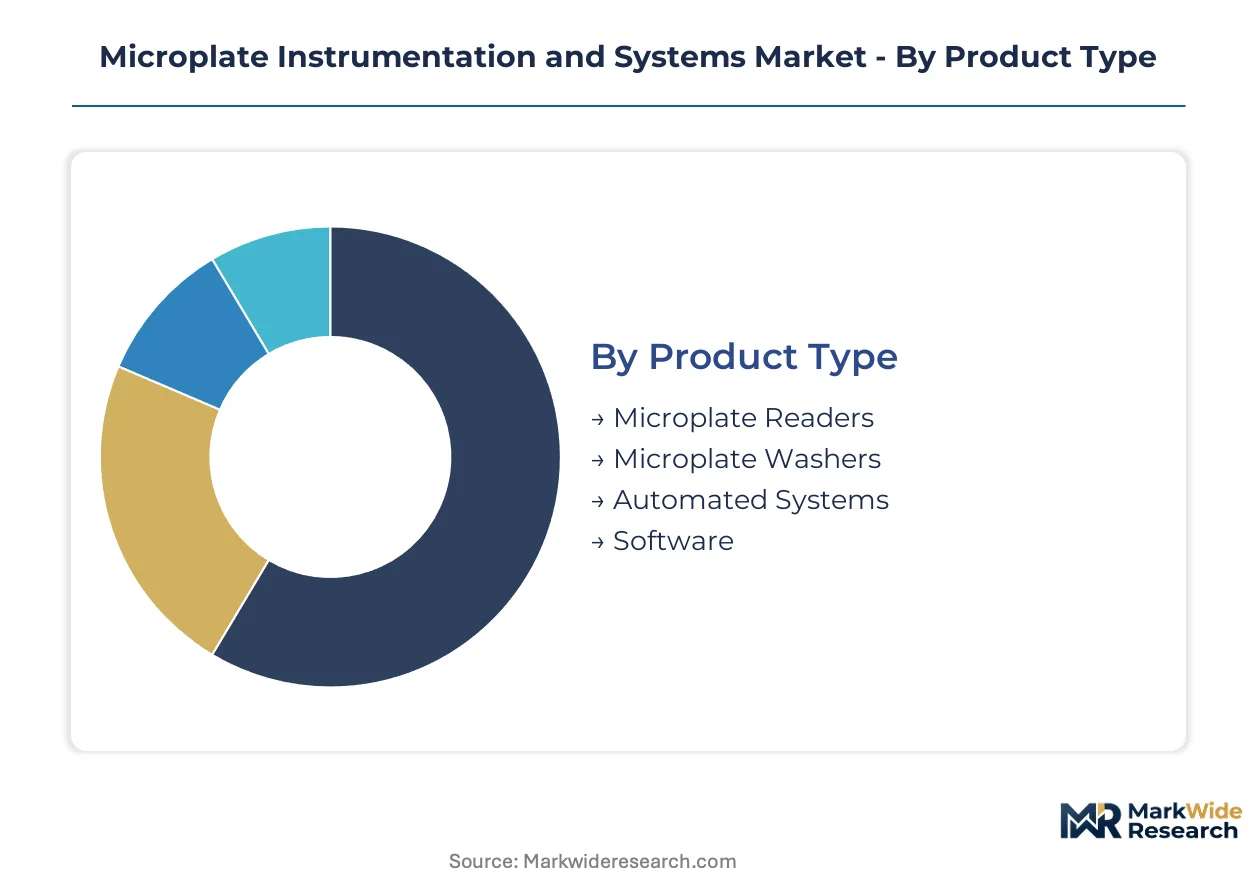
Microplate instrumentation segments diverge sharply between standardized hardware platforms and configurable software ecosystems. Procurement patterns vary by end-use maturity, with pharmaceutical buyers prioritizing validation documentation while academic users emphasize modular upgrade paths.
Product Type:
Domestic production concentrates in automated systems for North American pharmaceutical clusters, while microplate readers flow through export channels serving European and Asian contract research networks.
- Microplate Readers:Optical detection platforms resolving absorbance to 0.001 OD or fluorescence to femtomolar concentrations. Demand clusters in United States biopharma R&D hubs where 21 CFR Part 11 compliance mandates accelerate replacement cycles of legacy hardware.
- Automated Systems:Walkaway platforms integrating robotic liquid handling with detection modules and LIMS-compatible data outputs. Boston and San Diego drug discovery pipelines are demanding these configurations to compress screening timelines.
- Microplate Washers:Electromechanical devices for plate conditioning between assay steps.
- Software:Instrument control and data analysis platforms with compliance documentation features.
Microplate readers command the established base. The steepest expansion runs through automated systems.
End User:
Cost tiers separate validation-intensive pharmaceutical procurement from price-sensitive academic purchasing, with diagnostic centers occupying a mid-tier position on total cost of ownership metrics.
- Pharmaceutical Companies:Dominant segment requiring GLP-compliant electronic records, automated workflows, and ISO 13485-aligned quality systems. FDA enforcement of 21 CFR Part 11 standards is tightening instrument validation protocols across United States drug development laboratories.
- Research Laboratories:Contract research organizations and core facilities prioritizing throughput density and modular detection configurations. ISO 17025 accreditation requirements in European markets are extending calibration burdens beyond initial capital expenditure thresholds.
- Diagnostic Centers:Clinical testing sites requiring regulatory-cleared platforms for patient sample analysis.
- Academic Institutions:University core facilities with constrained capital budgets and emphasis on multi-user accessibility.
Pharmaceutical companies anchor revenue concentration. Academic institutions are climbing the fastest on replacement-cycle pace.
Technology:
Volume distribution favors absorbance and fluorescence as mature workhorses, while multiplexing architectures gain share through reagent cost compression.
- Multiplexing:Simultaneous multi-parameter detection compressing multiple assay readouts into single-well measurements. Massachusetts and California biopharma discovery groups are adopting these systems to reduce plate handling steps and reagent consumption per screening campaign.
- Fluorescence:Sensitivity-driven detection modality for low-abundance analyte quantification.
- Luminescence:Label-free and reporter-gene assay formats with minimal background interference.
- Absorbance:Colorimetric endpoint detection for ELISA and protein quantification workflows.
Fluorescence detection commands the established base. Multiplexing architectures show the steepest expansion trajectory.
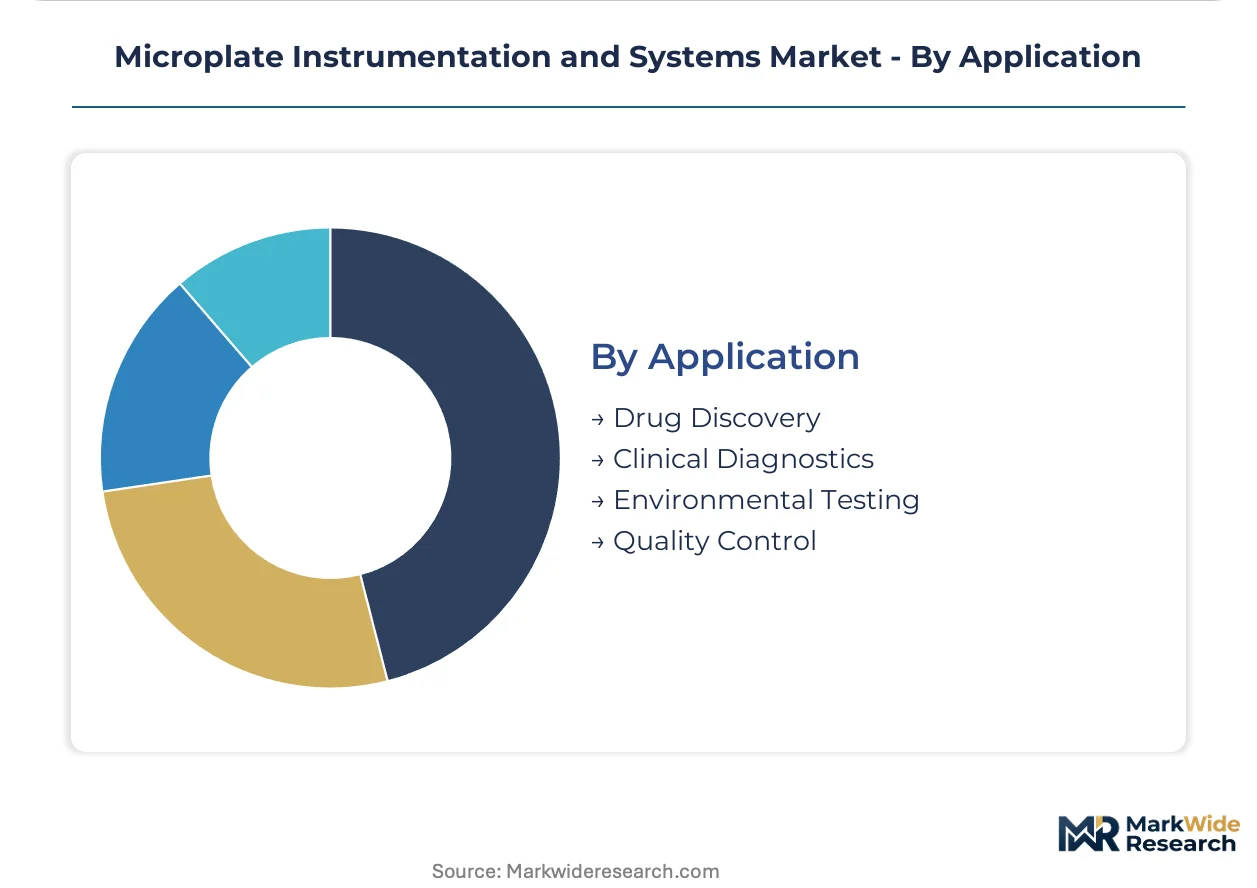
Application:
Customer type differentiation separates high-throughput drug discovery demand from regulated clinical diagnostics, with environmental testing emerging as a specialized compliance-driven segment.
- Drug Discovery:High-throughput screening campaigns requiring 24-hour instrument utilization and multimodal detection flexibility. Cultivated meat producers in Singapore and Netherlands are adopting microplate-based nutrient optimization assays for bioreactor scaling, extending demand beyond traditional pharmaceutical accounts.
- Clinical Diagnostics:Patient sample analysis with regulatory clearance requirements and quality control documentation. EMA's In Vitro Diagnostic Medical Devices Regulation is reclassifying certain companion diagnostic platforms, triggering MDR Article 10 design-control standards for manufacturers serving European oncology trials.
- Environmental Testing:EPA reference methods for microplate-based toxicity assays extending procurement into contract environmental laboratories.
- Quality Control:Manufacturing release testing and stability monitoring for biopharmaceutical production.
Drug discovery commands the established base. Environmental testing shows the steepest expansion through regulatory mandate extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese suppliers dominate precision optics exports for microplate instrumentation, while United States biopharma clusters drive import demand for high-throughput screening platforms. Trade flows concentrate between North American drug discovery hubs and European component manufacturers.
United States
FDA enforcement of 21 CFR Part 11 standards accelerates replacement cycles in pharmaceutical laboratories. Boston and San Diego biopharma clusters demand walkaway automation with LIMS-compatible outputs. The EPA's reference methods for microplate-based toxicity assays extend procurement into contract environmental laboratories beyond traditional pharma accounts.
Germany
Photomultiplier tube and filter component manufacturing anchors precision optics supply for global instrument builders. ISO 17025-accredited service providers in Bavaria and Baden-Württemberg fragment traditional bundled maintenance agreements. ECHA's REACH registration requirements mandate high-throughput toxicity screening that favors 1536-well density platforms.
China
NMPA regulatory pathways for in vitro diagnostic platforms are tightening design-control documentation for companion diagnostic microplate systems. Domestic production concentrates in automated liquid-handling modules for export to Asian contract research networks. Yangtze River Delta biotech parks are adopting multiplexing architectures for antibody screening campaigns.
Switzerland
Swissmedic quality system requirements align with ISO 13485 certification standards for clinical-grade instrument validation. Basel's pharmaceutical corridor drives demand for multimodal detection platforms spanning absorbance, fluorescence, and luminescence channels. Academic core facilities in Zurich and Geneva are unbundling service contracts from hardware procurement.
Singapore
Cultivated meat producers are adopting microplate-based nutrient optimization assays for bioreactor scaling, extending demand beyond pharmaceutical applications. The national food agency's novel food safety frameworks reference high-throughput screening protocols. Biopolis research cluster integrates automated microplate workflows into cellular agriculture development pipelines.
Microplate Instrumentation and Systems Market Competitive Landscape
Concentration sits with diversified life sciences conglomerates that leverage reagent-instrument bundling to sustain installed-base loyalty. The market structure tiers across three strategic archetypes: full-platform manufacturers with multimodal detection portfolios, precision optics specialists supplying photomultiplier components, and automated liquid-handling integrators. Competitive moves center on modular upgrade path development and third-party service contract capture.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify the bundling archetype, while Agilent Technologies anchors the multimodal detection tier. BMG LABTECH GmbH occupies a position within the precision optics specialist category. Tecan Group sits within the automated integration segment. These players represent distinct competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| PerkinElmer |
| Bio-Rad Laboratories |
| Tecan Group |
| BMG LABTECH GmbH |
| Corning Incorporated |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Photomultiplier tube substitution toward solid-state silicon photomultipliers is simultaneously shifting component sourcing from Japanese vacuum tube manufacturers to German and American semiconductor fabs while compressing per-unit detection module costs by eliminating high-voltage power supply requirements. This substitution dynamic is redistributing value capture across the microplate instrumentation supply chain and enabling tiered pricing architectures that separate research-grade from clinical-grade platform configurations.
Pricing Analysis
Pharmaceutical OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because academic core facilities are unbundling maintenance agreements and sourcing third-party calibration. Contract research organizations exhibit the highest price sensitivity, while GLP-compliant pharmaceutical laboratories absorb premium pricing for validation documentation.
Supply Chain Analysis
Photomultiplier tube manufacturing chokepoints in Hamamatsu and RIKEN facilities tether instrument builders to Japanese precision optics supply. German filter component production and Chinese automated liquid-handling module assembly complete the geographic concentration. Raw material dependencies span rare-earth phosphors, fused silica substrates, and precision-machined aluminum optical benches. Single-source vulnerability runs through photodetector supply. Distribution runs through direct sales forces for pharmaceutical accounts and distributor networks serving academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microplate instrumentation functions as a service-attach opportunity where recurring calibration and reagent supply contracts are expanding faster than hardware replacement cycles. The unbundling of maintenance agreements across European contract research organizations signals accelerating aftermarket revenue capture potential.
For Market Incumbents: Consolidate installed-base loyalty through reagent-instrument bundling that locks pharmaceutical accounts into proprietary detection chemistries. Acquire ISO 17025-accredited service providers in Germany and Switzerland to capture third-party calibration demand that is fragmenting traditional maintenance revenue. Flow cytometry substitution in immuno-oncology workflows threatens high-content screening positions, requiring multimodal detection platform investment to defend application breadth.
For New Entrants and Emerging Players: Differentiate on label-free biosensor architectures that eliminate reagent dependency and extend instrument utilization rates across 24-hour operations. Target cultivated meat producers in Singapore and Netherlands where nutrient optimization assay demand is emerging outside saturated pharmaceutical accounts. Pursue point-of-care diagnostics convergence in India and Brazil through miniaturized microplate formats that bypass centralized laboratory infrastructure requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision optics specialists holding photomultiplier tube manufacturing capabilities. The five-to-ten-year viability window favors platforms with existing FDA 510(k) clearances and EMA notified body relationships as regulatory elevation favors established builders. Monitor EMA MDR Article 10 compliance certification timelines as an inflection signal for European market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Bundling | Thermo Fisher Scientific's strategy locks pharmaceutical accounts into proprietary detection chemistries and sustains installed-base loyalty. |
| ISO 17025 Service Provider Acquisition | Captures third-party calibration demand from academic core facilities unbundling maintenance agreements in Germany and Switzerland. |
| Label-Free Biosensor Platform Launch | Eliminates reagent spend per screening campaign and extends utilization rates across Massachusetts and California biopharma clusters. |
| Cellular Agriculture Application Development | Opens cultivated meat producer demand in Singapore and Netherlands beyond saturated pharmaceutical accounts. |
| EMA MDR Article 10 Compliance Investment | Secures European oncology trial market access as regulatory elevation favors established instrument builders. |
Research Methodology
Initial hypotheses were tested against primary input from drug discovery executives, regulatory affairs leads, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary fieldwork combined structured interviews with instrument procurement decision-makers at pharmaceutical laboratories and contract research organizations. Secondary sources encompassed FDA 510(k) filings, EMA MDR technical documentation, ISO 13485 certification registries, and hospital procurement databases. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and application segmentation dimensions.
Variance decomposition across the projection horizon isolated volume drivers from price-mix effects within each segment. The analytical framework modeled detection modality adoption curves, replacement cycle timing by end-user tier, and regulatory compliance cost pass-through. Segmentation dimensions spanned product configuration, buyer maturity, technology architecture, and regional regulatory cluster. CAGRs were derived from fitted adoption curves rather than linear extrapolation. Forecast inputs incorporated 21 CFR Part 11 enforcement intensity and EPA reference method expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of electronic records standards or accelerated flow cytometry substitution would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle pacing and regulatory compliance cost trajectories. Practitioners should keep alternative scenarios live as EMA MDR implementation timelines and photomultiplier tube supply consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Disintegration Analyzer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Handheld XRF Analyzers Market