
 ICP-MS System Market | 2026-2036
ICP-MS System Market Size, Share, and Industry Trends Forecast 2026-2036
ICP-MS System Market Outlook
The gap between research-grade triple quadrupole systems and routine single quadrupole workhorses is rebalancing as pharmaceutical and environmental labs split their procurement strategies. Thermo Fisher Scientific leverages its installed base in proteomics to cross-sell high-resolution ICP-MS configurations into food safety networks. Agilent Technologies sustains pricing power through captive supply of collision cell consumables and application-specific method libraries. PerkinElmer anchors its position in emerging markets with compact benchtop systems designed for laboratories with limited infrastructure and technical staffing.
Inductively coupled plasma mass spectrometry (ICP-MS) is an elemental analysis technique that ionizes samples in an argon plasma at temperatures exceeding 6,000 Kelvin, then separates and quantifies ions by their mass-to-charge ratio using a quadrupole or time-of-flight analyzer, achieving detection limits in parts-per-trillion for most elements. Its primary industrial purpose spans environmental compliance monitoring, pharmaceutical quality control, and food safety verification where regulatory thresholds for toxic metals demand extreme analytical sensitivity. Quadrupole systems still occupy the largest revenue share due to their versatility across routine and research workflows, while triple quadrupole configurations are displacing older platforms in clinical toxicology and semiconductor-grade chemical analysis where spectral interferences compromise conventional detection. Time-of-flight technology leads growth in geochronology and isotope ratio applications where simultaneous full-spectrum acquisition accelerates sample throughput for mining exploration and nuclear forensics.
The EPA Safe Drinking Water Act and FDA ICH Q3D guideline jointly shape instrument specifications by mandating validated multi-element methods with documented uncertainty budgets for public health reporting. REACH and RoHS enforcement in Europe further tightens permissible thresholds for cadmium, lead, and mercury in consumer products and electronics supply chains, forcing manufacturers to deploy ICP-MS for incoming material verification. ISO 17025 accreditation requirements for testing laboratories create a compliance floor that sustains replacement demand even during capital expenditure contractions. Stakeholders must monitor how PFAS analytical method expansions redirect environmental lab budgets between LC-MS/MS and ICP-MS platforms, as dual-capability instrument investments reshape vendor competitive dynamics.
Market Dynamics
Pharmaceutical and environmental laboratories are splitting procurement strategies between high-resolution triple quadrupole systems and compact single quadrupole workhorses, creating divergent demand curves that reshape vendor product roadmaps and service bundling.
Growth Catalysts
- ICH Q3D Implementation:FDA's elemental impurities guidance mandates validated multi-element methods for drug safety, forcing pharmaceutical manufacturers to deploy ICP-MS for incoming raw material verification and finished product release testing.
- PFAS Monitoring Expansion:State-level mandates for per- and polyfluoroalkyl substances in drinking water are redirecting environmental laboratory budgets toward instruments capable of detecting trace-level elemental contaminants alongside organic analysis.
- Semiconductor Materials Purity:Fabrication facilities require sub-ppt detection limits for process chemicals, driving displacement of older atomic absorption platforms with collision-cell-equipped ICP-MS configurations.
Market Restraints
- Argon Supply Volatility:Plasma operation consumes 15-20 liters of high-purity argon per hour, and regional shortages in industrial gas distribution inflate operating costs for high-throughput laboratories.
- Technical Talent Scarcity:Method development for complex matrices requires expertise in mass spectral interferences and collision cell optimization, creating hiring bottlenecks in emerging market laboratories.
- High Instrument Capital Intensity:Triple quadrupole configurations demand upfront investments that strain budgets at mid-sized contract testing organizations, extending replacement cycles beyond typical depreciation schedules.
Strategic Opportunities
- Food Safety Networks:Expansion of heavy metal screening in imported agricultural products creates demand for portable and benchtop systems at border inspection facilities and regional testing hubs.
- Isotope Ratio Applications:Geochronology and nuclear forensics laboratories are adopting time-of-flight ICP-MS for simultaneous full-spectrum acquisition, opening specialized service revenue streams.
- India's PLI Scheme:Production-linked incentives for active pharmaceutical ingredient manufacturing are driving domestic laboratory infrastructure investment requiring elemental analysis capabilities.
Industry Challenges
- ISO 17025 Accreditation Timelines:Method validation and uncertainty budgeting for multi-element protocols extend certification cycles, delaying revenue generation for new laboratory entrants.
- Legacy LIMS Integration:Data transfer protocols between modern ICP-MS software and older laboratory information management systems require custom middleware development, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICP-MS System Market |
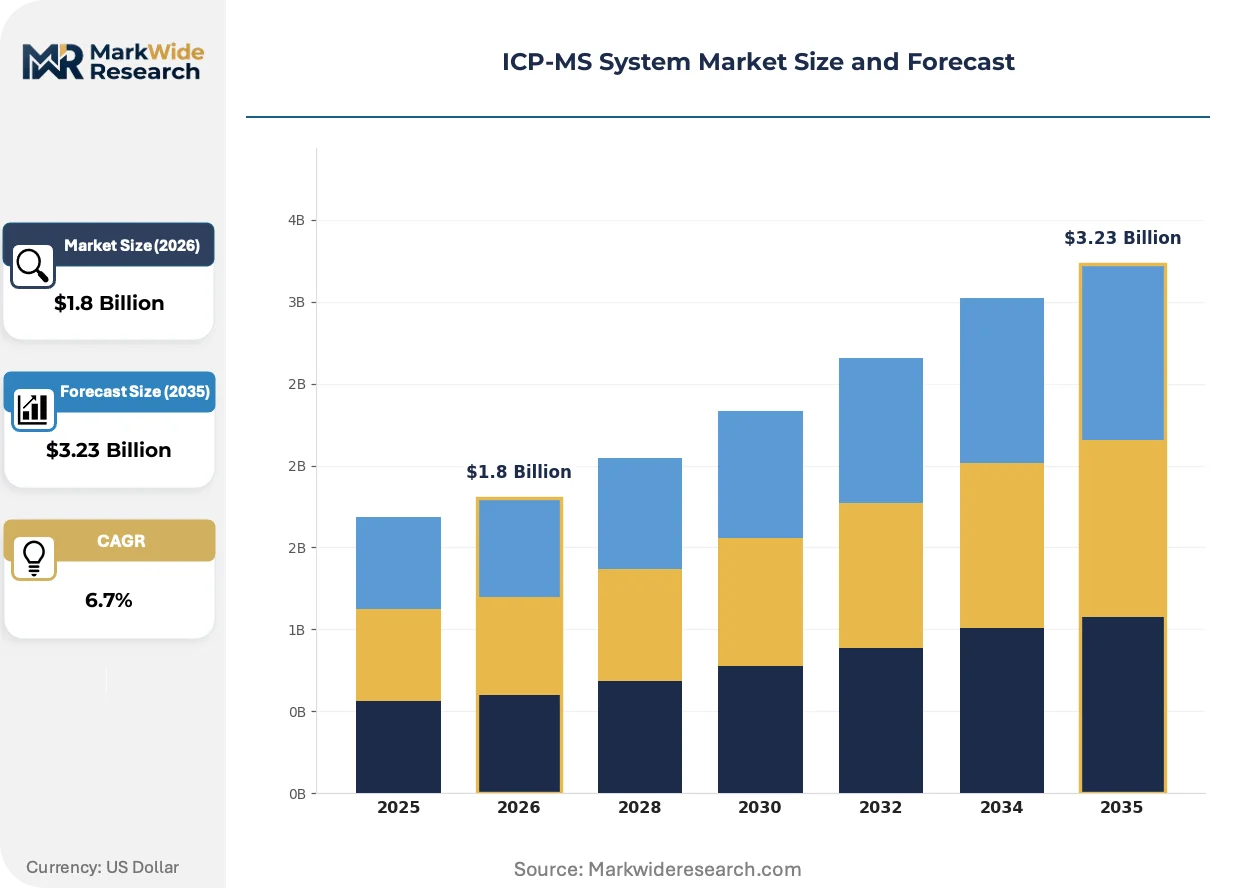
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrupole, Time-of-Flight, Triple Quadrupole, Single Quadrupole End User: Environmental Testing Labs, Pharmaceutical Companies, Food & Beverage Industries, Chemical Research Institutions Application: Trace Element Analysis, Isotope Ratio Analysis, Heavy Metal Detection, Nutritional Analysis Technology: Mass Spectrometry, Switching Valve Technologies, Sample Introduction, Plasma Generation Technologies |
| Companies Covered | Shimadzu Corporation, Nu Instruments, Agilent Technologies, Intertek Group, Analytik Jena GmbH, Thermo Fisher Scientific, HORIBA, Skyray Instrument, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICP-MS System Market Strategic Shifts
Laboratory instrumentation vendors are converging hardware miniaturization with cloud-native data platforms, collapsing the traditional trade-off between analytical performance and operational accessibility for resource-constrained facilities.
Collision/reaction cell technology is integrating selective ion-molecule chemistry to suppress polyatomic interferences in complex matrices like seawater and biological fluids. Environmental monitoring stations in coastal regions are adopting these configurations for automated, unattended arsenic and selenium quantification. The technology is integrating method development expertise directly into instrument firmware, reducing reliance on specialized operators.
REACH enforcement in Europe tightens permissible thresholds for cadmium, lead, and mercury in consumer electronics supply chains. Manufacturers must deploy ICP-MS for incoming material verification to demonstrate compliance with RoHS substance restrictions. Electronics assembly facilities in Germany and the Netherlands are prioritizing instruments with automated sample handling to manage high-volume screening workflows.
Service unbundling is separating hardware procurement from application support and method development contracts. Pharmaceutical quality control departments are negotiating standalone training packages and per-sample remote troubleshooting rather than comprehensive maintenance agreements. This pattern concentrates in the United States, where laboratory directors seek operational flexibility amid budget cycle uncertainty.
ICP-MS System Market Segmentation
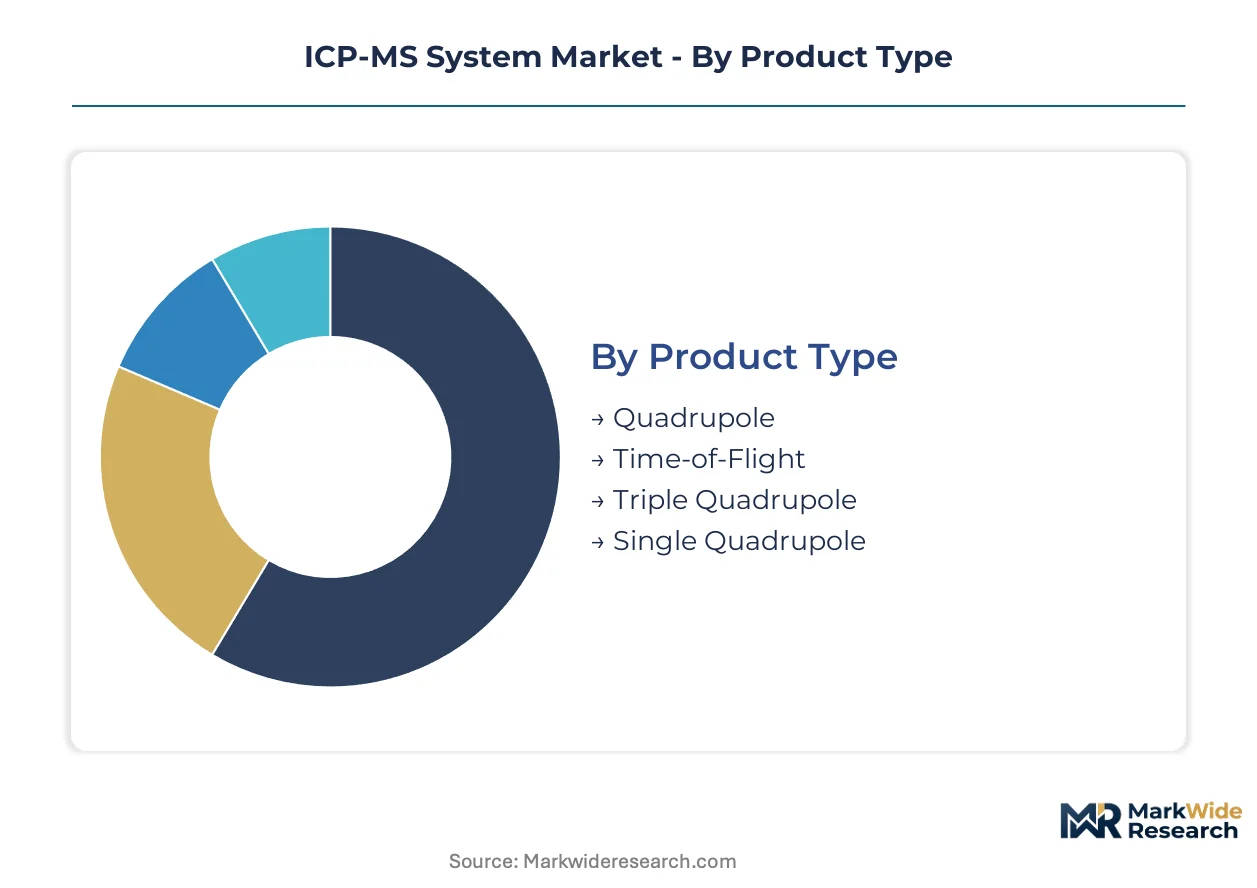
ICP-MS instrument portfolios split across detector architectures, plasma technologies, and customer workflows that each command distinct service bundles and replacement cadences. Upgrade cycles diverge sharply between routine compliance labs and research-intensive facilities, creating tiered vendor engagement models.
Product Type:
Replacement cycles stretch from seven years for routine single quadrupole workhorses to four-year refresh rates for triple quadrupole platforms in semiconductor-grade applications.
- Quadrupole:These systems employ four parallel rods generating oscillating electric fields that filter ions by mass-to-charge ratio, delivering sub-ppb detection limits across most elements. Demand clusters in United States municipal water laboratories facing EPA Safe Drinking Water Act enforcement, where validated multi-element methods must process high sample volumes with minimal operator intervention.
- Triple Quadrupole:Tandem mass configuration adds a second quadrupole collision cell between analyzers, enabling selective reaction monitoring that eliminates polyatomic interferences in complex matrices. Pharmaceutical quality control departments in Germany and Switzerland deploy these for ICH Q3D compliance, where documented uncertainty budgets for arsenic, cadmium, and mercury impurities require interference-free quantification.
- Time-of-Flight:Simultaneous full-spectrum acquisition without scanning delivers rapid isotope ratio precision for geochronology applications.
- Single Quadrupole:Compact benchtop footprint and simplified electronics reduce capital outlay for emerging market environmental monitoring stations.
Volume placements concentrate in Quadrupole configurations; the faster expansion belongs to Triple Quadrupole systems displacing older platforms in regulated pharmaceutical workflows.
End User:
Customer procurement authority varies from centralized capital committees at multinational pharmaceutical firms to decentralized purchasing at regional contract testing organizations.
- Environmental Testing Labs:These facilities process regulatory compliance samples for EPA, ECHA, and state-level PFAS monitoring programs, requiring instruments with automated sample handling and 24-hour unattended operation. United States utilities facing tightened drinking water standards for lead and emerging contaminants are consolidating vendor relationships around service response time guarantees rather than hardware specifications alone.
- Pharmaceutical Companies:Quality control and analytical development departments validate elemental impurity methods per ICH Q3D, with raw material verification and finished product release testing driving instrument redundancy requirements. Facilities in India under the PLI scheme for active pharmaceutical ingredient manufacturing are building captive analytical capabilities rather than outsourcing to contract research organizations.
- Food & Beverage Industries:Heavy metal screening in imported agricultural products demands portable and benchtop systems at border inspection facilities.
- Chemical Research Institutions:Method development for novel materials and nuclear forensics applications prioritizes time-of-flight configurations with flexible software architecture.
Capital deployment is heaviest among Pharmaceutical Companies; the steepest expansion trajectory is appearing in Environmental Testing Labs responding to state-level monitoring mandates.
Application:
Method validation requirements differ substantially between routine compliance screening and research-grade isotope ratio precision work.
- Trace Element Analysis:Multi-element quantification at parts-per-trillion sensitivity underpins environmental compliance, pharmaceutical safety, and semiconductor materials verification. United States fabricators require sub-ppt detection for process chemicals, displacing atomic absorption platforms with collision-cell-equipped configurations.
- Heavy Metal Detection:Regulatory thresholds for lead, cadmium, mercury, and arsenic in drinking water and food products mandate extreme analytical sensitivity with documented measurement uncertainty. REACH and RoHS enforcement in Europe tightens permissible thresholds, forcing electronics manufacturers to deploy ICP-MS for incoming material verification at assembly facilities in Germany and the Netherlands.
- Isotope Ratio Analysis:Geochronology and nuclear forensics laboratories require simultaneous full-spectrum acquisition.
- Nutritional Analysis:Essential element quantification in dietary supplements and fortified foods supports label claim verification.
Method development concentrates in Trace Element Analysis; Isotope Ratio Analysis is climbing the fastest as mining exploration and nuclear safeguard applications expand.
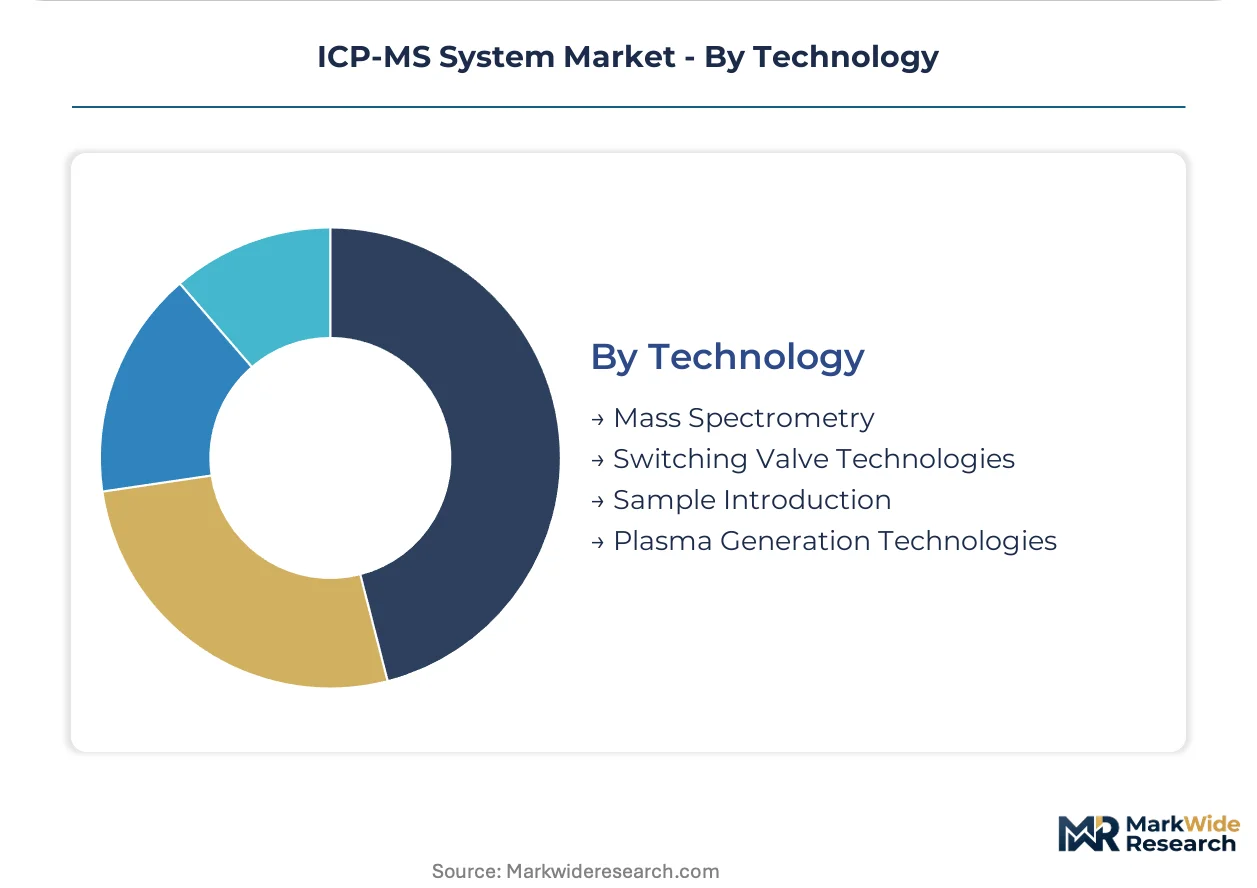
Technology:
Component-level innovation in plasma generation and sample introduction systems increasingly determines competitive differentiation beyond core mass analyzer architecture.
- Mass Spectrometry:Quadrupole, time-of-flight, and tandem configurations represent the core detection platforms, with collision/reaction cell integration now standard for interference suppression. Environmental monitoring stations in coastal Japan and California are adopting selective ion-molecule chemistry for automated arsenic and selenium quantification in seawater matrices.
- Plasma Generation Technologies:Solid-state RF generators at 27.12 MHz or 40.68 MHz replace older crystal-controlled designs, improving plasma stability and reducing argon consumption. High-throughput laboratories in China and South Korea prioritize these configurations to mitigate operating cost volatility from regional industrial gas supply constraints.
- Sample Introduction:Automated dilution, online digestion, and laser ablation accessories expand matrix compatibility.
- Switching Valve Technologies:Rapid stream selection enables sequential analysis of diverse sample types without manual intervention.
Hardware shipments concentrate in Mass Spectrometry platforms; Plasma Generation Technologies are gaining share fastest as energy efficiency and gas consumption become procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's pharmaceutical corridor drives concentrated ICP-MS procurement for elemental impurity testing under FDA oversight. Instrument vendors prioritize service infrastructure around this cluster to capture recurring maintenance revenue from quality control laboratories.
United States
EPA Safe Drinking Water Act enforcement and state-level PFAS monitoring mandates compel municipal utilities to upgrade detection capabilities. FDA's ICH Q3D guidance forces pharmaceutical manufacturers in Massachusetts and New Jersey to deploy validated multi-element methods. Environmental testing labs in California's Central Valley automate arsenic and selenium quantification for agricultural compliance.
Germany
REACH and RoHS enforcement tightens permissible thresholds for cadmium, lead, and mercury in consumer electronics supply chains. ECHA substance restrictions force manufacturers to verify incoming materials at assembly facilities in Bavaria and Baden-Württemberg. Automated sample handling systems dominate procurement in the Rhine-Main industrial corridor.
China
Semiconductor fabrication facilities in Shanghai and Shenzhen require sub-ppt detection limits for process chemicals. MIIT domestic production incentives accelerate laboratory infrastructure investment for materials verification. Solid-state RF generators gain preference in high-throughput labs to mitigate regional argon supply volatility.
India
PLI scheme incentives for active pharmaceutical ingredient manufacturing drive captive analytical capability building in Gujarat and Maharashtra. CDSCO quality standards elevate elemental impurity testing requirements for export-oriented drug producers. Contract testing organizations in Hyderabad expand collision-cell-equipped platforms for heavy metal screening.
Japan
Coastal environmental monitoring stations adopt selective ion-molecule chemistry for automated seawater analysis. METI industrial standards enforce trace element verification in electronics supply chains. Geochronology laboratories in Tokyo and Osaka deploy time-of-flight configurations for isotope ratio precision work.
ICP-MS System Market Competitive Environment
Premium-margin players sit above commodity-margin players across service bundling and application-specific method libraries. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with cross-selling leverage, specialized analytical instrumentation firms with captive consumables revenue, and emerging market-focused compact system providers. Consolidation pressures concentrate among mid-scale regional distributors lacking direct service capabilities. Competitive moves center on unbundling maintenance contracts from hardware sales and deepening collision cell technology integration.
Among diversified analytical instrumentation providers, Thermo Fisher Scientific, Agilent Technologies, and PerkinElmer occupy positions spanning premium research-grade and routine compliance segments. Thermo Fisher leverages proteomics installed base relationships to cross-sell high-resolution configurations. Agilent sustains pricing power through captive supply of collision cell consumables. PerkinElmer anchors emerging market penetration with compact benchtop systems designed for laboratories with limited infrastructure. These three represent distinct archetypes: cross-selling platform leverage, consumables-anchored recurring revenue, and accessibility-focused geographic expansion.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Nu Instruments |
| Agilent Technologies |
| Intertek Group |
| Analytik Jena GmbH |
| Thermo Fisher Scientific |
| HORIBA |
| Skyray Instrument |
| PerkinElmer |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up service networks in the United States and Germany have consolidated regional maintenance providers, tightening vendor pricing discipline while extending payment terms for collision cell consumables and argon supply contracts. This ownership concentration feeds directly into procurement leverage at environmental testing labs and pharmaceutical quality control departments, where bundled service agreements now dominate capital allocation decisions.
Pricing Analysis
Value-based pricing anchored to instrument uptime guarantees and validated method throughput now dominates triple quadrupole configurations, with pharmaceutical manufacturers in Massachusetts and New Jersey paying premium rates for documented uncertainty budgets under FDA ICH Q3D enforcement. Three-tier pricing structure across premium, standard, and economy levels separates collision-cell-equipped research systems from routine single quadrupole workhorses and compact benchtop units for emerging markets. Cost compression in the economy tier is intensifying because PerkinElmer and Skyray Instrument compete on footprint and simplified electronics for Indian and Chinese environmental monitoring stations. Contract testing organizations exhibit the highest price sensitivity, while semiconductor fabricators prioritize sub-ppt detection limits over capital outlay.
Supply Chain Analysis
Freight costs for high-purity argon cylinders and solid-state RF generator components from Germany, Japan, and the United States have risen substantially, compressing margins for vendors serving coastal environmental monitoring stations in California and Japan. Component sourcing draws from precision-machined quadrupole rod assemblies in Switzerland, detector electronics in South Korea, and plasma torch ceramics in Germany. Single-source vulnerability concentrates in collision cell consumables, where Agilent Technologies maintains captive supply relationships that constrain third-party alternatives. Distribution runs through direct field service organizations in North America and Europe, with regional distributors handling emerging market placements where technical staffing limitations favor compact system configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ICP-MS system market has become a vertical-integration race, with incumbents pursuing backward integration into collision cell consumables and argon supply logistics to defend service margins against unbundling pressures from pharmaceutical quality control departments.
For Market Incumbents: Anchor defensive positioning through captive supply of application-specific method libraries and automated sample handling accessories that raise switching costs for environmental testing labs facing EPA enforcement. Consolidate regional service networks in the United States and Germany to capture recurring maintenance revenue from FDA ICH Q3D compliance workflows. Capacity addition in India under the PLI scheme for active pharmaceutical ingredient manufacturing offers a geographic lever to offset pricing softness in mature markets. For New Entrants and Emerging Players: The gap between premium triple quadrupole systems and economy single quadrupole configurations creates entry space for compact benchtop specialists targeting India's contract testing organizations and China's semiconductor materials verification labs. Food safety networks at border inspection facilities represent the most penetrable segment, with portable systems for heavy metal screening in imported agricultural products offering a defined go-to-market angle through regional testing hubs in Gujarat and Maharashtra. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale collision cell technology specialists in Germany and Japan with established ISO 17025 method validation capabilities but constrained direct service footprints. Long-term viability hinges on integration into diversified life science conglomerates with cross-selling leverage across proteomics and food safety networks. Watch for PFAS analytical method expansions redirecting environmental lab budgets between LC-MS/MS and ICP-MS platforms as the inflection indicator for vendor competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Collision Cell Technology Integration | Selective ion-molecule chemistry suppresses polyatomic interferences in complex seawater and biological matrices. |
| Backward Integration into Consumables | Captive supply of reaction cell gases and replacement quadrupole rods defends service margins against unbundling. |
| Compact Benchtop System Development | Simplified electronics and reduced argon consumption address infrastructure constraints in Indian and Chinese laboratories. |
| Cloud-Native Data Platform Deployment | Remote diagnostics and automated method development reduce reliance on specialized operators at environmental monitoring stations. |
| Geographic Expansion into India | PLI scheme incentives for active pharmaceutical ingredient manufacturing drive captive analytical capability building in Gujarat and Maharashtra. |
Study Parameters
Document review covered FDA ICH Q3D guidance documents, EPA Safe Drinking Water Act enforcement records, and ECHA REACH substance restriction filings, complemented by interviews with laboratory directors at environmental testing facilities, quality control managers at pharmaceutical manufacturers, and procurement leads at semiconductor fabrication facilities. Secondary validation drew from instrument vendor SEC filings, ISO 17025 accreditation databases, and customs records for high-purity argon trade flows. Bottom-up triangulation across installed base estimates and top-down validation against capital expenditure disclosures at municipal utilities and contract testing organizations ensured cross-verification of market sizing assumptions.
Segment-level projections across quadrupole, triple quadrupole, and time-of-flight configurations incorporated end-user procurement authority variations, from centralized capital committees at multinational pharmaceutical firms to decentralized purchasing at regional contract testing organizations. CAGRs were derived from replacement cycle analysis spanning seven-year refresh rates for routine single quadrupole workhorses to four-year cycles for semiconductor-grade triple quadrupole platforms. Argon supply volatility indices and collision cell technology adoption curves served as industry-specific forecast inputs throughout the modeling period.
Inputs from FDA enforcement actions and state-level PFAS monitoring mandates were available through the study window; gaps in real-time capital expenditure data at private contract testing organizations introduce uncertainty bands around replacement demand estimates. Forecasts reflect assumptions regarding regulatory enforcement continuity and argon supply chain stability. Stakeholders should weight assumptions against their own operating context, particularly regarding regional industrial gas distribution constraints and technical talent availability for method development in complex matrices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Dew Point Analyzer Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Global Infrared Thermography Market