
 Battery Testers and Analyzers Market | 2026-2036
Battery Testers and Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Testers and Analyzers Market Analytics
Project finance for battery gigafactory test lines is reshaping competitive dynamics, allowing mid-tier equipment vendors to bid against established players. Keysight Technologies leverages its RF measurement heritage to dominate high-frequency impedance analysis for solid-state prototypes. Chroma ATE Inc. sustains cost leadership through captive manufacturing of power electronic loads in Taiwan. Arbin Instruments specializes in multi-channel cyclers for grid-scale storage validation, competing on channel density rather than brand breadth.
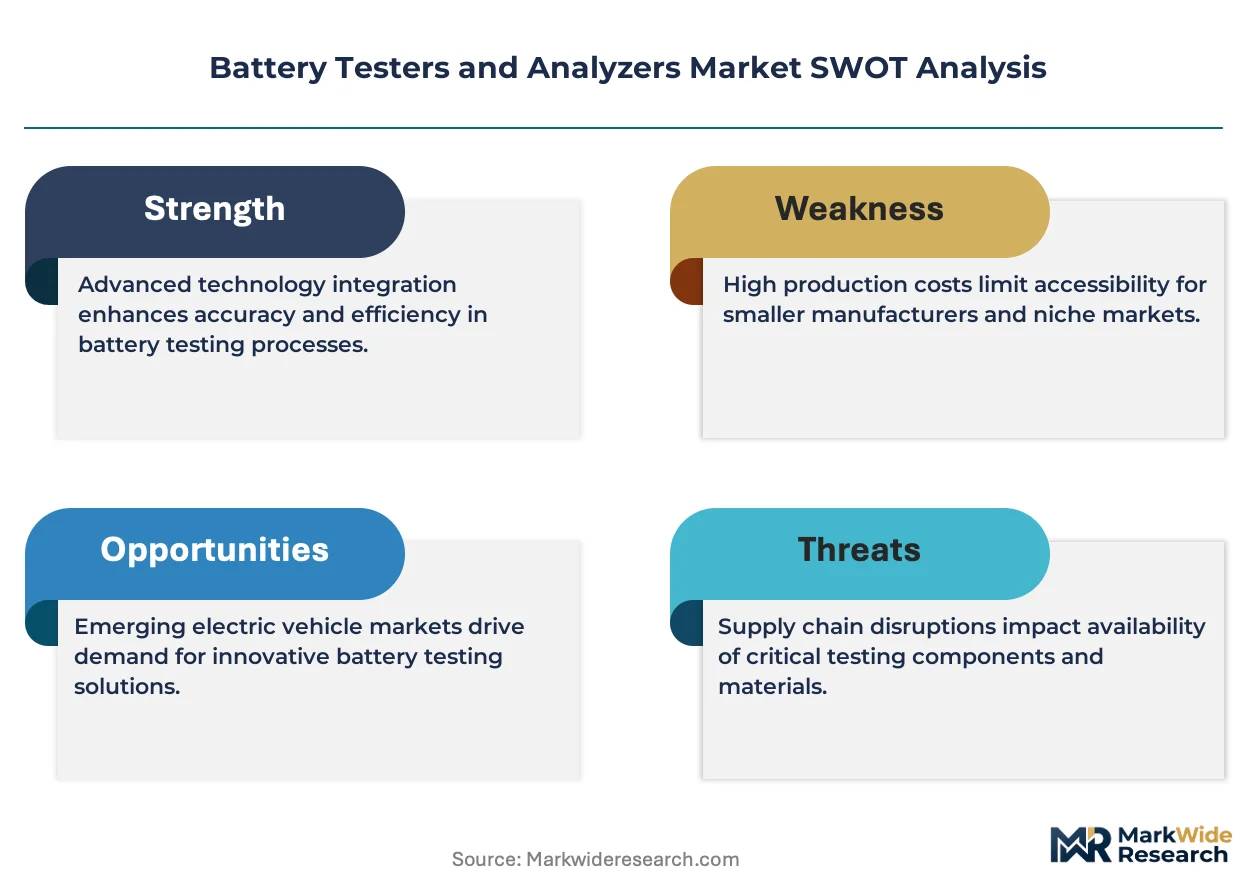
Battery testers and analyzers are electrochemical diagnostic instruments that apply controlled current loads, impedance spectroscopy, or conductance pulses to quantify state-of-charge, state-of-health, and internal resistance across cell chemistries including lithium-ion, nickel-metal hydride, and lead-acid. Their primary purpose is to prevent catastrophic failure, optimize replacement timing, and certify warranty compliance in energy storage systems. Microprocessor-based testing equipment commands the dominant revenue share due to embedded algorithmic compensation for temperature and aging effects, while non-destructive methods are displacing traditional load testing in automotive warranty networks where cell removal proves impractical. Automated testing lines serve manufacturers with throughput requirements exceeding ten thousand cells per hour, whereas manual testers retain relevance in aftermarket service bays where capital constraints predominate.
FDA oversight of medical device batteries and EPA hazardous waste rules for lead-acid disposal shape product design requirements in the United States, while REACH compliance in Europe restricts cadmium and mercury in tester probe alloys, forcing material substitutions. The EU Battery Regulation's digital passport mandate will require testers to generate machine-readable health records, altering software architecture priorities. Stakeholders must monitor how ISO 17025 accreditation requirements evolve for third-party battery certification labs, as this determines which equipment vendors qualify for procurement shortlists.
Market Dynamics
Electrochemical impedance spectroscopy is displacing DC load testing as the dominant validation protocol, compressing cycle times from hours to minutes while demanding recalibration of lab infrastructure across automotive and grid storage certification chains.
Growth Catalysts
- EU Battery Regulation:Digital passport mandates require machine-readable state-of-health records, forcing fleet operators and recyclers to upgrade diagnostic hardware before compliance deadlines.
- Solid-state prototyping:Lithium-metal anode development programs need specialized high-frequency impedance analyzers that legacy DC cyclers cannot replicate.
- Germany:Automotive OEMs operate the densest concentration of large-scale battery validation labs in Europe, creating sustained equipment procurement velocity.
Market Restraints
- Probe alloy supply:REACH restrictions on cadmium and mercury in tester contacts force material substitutions that extend lead times for European manufacturers.
- Semiconductor input costs:Power electronic load components face pricing volatility from Taiwan foundry capacity constraints.
- Calibration standard fragmentation:Competing national metrology institutes issue non-harmonized reference protocols, complicating cross-border certification.
Strategic Opportunities
- Second-life EV battery grading:Stationary storage integrators need low-cost diagnostic tools to sort retired automotive cells by remaining capacity.
- India:PLI scheme incentives for domestic cell manufacturing are driving demand for in-line test equipment at planned gigafactory sites.
- AI-driven predictive maintenance:Cloud-connected testers enable fleet operators to shift from scheduled replacement to condition-based asset management.
Industry Challenges
- Electrochemical modeling expertise:Equipment vendors struggle to hire battery scientists capable of translating cell degradation mechanisms into embedded diagnostic algorithms.
- ISO 17025 accreditation timelines:Third-party certification labs face 18-24 month approval cycles that delay equipment vendor qualification for procurement shortlists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Testers and Analyzers Market |
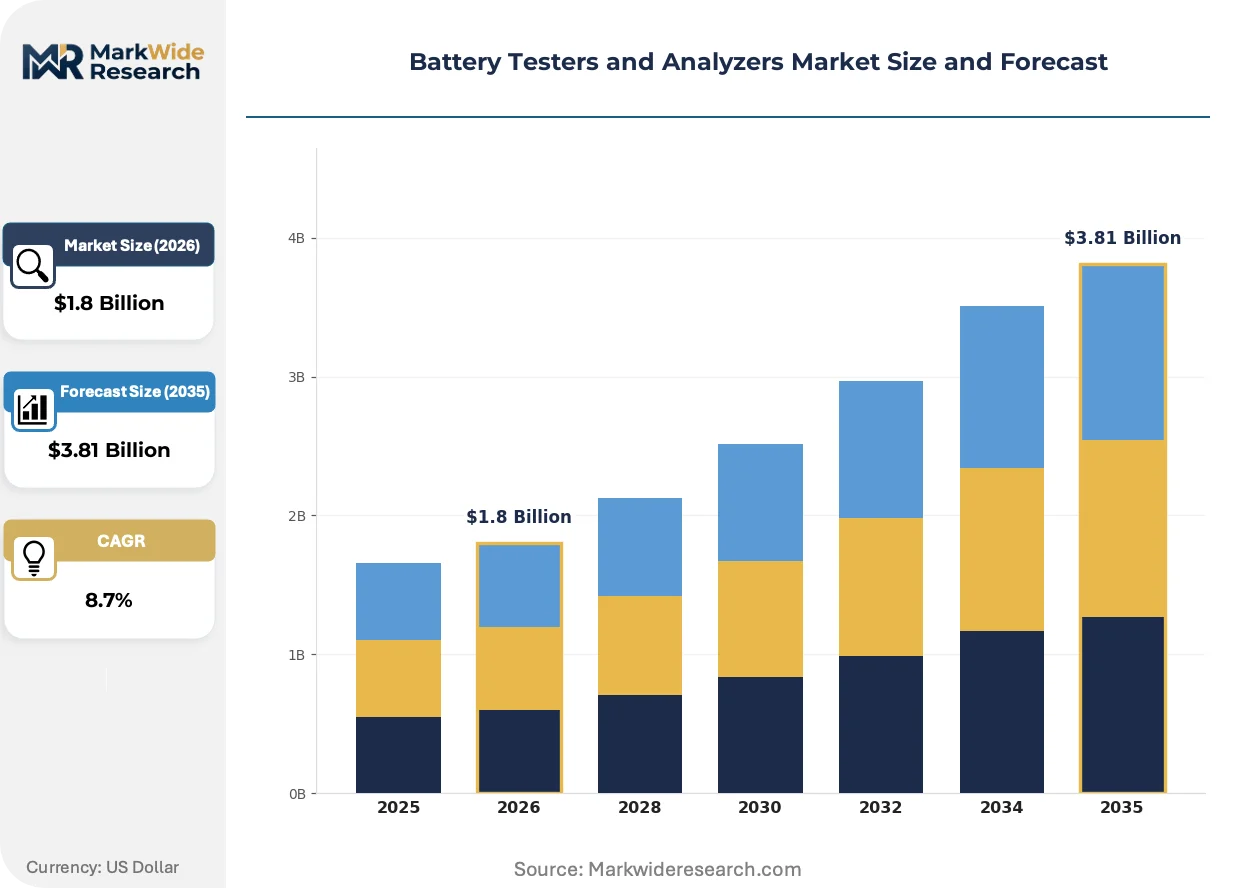
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductance Testers, Digital Battery Testers, Load Testers, Analog Testers Application: Automotive, Renewable Energy, Telecommunications, Consumer Electronics End User: Manufacturers, Service Providers, Distributors, Retailers Technology: Microprocessor-Based, Non-Destructive, Automated Testing, Manual Testing |
| Companies Covered | Keysight Technologies, Fluke Corporation, Chroma ATE Inc., Arbin Instruments, Ametek Inc., Megger Group, Cadex Electronics Inc., Hioki E.E. Corporation, National Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Testers and Analyzers Market Evolving Landscape
Diagnostic architectures are converging around embedded intelligence and connectivity, transforming standalone instruments into nodes within broader battery lifecycle management systems.
Cloud-native testing platforms are digitizing how validation data flows between cell manufacturers, automotive OEMs, and recyclers. These systems enable real-time algorithm updates without hardware replacement. Tier-1 battery suppliers in South Korea and Japan are piloting subscription-based firmware models that compress capital expenditure into operational budgets.
REACH compliance in Europe is forcing redesign of probe metallurgy and contact chemistries. Equipment manufacturers must document substance declarations across complex supply chains. The regulatory burden falls heaviest on mid-tier vendors serving aftermarket service networks, who lack dedicated compliance teams.
Fleet procurement patterns are fragmenting as electric bus and truck operators build in-house diagnostic capabilities rather than relying on dealer networks. This bypasses traditional distribution channels concentrated in automotive service equipment. The shift is most visible in California and Germany, where zero-emission mandates have created the largest commercial EV fleets.
Battery Testers and Analyzers Market Segmentation
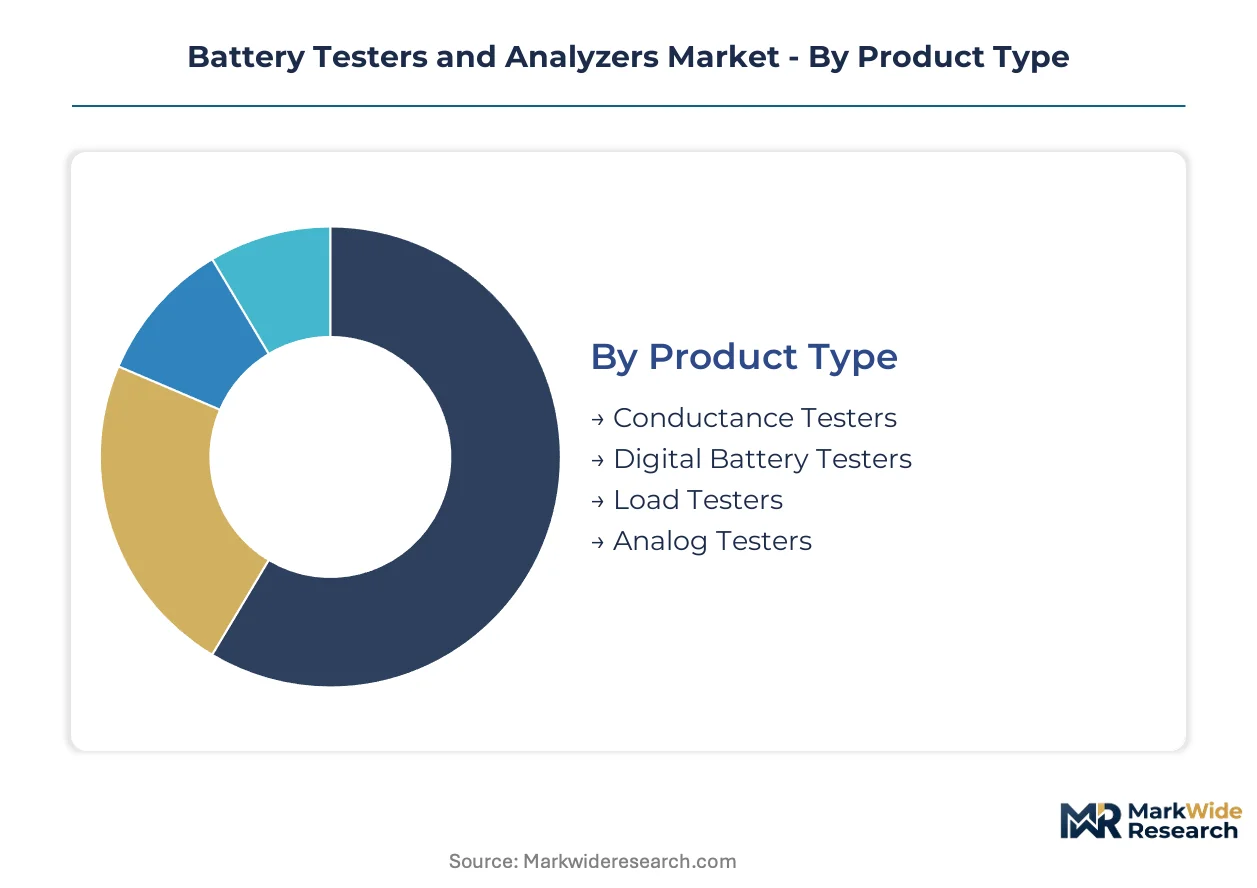
Battery testers and analyzers serve divergent operational environments—from high-throughput gigafactory lines to aftermarket service bays—demanding equipment configurations that trade speed against capital cost and diagnostic depth. Segmentation reveals how vendor portfolios align with these tension points across product architecture, use case, and customer procurement power.
Product Type:
Mature electrochemical methods now compete with emerging digital architectures that embed algorithmic compensation for temperature drift and aging curves.
- Conductance Testers:These instruments apply low-frequency AC signals to measure internal resistance and state-of-health without deep discharge cycles. Automotive warranty networks in Germany and the United States favor conductance methods for their sub-minute test duration, though calibration drift remains a documented pain point in high-temperature service environments.
- Digital Battery Testers:Microprocessor-controlled units with LCD readouts dominate aftermarket service channels where technicians require pass/fail clarity without specialized training. Fleet operators in California's zero-emission bus programs specify digital testers for driver-accessible daily diagnostics, compressing reliance on dealer networks.
- Load Testers:Traditional DC load banks apply controlled discharge currents to verify cold-cranking amp ratings in lead-acid starter batteries.
- Analog Testers:Simple voltage and hydrometer-based instruments persist in emerging market service bays with severe capital constraints.
Conductance testers handle the majority of throughput in automotive certification chains; digital battery testers are expanding most quickly in commercial fleet internalization trends.
Application:
Cost tier separation is pronounced: high-reliability applications justify premium impedance spectroscopy equipment, while price-sensitive segments tolerate reduced diagnostic granularity.
- Automotive:OEM validation labs and EV fleet operators drive demand for multi-channel cyclers and high-frequency analyzers capable of solid-state prototype characterization. The EU Battery Regulation's digital passport mandate is forcing upgrades across German and French automotive clusters.
- Renewable Energy:Grid-scale storage integrators require diagnostic tools for second-life EV battery grading, sorting retired automotive cells by remaining capacity for stationary deployment. California and Texas utility-scale projects are piloting automated testing lines for containerized battery systems.
- Telecommunications:Tower operators prioritize compact, rack-mounted testers for remote monitoring of backup power systems.
- Consumer Electronics:High-volume cell phone and laptop manufacturers favor in-line automated testing with sub-second cycle times.
Automotive commands the dominant equipment spend; renewable energy is gaining share fastest as battery storage deployments accelerate.
End User:
Volume concentration varies sharply: manufacturers procure automated lines by the hundred-unit scale, while service providers purchase single-unit instruments with extended payment terms.
- Manufacturers:Cell and pack producers operate the densest concentrations of testing equipment, with South Korean and Japanese tier-1 suppliers piloting subscription-based firmware models that convert capital expenditure to operational budgets.
- Service Providers:Independent repair shops and dealer networks represent fragmented, price-sensitive demand concentrated in aftermarket automotive channels.
- Distributors:Equipment resellers require demonstration and calibration units to support regional sales networks.
- Retailers:Consumer-facing battery retailers stock entry-level testers for warranty verification and cross-selling opportunities.
Manufacturers absorb the majority of high-value equipment shipments; service providers are the fastest-expanding customer type as fleet operators build in-house diagnostic capabilities.
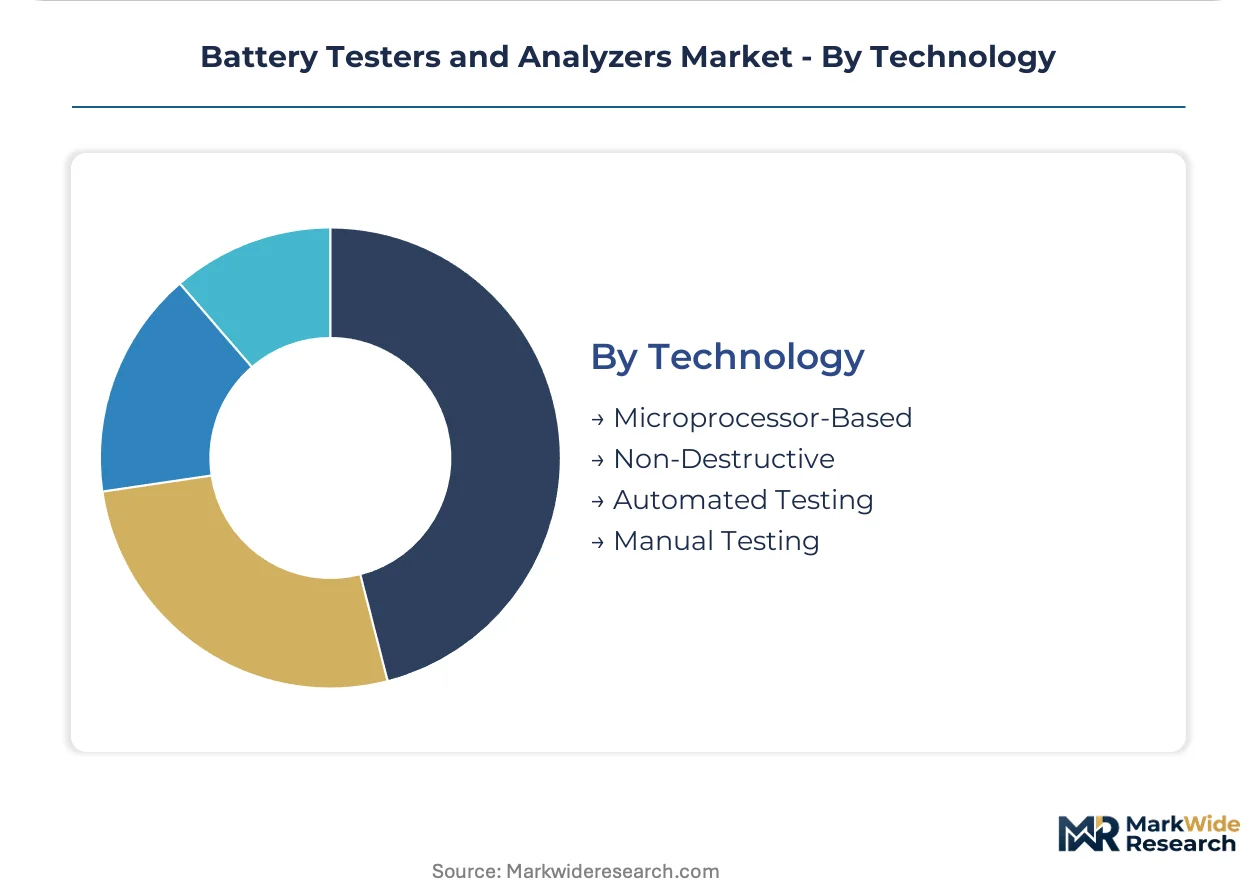
Technology:
Margin structures diverge: microprocessor-based and automated systems command premium pricing, while manual methods compete on first-cost minimization.
- Microprocessor-Based:Embedded algorithmic compensation for temperature and aging effects enables diagnostic accuracy across lithium-ion, nickel-metal hydride, and lead-acid chemistries. These systems dominate revenue share due to their versatility in multi-chemistry environments.
- Non-Destructive:Electrochemical impedance spectroscopy and conductance methods are displacing traditional load testing in automotive warranty networks where cell removal proves impractical, compressing test cycles from hours to minutes.
- Automated Testing:In-line systems serve manufacturers with throughput requirements exceeding ten thousand cells per hour.
- Manual Testing:Handheld and benchtop instruments retain relevance in aftermarket service bays where capital constraints predominate and technician labor cost is below equipment amortization thresholds.
Microprocessor-based technology anchors the installed base; non-destructive methods are climbing the fastest as impedance spectroscopy protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment vendors command 20-25% pricing premiums over Taiwanese counterparts in automotive validation contracts, while Indian procurement budgets for gigafactory test lines remain 40% below European benchmarks despite accelerating volume commitments.
Germany
BMW, Volkswagen, and Mercedes-Benz operate Europe's densest network of battery validation labs, driving sustained demand for high-channel cyclers and impedance spectroscopy systems. The EU Battery Regulation's digital passport mandate forces OEMs to upgrade diagnostic hardware by 2027. Stuttgart and Munich host concentrated procurement activity for solid-state prototype testing equipment.
United States
EPA hazardous waste rules for lead-acid battery disposal shape tester design requirements, while FDA oversight of medical device batteries creates dual-compliance procurement criteria. California's zero-emission bus mandates push fleet operators toward in-house diagnostic capabilities, bypassing traditional dealer networks in Los Angeles and San Francisco Bay Area clusters.
China
CATL and BYD expansion programs absorb automated testing lines at throughput scales exceeding ten thousand cells per hour. MIIT battery safety standards mandate state-of-health documentation for energy storage system deployments. Shenzhen and Shanghai concentrate domestic equipment procurement, though high-frequency impedance analyzers for solid-state development still import from Western vendors.
India
PLI scheme incentives for domestic cell manufacturing drive demand for in-line test equipment at planned gigafactory sites in Gujarat and Tamil Nadu. Central Electricity Authority grid codes require battery storage systems to demonstrate cycle-life certification. Reliance Industries and Ola Electric anchor validation lab investments in the Mumbai-Pune corridor.
South Korea
LG Energy Solution and Samsung SDI pilot subscription-based firmware models that convert capital expenditure to operational budgets. MFDS medical device battery regulations create specialized tester requirements for healthcare applications. Seoul Capital Area concentrates R&D procurement for next-generation solid-state characterization equipment.
Battery Testers and Analyzers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power electronics and probe metallurgy. The vendor base separates into three functional layers: full-stack diagnostic platforms, modular test equipment, and consumable probe suppliers. Consolidation pressure concentrates at the platform tier where automotive OEMs demand single-source accountability for validation lab outcomes. Competitive moves center on backward integration into semiconductor load manufacturing and cloud-native firmware architectures that enable recurring revenue streams.
Within the platform integrator tier, Keysight Technologies and Chroma ATE Inc. exemplify divergent geographic positioning—Keysight leverages RF measurement heritage from its Santa Rosa, California base, while Chroma sustains cost leadership through captive manufacturing in Taiwan. Arbin Instruments occupies a specialized position in multi-channel cyclers for grid-scale storage validation. These three companies represent distinct strategic archetypes: technology heritage, manufacturing scale, and application-specific channel density.
| Leading Market Players |
|---|
| Keysight Technologies |
| Fluke Corporation |
| Chroma ATE Inc. |
| Arbin Instruments |
| Ametek Inc. |
| Megger Group |
| Cadex Electronics Inc. |
| Hioki E.E. Corporation |
| National Instruments |
| Others |
Value Network & Pricing Analysis
Shanghai-Rotterdam container freight corridors transmit semiconductor load component pricing volatility directly into European equipment manufacturer cost structures, compressing margins for mid-tier vendors while enabling German and Taiwanese incumbents to sustain premium positioning through captive supply arrangements.
Pricing Analysis
Configured-to-order pricing for multi-channel cyclers and impedance spectroscopy systems commands spreads of 40-60% above standard digital tester SKUs, with ISO 17025 certification tier and automotive OEM brand accreditation serving as the primary price differentiation drivers. Pricing pressure stems from Taiwan foundry capacity constraints on power electronic loads, which disproportionately squeezes mid-tier vendors lacking backward integration into semiconductor manufacturing. Fleet operators and aftermarket service providers represent the polar extremes of buyer price sensitivity, with commercial EV bus operators in California and Germany tolerating premium hardware costs for embedded connectivity while independent repair shops in emerging markets resist capital outlays above economy-tier analog instruments.
Supply Chain Analysis
Hon Hai Precision Industry and Pegatron concentrate contract manufacturing capacity for digital battery tester assembly, with additional foundry support from Jabil and Flex in Mexico and Eastern Europe serving regional fulfillment hubs. Taiwan, China, and South Korea anchor geographic supply concentration for power semiconductors, probe metallurgy, and precision resistive loads, while REACH-compliant cadmium-free probe alloys draw from specialized German and Japanese material suppliers. Single-source vulnerability in high-frequency impedance analyzer ASICs creates structural risk for solid-state characterization equipment, with distribution running through direct OEM channels for automated lines and authorized distributor networks for aftermarket handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's digital passport mandate constitutes a regulatory inflection that compresses compliance timelines and redirects capital toward connected diagnostic architectures, elevating firmware-enabled recurring revenue models over transactional hardware sales.
For Market Incumbents: Entrench position through backward integration into semiconductor load manufacturing and cloud-native firmware architectures that lock in automotive OEM validation lab relationships. Subscription-based diagnostic platforms neutralize emerging entrant price aggression while embedding switching costs. Prioritize ISO 17025 accreditation investment to maintain procurement shortlist eligibility as third-party certification lab consolidation accelerates. For New Entrants and Emerging Players: Build out specialized capabilities in second-life EV battery grading equipment, where stationary storage integrators demand low-cost diagnostic tools absent incumbent focus. India's PLI scheme-driven gigafactory buildout represents the most penetrable geography, with in-line test equipment procurement budgets expanding faster than vendor qualification timelines. Pursue channel partnerships with regional cell manufacturers rather than direct OEM sales approaches. For Investors and Strategic Acquirers: The EU Battery Regulation's 2027 compliance deadline reshapes the acquisition landscape toward equipment vendors with embedded algorithmic expertise and cloud-connected platform architectures. Long-term viability hinges on firmware-enabled recurring revenue conversion rather than pure hardware shipment growth. Target acquisition candidates with demonstrated electrochemical modeling teams capable of translating cell degradation mechanisms into diagnostic algorithms. Monitor quarterly order intake from German automotive validation labs as the primary inflection indicator for sector momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Loads | Taiwan foundry partnerships insulate margin structures from capacity constraint pricing volatility. |
| Cloud-Native Firmware Platform Launch | South Korean tier-1 suppliers pilot subscription models that compress customer capital expenditure. |
| ISO 17025 Accreditation Investment | Third-party certification lab qualification determines procurement shortlist inclusion for automotive OEMs. |
| Second-Life Battery Grading Product Line | California and Texas utility-scale projects pilot automated testing lines for containerized battery systems. |
| India Gigafactory Channel Partnership | Reliance Industries and Ola Electric anchor validation lab investments in the Mumbai-Pune corridor. |
Research Methodology
A spread of perspectives from battery validation lab directors, automotive OEM procurement officers, electrochemical test equipment engineers, and grid-scale storage integrators converged on the working assumptions that shaped demand modeling and technology adoption curves. Primary fieldwork combined structured interviews with equipment vendor sales executives and aftermarket service network operators. Secondary validation drew from MIIT battery safety standards documentation, EU Battery Regulation implementation guidance, SEC filings of publicly traded test equipment manufacturers, and customs data on semiconductor load component trade flows. Bottom-up cell and pack manufacturer procurement estimates were triangulated against top-down automotive OEM R&D expenditure disclosures.
Demand-supply balance framing anchored the analytical framework, with segmentation modeling across product architecture, application vertical, end-user procurement power, and technology maturity throughout the forecast period. Electrochemical impedance spectroscopy adoption curves, solid-state prototype characterization equipment deployment rates, and fleet operator diagnostic budget expansion served as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical equipment shipment data against named regulatory milestone timelines and named automotive OEM battery validation lab expansion announcements.
Sensitivities concentrate around Taiwan foundry capacity allocation shifts, REACH probe alloy substitution timelines, and German automotive OEM validation lab budget revisions. Forecasts reflect assumptions on impedance spectroscopy protocol standardization velocity and cloud-connected tester firmware monetization penetration. Quarterly review of German automotive cluster procurement announcements, India PLI scheme gigafactory groundbreaking dates, and Taiwan semiconductor load component lead time indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Vapor Pressure Analyzer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market