
 Simultaneous-Functionality Analyzers Market | 2026-2036
Simultaneous-Functionality Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Simultaneous-Functionality Analyzers Market Insights
The gap between premium laboratory-grade simultaneous-functionality analyzers and commodity portable units is realigning procurement patterns across industrial end users. Hitachi leverages its electron microscopy heritage to dominate high-end materials characterization segments where precision thresholds exceed commodity capabilities. Mettler-Toledo sustains strong positions in thermal analysis combinations through dense service networks and calibration protocols that smaller competitors struggle to replicate.
Simultaneous-functionality analyzers integrate multiple analytical techniques—such as combined thermal gravimetric analysis with differential scanning calorimetry or hyphenated chromatography-mass spectrometry—into unified platforms that measure several material properties concurrently, typically achieving detection limits in parts-per-million ranges and temperature precision within fractions of a degree Celsius. Their primary purpose is eliminating sequential testing bottlenecks in quality control and research environments where throughput speed directly impacts batch release economics. Benchtop analyzers occupy the densest margin pools due to their balance of capability breadth and capital accessibility for mid-sized laboratories. Optical sensors lead technology adoption in food and beverage applications where non-destructive inline monitoring preserves sample integrity during production runs.
FDA method validation standards and EPA analytical protocols collectively shape instrument specifications, forcing manufacturers to document linearity, accuracy, and robustness across combined detection modes rather than isolated techniques. ISO 17025 accreditation requirements for testing laboratories further filter vendor qualification, privileging suppliers with embedded compliance software and traceable calibration chains. Stakeholders must monitor how evolving EMA guidelines on continuous manufacturing analytics will reshape the interface between inline analyzers and batch release systems.
Market Dynamics
Pharmaceutical quality control laboratories are consolidating multi-parameter testing onto unified platforms to compress batch release timelines and satisfy tightening FDA analytical method validation requirements.
Growth Catalysts
- EMA continuous manufacturing guidelines:The European Medicines Agency's evolving framework on real-time release testing is mandating inline analytical capabilities that only simultaneous-functionality platforms can deliver.
- Germany's chemical corridor:Dense clustering of BASF, Bayer, and Lanxess operations around Ludwigshafen and Leverkusen is generating concentrated demand for thermal-gravimetric combined systems.
- Hyphenated chromatography-mass spectrometry:Food safety laboratories are adopting these integrated detection systems to meet multi-residue screening mandates with single-injection workflows.
Market Restraints
- Precious metal sensor costs:Platinum and rhodium components in thermal analysis modules expose manufacturers to commodity price volatility from South African supply concentration.
- ISO 17025 accreditation timelines:Testing laboratories face 12-18 month certification cycles that delay instrument commissioning and revenue realization.
- Standalone portable units:Commodity handheld spectrometers are capturing price-sensitive field applications where precision thresholds permit lower-grade detection.
Strategic Opportunities
- India's PLI scheme for pharmaceuticals:Production-linked incentives for domestic drug manufacturing are stimulating greenfield quality control laboratory construction in Hyderabad and Ahmedabad.
- Optical sensor convergence:Near-infrared and Raman spectroscopy integration is enabling non-destructive inline monitoring for dairy and beverage processing lines.
- EPA analytical protocol revisions:Updated environmental testing mandates for PFAS and emerging contaminants are forcing laboratories to upgrade from sequential to simultaneous detection platforms.
Industry Challenges
- Cross-disciplinary calibration expertise:Combined thermal-gravimetric and differential scanning calorimetry systems require technicians trained in both thermal physics and materials science, creating hiring bottlenecks.
- LIMS integration complexity:Laboratory information management system vendors use proprietary data formats that complicate automated reporting from multi-technique analyzers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simultaneous-Functionality Analyzers Market |
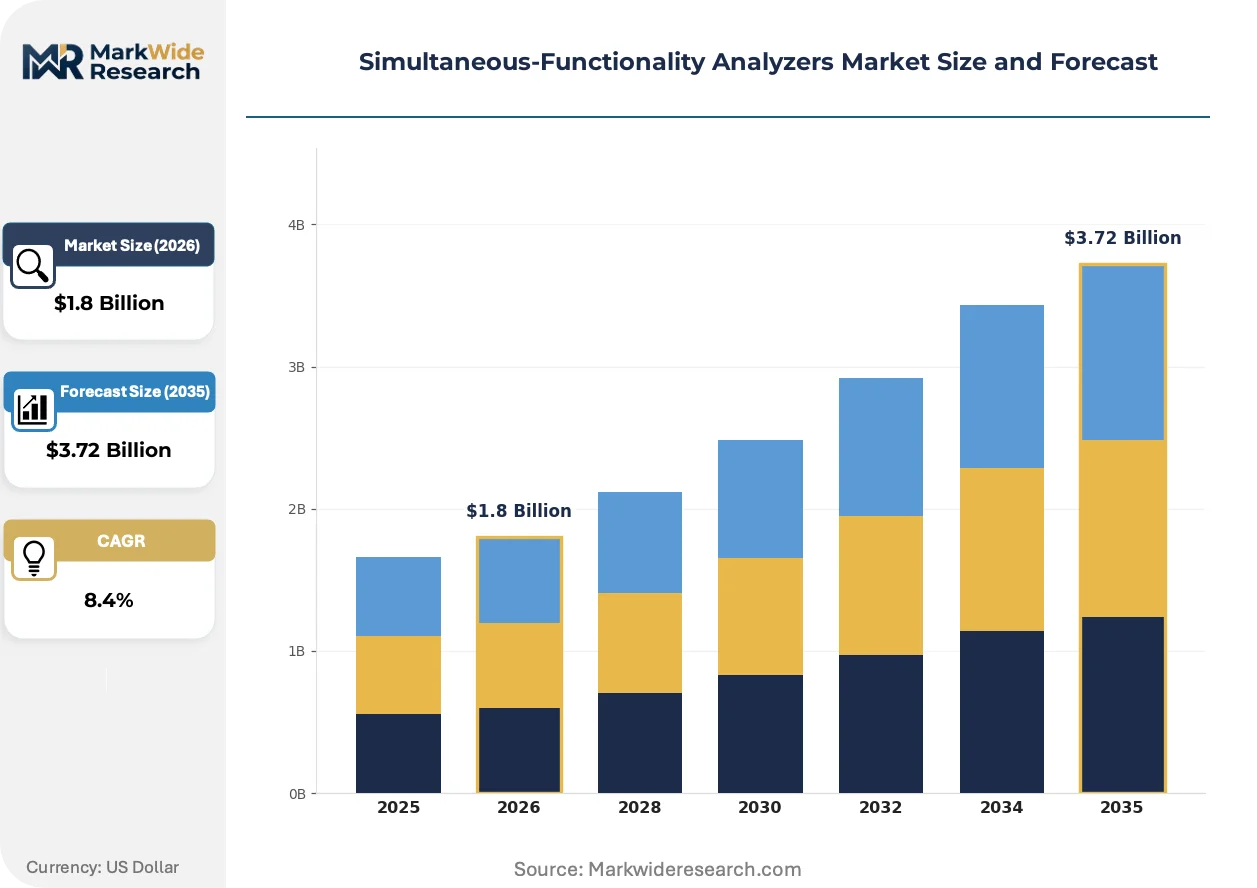
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Benchtop Analyzers, Inline Analyzers, Laboratory Analyzers Technology: Optical Sensors, Electrochemical Sensors, Mass Spectrometry, Chromatography End User: Pharmaceuticals, Environmental Monitoring, Food & Beverage, Chemicals Application: Quality Control, Research & Development, Process Monitoring, Compliance Testing |
| Companies Covered | Hitachi, Mettler-Toledo, PerkinElmer, Netzsch, Shimadzu, Leco, Linseis, Instrument Specialists, Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simultaneous-Functionality Analyzers Market Trends and Innovations
Unified detection platforms are compressing capital expenditure cycles while regulatory agencies are rewriting validation protocols around real-time data streams rather than discrete batch testing.
Miniaturized optical sensor arrays is electrifying inline food and beverage monitoring by enabling continuous composition analysis without sample destruction. Dairy processors in Wisconsin and cheese manufacturers in Normandy are deploying these systems at line speeds exceeding 500 units per minute. The technology is electrifying quality control economics by eliminating laboratory sample queues and enabling immediate process adjustment.
REACH substance restriction amendments are forcing materials characterization laboratories to document thermal degradation profiles across broader temperature ranges than legacy single-technique instruments permitted. The European Chemicals Agency's expanded SVHC candidate list now requires concurrent detection of decomposition products and residual solvents. Contract testing organizations in Germany and the Netherlands are responding by retiring sequential thermal analyzers in favor of combined TGA-DSC platforms.
Service unbundling is fragmenting traditional instrument procurement as mid-sized laboratories purchase hardware through distribution channels while sourcing calibration and compliance software separately. This pattern is most pronounced among independent environmental testing firms in the US Great Lakes region where capital constraints favor staged investment. Third-party ISO 17025 accreditation bodies are capturing recurring revenue streams that manufacturers previously monopolized through bundled service contracts.
Simultaneous-Functionality Analyzers Market Segmentation
Segmentation in simultaneous-functionality analyzers reflects divergent capital cycles and precision requirements across industrial laboratories. Procurement patterns split between replacement-driven upgrades in established facilities and greenfield installations in emerging manufacturing clusters.
Product Type:
Replacement cycles vary dramatically by product tier, with mid-sized laboratories driving the densest upgrade activity as legacy single-technique instruments reach end-of-life.
- Benchtop Analyzers:These platforms balance thermal-gravimetric and differential scanning calorimetry capabilities within footprint-constrained laboratory environments. German chemical manufacturing corridors around Ludwigshafen and Leverkusen concentrate procurement as BASF, Bayer, and Lanxess facilities consolidate multi-parameter testing onto unified platforms to compress batch release timelines.
- Laboratory Analyzers:Full-scale systems achieve detection limits in parts-per-million ranges with temperature precision within fractions of a degree Celsius for materials characterization at research institutions. FDA method validation standards and EPA analytical protocols shape specifications, forcing manufacturers to document linearity, accuracy, and robustness across combined detection modes.
- Portable Analyzers:Handheld units serve field applications where precision thresholds permit lower-grade detection.
- Inline Analyzers:Real-time release testing platforms integrate directly into continuous manufacturing lines.
Volume placements concentrate in Benchtop Analyzers; the faster expansion belongs to Inline Analyzers.
Technology:
Technology selection tracks directly to detection chemistry and sample throughput requirements, with optical methods gaining share in non-destructive applications.
- Optical Sensors:Near-infrared and Raman spectroscopy integration enables non-destructive inline monitoring for dairy and beverage processing lines at speeds exceeding 500 units per minute. Wisconsin dairy processors and Normandy cheese manufacturers deploy these systems to eliminate laboratory sample queues and enable immediate process adjustment.
- Mass Spectrometry:Hyphenated chromatography-mass spectrometry systems deliver multi-residue screening mandates with single-injection workflows for food safety laboratories. EMA continuous manufacturing guidelines mandate real-time release testing capabilities that these integrated detection platforms provide.
- Electrochemical Sensors:Cost-effective detection for routine ionic and redox measurements in environmental monitoring.
- Chromatography:Separation-based analysis for complex mixture resolution in pharmaceutical quality control.
Revenue concentration sits with Mass Spectrometry; Optical Sensors are climbing the fastest as food and beverage adoption accelerates.
End User:
End-user demand fragments across regulatory intensity and sample volume, with pharmaceutical laboratories setting performance benchmarks that cascade to adjacent sectors.
- Pharmaceuticals:Quality control laboratories consolidate multi-parameter testing onto unified platforms to satisfy tightening FDA analytical method validation requirements. India's PLI scheme for pharmaceuticals stimulates greenfield quality control laboratory construction in Hyderabad and Ahmedabad, generating concentrated instrument demand.
- Environmental Monitoring:EPA analytical protocol revisions for PFAS and emerging contaminants force laboratories to upgrade from sequential to simultaneous detection platforms. Contract testing organizations respond by retiring legacy thermal analyzers in favor of combined TGA-DSC systems.
- Food & Beverage:Non-destructive inline monitoring preserves sample integrity during production runs.
- Chemicals:Materials characterization laboratories document thermal degradation profiles across expanded temperature ranges per REACH substance restriction amendments.
Capital deployment peaks in Pharmaceuticals; Environmental Monitoring shows the steepest expansion trajectory as regulatory testing mandates broaden.
Application:
Application segmentation reflects workflow positioning, with quality control commanding premium pricing due to batch release economics.
- Quality Control:Throughput speed directly impacts batch release economics in pharmaceutical manufacturing, driving specification for detection limits and temperature precision. ISO 17025 accreditation requirements for testing laboratories filter vendor qualification, privileging suppliers with embedded compliance software and traceable calibration chains.
- Process Monitoring:Real-time data streams from inline analyzers enable immediate process adjustment in continuous manufacturing environments. EMA guidelines on continuous manufacturing analytics reshape the interface between inline analyzers and batch release systems.
- Research & Development:Exploratory materials characterization at research institutions.
- Compliance Testing:Regulatory-mandated verification for environmental and safety standards.
Installed base dominance rests with Quality Control; Process Monitoring gains share fastest as continuous manufacturing adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen and Leverkusen anchor concentrated demand for thermal-gravimetric combined systems, with Germany's chemical manufacturing corridor generating procurement volumes that exceed most national markets. Dense clustering of BASF, Bayer, and Lanxess operations creates instrument density unmatched elsewhere.
United States
Pharmaceutical quality control laboratories in Massachusetts and New Jersey consolidate multi-parameter testing onto unified platforms to compress batch release timelines. FDA analytical method validation guidelines tighten instrument performance requirements, privileging suppliers with embedded compliance software. Wisconsin dairy processors deploy near-infrared optical sensors at line speeds exceeding 500 units per minute for immediate process adjustment.
Germany
REACH substance restriction amendments force materials characterization laboratories to document thermal degradation profiles across expanded temperature ranges. ECHA's expanded SVHC candidate list mandates concurrent detection of decomposition products and residual solvents. Contract testing organizations in the Netherlands and Germany retire sequential thermal analyzers in favor of combined TGA-DSC platforms.
India
Production-linked incentives for domestic drug manufacturing stimulate greenfield quality control laboratory construction in Hyderabad and Ahmedabad. CDSCO alignment with FDA validation standards filters vendor qualification toward suppliers with traceable calibration chains. Mid-sized pharmaceutical manufacturers in Gujarat consolidate procurement through distribution channels while sourcing calibration separately.
Japan
PMDA quality guidelines for continuous manufacturing reshape the interface between inline analyzers and batch release systems. Research institutions in the Kansai and Kanto regions specify detection limits in parts-per-million ranges for exploratory materials characterization. Precision instrument manufacturers in Nagoya supply thermal analysis modules to regional chemical producers.
China
NMPA method validation standards for real-time release testing mandate inline analytical capabilities that simultaneous-functionality platforms deliver. Chemical manufacturing clusters in Jiangsu and Shandong provinces upgrade from sequential to combined detection systems. Domestic instrument makers capture mid-tier procurement through price positioning below premium imports.
Simultaneous-Functionality Analyzers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision thresholds and service network density. The vendor base stratifies into three tiers: electron microscopy heritage specialists dominating high-end materials characterization, thermal analysis combination providers sustaining positions through calibration protocols, and portable unit fabricators capturing price-sensitive field applications. Consolidation pressure concentrates among mid-sized laboratories seeking bundled compliance software. Strategic moves center on service unbundling and third-party ISO 17025 accreditation partnerships.
Within the precision instrumentation tier, Hitachi and Mettler-Toledo exemplify divergent archetypes. Hitachi occupies a position representing electron microscopy heritage applied to materials characterization segments where detection thresholds exceed commodity capabilities. Mettler-Toledo anchors the thermal analysis combination segment, with dense service networks that smaller competitors struggle to replicate. PerkinElmer sits within the hyphenated detection systems space, representing integrated chromatography-mass spectrometry platforms for multi-residue screening workflows.
| Leading Market Players |
|---|
| Hitachi |
| Mettler-Toledo |
| PerkinElmer |
| Netzsch |
| Shimadzu |
| Leco |
| Linseis |
| Instrument Specialists |
| Rigaku Corporation |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical quality control laboratory consolidation onto unified multi-parameter platforms is forcing manufacturers to restructure cost recovery models and component sourcing strategies. Suppliers must absorb precious metal volatility in thermal analysis modules while defending margin structures against portable unit commoditization.
Pricing Analysis
Throughput-linked value capture dominates simultaneous-functionality analyzer pricing, with contracts tying instrument lease rates to batch release velocity and uptime guarantees. Three-tier pricing structure across premium laboratory-grade, standard benchtop, and economy portable levels segments buyer archetypes by precision threshold and regulatory burden. Cost compression in portable tiers is intensifying because handheld spectrometer makers from China are flooding field applications with lower-grade detection alternatives. Price sensitivity peaks among independent environmental testing firms in the US Great Lakes region, while pharmaceutical manufacturers in Massachusetts and New Jersey show lowest elasticity due to FDA validation lock-in.
Supply Chain Analysis
ISO 17025 accreditation requirements for component traceability are gating supplier qualification and fragmenting procurement channels across the value chain. Thermal sensor fabrication concentrates in Japan, Germany, and the United States, with platinum and rhodium sourcing anchored in South African mining operations. Precision optical arrays and mass spectrometry ion sources draw from specialized Japanese and German component makers. Single-source vulnerability in precious metal feedstocks exposes manufacturers to commodity price swings. Distribution runs through authorized service networks that bundle calibration protocols with hardware placement, though mid-sized laboratories increasingly unbundle these elements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision sensor fabrication and captive calibration service capacity is emerging as the decisive competitive lever in this market. Players securing upstream control over thermal analysis modules and downstream lock-in through accreditation partnerships are consolidating margin pools.
For Market Incumbents: Hedge against portable unit commoditization by embedding compliance software that automates FDA and EPA validation documentation, creating switching costs pharmaceutical laboratories cannot easily replicate. Deepen backward integration into platinum-group metal sourcing through long-term offtake agreements with South African refiners to neutralize raw material volatility that erodes thermal analysis module margins.
For New Entrants and Emerging Players: Mid-sized dairy processors in Wisconsin and Normandy cheese manufacturers represent an underserved buyer archetype seeking non-destructive inline monitoring without enterprise-grade capital commitments. These food and beverage operators need optical sensor arrays at throughput speeds exceeding 500 units per minute but lack internal calibration expertise. A hardware-as-a-service model bundling near-infrared and Raman spectroscopy platforms with third-party ISO 17025 accreditation support penetrates this white space faster than traditional instrument sales.
For Investors and Strategic Acquirers: The window for entry favors specialist calibration and compliance software providers serving the laboratory information management system integration gap. Long-term viability in this market rests on controlling recurring revenue streams from validation documentation and traceable calibration chains rather than one-time hardware placement. Watch for EMA guideline finalization on continuous manufacturing analytics as the inflection signal that will reshape inline analyzer procurement and trigger consolidation among vendors lacking real-time release testing capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Captive supply of thermal analysis modules neutralizes South African platinum price volatility and secures margin control. |
| Calibration Service Unbundling | Third-party ISO 17025 accreditation partnerships capture recurring revenue streams independent of hardware sales cycles. |
| Compliance Software Embedding | Automated FDA and EPA validation documentation creates switching costs that lock pharmaceutical laboratories into vendor ecosystems. |
| Optical Sensor Miniaturization | Near-infrared and Raman array convergence enables non-destructive inline monitoring at dairy line speeds exceeding 500 units per minute. |
| Geographic Expansion into India's PLI Corridors | Greenfield quality control laboratory construction in Hyderabad and Ahmedabad generates concentrated instrument demand from domestic drug manufacturers. |
Research Methodology
Independent corroboration across primary interviews with laboratory directors, instrument procurement managers, calibration service technicians, and regulatory compliance officers, combined with secondary validation from FDA guidance documents, EPA analytical protocols, EMA continuous manufacturing guidelines, and ISO 17025 accreditation body records, underwrites the qualitative findings. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against end-user capital expenditure surveys ensure dimensional consistency. Conversations with thermal analysis module suppliers and optical sensor array manufacturers provided upstream cost structure visibility.
Rate-of-change decomposition across the analysis window separates volume expansion from price mix effects and technology substitution patterns. Segmentation dimensions modeled include product tier, detection technology, end-use industry, and application workflow positioning, with regional regulatory clusters treated as cross-cutting modifiers. CAGRs were derived from logistic adoption curves fitted to historical placement data and forward-projected against regulatory mandate timelines. Forecast inputs incorporated EMA guideline evolution on real-time release testing and EPA protocol revisions for PFAS detection.
Revisions become necessary when EMA finalizes continuous manufacturing analytics guidelines, when South African platinum supply disruptions exceed historical volatility bands, or when portable spectrometer detection thresholds achieve laboratory-grade parity. Forecasts reflect assumptions about regulatory enforcement intensity and capital expenditure cycle timing that carry inherent uncertainty. Stakeholders should weight assumptions against their own operating context and instrument replacement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Digital Turbidity Meter Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market