
 North America Analytical Instrumentation Market | 2026-2036
North America Analytical Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Analytical Instrumentation Market Analytics
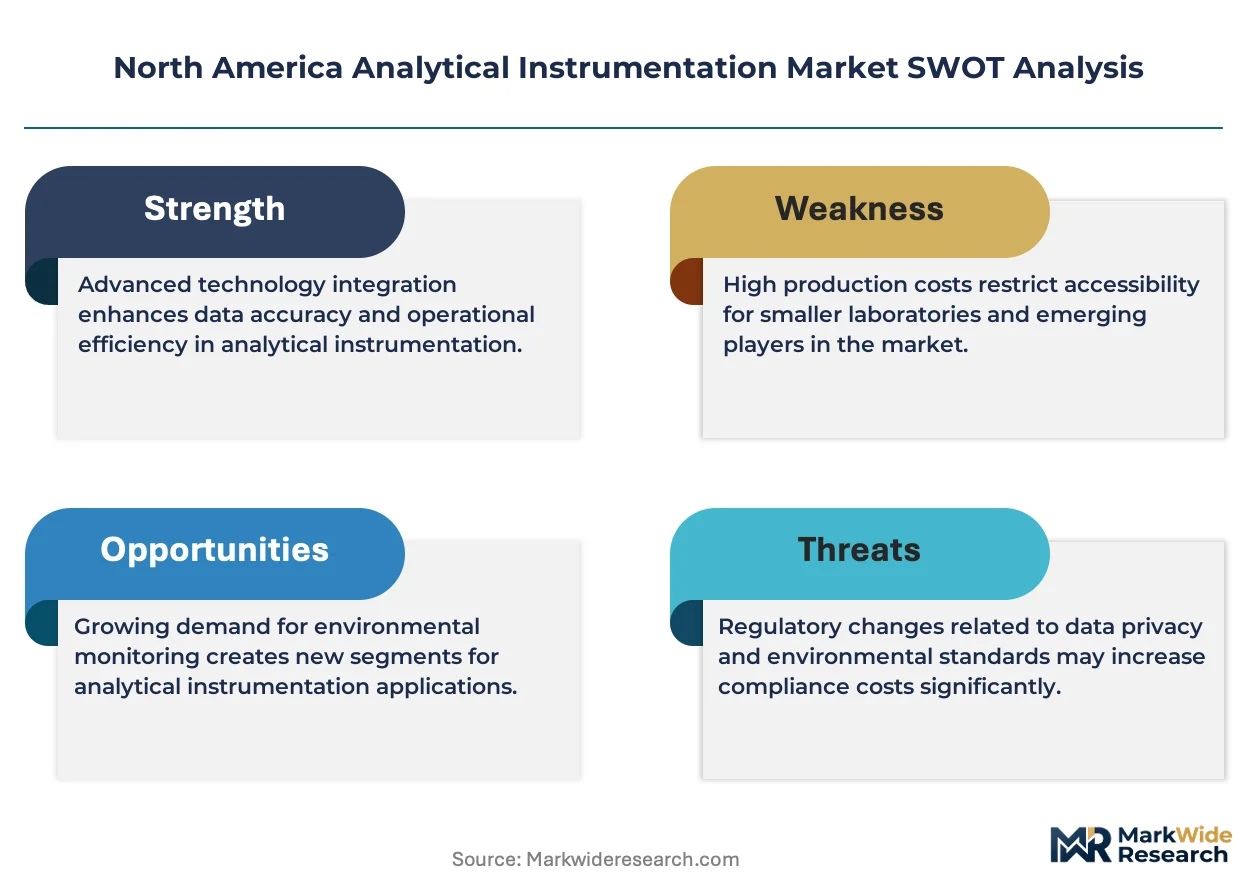
The capability gap between high-throughput platform specialists and modular instrument vendors is bifurcating competitive strategy across the North America Analytical Instrumentation Market. Thermo Fisher Scientific leverages integrated software-hardware ecosystems to dominate pharmaceutical contract research workflows. Agilent Technologies anchors its position through in-house production of ion source components that reduce service turnaround times for environmental testing labs. Bruker Corporation differentiates via specialized nuclear magnetic resonance systems that command premium placement in academic structural biology departments.
North America Analytical Instrumentation encompasses precision measurement systems that separate, identify, and quantify chemical and biological substances using detection limits ranging from parts-per-million to parts-per-trillion, with thermal stability requirements typically spanning minus forty to four hundred degrees Celsius for chromatographic ovens. These instruments serve critical functions in pharmaceutical batch release testing, environmental contaminant screening, and food safety verification. Chromatography systems absorb the largest share of capital expenditure among product types due to their ubiquity across regulated quality control environments. Mass spectrometry segments are recording the fastest expansion as proteomics and metabolomics research laboratories in the United States and Canada replace legacy detection methods with higher-resolution platforms. Spectroscopy maintains mature demand profiles in petrochemical refining applications where established ASTM methods limit technology turnover.
FDA Current Good Manufacturing Practice guidelines and EPA Clean Water Act analytical methods collectively mandate validated instrument protocols that shape procurement specifications for pharmaceutical and environmental end users. Health Canada and the USDA Food Safety and Inspection Service impose parallel requirements that sustain replacement cycles across North American quality control laboratories. Stakeholders must monitor evolving PFAS testing mandates and biologics characterization standards to anticipate the next wave of instrument refresh decisions.
Market Dynamics
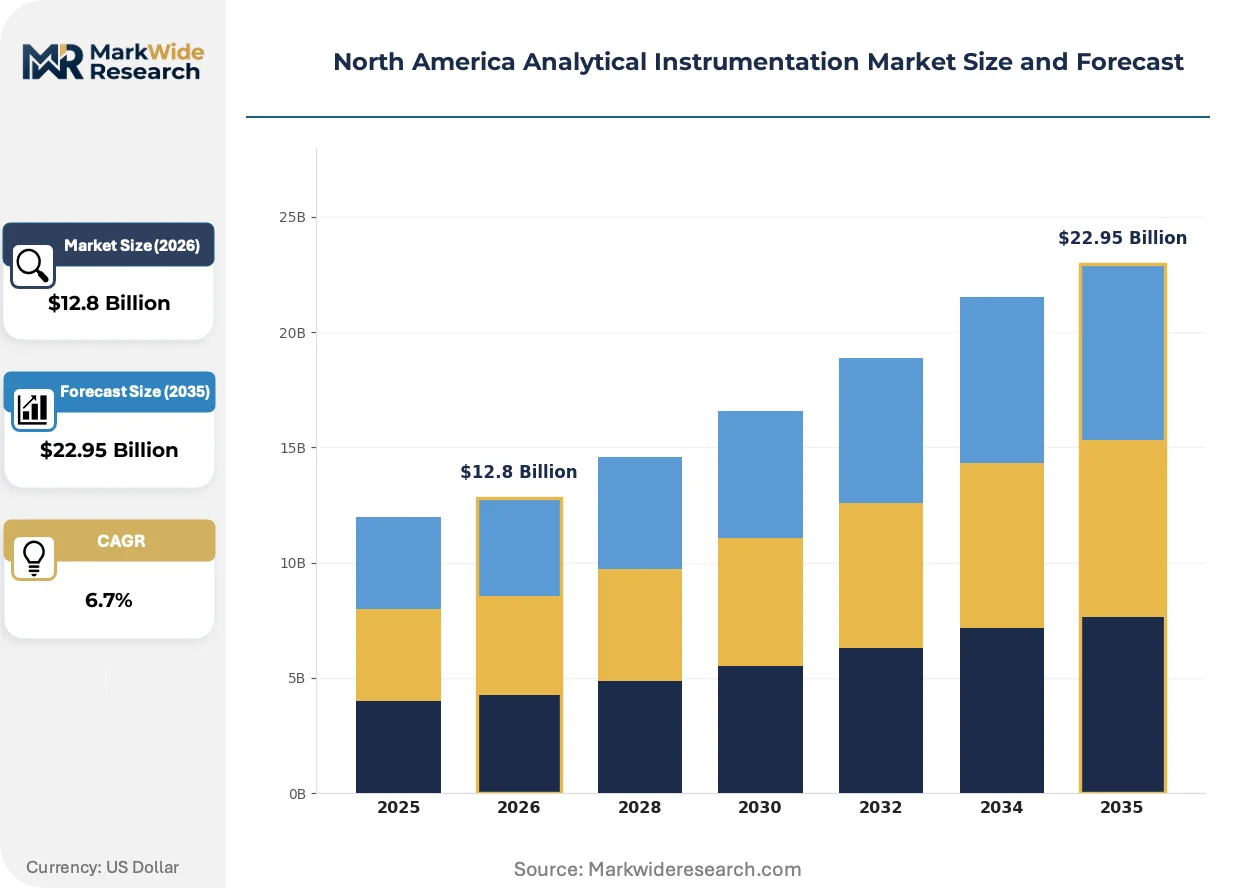
PFAS testing mandates and biologics characterization standards are accelerating replacement cycles across pharmaceutical and environmental quality control laboratories, forcing vendors to recalibrate service architectures around compliance velocity rather than equipment longevity alone.
Growth Catalysts
- FDA Current Good Manufacturing Practice guidelines:Pharmaceutical manufacturers in the United States are expanding quality control laboratories with advanced chromatography systems to meet validation requirements for batch release testing.
- Portable mass spectrometry:Canada's environmental monitoring agencies are deploying these units for real-time contaminant detection in the Great Lakes watershed, creating pull for field-hardened instrument platforms.
- Proteomics and metabolomics research:Laboratories across the United States and Canada are replacing legacy detection methods with higher-resolution mass spectrometry platforms, driving capital expenditure in academic and contract research settings.
Market Restraints
- Helium supply concentration:Mass spectrometry and chromatography systems depend on helium for carrier gas applications, with supply vulnerability concentrated in Qatar and Algeria creating input cost volatility and allocation risk.
- EPA Clean Water Act analytical methods:The prescriptive nature of these validated protocols limits technology turnover speed, compressing upgrade windows for environmental testing laboratories.
- ASTM method entrenchment:Petrochemical refining applications maintain mature demand profiles where established spectroscopy standards restrict adoption of newer detection platforms.
Strategic Opportunities
- Biologics characterization standards:Evolving FDA requirements for complex therapeutic proteins create white space for specialized nuclear magnetic resonance and high-resolution mass spectrometry configurations in contract manufacturing organizations.
- USDA Food Safety and Inspection Service mandates:Parallel requirements to Health Canada and FDA protocols sustain replacement cycles across North American food safety laboratories, opening service contract opportunities for integrated software-hardware ecosystems.
- Microflow liquid chromatography:Convergence with mass spectrometry is enabling sensitivity gains for clinical diagnostic applications, with early adoption concentrated in precision medicine hubs within Boston and San Diego.
Industry Challenges
- Metrology technician scarcity:Environmental testing laboratories face acute shortages of personnel qualified to operate and maintain hyphenated chromatography-mass spectrometry systems under EPA-mandated quality assurance protocols.
- 21 CFR Part 11 compliance integration:Pharmaceutical manufacturers struggle to embed electronic records and signatures capabilities into legacy laboratory information management systems without triggering full instrument replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Analytical Instrumentation Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography, Spectroscopy, Mass Spectrometry, Electrochemical Analyzer Industry Vertical: Chemicals, Pharmaceuticals, Food & Beverage, Environmental Technology: Gas Chromatography, High-Performance Liquid Chromatography, Near-Infrared Spectroscopy, Atomic Absorption Spectroscopy End User: Research Laboratories, Manufacturing, Quality Control, Academic Institutions |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Bruker Corporation, Waters Corporation, Shimadzu Corporation, Danaher Corporation, Malvern Panalytical, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Analytical Instrumentation Market Evolving Landscape
Detection platform architecture is splitting between high-throughput integrated systems and modular configurable instruments, with software-defined workflows displacing hardware-centric specifications in procurement evaluations across regulated industries.
Microflow liquid chromatography paired with high-resolution mass spectrometry is bifurcating method development strategies in pharmaceutical quality control. Large molecule drug manufacturers are adopting these configurations for impurity profiling at accelerated timelines. The technology is bifurcating vendor competitive positioning between integrated platform specialists and component suppliers capable of mixing-and-matching detection modules.
Health Canada and PMRA are tightening analytical method validation requirements for pesticide residue testing in agricultural commodities, mandating tandem mass spectrometry confirmation for all quantitative results. Food safety laboratories are responding by consolidating multi-residue screening workflows onto single quadrupole-time-of-flight platforms capable of both targeted and non-targeted detection.
Service contract unbundling is reshaping how environmental testing laboratories acquire instrument capability. Third-party metrology providers in Ontario and California are capturing preventive maintenance revenue previously retained by original equipment manufacturers, with procurement teams now separating hardware capital from software licensing and field service obligations in multi-year agreements.
North America Analytical Instrumentation Market Segmentation
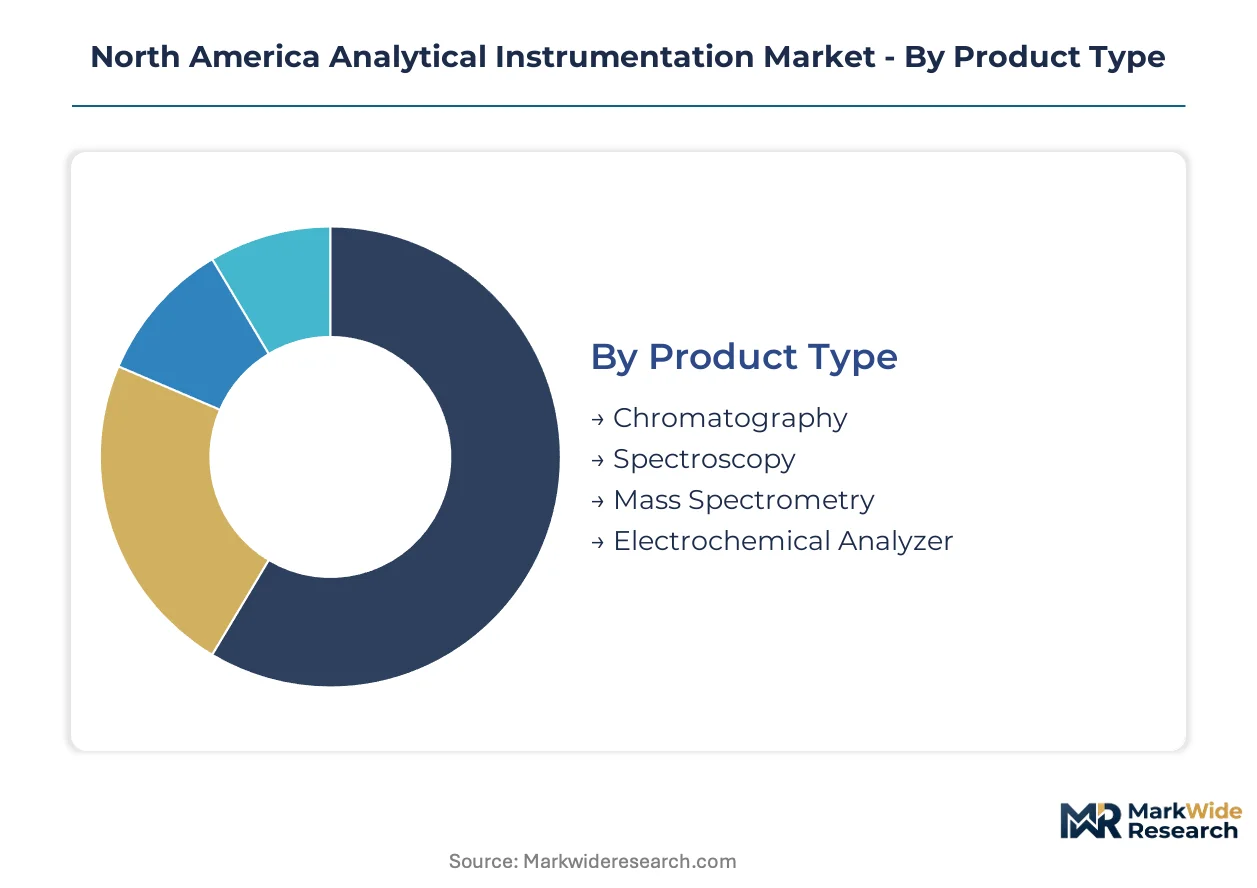
Segmentation in the North America Analytical Instrumentation Market reveals how regulatory mandates and research priorities concentrate capital across distinct technology platforms. Understanding these divisions exposes where compliance velocity and detection sensitivity drive procurement decisions.
Product Type:
Domestic pharmaceutical manufacturing absorbs the majority of chromatography and mass spectrometry output, while spectroscopy platforms serve more distributed petrochemical and environmental testing demand across the United States and Canada.
- Chromatography:Systems separate complex mixtures using stationary and mobile phases, with thermal stability specifications spanning minus forty to four hundred degrees Celsius for oven modules. United States pharmaceutical manufacturers deploy these for FDA-mandated batch release testing, creating concentrated demand in New Jersey and Massachusetts quality control corridors.
- Mass Spectrometry:Platforms identify compounds through mass-to-charge ratio detection with limits reaching parts-per-trillion. Proteomics laboratories in Boston and San Diego precision medicine hubs are replacing legacy detection methods with higher-resolution configurations, accelerating capital refresh cycles.
- Spectroscopy:Mature demand profile in petrochemical refining where ASTM method entrenchment limits technology turnover speed.
- Electrochemical Analyzer:Portable units serve field applications in Great Lakes watershed monitoring and agricultural soil testing.
Chromatography holds the largest share; momentum sits with mass spectrometry.
Industry Vertical:
Cost tiers separate premium validated systems for pharmaceutical GMP environments from standard configurations serving chemical and food safety applications.
- Pharmaceuticals:Contract manufacturing organizations in the United States absorb integrated software-hardware ecosystems for complex therapeutic protein characterization. FDA Current Good Manufacturing Practice guidelines mandate validated instrument protocols that sustain replacement cycles.
- Environmental:Testing laboratories face acute metrology technician scarcity for hyphenated chromatography-mass spectrometry systems under EPA-mandated quality assurance protocols.
- Chemicals:Petrochemical refiners maintain established spectroscopy standards that restrict adoption of newer detection platforms.
- Food & Beverage:Health Canada and PMRA tightening of pesticide residue validation requirements is consolidating multi-residue screening onto tandem mass spectrometry platforms.
Pharmaceuticals command premium pricing; environmental applications are expanding most quickly.
Technology:
Customer type stratification separates high-throughput pharmaceutical contract research workflows from modular academic and environmental testing configurations.
- High-Performance Liquid Chromatography:Dominates biologics impurity profiling with microflow configurations converging with mass spectrometry for clinical diagnostic sensitivity gains.
- Gas Chromatography:Helium carrier gas dependency creates supply vulnerability concentrated in Qatar and Algeria, generating input cost volatility for environmental testing laboratories.
- Near-Infrared Spectroscopy:Process analytical technology deployments in United States pharmaceutical manufacturing enable real-time release testing.
- Atomic Absorption Spectroscopy:Mature installed base in heavy metals testing for EPA Clean Water Act compliance monitoring.
High-Performance Liquid Chromatography anchors current revenue; Gas Chromatography faces supply-side pressure.
End User:
Application maturity separates regulated quality control environments from exploratory research settings with faster technology turnover.
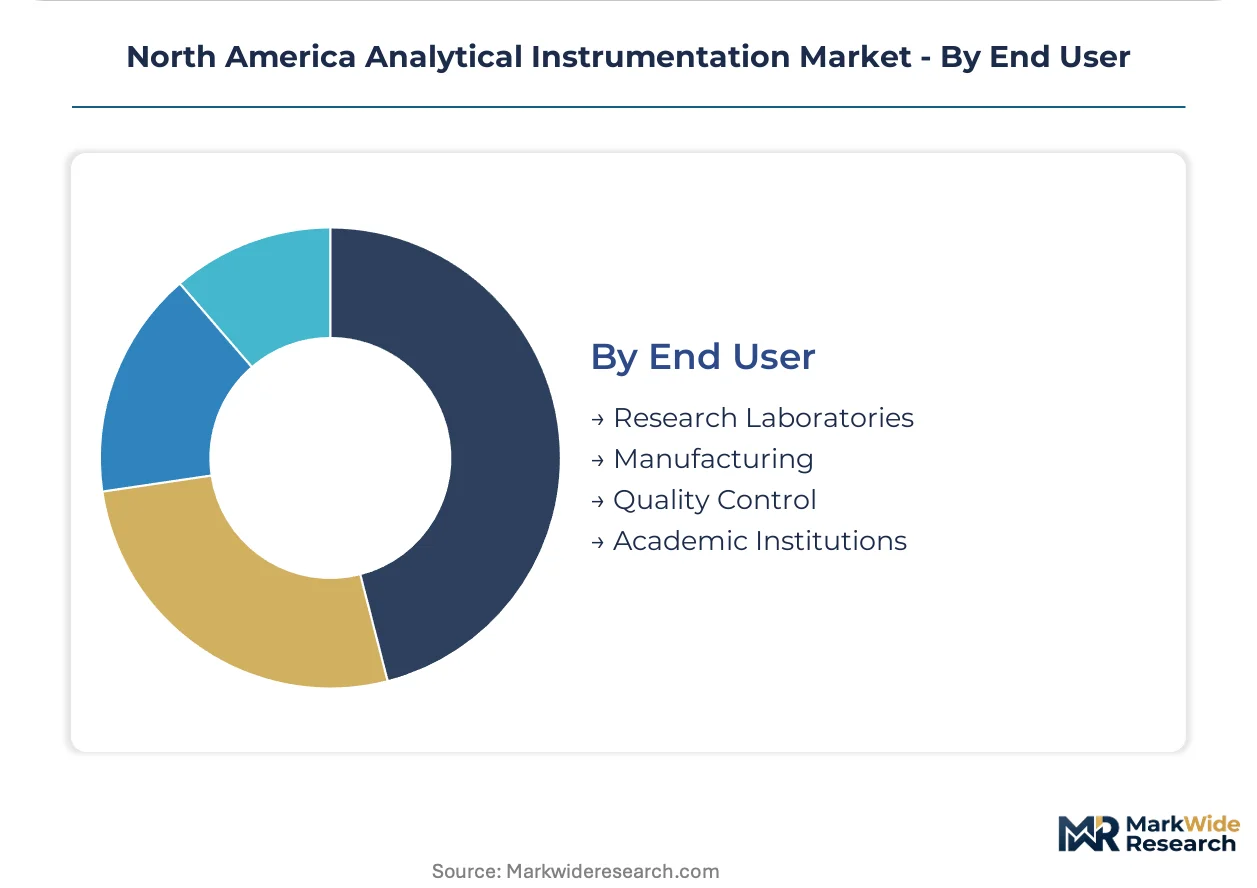
- Quality Control:Pharmaceutical and food safety laboratories sustain replacement cycles through FDA, USDA, and Health Canada mandate alignment. 21 CFR Part 11 compliance integration struggles trigger full instrument replacement rather than legacy system upgrades.
- Research Laboratories:Proteomics and metabolomics facilities in the United States and Canada are climbing the fastest as higher-resolution mass spectrometry platforms displace legacy detection methods.
- Manufacturing:Process analytical technology deployments in biologics production require specialized nuclear magnetic resonance configurations.
- Academic Institutions:Structural biology departments command premium placement for specialized nuclear magnetic resonance systems.
Quality Control generates the largest revenue base; Research Laboratories show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental testing laboratories in Canada show the highest price elasticity due to constrained provincial budgets, while United States pharmaceutical manufacturers absorb premium pricing for validated systems without volume reduction.
United States
FDA Current Good Manufacturing Practice guidelines and biologics characterization standards drive capital expenditure in pharmaceutical quality control corridors. Contract manufacturing organizations across New Jersey and Massachusetts deploy integrated chromatography-mass spectrometry systems for complex therapeutic protein validation. Proteomics laboratories in Boston and San Diego precision medicine hubs are replacing legacy detection methods with higher-resolution platforms.
Canada
Health Canada and PMRA tightening of pesticide residue validation requirements is consolidating multi-residue screening workflows onto tandem mass spectrometry platforms. Ontario environmental monitoring agencies deploy portable mass spectrometry units for real-time contaminant detection in the Great Lakes watershed. Third-party metrology providers in Ontario and Quebec are capturing preventive maintenance revenue through service contract unbundling.
Mexico
Federal environmental regulations and growing food export requirements to the United States are expanding quality control laboratory capacity. The country's national pharmaceutical regulator is aligning with international standards for analytical method validation. Industrial clusters in Mexico City Metro and Nuevo León are absorbing mid-tier chromatography systems for chemical and food safety applications.
North America Analytical Instrumentation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Analytical Instrumentation Market. The vendor base concentrates around integrated platform specialists and modular instrument suppliers serving distinct procurement profiles. Three archetypes dominate: full-stack ecosystem providers, component specialists with in-house production capabilities, and premium niche system developers. M&A activity targets software-defined workflow capabilities, while strategic partnerships address helium supply vulnerability through alternative carrier gas technologies.
Within the integrated platform tier, Thermo Fisher Scientific and Agilent Technologies exemplify full-stack ecosystem providers that anchor pharmaceutical contract research workflows through software-hardware convergence. Bruker Corporation occupies a position among premium niche developers, commanding placement in academic structural biology departments through specialized nuclear magnetic resonance configurations. These three entities represent the strategic positioning spectrum from scale-driven standardization to premium specialization.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Bruker Corporation |
| Waters Corporation |
| Shimadzu Corporation |
| Danaher Corporation |
| Malvern Panalytical |
| Mettler Toledo |
| Others |
Value Network & Pricing Analysis
Helium-to-hydrogen carrier gas substitution in gas chromatography systems is simultaneously redrawing procurement geography toward Eastern European hydrogen suppliers and compressing operating cost structures for environmental testing laboratories. This input shift feeds directly into vendor pricing power as original equipment manufacturers recalibrate service contract economics around alternative carrier gas compatibility.
Pricing Analysis
Preventive maintenance and extended service contracts generate lifetime value exceeding initial hardware margins by substantial multiples across pharmaceutical and environmental customer segments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated configurations for GMP environments from modular academic systems and field-portable units. Pricing pressure stems from third-party metrology providers in Ontario and California capturing aftermarket service revenue through contract unbundling. Environmental testing laboratories in Canada exhibit the highest price elasticity due to constrained provincial budgets, while United States pharmaceutical manufacturers absorb premium validated systems without volume reduction.
Supply Chain Analysis
Extended lead times for specialized ion source components and superconducting magnet assemblies have stretched to twelve-to-eighteen-month horizons following pandemic-era disruptions. Manufacturing concentration centers on the United States, Germany, and Japan for precision optical and vacuum subsystems. Critical dependencies include helium from Qatar and Algeria, rare earth elements for magnet fabrication anchored in China, and specialized electronic components from Taiwan. Single-source vulnerability in superconducting wire supply creates bottleneck risk for nuclear magnetic resonance system delivery. Distribution runs through direct field service organizations for pharmaceutical accounts and authorized distributor networks for academic and environmental segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Analytical Instrumentation Market sits in early-cycle expansion as proteomics and metabolomics research laboratories accelerate capital refresh timelines for higher-resolution detection platforms. Biologics characterization standards and PFAS testing mandates sustain replacement velocity across regulated quality control environments.
For Market Incumbents: Fortify software-hardware ecosystem lock-in through embedded 21 CFR Part 11 compliance modules that trigger full platform replacement rather than modular upgrades. Deepen captive supply of ion source components to compress service turnaround times below third-party metrology competitors. Priority investment in microflow liquid chromatography-mass spectrometry convergence addresses displacement threat from specialized clinical diagnostic entrants. For New Entrants and Emerging Players: Differentiate on field-hardened portable mass spectrometry configurations for Great Lakes watershed monitoring and agricultural soil testing applications where incumbents lack optimized form factors. Target Canada's provincial environmental agencies with unbundled hardware and software procurement structures that bypass integrated platform premiums. Go-to-market through third-party service partnerships in Ontario and Quebec captures preventive maintenance revenue without direct field organization buildout. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors software-defined workflow specialists over hardware-centric legacy vendors. Long-term viability across the next decade hinges on electronic records integration capabilities and alternative carrier gas technology portfolios. Acquisition target archetype: component suppliers with in-house ion source production and established EPA method validation libraries. Signal to watch: Health Canada and PMRA expansion of tandem mass spectrometry mandates into veterinary drug residue testing.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Carrier Gas Technology Development | Hydrogen and nitrogen compatibility investments reduce helium dependency exposure from Qatar and Algeria supply concentration. |
| Software-Defined Workflow Platform Launch | Electronic records and signatures capabilities embedded at instrument level preempt 21 CFR Part 11 compliance replacement cycles. |
| Microflow LC-MS Configuration Expansion | Clinical diagnostic sensitivity gains in Boston and San Diego precision medicine hubs accelerate biologics impurity profiling adoption. |
| Third-Party Metrology Partnership | Preventive maintenance revenue capture in Ontario and California bypasses incumbent direct service organization economics. |
| Academic Structural Biology System Specialization | Premium nuclear magnetic resonance placement commands protected margins in Bruker-dominated departmental procurement. |
Research Methodology
A standing panel of pharmaceutical quality control directors, environmental testing laboratory managers, academic proteomics facility heads, and original equipment manufacturer service executives provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from FDA guidance documents, EPA analytical method databases, Health Canada regulatory filings, and SEC 10-K instrument revenue disclosures. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital expenditure surveys anchored segmentation outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, industry vertical, technology platform, and end-user application dimensions alongside regional regulatory cluster differentiation. CAGRs derived from historical replacement cycle analysis, compliance mandate timing, and research funding trajectory inputs. Helium supply volatility scenarios and biologics approval pipeline data informed sensitivity testing.
Material uncertainties — regulatory method validation delays, carrier gas supply disruptions, and metrology technician scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding FDA and Health Canada enforcement continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Network Analyzers Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Analytical Instrumentation Market