
 Europe Dissolved Gas Analyzer Market | 2026-2036
Europe Dissolved Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dissolved Gas Analyzer Market Foresight
German electrical equipment manufacturers is rebalancing supply chains toward modular dissolved gas analyzer platforms that integrate with digital substation architectures. Siemens Energy leverages its transformer OEM relationships to bundle monitoring hardware with long-term service contracts. ABB Ltd. anchors its position through IEC 61850-compliant communication protocols that streamline SCADA integration for European utilities. Vaisala Oyj competes on optical sensor miniaturization, reducing maintenance intervals for remote transformer installations.
A dissolved gas analyzer detects and quantifies fault gases—hydrogen, methane, ethane, ethylene, acetylene, carbon monoxide, and carbon dioxide—dissolved in transformer insulating oil, typically measuring concentrations at parts-per-million sensitivity to diagnose thermal or electrical degradation before catastrophic failure. The instrument employs gas chromatography or photoacoustic spectroscopy to separate and quantify individual gas species against IEEE C57.104 or IEC 60599 diagnostic thresholds. Online systems command premium positioning as grid operators abandon periodic manual oil sampling in favor of continuous dissolved gas trend monitoring with automated alarm escalation. Portable units retain relevance for forensic diagnostics and smaller distribution transformers where capital constraints prevent permanent installation. Electrochemical sensor platforms face displacement by infrared and photoacoustic methods where multi-gas discrimination and drift stability prove decisive.
The EU F-Gas Regulation and national implementations by Germany's Federal Environment Agency constrain refrigerant and insulation gas choices, indirectly elevating dissolved gas monitoring priority for extending transformer service life. ECHA's REACH framework governs oil sampling protocols and sensor material compliance, while CE marking under the EU AI Act increasingly covers edge-analytics modules performing automated fault classification. Stakeholders must weigh interoperability investments against proprietary cloud platforms as standardization bodies finalize data exchange formats for predictive maintenance ecosystems.
Market Dynamics
The EU Green Deal's transformer reliability mandates are compressing maintenance cycles across European power grids, forcing utilities to retire scheduled inspection protocols in favor of continuous dissolved gas monitoring architectures that feed predictive asset management platforms.
Growth Catalysts
- EU Green Deal mandates:Germany's Federal Environment Agency and France's grid regulator impose stricter transformer reliability standards that require continuous fault gas detection.
- Digital substation architectures:IEC 61850-compliant communication protocols enable seamless SCADA integration, accelerating online monitoring system procurement across transmission operators.
- Optical sensor miniaturization:Photoacoustic spectroscopy platforms reduce maintenance intervals for remote transformer installations in Nordic and Alpine regions.
Market Restraints
- Precision sensor input costs:Infrared detector arrays and photoacoustic cells face supply concentration in East Asian manufacturing clusters, creating price volatility for European OEMs.
- REACH compliance friction:ECHA's material registration requirements extend certification timelines for electrochemical sensor platforms containing restricted substances.
- Portable unit substitution:Capital-constrained distribution utilities in Southern Europe defer permanent installations, limiting online system penetration in secondary transformer fleets.
Strategic Opportunities
- Polish and Romanian grid expansion:EU cohesion funds finance transmission infrastructure upgrades in these markets, creating first-mover advantage for online monitoring deployments.
- EU AI Act edge analytics:Automated fault classification modules with CE marking requirements open premium positioning for vendors integrating machine learning at the sensor level.
- Service contract bundling:Long-term performance agreements that combine hardware, cloud analytics, and field calibration reshape buyer relationships beyond equipment transactions.
Industry Challenges
- SCADA integration complexity:Legacy transformer fleets with proprietary communication stacks require costly protocol bridging for IEC 61850 compliance.
- Photoacoustic calibration expertise:Specialized technician training for drift-resistant multi-gas discrimination lags deployment timelines in smaller utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dissolved Gas Analyzer Market |
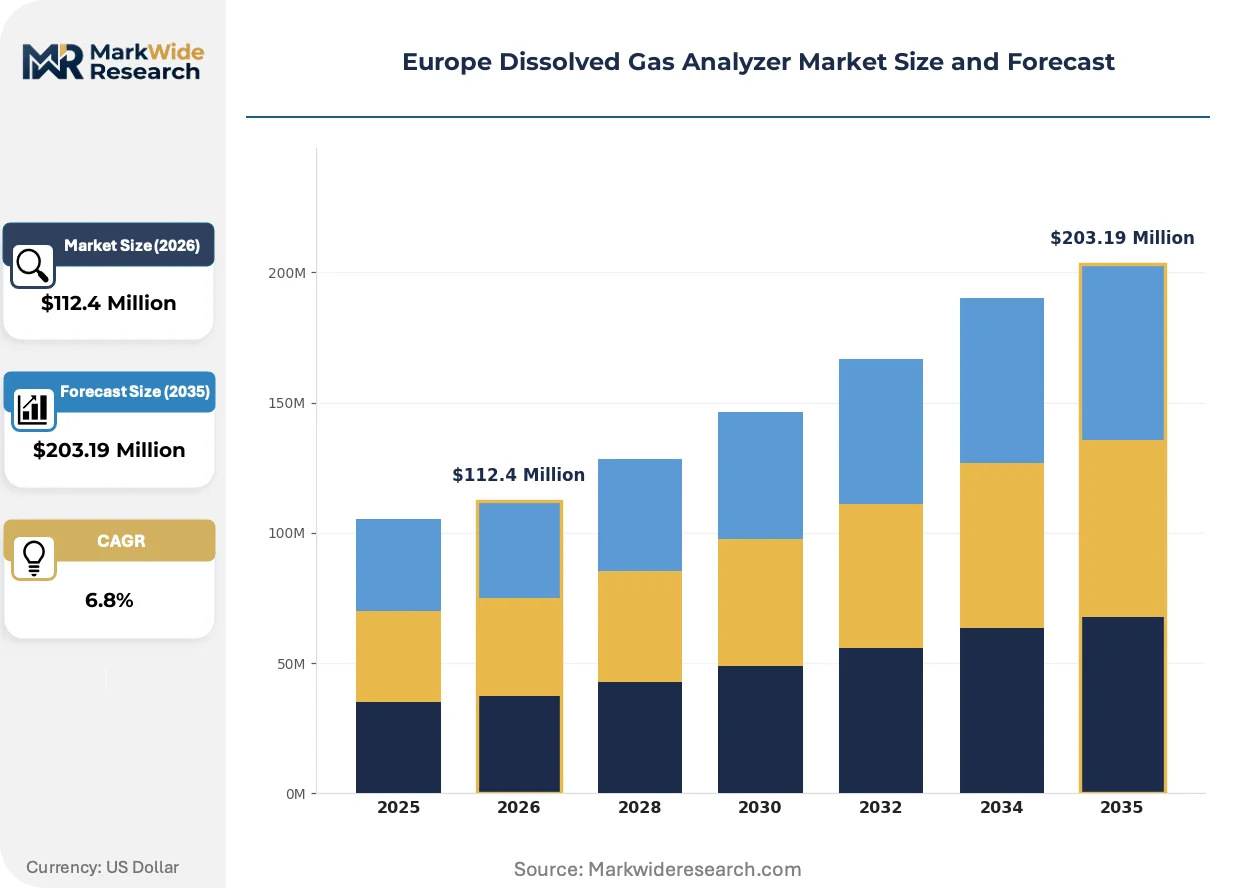
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $203.19 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Online, Laboratory, Hybrid End User: Utilities, OEMs, Industrial Facilities, Research Labs Technology: Optical, Electrochemical, Gas Chromatography, Infrared Application: Transformer Monitoring, Environmental Testing, Quality Control, Safety Compliance |
| Companies Covered | Qualitrol Company LLC, Weidmann Electrical Technology AG, Siemens Energy, Vaisala Oyj, EMH Energy-Messtechnik GmbH, ABB Ltd., Doble Engineering Company, LumaSense Technologies, Inc., General Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dissolved Gas Analyzer Market Shifts & Advancements
Photoacoustic spectroscopy is compressing the technology stack for dissolved gas detection, while regulatory frameworks and procurement architectures reshape how European utilities acquire and operationalize monitoring capabilities.
Photoacoustic spectroscopy is expanding into multi-gas quantification at parts-per-million sensitivity without chromatographic separation. Transmission operators in Germany and the Netherlands deploy these platforms for continuous hydrogen and acetylene trending. The technology is expanding into applications previously served by gas chromatography, compressing maintenance budgets and footprint requirements for substation installations.
REACH registration deadlines for sensor materials are tightening supplier qualification windows. ECHA's substance restriction proposals target electrochemical cell electrolytes, accelerating infrared and photoacoustic platform development. Component manufacturers are responding with material substitution roadmaps that prioritize drift stability over legacy electrochemical architectures.
Utility procurement departments now unbundle hardware acquisition from multi-year calibration and cloud analytics subscriptions. French and Belgian transmission system operators lead this transition, replacing capital-heavy upfront purchases with operational expenditure models. Nordic distribution cooperatives follow, prioritizing vendors offering remote diagnostic support over equipment ownership.
Europe Dissolved Gas Analyzer Market Segmentation
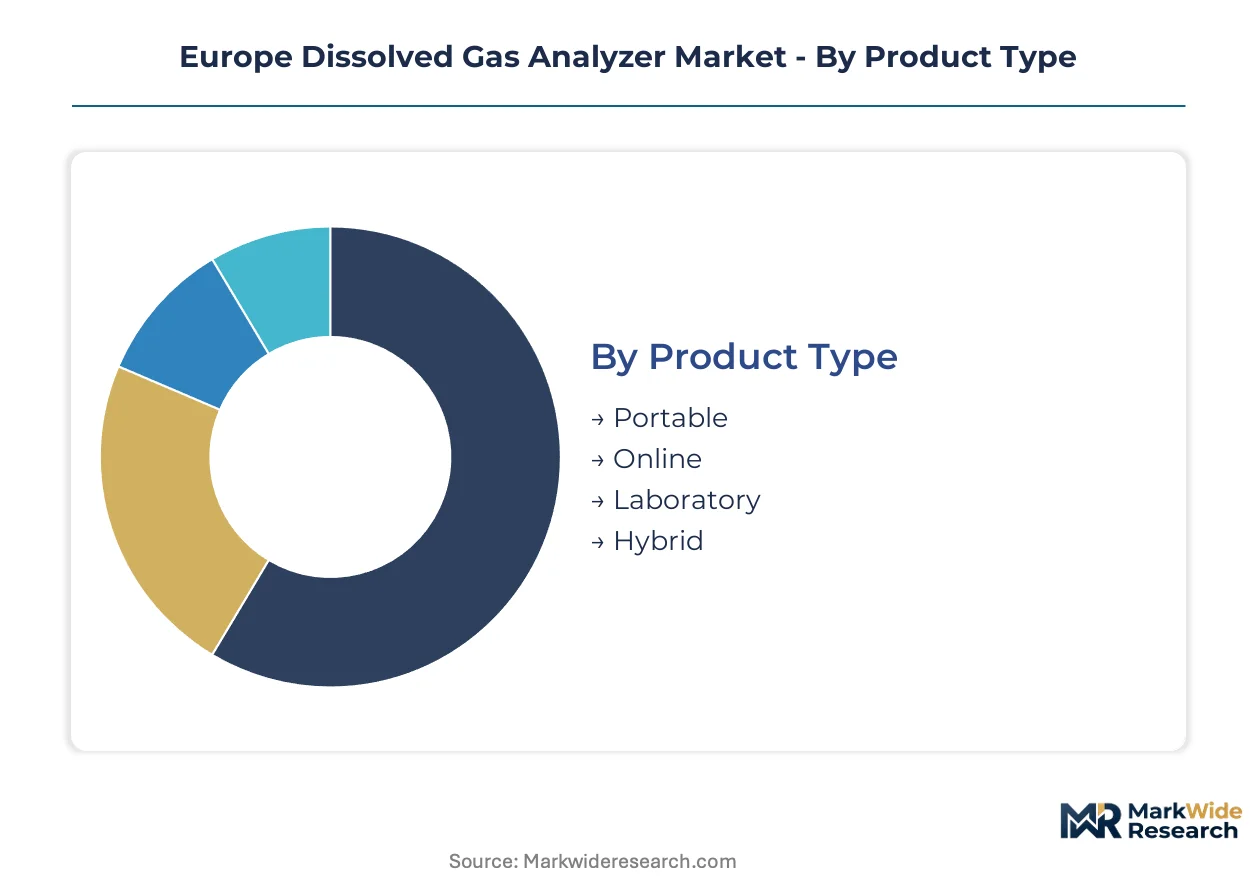
Segmentation in the Europe Dissolved Gas Analyzer Market reveals how procurement priorities diverge across grid operators, manufacturers, and industrial end-users. Each dimension—product architecture, detection technology, and application environment—creates distinct competitive battlegrounds for vendors positioning against EU regulatory mandates.
Product Type:
Capital deployment cycles and workforce mobility requirements separate buyers in this category, with transmission operators favoring permanent installations while distribution utilities weigh portability against total cost of ownership.
- Online:Continuous monitoring architectures integrate directly with SCADA systems via IEC 61850 protocols, enabling automated alarm escalation without manual oil sampling. German and French transmission operators prioritize these systems under EU Green Deal reliability mandates, accepting premium positioning for predictive maintenance integration.
- Portable:Handheld units serve forensic diagnostics and smaller distribution transformers where capital constraints prevent permanent installation. Southern European utilities defer online system procurement for secondary fleets, sustaining demand for battery-operated electrochemical and infrared platforms with simplified calibration protocols.
- Laboratory:Benchtop systems deliver chromatographic precision for dispute resolution and insurance certification, serving transformer OEM warranty validation and third-party testing laboratories.
- Hybrid:Modular platforms combine portable sampling with docked analysis stations, appealing to industrial facilities requiring both spot-check flexibility and trending capabilities.
Online systems lead volumes today; hybrid configurations are gaining share fastest among industrial end-users seeking operational flexibility.
End User:
Procurement authority and technical integration depth shape how each buyer segment evaluates dissolved gas analyzer offerings, from bundled service contracts to standalone equipment tenders.
- Utilities:Grid operators command the largest procurement budgets, driving standardization around IEC 61850-compliant communication stacks and cloud-connected analytics platforms.
- OEMs:Transformer manufacturers bundle monitoring hardware with new equipment sales, leveraging factory calibration relationships to secure long-term service revenue streams.
- Industrial Facilities:Steel plants, chemical complexes, and data centers operate captive transformer fleets, prioritizing portable units and hybrid systems for maintenance flexibility.
- Research Labs:Universities and national metrology institutes validate new detection methodologies, sustaining niche demand for laboratory-grade chromatographic platforms.
Utilities dominate absolute spending; industrial facilities are expanding procurement most quickly as captive generation assets multiply.
Technology:
Detection methodology selection hinges on gas discrimination requirements, drift stability, and REACH compliance constraints affecting sensor material choices.
- Optical:Photoacoustic spectroscopy platforms achieve multi-gas quantification without chromatographic separation, compressing maintenance intervals for remote Nordic and Alpine installations.
- Infrared:Non-dispersive infrared detectors deliver stable hydrogen and carbon monoxide measurements, displacing electrochemical cells where ECHA substance restrictions threaten supply continuity.
- Gas Chromatography:Laboratory-grade separation remains the reference standard for fault gas ratio calculations under IEC 60599, defending position in arbitration and certification workflows.
- Electrochemical:Legacy sensor platforms face displacement as REACH registration deadlines tighten for electrolyte materials, though cost advantages persist in portable unit segments.
Optical platforms command the steepest expansion trajectory; gas chromatography retains the highest average selling prices in laboratory applications.
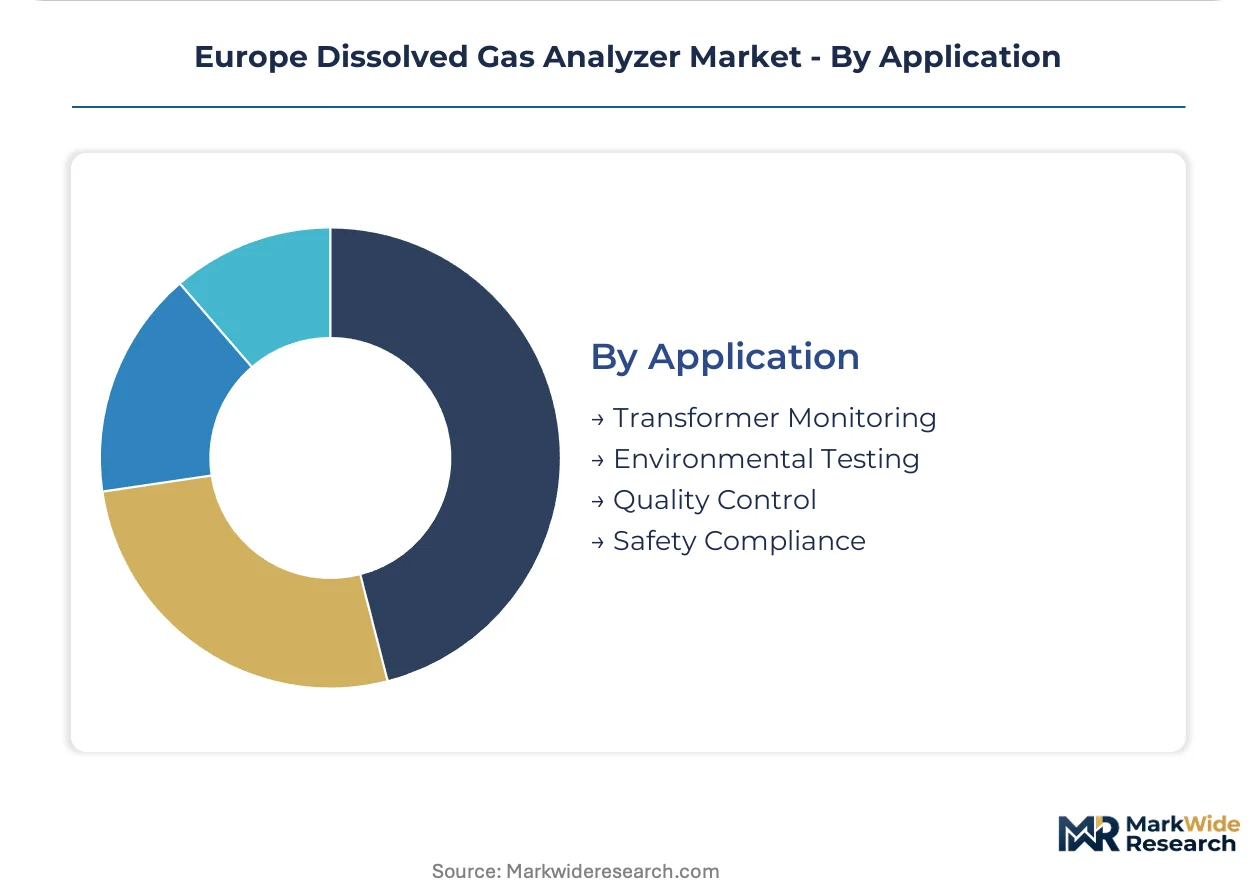
Application:
Regulatory pressure intensity and asset criticality determine which use cases justify continuous monitoring investment versus periodic sampling protocols.
- Transformer Monitoring:Fault gas detection in insulating oil represents the core application, with online systems displacing manual sampling across EU transmission infrastructure.
- Safety Compliance:Mandatory dissolved gas testing for high-voltage assets under national implementations of the EU Green Deal creates recurring revenue for calibration and certification services.
- Environmental Testing:Soil and groundwater analysis for transformer oil contamination extends analyzer utility beyond electrical assets, particularly in brownfield remediation projects.
- Quality Control:Refinery and lubricant blending operations monitor gas content in new oil deliveries, sustaining laboratory system demand for batch certification.
Transformer monitoring anchors category volumes; safety compliance applications are climbing the fastest as reliability mandates tighten across member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between member states is reshaping where dissolved gas analyzer vendors concentrate production and calibration facilities. The EU Green Deal's uneven implementation creates compliance-cost gaps that manufacturers exploit when situating final assembly and sensor testing operations.
Germany
German transmission operators command the largest procurement budgets for online monitoring systems under Federal Environment Agency reliability mandates. The country's Federal Network Agency enforces stricter transformer inspection intervals than neighboring jurisdictions. Siemens Energy anchors production in Berlin and Munich, leveraging OEM relationships to bundle dissolved gas analyzers with transformer service contracts.
France
French grid regulator CRE imposes continuous fault gas detection requirements for high-voltage assets exceeding 225 kV. The country's nuclear-dominated generation fleet demands exceptional transformer reliability, driving premium positioning for photoacoustic platforms. Transmission system operator RTE operates testing laboratories in Lyon and Paris that validate analyzer calibration protocols for continental deployment.
Netherlands
Dutch distribution cooperatives pioneer operational expenditure procurement models that unbundle hardware from cloud analytics subscriptions. The Netherlands Enterprise Agency subsidizes digital substation pilot programs under national climate agreements. Rotterdam's port-industrial complex sustains demand for portable units serving chemical plant captive transformer fleets.
Poland
EU cohesion funds finance transmission infrastructure expansion across Poland's northeastern grid corridor. The country's Energy Regulatory Office transposes EU Green Deal mandates with accelerated timelines for assets near urban centers. Warsaw-based utilities deploy hybrid systems combining portable sampling with docked analysis stations for maintenance flexibility.
Sweden
Swedish distribution operators prioritize optical sensor miniaturization for remote Alpine and subarctic transformer installations. The Swedish Energy Agency funds predictive maintenance pilots that integrate dissolved gas trending with hydropower asset management. Vattenfall operates validation facilities in Stockholm that stress-test photoacoustic platforms for Nordic climate conditions.
Europe Dissolved Gas Analyzer Market Competitive Landscape
European producers anchor the premium tier for IEC 61850-compliant systems; North American specialists hold position in laboratory-grade chromatography platforms. Market structure tilts toward consolidated vendor relationships at transmission utilities and fragmented procurement across industrial facilities. Three archetypes dominate: transformer OEMs bundling monitoring hardware with equipment sales, pure-play sensor manufacturers competing on optical miniaturization, and diversified electrical equipment conglomerates leveraging service contract scale. Geographic expansion through Polish and Romanian grid partnerships and technology licensing for photoacoustic sensor architectures represent the dominant competitive vectors.
Among European-based specialists, EMH Energy-Messtechnik GmbH exemplifies the mid-tier instrumentation archetype focused on utility-grade compliance. Vaisala Oyj anchors the optical sensor segment through Finnish precision manufacturing heritage. Siemens Energy occupies a position bridging OEM bundling advantages with digital substation integration capabilities. These three represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| Qualitrol Company LLC |
| Weidmann Electrical Technology AG |
| Siemens Energy |
| Vaisala Oyj |
| EMH Energy-Messtechnik GmbH |
| ABB Ltd. |
| Doble Engineering Company |
| LumaSense Technologies, Inc. |
| General Electric |
| Others |
Supply & Pricing Matrix
Captive production of photoacoustic sensor cells in Finland and Germany anchors both supply security and premium pricing power for European dissolved gas analyzer manufacturers, insulating them from East Asian component volatility while justifying IEC 61850-compliant system premiums.
Pricing Analysis
Distributor margins for laboratory-grade chromatography systems absorb 15-25 points before reaching end-users, while direct-to-OEM bundling contracts command steeper discounts in exchange for multi-year calibration lock-ins. Three-tier pricing structure across premium, standard, and economy levels separates photoacoustic platforms with edge analytics from infrared mid-range systems and electrochemical portable units. Cost compression in portable segments is intensifying because Southern European utilities defer capital expenditure for permanent installations. Distribution utilities exhibit highest price sensitivity; transmission operators prioritize predictive maintenance integration over unit economics.
Supply Chain Analysis
Freight costs for photoacoustic sensor arrays from East Asian manufacturing clusters impose working capital burdens that modular European assembly mitigates through regional component sourcing. Infrared detector arrays draw from Japanese and German optical foundries; photoacoustic cells source from Finnish precision manufacturing; electrochemical electrolytes hinge on Belgian and Dutch chemical suppliers. Single-source vulnerability concentrates in helium-neon laser tubes for interferometric detection. Distribution runs through authorized service partners performing field calibration and cloud analytics provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in dissolved gas analyzers rests on sensor miniaturization cost curves and the shift toward subscription-based predictive maintenance contracts that capture recurring revenue above equipment depreciation.
For Market Incumbents: Anchor defensive positioning through backward integration into optical sensor fabrication and exclusive calibration network control. Photoacoustic platform commoditization from Asian module suppliers threatens premium tiers. Certification investment in EU AI Act edge-analytics compliance creates switching costs for utility procurement departments. For New Entrants and Emerging Players: Transformer OEM service departments represent the most penetrable channel partner type for modular monitoring platform distribution. Polish and Romanian grid expansion under cohesion fund financing offers first-mover positioning before incumbent service contract lock-in. Target industrial captive transformer fleets with hybrid portable-docked systems bypassing utility procurement complexity. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service networks because customer relationships fragment across national maintenance protocols and language-specific technical support requirements. Five-to-ten year viability favors vendors with installed base density generating recurring cloud analytics subscription streams. Monitor ECHA substance restriction announcements for electrochemical sensor obsolescence inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Photoacoustic Sensor Miniaturization | Reduces maintenance intervals for Vattenfall's remote Nordic transformer installations. |
| IEC 61850 Protocol Certification | Enables RTE France's seamless SCADA integration mandates for high-voltage assets. |
| Calibration Service Network Expansion | Captures recurring revenue from German Federal Environment Agency inspection cycles. |
| EU AI Act Edge Analytics Development | Creates CE marking differentiation for automated fault classification modules. |
| Polish Grid Partnership Formation | Secures first-mover positioning in EU cohesion fund transmission upgrades. |
Research Methodology
Direct dialogue with utility asset managers, transformer OEM service directors, ECHA regulatory compliance officers, and photoacoustic sensor R&D leads grounded qualitative assessments in operational reality. Secondary validation drew from EU Green Deal implementation documents, IEC 61850 protocol specifications, ECHA REACH substance restriction proposals, and transmission operator procurement disclosures. Bottom-up equipment shipment tallies and top-down grid investment forecasts were triangulated against regulatory mandate timelines.
Bottom-up modeling tracked online, portable, laboratory, and hybrid system deployments across German, French, Dutch, Polish, and Swedish grid operators. Segmentation dimensions spanned product architecture, detection technology, end-user category, and application environment. CAGRs were derived from regression analysis against transformer fleet expansion rates and reliability mandate compliance deadlines. Forecast inputs incorporated EU cohesion fund allocation schedules and ECHA material restriction phase-out timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction acceleration and photoacoustic sensor cost curve trajectories. Model outputs reflect assumptions around regulatory enforcement consistency and utility capital expenditure prioritization. A model refresh is warranted upon material change in EU Green Deal transformer reliability mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
Thermogravimetric Analyzer Market
Analytical Instruments
Signaling Analyzer Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Microfluidics Market