
 India Uninterruptible Power Supply (UPS) Market | 2026-2036
India Uninterruptible Power Supply (UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
India Uninterruptible Power Supply (UPS) Market Foresight
India's Bureau of Energy Efficiency (BEE) star-rating mandates for power conditioning equipment is rebalancing procurement priorities toward efficiency-optimized systems. Schneider Electric India leverages its pan-India service network to sustain large-format installations across industrial corridors. Delta Electronics Inc. anchors the premium online UPS segment through in-house semiconductor fabrication. Consul Neowatt Power Solutions Pvt. Ltd. dominates the sub-10 kVA tier with localized assembly operations in Tamil Nadu.
An uninterruptible power supply is an electrical apparatus that provides emergency power to critical loads when the mains supply fails, using rectifiers, inverters, and battery banks to maintain output within voltage tolerances of plus or minus two percent. Online double-conversion topology eliminates transfer-time gaps, making it essential for semiconductor fabrication, medical imaging suites, and financial trading infrastructure. The 10 kVA - 100 kVA capacity band carries the densest margin pool as commercial real estate and mid-tier data centers prioritize scalable redundancy. Li-ion technology displaces lead-acid across deployments above 50 kVA where floor-space constraints and cycle-life economics favor higher energy density. The IT & Telecom end-user segment generates the steepest volume trajectory as hyperscale cloud regions expand in Hyderabad and Chennai.
BIS certification under IS 16242 and CEA grid-interconnection standards shape product eligibility for government and utility-linked tenders. DGFT import restrictions on power electronics components are accelerating indigenization of printed circuit board assemblies and magnetics. Stakeholders must monitor BIS notification timelines and PLI scheme revisions for energy storage to calibrate capital allocation between imported subsystems and domestic manufacturing partnerships.
Market Dynamics
Li-ion battery chemistry is compressing total cost of ownership curves across commercial UPS deployments, forcing recalibration of capital planning cycles and service revenue models for installers nationwide.
Growth Catalysts
- Data center uptime mandates:The Digital Personal Data Protection Act imposes strict availability requirements on operators in Maharashtra and Karnataka, accelerating procurement of online double-conversion systems.
- BIS certification expansion:IS 16242 compliance requirements for power electronics are filtering out uncertified imports, creating protected demand pools for qualified domestic assemblers.
- Cloud region buildouts:Hyperscale facilities in Hyderabad and Chennai are consuming 10 kVA - 100 kVA units at scale, pulling capacity from Tamil Nadu and Delhi-NCR manufacturing bases.
Market Restraints
- Semiconductor import dependency:DGFT restrictions on power electronics components force assemblers to source IGBTs and MOSFETs through constrained channels, elongating lead times.
- Lead-acid stranded assets:Existing battery banks in installed base create replacement inertia, delaying Li-ion conversion economics for mid-tier commercial buyers.
- Grid-interconnection standards:CEA technical specifications for utility-linked tenders add compliance layers that disqualify smaller regional manufacturers from public sector opportunities.
Strategic Opportunities
- PLI scheme alignment:Production-linked incentives for energy storage manufacturing offer capital subsidy offsets for firms indigenizing printed circuit board assemblies and magnetics.
- Tier-2 city penetration:Underpenetrated commercial complexes in Pune, Ahmedabad, and Kochi present whitespace for scalable 10 kVA - 50 kVA deployments as distributed IT infrastructure spreads.
- Modular topology convergence:Rack-mounted scalable architectures combined with lithium-ion density are enabling pay-as-you-grow procurement models for mid-tier data centers.
Industry Challenges
- Power electronics talent scarcity:Shortage of engineers proficient in magnetics design and thermal management constrains product development cycles for domestic manufacturers.
- BIS notification latency:Uncertain timelines for revised IS 16242 amendments complicate R&D roadmaps and inventory positioning for component suppliers.
- Legacy system interoperability:Integration friction with existing building management systems and diesel generator controllers extends commissioning timelines for hybrid power architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Uninterruptible Power Supply (UPS) Market |
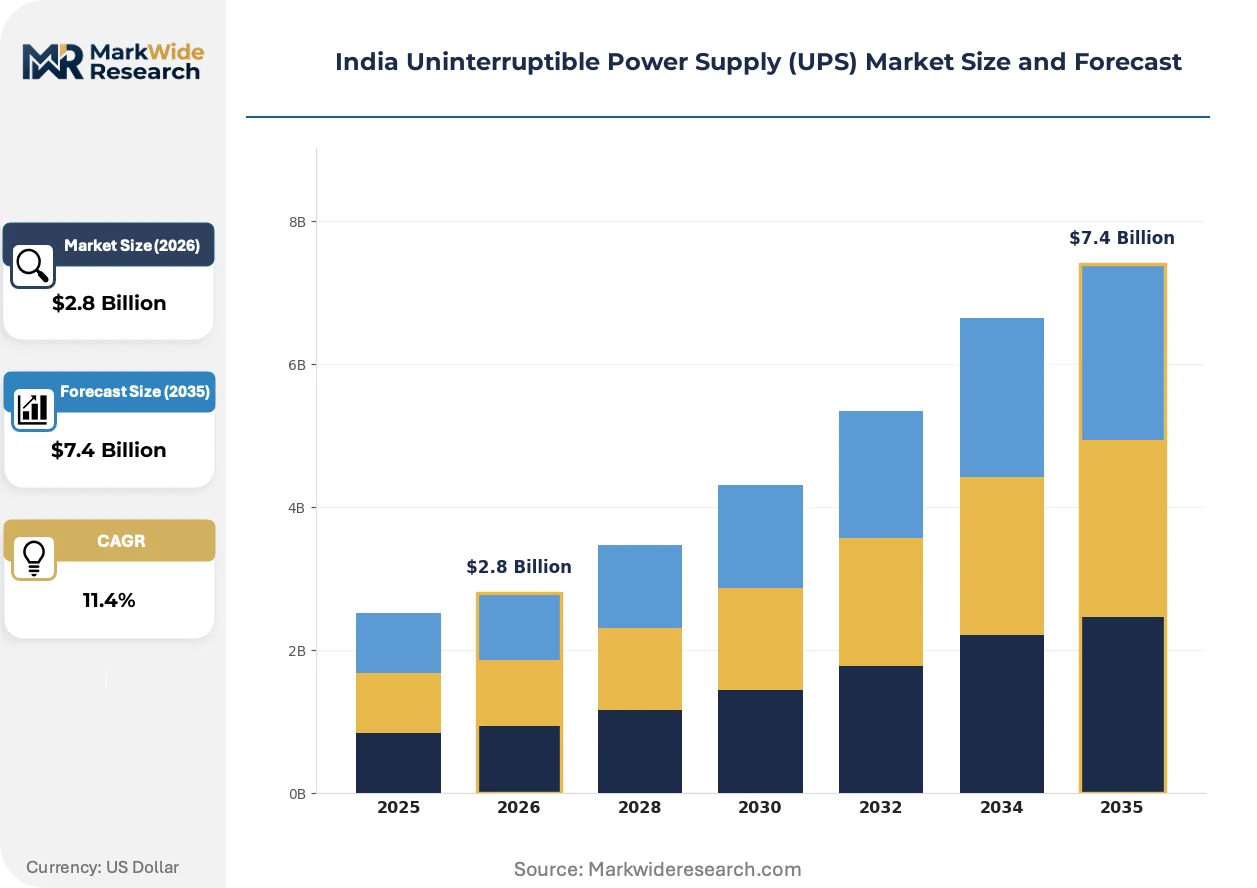
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standby, Line-Interactive, Online, Ferroresonant Capacity: Below 1 kVA, 1 kVA - 10 kVA, 10 kVA - 100 kVA, Above 100 kVA End User: IT & Telecom, Healthcare, Manufacturing, Commercial Technology: Lead-Acid, Li-ion, Flywheel, Others |
| Companies Covered | Delta Electronics Inc., Schneider Electric India, Eaton Corporation PLC, Vertiv Energy Pvt. Ltd., Consul Neowatt Power Solutions Pvt. Ltd., Riello Elettronica SpA, ABB Ltd, Microtek International Pvt Ltd., Emerson Electric Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Uninterruptible Power Supply (UPS) Market Shifts & Advancements
Topology evolution and chemistry substitution are compressing physical footprints while regulatory pressure on efficiency metrics is recalibrating procurement evaluation criteria across end-use verticals.
Silicon carbide (SiC) power semiconductors are reducing switching losses in rectifier and inverter stages, enabling higher power density in 50 kVA - 100 kVA cabinets. Data center operators in Bengaluru and Hyderabad are specifying SiC-based units for new builds to minimize cooling loads. This technology is expanding into medical imaging and semiconductor fabrication facilities where voltage tolerance requirements are most stringent.
Bureau of Energy Efficiency star-rating mandates for power conditioning equipment are elevating efficiency thresholds in public procurement guidelines. Commercial real estate developers in Delhi-NCR now face implicit efficiency floors for LEED certification alignment. The 10 kVA - 100 kVA segment is most affected, with buyers demanding 95%+ efficiency ratings as table stakes.
Facility managers are unbundling after-sales service contracts from hardware procurement, selecting third-party maintenance providers based on response time guarantees rather than OEM affiliation. Mid-tier commercial complexes in Chennai and Mumbai are driving this fragmentation. This pattern is most visible in the IT & Telecom vertical where uptime penalties outweigh brand loyalty in vendor selection.
India Uninterruptible Power Supply (UPS) Market Segmentation
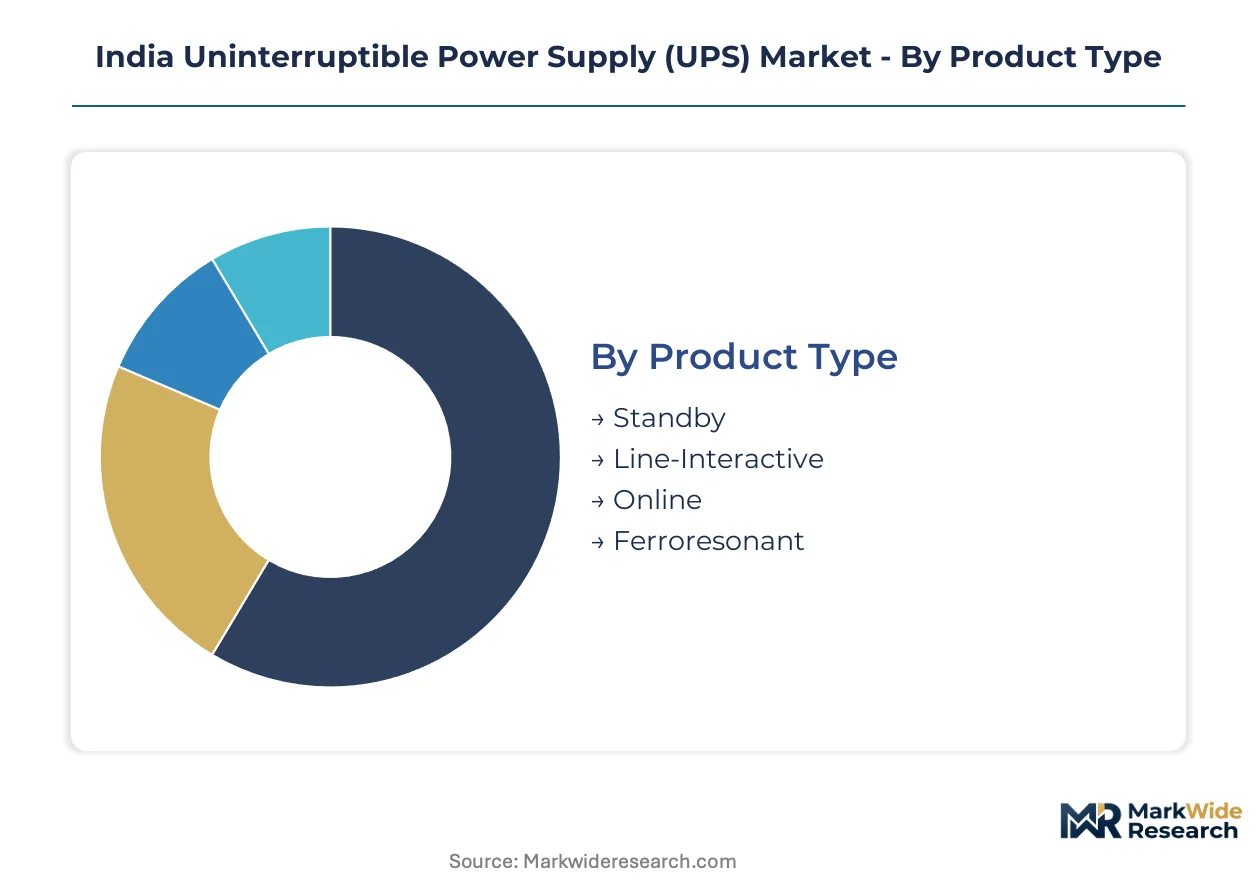
UPS procurement in India fragments across four critical decision axes: topology selection determines power quality guarantees, capacity sizing matches redundancy requirements to load profiles, end-use verticals impose distinct uptime mandates, and battery chemistry dictates total cost of ownership over deployment lifecycles.
Product Type:
Topology selection hinges on transfer-time tolerance and voltage regulation precision required by downstream equipment.
- Standby:Offline topology switches to battery only during mains failure, introducing 4-8 millisecond transfer gaps. Small offices in Tier-3 cities deploy these for desktop computers and POS terminals where momentary interruptions are non-critical.
- Line-Interactive:Buck-boost voltage regulation without full double-conversion reduces energy losses while conditioning sags and surges. Retail banking branches across Gujarat and Rajasthan favor this middle-ground architecture for ATM networks and teller workstations.
- Online:Double-conversion topology rectifies AC to DC and inverts back to AC continuously, eliminating transfer time and holding voltage within ±1% tolerance. Data centers in Hyderabad and Chennai mandate this standard for server racks under the Digital Personal Data Protection Act.
- Ferroresonant:Saturable transformer design delivers inherent voltage regulation through magnetic flux saturation. Legacy industrial installations in Tamil Nadu's textile belt retain these for motor drive protection where harmonic tolerance permits older technology.
Online systems lead on scale; Line-Interactive units lead on momentum in cost-constrained distributed infrastructure.
Capacity:
Procurement volume concentrates where commercial real estate density intersects with IT load expansion.
- Below 1 kVA:Desktop and single-workstation protection for SOHO segments. Individual professionals in Bengaluru's co-working spaces drive replacement cycles as remote work infrastructure upgrades.
- 1 kVA - 10 kVA:Small server rooms and departmental IT closets. Consul Neowatt's Tamil Nadu assembly operations capture this tier through localized distribution networks serving SME manufacturing clusters.
- 10 kVA - 100 kVA:Modular three-phase systems supporting mid-tier data centers and commercial complexes. Delhi-NCR developers specify this band for LEED-aligned efficiency mandates under BEE star-rating programs.
- Above 100 kVA:Centralized protection for hyperscale facilities and semiconductor fabrication plants. Maharashtra's chip manufacturing investments under the PLI scheme are pulling megawatt-class containerized deployments.
10 kVA - 100 kVA leads on scale; Above 100 kVA leads on momentum as sovereign silicon investments accelerate.
End User:
Vertical-specific uptime penalties and regulatory exposure reshape vendor selection criteria across buyer categories.
- IT & Telecom:Hyperscale cloud regions in Hyderabad and Chennai consume scalable rack-mounted architectures. TRAI infrastructure reliability guidelines and DPDP Act liability exposure prioritize online double-conversion with N+1 redundancy.
- Healthcare:Medical imaging suites and surgical suites demand zero-transfer-time protection. CDSCO equipment registration requirements and NABH accreditation standards filter procurement toward IS 16242-certified systems with isolated grounding.
- Manufacturing:PLC protection and robotic workcell continuity dominate load profiles. Automotive suppliers in Pune and Chennai specify voltage sag ride-through capabilities to prevent production line scrap during grid disturbances.
- Commercial:Mixed-use developments and retail malls prioritize first-cost optimization over precision. BEE efficiency floors are elevating minimum specifications in Delhi-NCR green building certifications.
IT & Telecom leads on scale; Healthcare leads on momentum as diagnostic infrastructure expands in Tier-2 cities.
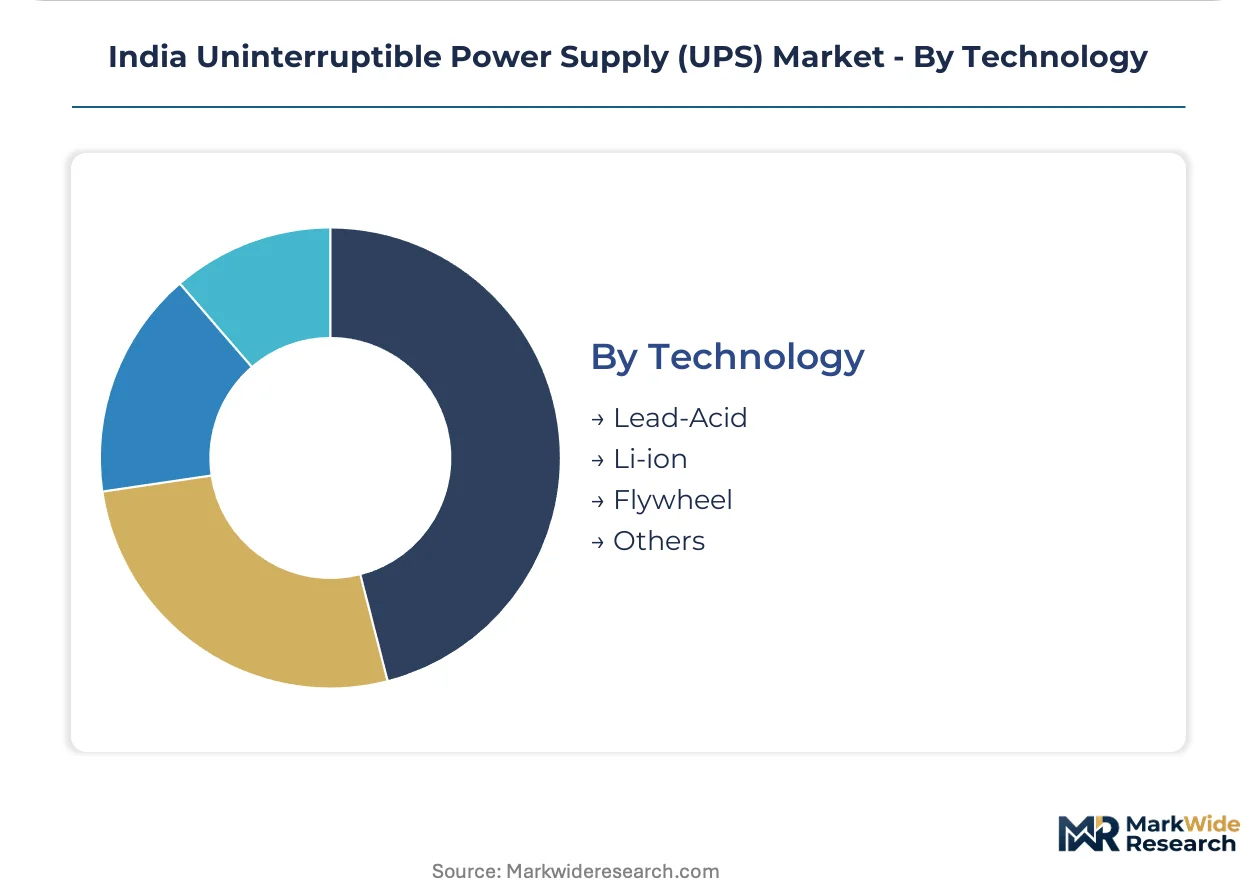
Technology:
Chemistry selection now pivots on floor-space economics and cycle-life modeling rather than capital cost alone.
- Lead-Acid:Flooded and VRLA designs dominate installed base below 50 kVA. Replacement inertia in Maharashtra's industrial corridors delays conversion despite higher lifecycle costs.
- Li-ion:NMC and LFP chemistries compress footprint by 60-70% and extend cycle life 3-5x over lead-acid. Deployments above 50 kVA in Bengaluru data centers are climbing the fastest as real estate costs justify premium pricing.
- Flywheel:Kinetic energy storage delivers 15-30 seconds of ride-through for diesel generator sequencing. Semiconductor fabrication facilities in Gujarat deploy these for clean-room loads where battery emissions are restricted.
- Others:Emerging solid-state and sodium-ion chemistries remain pre-commercial. R&D partnerships between IIT Madras and domestic assemblers are testing indigenized alternatives to imported lithium cells.
Lead-Acid leads on scale; Li-ion leads on momentum as BEE efficiency mandates and space constraints converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indian UPS industry traces its manufacturing lineage to Tamil Nadu's electronics corridor, where component assembly for power conditioning equipment scaled through the 1990s alongside India's software services boom.
Maharashtra
Data center operators in Mumbai and Pune are expanding UPS procurement to meet uptime commitments under the Digital Personal Data Protection Act. The state's IT & ITeS policy offers infrastructure incentives for hyperscale facilities. MMRDA's integrated township regulations in Navi Mumbai are mandating backup power specifications for commercial developments.
Karnataka
Bengaluru's cloud region buildouts are consuming 10 kVA - 100 kVA online double-conversion systems at scale. The Karnataka Data Centre Policy provides power tariff subsidies for certified facilities. Electronics City and Whitefield industrial clusters are seeing concentrated deployment of lithium-ion based modular architectures.
Tamil Nadu
Sriperumbudur and Oragadam industrial belts host localized UPS assembly operations serving SME manufacturing clusters. The state's Electronics Manufacturing Policy aligns with PLI scheme benefits for energy storage components. Chennai's medical device parks are specifying IS 16242-certified systems for diagnostic infrastructure.
Telangana
Hyderabad's hyperscale cloud regions are pulling megawatt-class containerized UPS deployments under TSIIC industrial corridor development. The Telangana Data Centre Policy mandates renewable energy integration with backup systems. Genome Valley and Fab City's semiconductor investments are driving precision power protection demand.
Delhi-NCR
Gurugram and Noida commercial complexes are prioritizing BEE star-rated efficiency-optimized systems for LEED certification alignment. DDA's unified building bylaws impose backup power mandates for high-rise developments. The region's fintech concentration in Cyber Hub and Sector 62 is accelerating online UPS specification.
India Uninterruptible Power Supply (UPS) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification-compliance and service-network dimensions. The vendor base organizes into three tiers: multinational technology owners with captive semiconductor fabrication, domestic assemblers with localized manufacturing footprints, and regional distributors with installation-service capabilities. Consolidation pressures are intensifying as BIS certification requirements filter out uncertified imports. Dominant competitive moves include backward integration into printed circuit board assemblies and strategic partnerships for lithium-ion battery sourcing.
Within the multinational tier, Delta Electronics Inc. and Schneider Electric India occupy positions anchored by pan-India service networks and in-house component capabilities. Consul Neowatt Power Solutions Pvt. Ltd. exemplifies the domestic assembler archetype with Tamil Nadu-based localized operations. These three entities represent distinct strategic postures: technology ownership, service infrastructure scale, and manufacturing proximity to demand clusters respectively.
| Leading Market Players |
|---|
| Delta Electronics Inc. |
| Schneider Electric India |
| Eaton Corporation PLC |
| Vertiv Energy Pvt. Ltd. |
| Consul Neowatt Power Solutions Pvt. Ltd. |
| Riello Elettronica SpA |
| ABB Ltd |
| Microtek International Pvt Ltd. |
| Emerson Electric Co. |
| Others |
Supply & Pricing Matrix
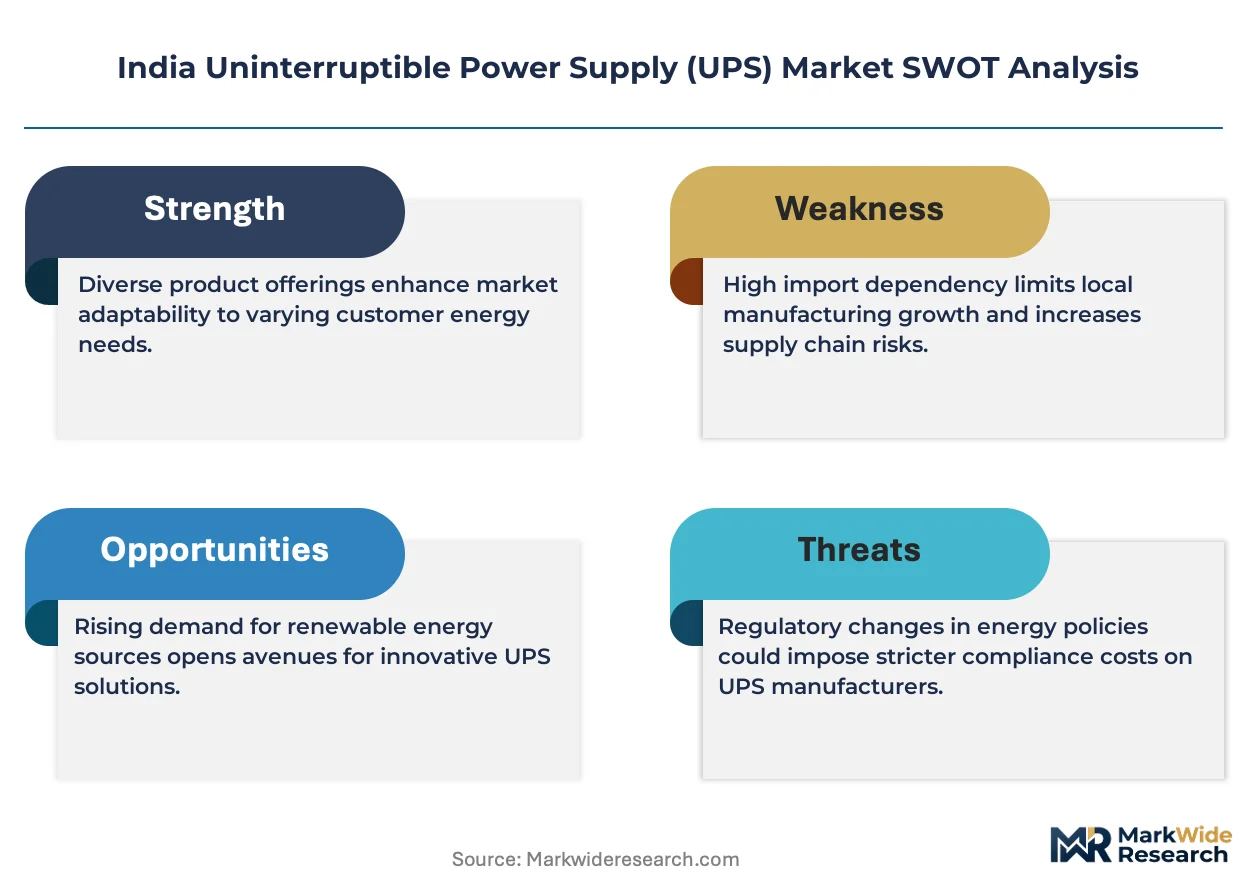
Family-owned mid-cap assemblers with Tamil Nadu manufacturing footprints anchor supply-side discipline, translating localized PCB assembly cost advantages into competitive pricing for sub-50 kVA tiers while multinational service networks command premium positioning above 100 kVA.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IS 16242-certified online double-conversion systems from line-interactive middle tiers and uncertified standby imports. Price differentiation rests on BIS compliance grade and bundled after-sales service coverage. Cost compression in the sub-10 kVA economy tier intensifies as Consul Neowatt's localized assembly erodes import margins. SME manufacturing clusters in Coimbatore and Rajkot exhibit highest price sensitivity; hyperscale data center operators in Hyderabad prioritize uptime guarantees over capital cost.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Sriperumbudur and Oragadam industrial belts, with regional distribution centers in Delhi-NCR, Bengaluru, and Hyderabad maintaining 48-hour response coverage. IGBT and MOSFET sourcing draws from China, Taiwan, and South Korea under DGFT channel constraints. Single-source vulnerability in power semiconductor imports elongates lead times for domestic assemblers. Distribution runs through authorized dealer networks with installation-service bundling for commercial complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India UPS market functions as a stable compounder where sovereign silicon investments and data center policy incentives generate durable procurement cycles across the projection horizon.
For Market Incumbents: Acquire lithium-ion battery pack assembly capabilities to offset stranded lead-acid inventory risk and capture BEE efficiency mandate premiums. Deepen backward integration into magnetics fabrication to mitigate DGFT semiconductor channel constraints. Lock in long-term service contracts with Maharashtra and Karnataka data center operators before third-party maintenance fragmentation accelerates. For New Entrants and Emerging Players: Tier-2 city commercial developers in Ahmedabad, Kochi, and Indore present whitespace for scalable 10 kVA - 50 kVA modular deployments. Target healthcare diagnostic infrastructure in Tier-2 cities where CDSCO registration requirements filter out uncertified imports. Pursue PLI scheme alignment for energy storage component manufacturing to offset capital intensity. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic assemblers with captive Tamil Nadu manufacturing and BIS certification pipelines. Five-to-ten year viability hinges on lithium-ion chemistry conversion economics and PLI scheme renewal trajectories. Monitor BIS notification timelines for IS 16242 amendments as inflection signal for inventory repositioning cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetics | Captive ferrite core and transformer production reduces DGFT import exposure for domestic assemblers. |
| Li-Ion Battery Pack Assembly Scale-Up | Localized NMC and LFP cell integration captures BEE star-rating premiums in commercial real estate. |
| PLI Scheme Alignment for PCBs | Production-linked subsidies offset capital costs for indigenized printed circuit board operations. |
| Third-Party Service Network Buildout | Independent maintenance capabilities exploit fragmentation in mid-tier commercial complex procurement. |
| Modular Rack-Mounted Architecture Launch | Pay-as-you-grow topologies align with hyperscale cloud region expansion in Hyderabad and Chennai. |
Research Methodology
Bottom-up data center and commercial complex load modeling reconciled against top-down power electronics import tracking forms the analytical core of this study. Primary interviews with plant engineers at Tamil Nadu assembly operations, procurement leads at Maharashtra hyperscale facilities, BIS certification officers, and DGFT customs specialists combined with secondary validation against BEE star-rating databases, CEA grid-interconnection filings, and PLI scheme disbursement records. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level precision.
Historical trendline analysis of UPS procurement cycles across Maharashtra, Karnataka, Tamil Nadu, Telangana, and Delhi-NCR informs projection frameworks. Segmentation dimensions span topology type, capacity band, end-use vertical, and battery chemistry across the modeling period. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points including DPDP Act enforcement and BIS notification schedules. Forecast inputs incorporate data center buildout pipelines under state IT policies and semiconductor fabrication investments under sovereign silicon initiatives.
Inputs from BIS certification databases and PLI scheme administrative records were available through the study window; gaps in real-time DGFT import channel data introduce uncertainty bands around lead time assumptions. Forecasts reflect documented assumptions regarding lithium-ion cost curves and regulatory enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Italy Power EPC Market
Power
Middle-East and Africa Power Market
Power
United States Power Market
Power
Saudi Arabia Power Market
Power
Sudan Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Global Advanced Marine Power Supply Market
Power
India Power Market
Power
Australia Power Market
Power
Smart Power Market
Power
Residential Portable Inverter Generator Market
Power
Modified Sine Wave Home Inverters Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
High Voltage DC Power System Market
Power
Digital Power Utility Market
Power
Asia-Pacific Package Substation Market