
 Argentina Power Market | 2026-2036
Argentina Power Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Power Market Analysis
Modular power purchase agreements are restructuring how large off-takers contract supply in Argentina. Genneia leverages its wind and solar hybrid portfolio to offer bundled firm energy blocks to industrial clients. YPF Luz anchors its position through captive gas reserves that backstop renewable intermittency. Pampa Energía competes by controlling dispatchable thermal assets that stabilize grid frequency during seasonal demand spikes.
Argentina power encompasses electricity generation, transmission, and distribution infrastructure operating across voltages from 13.2 kV distribution to 500 kV trunk lines, with thermal plants burning natural gas or fuel oil and renewable assets converting wind or solar flux into grid-synchronous alternating current. Its primary purpose is delivering reliable electron flow to sustain industrial production, urban services, and agricultural pumping. Thermal generation retains the largest installed base yet carries thinning margins as fuel import costs fluctuate, while photovoltaic deployment shows the fastest capacity expansion driven by declining module prices and RenovAr contract awards. Distributed generation is gaining structural traction as Cammesa regulatory reforms allow net metering for commercial users seeking price hedges against wholesale volatility.
Argentina's Secretariat of Energy oversees auction design and dispatch rules, while Cammesa manages the wholesale electricity market clearing and transmission scheduling. The Ente Nacional Regulador de la Electricidad sets distribution tariffs and service quality benchmarks that constrain revenue recovery for Edenor and other concessionaires. Stakeholders must monitor whether federal fiscal constraints delay promised transmission line completions that would unlock stranded renewable capacity in southern provinces.
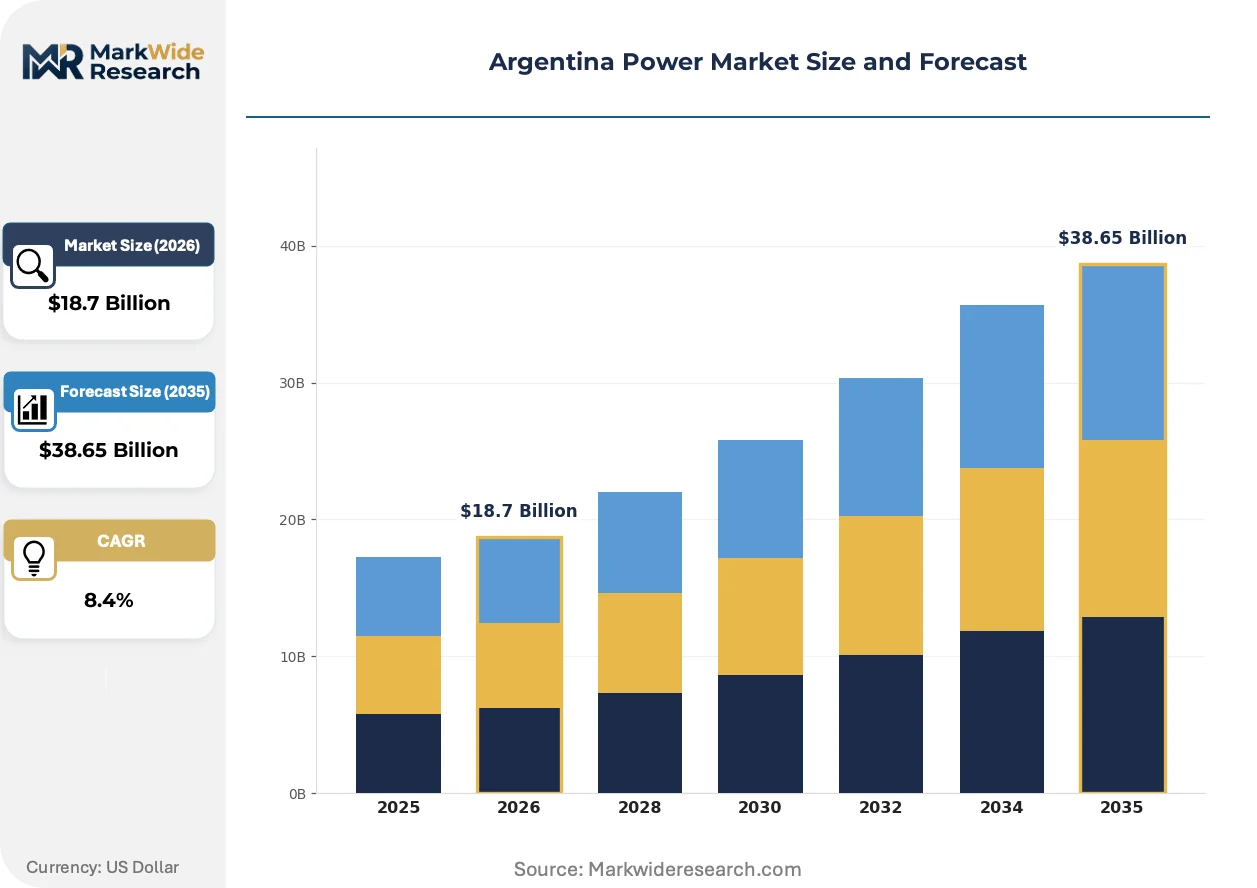
Market Dynamics
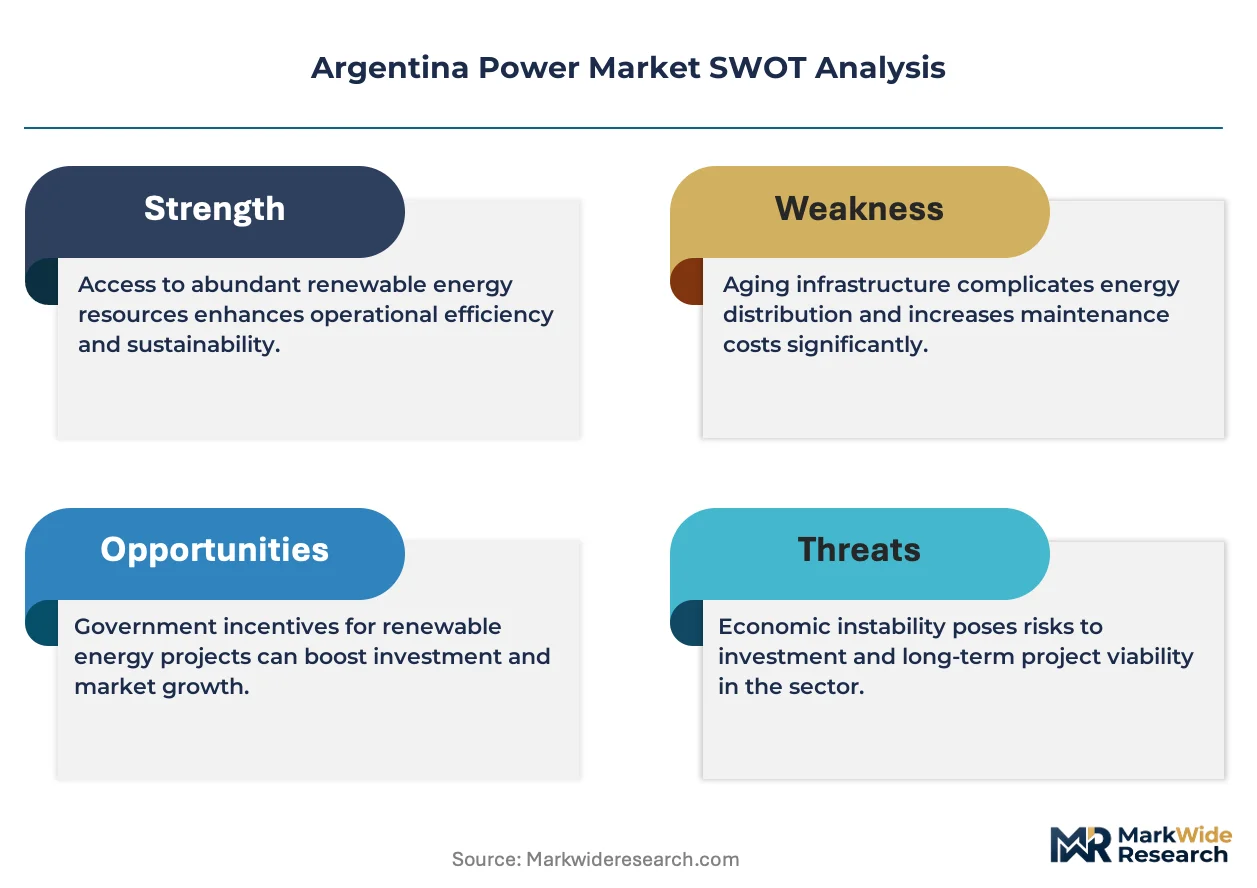
Argentina's power sector is undergoing a structural pivot as the RenovAr auction mechanism redirects capital toward renewable assets while transmission bottlenecks strand generation capacity in Patagonia. This tension between policy-driven supply expansion and physical infrastructure constraints defines competitive positioning for developers and off-takers alike.
Growth Catalysts
- RenovAr auction rounds:The Secretariat of Energy's competitive bidding framework awards long-term power purchase agreements to wind and solar projects, de-risking developer returns and channeling international financing toward Argentine renewables.
- Patagonian industrial load growth:Oil and gas extraction operations in Neuquén and Chubut provinces are contracting firm capacity blocks to power drilling rigs and processing facilities, creating anchor demand for new generation.
- Hybrid plant configurations:Developers are pairing wind turbines with photovoltaic arrays and battery storage to deliver dispatchable renewable blocks that mimic thermal plant reliability profiles.
Market Restraints
- Natural gas import dependency:Thermal generators face margin compression when international LNG spot prices spike, as domestic production from Vaca Muerta shale remains insufficient to cover baseload demand.
- Transmission congestion:The 500 kV trunk network lacks capacity to evacuate renewable generation from Comahue and Patagonia to Buenos Aires load centers, forcing curtailment of zero-marginal-cost supply.
- Currency convertibility risk:Dollar-denominated equipment procurement and peso-denominated tariff revenues create foreign exchange exposure that constrains project finance availability for international investors.
Strategic Opportunities
- Comahue region transmission expansion:The planned 500 kV line from Choele Choel to Buenos Aires province would unlock stranded wind capacity and reduce congestion rents captured by incumbent thermal dispatchers.
- Distributed generation net metering:Cammesa regulatory reforms enable commercial users to offset wholesale market exposure through behind-the-meter solar installations with simplified interconnection standards.
- Green hydrogen pilot corridors:The Secretariat of Energy is evaluating electrolyzer deployments adjacent to Patagonian wind farms to export ammonia and synthetic fuels, creating new offtake for surplus renewable generation.
Industry Challenges
- Grid code compliance timelines:Renewable developers must complete frequency response and voltage ride-through certification with Cammesa before commercial operation, with testing queue backlogs extending project schedules.
- Transmission construction delays:Federal fiscal constraints have slowed promised line completions, leaving developers with contracted capacity unable to deliver energy to offtakers and facing liquidated damages exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Power Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Thermal, Nuclear, Hydropower End User: Residential, Commercial, Industrial, Agriculture Technology: Photovoltaic, Wind Turbine, Gas Turbine, Biomass Deployment: On-grid, Off-grid, Distributed, Centralized |
| Companies Covered | Genneia, YPF Luz, Pampa Energía, Central Puerto, AES Argentina, Enel Green Power Argentina, PCR, Coral Energía, Edenor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Power Market Emerging Trajectories
Argentina's electricity sector is experiencing rapid technology adoption and regulatory recalibration as distributed generation, hybrid renewables, and market liberalization reshape how power is produced, traded, and consumed across the national grid.
Behind-the-meter photovoltaic systems are decentralizing electricity supply for commercial and industrial users seeking price hedges against Cammesa wholesale volatility. Supermarkets, cold storage facilities, and manufacturing plants in Greater Buenos Aires are installing rooftop arrays at accelerating pace. This distributed architecture is compressing distribution utility revenue bases while forcing Edenor and other concessionaires to adapt tariff structures.
The Secretariat of Energy's distributed generation decree and subsequent Cammesa technical standards have created a regulatory pathway for net metering that bypasses traditional wholesale market participation. Industrial offtakers are leveraging these rules to contract hybrid on-site generation combining solar, storage, and backup thermal. The commercial segment is responding fastest, with retail and logistics facilities leading installation volumes.
Large energy buyers are abandoning traditional take-or-pay contracts with thermal generators in favor of shorter-term renewable energy certificate purchases and physical hedges with hybrid wind-solar portfolios. Mining operations in Catamarca and San Juan are negotiating directly with developers for firm renewable blocks backed by battery storage. This procurement evolution is most visible in the lithium extraction corridor, where offtakers prioritize carbon-free supply to meet export market requirements.
Argentina Power Market Segmentation
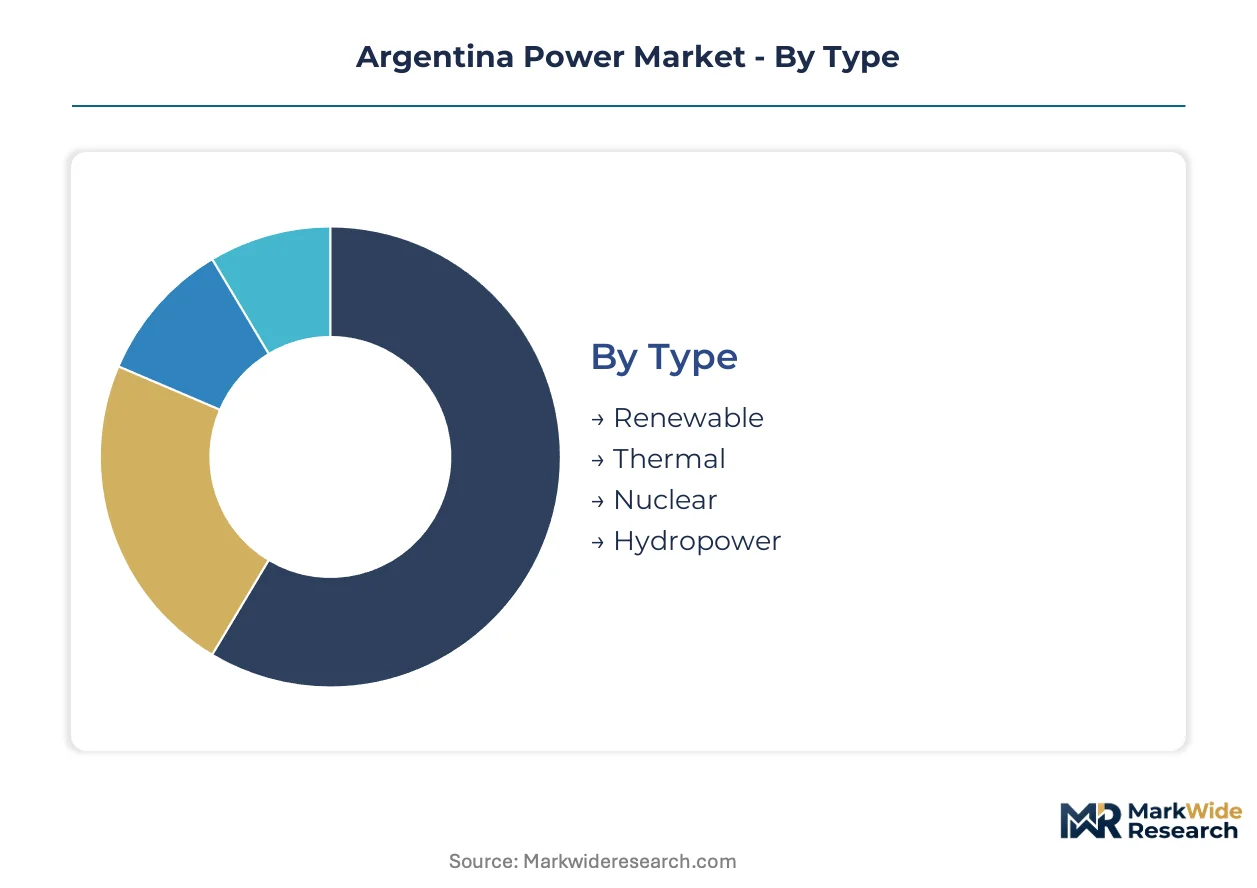
Argentina's power market segments reflect divergent capital requirements, regulatory treatment, and grid integration challenges. Understanding these divisions clarifies where developers allocate engineering resources and how offtakers match procurement strategies to supply characteristics.
Type:
Capital intensity varies sharply across generation technologies, with nuclear and large hydro demanding multi-billion dollar commitments while distributed solar requires minimal balance sheet deployment.
- Renewable:Wind and solar assets convert atmospheric flux into grid-synchronous alternating current through variable-speed turbines and photovoltaic inverters. Patagonian wind farms in Chubut and Santa Cruz provinces anchor new capacity additions, driven by RenovAr auction contracts that guarantee dollar-linked revenues.
- Thermal:Combined-cycle gas turbines and reciprocating engines burn natural gas or fuel oil to produce dispatchable baseload power. Buenos Aires province concentrates the legacy installed base, though margin compression from LNG import price volatility constrains new investment.
- Nuclear:Heavy water reactors at Atucha and Embalse generate baseload electrons with minimal carbon emissions. The Secretariat of Energy maintains state control over these assets due to their strategic fuel cycle requirements and national security dimensions.
- Hydropower:Reservoir and run-of-river installations harness Andean watershed gradients for seasonal peaking capacity. Comahue region facilities on the Limay and Neuquén rivers provide critical frequency regulation services to Cammesa.
Most installed capacity flows through Thermal. Expansion is steepest in Renewable.
End User:
Demand profiles diverge by consumption pattern, with industrial offtakers seeking firm capacity blocks while residential users prioritize tariff stability over supply flexibility.
- Residential:Urban households and rural electrification programs consume voltage-stabilized alternating current through distribution networks regulated by Ente Nacional Regulador de la Electricidad tariff schedules. Greater Buenos Aires density drives aggregate load concentration.
- Commercial:Retail chains, cold storage facilities, and office complexes in Córdoba and Rosario metropolitan areas deploy behind-the-meter solar to hedge against Cammesa wholesale price volatility.
- Industrial:Mining operations in Catamarca lithium corridors and petrochemical complexes in Neuquén contract hybrid renewable-thermal blocks with guaranteed availability clauses.
- Agriculture:Irrigation pumping and grain processing facilities in the Pampas region require seasonal load flexibility matched to harvest cycles and rainfall patterns.
Industrial buyers command the largest contracted capacity volumes. Commercial segment adoption of distributed generation is climbing the fastest.
Technology:
Equipment selection determines project development timelines, with photovoltaic permitting accelerating faster than combustion turbine environmental reviews.
- Photovoltaic:Silicon wafer arrays convert solar irradiance into direct current electricity through semiconductor junctions, with inverters synchronizing output to Cammesa grid codes. Module price declines have compressed levelized costs below new thermal construction.
- Wind Turbine:Horizontal-axis generators extract kinetic energy from Patagonian air masses with capacity factors exceeding thermal alternatives. Neuquén province hosts the most advanced blade manufacturing and maintenance clusters.
- Gas Turbine:Aero-derivative and heavy-frame machines provide spinning reserves and black-start capability for system reliability. Vaca Muerta shale proximity in western provinces influences fuel sourcing economics.
- Biomass:Agricultural residue combustion and anaerobic digesters convert organic waste into dispatchable generation. Santa Fe and Entre Ríos provinces leverage soy processing byproducts for captive industrial heat and power.
Photovoltaic dominates new capacity additions. Wind turbine deployment shows the steepest expansion trajectory in Patagonia.
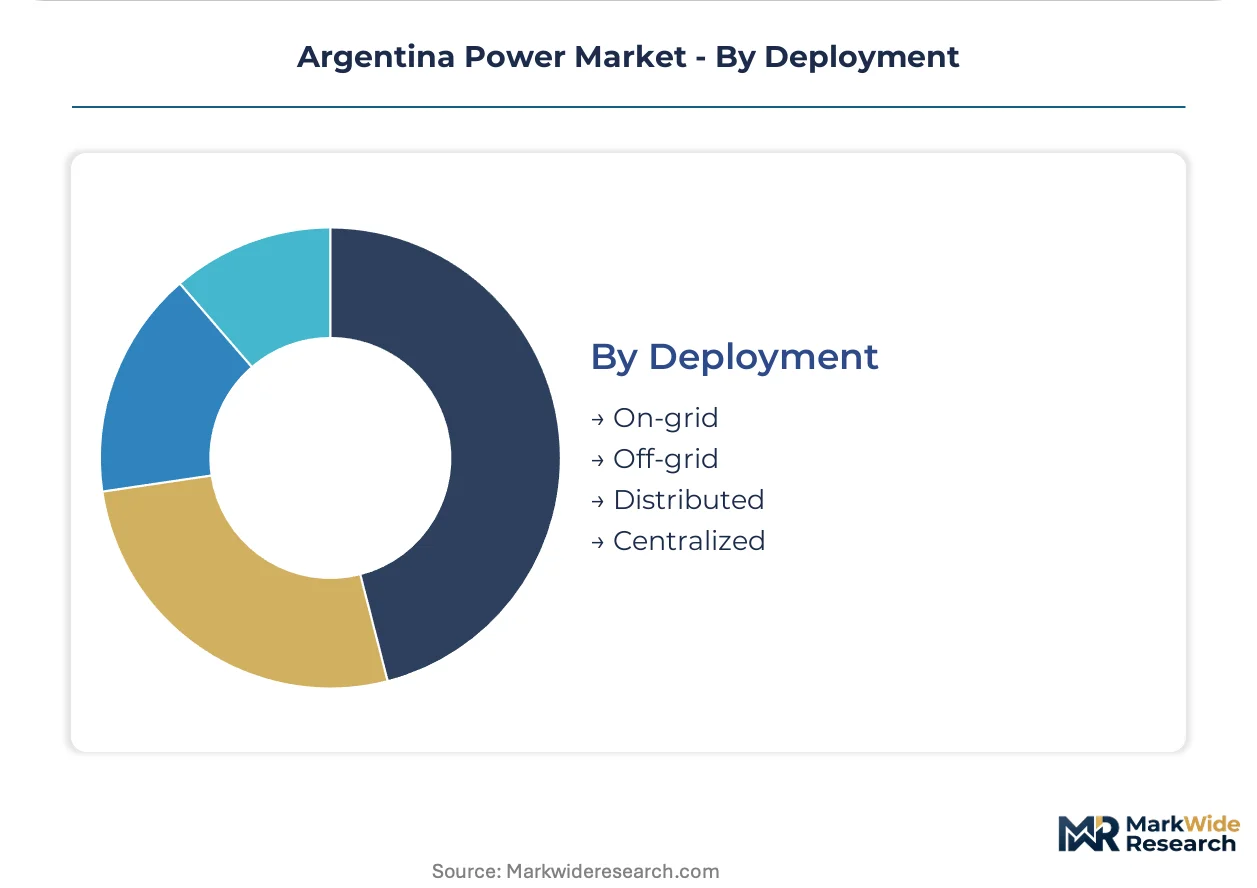
Deployment:
Grid connection architecture shapes regulatory jurisdiction, with centralized assets falling under wholesale market rules while distributed installations navigate net metering frameworks.
- On-grid:Synchronous generators connect directly to Cammesa-managed transmission infrastructure at voltages from 132 kV to 500 kV. These assets participate in wholesale dispatch and must comply with frequency response mandates.
- Off-grid:Isolated microgrids serve remote mining camps and rural settlements through captive diesel or renewable-battery hybrids. Southern Patagonia and Andean border regions concentrate this segment due to transmission distance economics.
- Distributed:Behind-the-meter installations under 10 MW capacity offset retail tariffs through net metering credits. Cammesa technical standards and Secretariat of Energy decrees govern interconnection queues.
- Centralized:Utility-scale plants exceeding 50 MW capacity anchor regional supply and require dedicated transmission access agreements. These projects dominate RenovAr auction awards and international financing flows.
Centralized assets carry the majority of installed megawatts. Distributed deployment is gaining share fastest as commercial users seek price hedges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's power sector emerged from state-led hydroelectric development in the mid-20th century, with the 1970s Yacyretá and Salto Grande megaprojects establishing the foundation for integrated national supply. Subsequent privatization waves and the 2001 crisis fragmented ownership structures, leaving today's market a hybrid of federal control over transmission and provincially licensed generation.
Buenos Aires Province
Petrochemical complexes in Bahía Blanca and La Plata industrial parks consume baseload blocks exceeding 500 MW combined. The provincial energy ministry enforces local content requirements for construction labor that delay project commissioning. Greater Buenos Aires distribution networks strain under summer cooling demand spikes that trigger Cammesa emergency dispatch protocols.
Neuquén Province
Vaca Muerta shale operations power drilling rigs through captive gas-fired microturbines that bypass wholesale market participation. The provincial hydrocarbons secretariat coordinates with Cammesa on grid interconnection standards for associated gas power plants. Rincón de los Sauces and Añelo host the densest concentration of oilfield electrification infrastructure in South America.
Chubut Province
Wind farms near Rawson and Puerto Madryn face curtailment rates exceeding 15 percent due to transmission bottlenecks on the 132 kV coastal trunk. The provincial renewable energy fund provides peso-denominated bridge financing for projects awaiting RenovAr auction award. Comodoro Rivadavia's oil refining complex maintains dual-fuel capability to switch between grid supply and self-generation.
Santa Cruz Province
Grid-isolated mining operations at Cerro Negro and Cerro Vanguardia rely on diesel-battery hybrids with renewable penetration below 10 percent. The national mining secretariat's electrification corridor study evaluates 220 kV extensions to unlock lithium brine processing demand. Río Turbio's coal-fired plant operates at minimum technical output due to federal carbon pricing exposure.
Córdoba Province
Automotive stamping plants in Villa María and Río Cuarto negotiate interruptible rate structures with EPEC, the provincial utility. The Córdoba energy agency's distributed generation registry shows commercial solar installations doubling annually since 2021. Jesús María hosts Argentina's only grid-connected biomass facility processing peanut hull residue from oilseed crushing.
Argentina Power Market Vendor Landscape
Premium-margin players sit above commodity-margin players across dispatch priority and contract duration. The market structures into three tiers: integrated utilities controlling transmission access, independent renewable developers with RenovAr-backed revenue streams, and provincial cooperatives serving captive agricultural load. Strategic differentiation concentrates on fuel sourcing security for thermal assets and grid code compliance speed for renewable interconnectors. Players defend position through backward integration into gas production and forward integration into industrial offtake relationships.
Within the integrated utility tier, Pampa Energía and Central Puerto anchor the competitive set through diversified generation portfolios spanning thermal, renewable, and hydroelectric assets. YPF Luz occupies a distinctive position linking upstream Vaca Muerta gas production with downstream power commercialization. Genneia exemplifies the pure-play renewable developer archetype, having scaled wind and solar capacity through successive RenovAr auction rounds without legacy thermal exposure.
| Leading Market Players |
|---|
| Genneia |
| YPF Luz |
| Pampa Energía |
| Central Puerto |
| AES Argentina |
| Enel Green Power Argentina |
| PCR |
| Coral Energía |
| Edenor |
| Others |
Supply Flow & Price Mechanics
Patagonian oil and gas operators anchor contracted capacity demand and lock in long-term power purchase agreements that set the dominant pricing benchmark across Argentina's wholesale electricity market. Their procurement scale forces developers to compete on dollar-linked tariff stability rather than spot market exposure, compressing margins for thermal generators while securing revenue visibility for renewable portfolios.
Pricing Analysis
Long-term offtake contracts with dollar-linked pricing clauses dominate transaction structures, separating RenovAr-backed renewable projects from peso-exposed thermal dispatch. Price differentiation hinges on firm capacity guarantees and grid code compliance certification speed, with hybrid wind-solar-battery configurations commanding premiums over intermittent-only supply. Cost compression in thermal generation is intensifying because LNG import price volatility erodes gas turbine margins. Industrial mining offtakers in Catamarca show the lowest price sensitivity, while commercial distributed generation adopters in Greater Buenos Aires prioritize payback period over tariff stability.
Supply Chain Analysis
Grid code compliance certification with Cammesa gates equipment procurement, forcing developers to pre-qualify inverters and turbine control systems before financial close. Module supply concentrates in China, inverter manufacturing anchors in Germany and China, and blade fabrication clusters in Brazil and Argentina's Neuquén province. Project development rests on lithium-ion battery imports from South Korea and China for storage co-location, silicon wafer supply from Chinese polysilicon refiners, and aero-derivative gas turbines from US and European OEMs. Single-source vulnerability runs through Chinese photovoltaic module supply. Distribution runs through Cammesa-managed wholesale market clearing with provincial utility last-mile dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's power market has entered a late-cycle quality phase where developer viability depends on transmission access certainty and grid code compliance velocity rather than pure renewable resource capture. Premium industrial offtakers now demand firm renewable blocks with battery backing, disqualifying intermittent-only projects from lithium corridor and petrochemical procurement.
For Market Incumbents: Deepen backward integration into Vaca Muerta gas production to backstop renewable intermittency and stabilize dispatch revenue. Incumbents must accelerate grid code certification queue navigation to defend against pure-play renewable developers with faster Cammesa interconnection timelines. Control of captive fuel supply and dispatchable thermal assets remains the critical margin defense lever against hybrid renewable entrants. For New Entrants and Emerging Players: Grid-isolated mining camps in Santa Cruz province represent the most penetrable offtake segment, with diesel-battery hybrid replacement demand exceeding 200 MW aggregate capacity. New entrants should target behind-the-meter commercial installations in Córdoba and Rosario metropolitan areas where net metering regulatory clarity has simplified interconnection standards. A direct EPC-own-operate model with equipment vendor financing partnerships offers the fastest path to operational cash flow without wholesale market participation risk. For Investors and Strategic Acquirers: Integrated oil and gas majors with power trading desks are the most active acquirer in this space, seeking captive offtake integration for their extraction operations. Long-term viability across the projection horizon favors developers with contracted RenovAr capacity and secured transmission access agreements over merchant-exposed thermal assets. Acquisition targets should display diversified technology portfolios spanning wind, solar, and battery storage with minimal peso-denominated revenue exposure. The signal to monitor is Cammesa transmission construction timeline announcements for the Choele Choel-Buenos Aires 500 kV corridor, which would unlock stranded Patagonian wind capacity and revalue developer portfolios with southern province exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Renewable-Storage Buildout | Patagonian wind-solar-battery configurations deliver firm capacity blocks that satisfy mining offtaker carbon-free supply requirements. |
| Backward Integration into Gas Production | YPF Luz's Vaca Muerta captive supply insulates dispatch revenue from international LNG spot price volatility. |
| Transmission Access Securement | Early commitment to 500 kV trunk line capacity reservations de-risks stranded generation exposure for Comahue wind portfolios. |
| Distributed Generation Platform Launch | Behind-the-meter commercial solar installations in Greater Buenos Aires bypass Cammesa wholesale price volatility for retail rate hedging. |
| Green Certification Program | Renewable energy certificate trading under RenovAr mechanism unlocks premium pricing from export-oriented industrial buyers. |
Methodological Framework
Bottom-up industrial load modeling reconciled against top-down generation capacity tracking forms the analytical core of this study. Primary interviews with IPP project developers, Cammesa grid planning officers, EPC contractors, and Ente Nacional Regulador de la Electricidad tariff specialists were cross-validated against secondary sources including Secretariat of Energy auction announcements, Cammesa dispatch statistics, and IEA country electricity profiles. Triangulation between stakeholder-reported contract structures and regulatory filing documentation ensured revenue model accuracy across thermal and renewable asset classes.
Input-output matrices mapped generation capacity additions by technology and province against industrial demand growth in Neuquén oilfields and Catamarca lithium corridors. Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from capacity-weighted average tariff trajectories and peso-dollar exchange rate assumptions applied across the analysis window. Forecast inputs incorporated Vaca Muerta shale production outlooks and RenovAr auction award schedules.
Underlying measurement precision varies by segment; centralized utility-scale projects with RenovAr contracts carry tighter precision than merchant-exposed thermal assets. Forecasts reflect assumptions regarding federal fiscal capacity to complete promised transmission infrastructure and Cammesa's ability to clear grid code certification backlogs. A model refresh is warranted upon material change in Secretariat of Energy auction design or federal infrastructure commitment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Smart Power Market
Power
North America CHP Market
Power
Qatar Power Market
Power
Marine Thermal Fluid Heaters Market
Power
Canada Power Market
Power
Wireless Power Receiver Market
Power
Iran Power Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Kuwait Power Market
Power
Global Ancillary Services Power Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Australia Power Market
Power
Existent Gum Steam Generator Market
Power
Japan Power Market
Power
Power Purchase Agreement Market
Power
Temporary Load Bank Rental Market