

Residential Micro Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Micro Inverter Market Insights
Homeowners with rooftop photovoltaic installations is reorganizing procurement patterns across the residential micro inverter supply chain as lease-to-own transitions accelerate. Enphase Energy leverages its integrated ecosystem of monitoring hardware and battery storage to sustain premium positioning in North American distribution channels. APsystems competes through module-level power electronics architectures that reduce balance-of-system costs for solar installers managing complex roof geometries.
A residential micro inverter converts direct current from individual solar panels into grid-compliant alternating current at the module level rather than through a centralized string inverter, typically operating at 95-97% peak efficiency with maximum power point tracking per panel. Its primary purpose is to optimize energy harvest from partially shaded or differently oriented arrays while eliminating single points of failure that plague string-based systems. Single-phase units dominate existing installed bases across mature residential solar markets, though three-phase variants are gaining traction in multi-dwelling and small commercial-adjacent installations where local utilities permit aggregated interconnection. Transformerless topologies anchor cost-sensitive segments in Asia-Pacific manufacturing hubs, while high-frequency designs command technical preference among European installers navigating strict electromagnetic compatibility requirements under CE marking protocols.
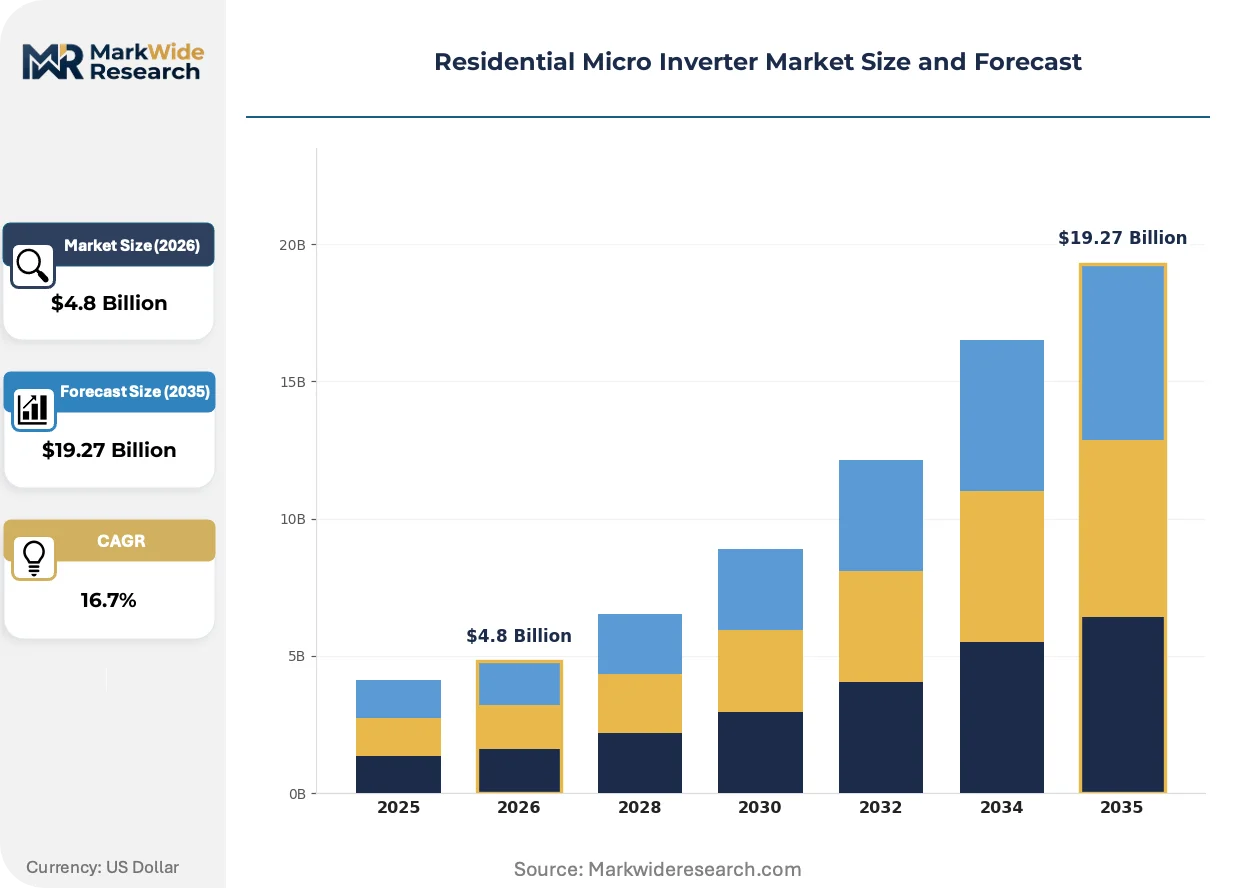
FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in wholesale markets, creating new revenue stack opportunities for micro inverter-enabled residential batteries that reshape product roadmaps toward bidirectional power flow. The EU Green Deal and national building performance standards across Germany, Italy, and the Netherlands mandate solar-ready construction for new residential permits, tightening efficiency thresholds that favor module-level electronics over conventional string alternatives. Stakeholders must monitor evolving interconnection queue reforms and dynamic tariff structures that determine whether panel-level optimization delivers sufficient economic return to justify hardware premiums over string inverter alternatives with rapid shutdown compliance.
Market Dynamics
Module-level power electronics is compressing product lifecycles as installers demand granular visibility into per-panel performance metrics and rapid shutdown compliance becomes mandatory across major solar markets.
Growth Catalysts
- FERC Order 2222:Aggregated distributed energy resources now access wholesale markets, creating revenue stacking opportunities for bidirectional micro inverters paired with residential battery storage.
- EU Green Deal building mandates:Solar-ready construction requirements in Germany, Italy, and Netherlands are tightening efficiency thresholds that favor module-level electronics over string alternatives in new residential permits.
- Hurricane resilience priorities:Florida's grid-hardening initiatives and post-storm rebuild cycles are accelerating inverter replacement demand and new-build solar attachment rates.
Market Restraints
- Silicon carbide supply concentration:High-efficiency switching components depend on limited foundry capacity concentrated in Taiwan and Japan, creating input cost volatility for premium micro inverter SKUs.
- String inverter rapid shutdown compliance:NEC 2017/2020 rapid shutdown requirements have enabled string inverter manufacturers to close the safety gap at lower price points, threatening micro inverter differentiation.
- Transformerless topology limitations:Cost-sensitive Asian manufacturing hubs face electromagnetic compatibility barriers under CE marking protocols that constrain export flexibility to European markets.
Strategic Opportunities
- V2H bidirectional integration:Vehicle-to-home power flow standards are converging with residential solar controls, opening white space for micro inverters that manage EV battery discharge alongside rooftop generation.
- Texas net metering volatility:ERCOT market reforms and retail rate restructuring are creating demand for panel-level optimization that maximizes self-consumption during dynamic pricing events.
- Installer direct procurement platforms:Digital distributor models are bypassing traditional electrical wholesaler markups, enabling margin capture for vendors with logistics infrastructure.
Industry Challenges
- IEEE 1547-2018 certification timelines:Interconnection standard updates require extensive grid-support function validation that compresses product launch windows and strains engineering resources.
- Multi-protocol integration complexity:Micro inverters must simultaneously communicate with battery management systems, EV chargers, and utility demand response platforms, fragmenting firmware development priorities.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Micro Inverter Market Trends and Innovations
Power semiconductor architectures and grid-interconnection protocols are reshaping competitive positioning as efficiency benchmarks rise and distributed energy resource aggregation matures.
GaN-based switching topologies are bifurcating the efficiency frontier in residential micro inverters. European installers navigating strict electromagnetic compatibility requirements under CE marking protocols are adopting these designs fastest. The technology is bifurcating vendor roadmaps between cost-optimized silicon MOSFET platforms and premium GaN-enabled variants targeting 99% peak efficiency claims.
California's NEM 3.0 export compensation restructuring is forcing design pivots toward self-consumption optimization. The policy reduces export credit values and incentivizes battery pairing, compressing payback calculations for solar-only installations. Installers in the state are responding by upselling storage-integrated micro inverter bundles that maximize behind-the-meter value capture.
Homeowner acquisition models are migrating from third-party leases to direct ownership financed through property-assessed clean energy mechanisms. Suburban and exurban developments in Texas and Florida are driving this displacement fastest. Installer sales cycles are compressing as digital quoting tools and satellite imagery reduce site assessment friction.
Residential Micro Inverter Market Segmentation
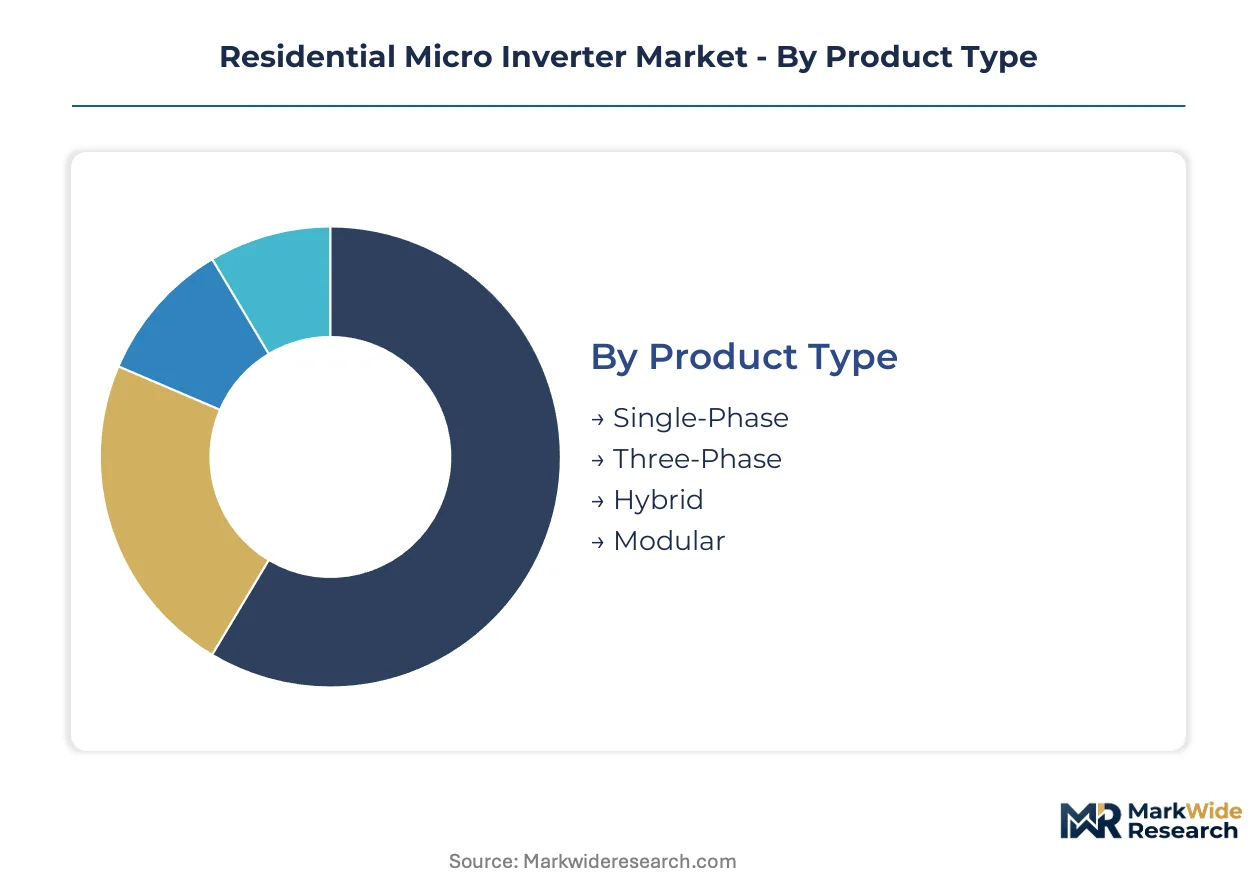
Residential micro inverter segmentation reflects divergent certification requirements across interconnection standards and the economic trade-offs between module-level optimization and string-based alternatives. Product architecture choices directly determine which geographies vendors can access and which incentive structures maximize customer returns.
Product Type:
Regulatory differentiation between single-phase and three-phase interconnection permissions shapes product portfolio prioritization across utilities with varying distribution infrastructure.
- Single-Phase:Dominates existing installed bases across mature residential solar markets with 95-97% peak efficiency and simplified NEC rapid shutdown compliance. California, Texas, and Florida homeowners drive replacement cycles as net metering volatility and hurricane resilience priorities accelerate attachment rates.
- Three-Phase:Gaining traction in multi-dwelling and small commercial-adjacent installations where local utilities permit aggregated interconnection. IEEE 1547-2018 grid-support function validation compresses launch windows for vendors targeting this higher-power segment.
- Hybrid:Integrates battery storage management with DC-AC conversion, enabling bidirectional power flow for FERC Order 2222 wholesale market participation.
- Modular:Scalable architectures reduce balance-of-system costs for complex roof geometries common in suburban developments.
Single-phase handles the majority of throughput; three-phase is the fastest mover on share.
Technology:
Cost tier separation between silicon MOSFET platforms and premium wide-bandgap alternatives determines which efficiency thresholds vendors can credibly claim.
- Transformerless:Anchors cost-sensitive manufacturing with reduced component count and lighter thermal management. Asian production hubs face electromagnetic compatibility barriers under CE marking protocols that constrain European export flexibility.
- High-Frequency:Commanding technical preference among European installers navigating strict EMC requirements under CE marking protocols. GaN-based switching variants target 99% peak efficiency claims in premium positioning strategies.
- Capacitive:Emerging topology for reduced switching losses in compact form factors suitable for integrated module-level electronics.
- Digital Signal Processor:Enables granular maximum power point tracking per panel and firmware-upgradable grid-support functions for evolving IEEE 1547 compliance.
Transformerless technology captures the highest shipment volumes; high-frequency designs are expanding most quickly in revenue contribution.
Application:
Customer type differentiation separates self-consumption optimizers from export-dependent system architectures under dynamic tariff restructuring.
- Residential Rooftop PV Systems:Core demand concentration as suburban and exurban homeowners displace third-party leasing with direct ownership models. NEM 3.0 export compensation cuts in California force design pivots toward battery-integrated bundles.
- Grid-Tied Solar:Interconnection queue reforms and dynamic tariff structures determine whether panel-level optimization justifies hardware premiums over rapid shutdown-compliant string alternatives.
- Off-Grid Solar:Remote and backup-power applications requiring integrated charge control and energy storage management.
- Solar Power Backup:Hurricane-driven resilience priorities in Florida accelerate replacement demand for systems with islanding capability during grid outages.
Residential rooftop systems handle the majority of throughput; grid-tied solar is climbing the fastest as utility rate structures evolve.
End User:
Procurement channel concentration determines margin capture for vendors with installer-direct digital platforms versus traditional electrical wholesaler routes.
- Homeowners:Fastest-expanding buyer archetype in suburban and exurban developments as distributed solar ownership models displace third-party leasing arrangements financed through property-assessed clean energy mechanisms.
- Solar Installers:Demand granular visibility into per-panel performance metrics and rapid shutdown compliance, compressing product lifecycles through module-level power electronics preferences.
- Real Estate Developers:EU Green Deal solar-ready construction mandates in Germany, Italy, and Netherlands tighten efficiency thresholds for new residential permits.
- Renewable Energy Consultants:Technical specification influence in multi-protocol integration requirements spanning battery management, EV charging, and utility demand response platforms.
Homeowners handle the majority of throughput; solar installers are gaining share fastest as procurement consolidates around installer-direct platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ERCOT grid interconnect underwrites Texas's outsized role in residential solar deployment, while California's transmission constraints and Florida's hurricane-hardened distribution infrastructure shape divergent micro inverter demand profiles across North American markets.
United States
California homeowners drive battery-integrated micro inverter bundles under NEM 3.0 export compensation cuts. FERC Order 2222 enables wholesale market participation for aggregated distributed energy resources. The Los Angeles-San Diego corridor concentrates installer procurement platforms.
Germany
The EU Green Deal mandates solar-ready construction for new residential permits in Baden-Württemberg and Bavaria. CE marking protocols under EMC Directive 2014/30/EU enforce strict electromagnetic compatibility thresholds. Munich's solar installer networks favor high-frequency GaN-based switching topologies.
China
Transformerless manufacturing hubs in Jiangsu and Zhejiang provinces anchor cost-sensitive production for export markets. GB/T 19964-2012 grid interconnection standards govern distributed photovoltaic integration. Yangtze River Delta electronics clusters supply silicon carbide switching components.
Australia
Dynamic export tariffs in New South Wales and Victoria maximize self-consumption value for panel-level optimization. Clean Energy Council accreditation requirements compress product certification timelines. Sydney's residential solar attachment rates lead national replacement cycles.
Netherlands
Net metering policy transitions in 2025 accelerate battery pairing decisions among Rotterdam and Amsterdam homeowners. Building codes under the EU Energy Performance of Buildings Directive tighten efficiency thresholds. Eindhoven's smart grid pilot programs test bidirectional power flow integration.
Residential Micro Inverter Market Competitive Landscape
Listed leaders compete with private specialists across capital access and technology licensing dimensions. The vendor base stratifies between integrated ecosystem providers and component-focused module-level power electronics specialists. Three archetypes dominate: premium-platform integrators, cost-optimized Asian manufacturers, and European EMC-compliant engineering houses. Competitive moves concentrate on installer-direct digital distribution bypassing traditional electrical wholesaler channels and GaN-based efficiency tier differentiation.
Within the premium-platform tier, Enphase Energy exemplifies integrated ecosystem positioning through monitoring hardware and storage bundling. APsystems occupies a position as a module-level power electronics specialist serving complex roof geometry applications. Hoymiles represents the cost-optimized manufacturing archetype with transformerless topology production serving price-sensitive procurement channels.
| Leading Market Players |
|---|
| Enphase Energy |
| APsystems |
| Hoymiles |
| Darfon Electronics |
| SMA Solar Technology |
| Altenergy Power Systems |
| Envertech |
| Fimer Group |
| Sensata Technologies |
| Others |
Pricing and Supply Chain Analysis
Foundry utilization rates above 85% in Taiwan and Japan are compressing silicon carbide switching component availability and elevating cost floors for premium micro inverter SKUs. This capacity tightness simultaneously concentrates supply-side leverage among wide-bandgap semiconductor manufacturers and forces pricing stratification across efficiency tiers.
Pricing Analysis
Volume-discount tiering separates GaN-enabled premium units from silicon MOSFET standard lines and transformerless economy SKUs. Price differentiation rests on CE marking compliance grade and installer-direct procurement scale rather than brand premium alone. Pricing pressure stems from string inverter rapid shutdown compliance narrowing the safety-feature gap at lower price points. Solar installers managing complex roof geometries show lowest price sensitivity, while cost-optimized Asian manufacturing hubs face highest margin compression.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are extending inbound logistics cycles for European-bound transformerless topologies. Manufacturing concentrates in Jiangsu and Zhejiang provinces for cost-sensitive production, with Taiwan and Japan anchoring silicon carbide component supply. Raw material dependencies include gallium nitride substrates, high-purity silicon wafers, and rare-earth magnetic materials. Single-source vulnerability in wide-bandgap foundry capacity represents the dominant structural risk. Distribution runs through installer-direct digital platforms that bypass traditional electrical wholesaler markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222's enablement of wholesale market participation for aggregated distributed energy resources marks a regulatory inflection that will reshape product roadmaps toward bidirectional power flow. This policy shift accelerates competitive disruption as hardware vendors race to capture new revenue stack opportunities.
For Market Incumbents: Compound ecosystem lock-in through deeper integration of battery management firmware with micro inverter controls. String inverter manufacturers closing the rapid shutdown compliance gap at lower price points threaten differentiation. Prioritize IEEE 1547-2018 certification investment to compress product launch windows and defend installer channel relationships against emerging GaN-based efficiency claims.
For New Entrants and Emerging Players: Firmware-upgradable grid-support functions for evolving interconnection standards represent a service-layer gap where incumbents under-serve. Target three-phase multi-dwelling installations in Texas and Florida where IEEE 1547 validation requirements strain incumbent engineering resources. Pursue direct digital distributor relationships that bypass traditional electrical wholesaler channels and capture margin through logistics infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ecosystem providers bundling monitoring hardware with storage and energy management services. Long-term viability in this market hinges on sustained R&D access to wide-bandgap semiconductor roadmaps and installer channel control. Monitor silicon carbide foundry capacity expansion announcements as the critical inflection signal for input cost trajectory and premium SKU margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Topology Transition | Enables 99% peak efficiency claims under strict CE marking EMC Directive 2014/30/EU protocols. |
| Bidirectional Power Flow Certification | Unlocks FERC Order 2222 wholesale market revenue stacking for residential battery aggregation. |
| Installer-Direct Platform Buildout | Bypasses electrical wholesaler markups and captures margin in California, Texas, and Florida procurement channels. |
| Three-Phase Product Line Expansion | Addresses multi-dwelling IEEE 1547-2018 grid-support validation gaps in ERCOT and Florida markets. |
| Silicon Carbide Supply Agreement | Secures foundry capacity in Taiwan and Japan against input cost volatility for premium SKU portfolios. |
Research Methodology
A spread of perspectives from micro inverter product managers, solar installer procurement leads, utility interconnection engineers, and semiconductor supply specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FERC filings, NREL technical reports, IEEE standards documentation, and customs trade data for power electronics components. Bottom-up shipment modeling and top-down addressable market sizing were triangulated to constrain variance.
Segmentation dimensions modeled include power rating tier, switching topology, phase configuration, and regional regulatory framework across the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle acceleration, and attachment rate assumptions by buyer archetype. Forecast inputs incorporated net metering policy trajectory, hurricane resilience infrastructure spending, and EU Green Deal building mandate implementation schedules.
Underlying assumptions cover stable silicon carbide foundry capacity expansion, with deviation risk concentrated in Taiwan-Japan supply concentration and interconnection standard update timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.