
 Global Power-To-X Market | 2026-2036
Global Power-To-X Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power-To-X Market Outlook
ISO 19880-1 gating for hydrogen fueling station components is unwinding competitive access across the Power-To-X value chain. Siemens Energy leverages its electrolyzer manufacturing scale to anchor European green hydrogen supply. Nel ASA specializes in PEM electrolyzer stacks and competes on modular system architectures. thyssenkrupp sustains its position through alkaline electrolyzer technology leadership and in-house production of critical cell components.
Power-to-X denotes electrochemical conversion of renewable electricity into energy carriers or chemical feedstocks, typically requiring electrolyzer efficiencies above 65% lower heating value and operating pressures between 30-80 bar for downstream process integration. Electrolysis dominates installed capacity while synthetic fuels applications command premium margins due to aviation and maritime offtake agreements. Deployment configurations increasingly favor hybrid arrangements co-locating offshore wind with onshore hydrogen storage and pipeline injection.
The EU Green Deal and F-Gas Regulation shape equipment standards and refrigerant choices for hydrogen liquefaction, while Germany's KBA certifies fuel quality for mobility applications. EPA hydrogen hub funding in the United States and Japan's METI hydrogen roadmap create divergent compliance pathways for multinational suppliers. Stakeholders must monitor certification reciprocity between jurisdictions to avoid stranded asset risk in export-oriented projects.
Market Dynamics
Offshore wind-to-hydrogen coupling is restructuring capital deployment across the Power-To-X sector, with developers prioritizing electrolyzer co-location at grid-constrained coastal sites over traditional transmission buildout.
Growth Catalysts
- EU Green Deal carbon border adjustment:Steelmakers in Germany face embedded carbon tariffs on imports, accelerating hydrogen-based direct reduction furnace commitments.
- Aviation offtake agreements:Synthetic fuel purchase commitments from European and Asian carriers create demand visibility for e-kerosene production investments.
- Alkaline electrolyzer efficiency gains:Cell stack improvements pushing system efficiencies above 70% lower heating value are lowering levelized hydrogen costs for industrial buyers.
Market Restraints
- Iridium supply concentration:PEM electrolyzer manufacturers depend on South African and Russian iridium for catalyst coatings, exposing supply chains to geopolitical disruption.
- Grid connection queuing delays:Renewable project interconnection backlogs in Germany and Spain postpone electrolyzer energization timelines by 18-36 months.
- Liquid organic hydrogen carrier competition:LOHC transport and storage systems offer alternative logistics pathways that fragment standardization efforts for pure hydrogen infrastructure.
Strategic Opportunities
- US Gulf Coast hydrogen hub development:EPA funding allocations for regional clean hydrogen production clusters attract equipment suppliers seeking manufacturing scale.
- Maritime ammonia fuel conversion:Engine manufacturers and shipyards in South Korea and Japan are retrofitting vessels for ammonia combustion, opening e-ammonia offtake channels.
- Power-to-liquid methanol for chemicals:German and Dutch chemical producers are contracting dedicated methanol synthesis capacity to displace gray methanol in formaldehyde and acetic acid production.
Industry Challenges
- Electrolyzer commissioning expertise gap:Specialized technicians for alkaline and PEM system startup and optimization remain scarce relative to installed capacity growth.
- ISO 19880-1 certification timelines:Hydrogen fueling station component testing protocols extend equipment qualification periods, delaying station deployment schedules.
- Pipeline steel embrittlement standards:Existing natural gas infrastructure requires material validation for hydrogen service, complicating injection and blending project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power-To-X Market |
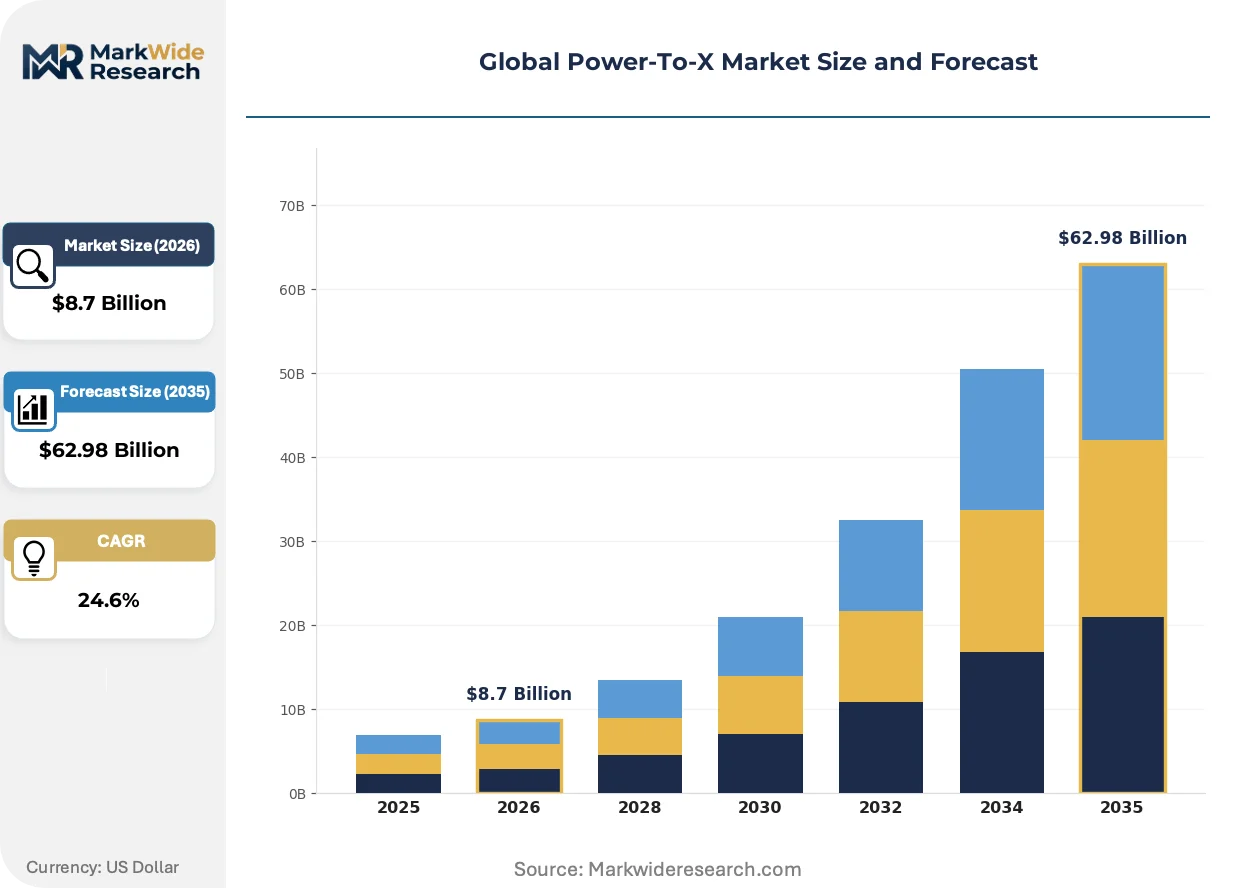
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Methanation, Anhydrous Ammonia, Hydrogenation Application: Energy Storage, Industrial Feedstock, Fuel Cell Vehicles, Synthetic Fuels End User: Utilities, Heavy Industries, Transportation, Chemical Manufacturers Deployment: Onshore, Offshore, Hybrid, Standalone |
| Companies Covered | Siemens Energy, thyssenkrupp, Linde plc, Air Liquide, Nel ASA, ENGIE, ITM Power, Valmet, MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power-To-X Market Strategic Shifts
System integration architectures are displacing standalone electrolyzer sales as the primary value capture mechanism, with vendors bundling storage, compression, and offtake conditioning into single-contract solutions.
Solid oxide electrolysis is supplanting incumbent alkaline and PEM technologies in high-temperature industrial applications. Steel and cement producers in the Netherlands and Denmark are piloting SOEC units for process heat integration. The technology is compressing the cost gap between green and gray hydrogen for continuous industrial demand.
Japan's METI hydrogen roadmap is mandating cost reduction targets and supply chain localization requirements for imported hydrogen derivatives. Equipment suppliers must establish domestic manufacturing partnerships or joint ventures to qualify for public procurement. The policy is reshaping competitive entry strategies for European and Korean electrolyzer manufacturers.
Long-term offtake contracting is replacing spot market exposure for project financeability. Developers in Denmark and Germany are securing 10-15 year purchase agreements with industrial buyers before final investment decisions. This shift is concentrating development activity around creditworthy offtakers in chemicals and refining rather than speculative mobility applications.
Global Power-To-X Market Segmentation
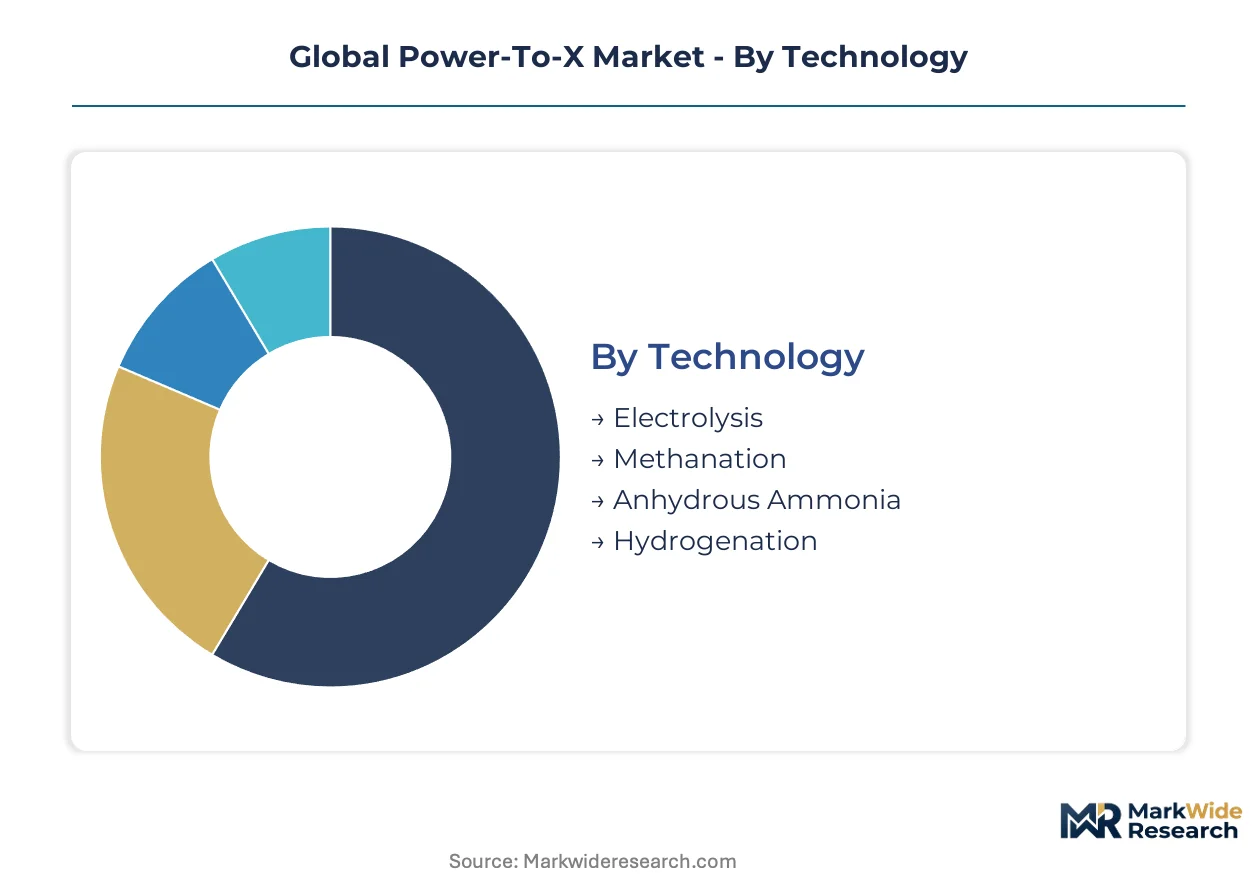
Power-to-X deployment configurations fragment the value chain into distinct equipment and service markets. Each segment demands specialized engineering competencies and carries divergent margin profiles based on integration complexity and offtake certainty.
Technology:
Margin pools concentrate in electrolyzer system integration rather than component supply, with project developers capturing value through bundled performance guarantees.
- Electrolysis:Alkaline and PEM cell stacks convert renewable electricity to hydrogen at 65-70% lower heating value efficiency. German steelmakers and Dutch chemical producers anchor demand for megawatt-scale installations under EU Green Deal carbon pricing.
- Methanation:Catalytic hydrogenation of carbon dioxide yields synthetic methane for grid injection. Danish biogas upgrading facilities and German power-to-gas pilots drive equipment orders, though catalyst replacement costs constrain project returns.
- Anhydrous Ammonia:Haber-Bosch synthesis adapted for renewable hydrogen feedstock serves maritime fuel and fertilizer markets. South Korean shipyards and Japanese engine manufacturers are qualifying e-ammonia for dual-fuel vessel retrofits.
- Hydrogenation:Direct conversion processes produce synthetic liquid fuels for aviation and maritime applications. Offtake agreements from European and Asian carriers provide demand visibility for e-kerosene and e-diesel investments.
Electrolysis holds installed capacity. Methanation is rotating up the share rankings as grid injection regulations mature.
Application:
Volume deployment currently favors industrial feedstock substitution over speculative mobility markets, with synthetic fuels commanding premium pricing through aviation compliance mandates.
- Synthetic Fuels:E-kerosene and e-methanol production for aviation and maritime sectors carries the steepest expansion trajectory. EU ReFuelEU Aviation mandates and IMO decarbonization targets lock in offtake visibility for project finance.
- Industrial Feedstock:Green hydrogen and ammonia displace gray hydrogen in ammonia synthesis, steel direct reduction, and methanol production. German steelmakers and Dutch chemical clusters contract dedicated supply under carbon border adjustment exposure.
- Energy Storage:Power-to-gas and power-to-liquid systems buffer renewable intermittency for seasonal electricity reconversion. Grid operators in Denmark and Germany pilot salt cavern storage with pipeline injection for winter discharge.
- Fuel Cell Vehicles:Hydrogen refueling infrastructure serves heavy-duty trucking and bus fleets. ISO 19880-1 certification timelines for station components delay deployment schedules relative to electrolyzer capacity growth.
Industrial feedstock dominates current capacity. Synthetic fuels is climbing the fastest as aviation offtake contracts lengthen.
End User:
Procurement patterns diverge between regulated utilities with cost-pass-through mechanisms and industrial buyers exposed to carbon border adjustments.
- Heavy Industries:Steel, cement, and chemicals producers purchase electrolyzer capacity to displace fossil feedstocks and process fuels. Thyssenkrupp and ArcelorMittal installations in Germany demonstrate direct reduction furnace integration.
- Chemical Manufacturers:Ammonia and methanol producers contract dedicated hydrogen supply for formaldehyde, acetic acid, and fertilizer synthesis. Dutch and German producers lead e-chemical offtake contracting.
- Utilities:Power sector players develop hydrogen storage and reconversion assets for grid balancing. Danish offshore wind operators co-locate electrolyzers at grid-constrained coastal sites.
- Transportation:Fleet operators and infrastructure developers procure hydrogen and synthetic fuels for compliance with EU AFIR and national zero-emission mandates. Maritime ammonia retrofits in South Korea and Japan expand the addressable market.
Heavy industries holds installed capacity. Chemical manufacturers is rotating up the share rankings as e-chemical contracting accelerates.
Deployment:
Capital deployment is shifting from standalone electrolyzer sales toward integrated system architectures that bundle generation, storage, and conditioning.
- Hybrid:Co-located offshore wind, electrolyzer, and hydrogen storage configurations optimize grid constraint economics. Danish and Dutch hydrogen valleys concentrate development activity around pipeline injection points.
- Offshore:Platform-mounted electrolyzers at wind farms eliminate transmission buildout for distant generation. North Sea developments test subsea cable replacement with hydrogen pipeline export.
- Onshore:Grid-connected electrolyzer installations at industrial demand centers minimize transport costs. German steel clusters and Rotterdam port facilities anchor onshore capacity.
- Standalone:Merchant electrolyzer sales to third-party integrators persist in markets with immature project development ecosystems. Equipment suppliers compete on modular system architectures for early-stage markets.
Onshore holds installed capacity. Hybrid is rotating up the share rankings as offshore wind-to-hydrogen coupling matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea hydrogen backbone pipeline network underwrites Europe's role in Power-to-X infrastructure, connecting offshore wind clusters to industrial demand centers across multiple jurisdictions.
Germany
Steelmakers in the Ruhr and coastal regions contract electrolyzer capacity for direct reduction furnaces under carbon border adjustment exposure. The KBA certifies fuel quality standards for mobility applications while the EU Green Deal shapes equipment procurement timelines. Hydrogen valleys in Lower Saxony and Brandenburg concentrate pipeline injection and salt cavern storage development.
Netherlands
Rotterdam port facilities anchor e-fuel and e-ammonia production for maritime offtake agreements. The F-Gas Regulation governs refrigerant choices for hydrogen liquefaction equipment. Offshore wind parks in the North Sea feed dedicated electrolyzer arrays at grid-constrained coastal sites.
Denmark
Utilities develop hybrid configurations co-locating offshore wind with onshore hydrogen storage and pipeline injection. National energy policy prioritizes power-to-gas systems for seasonal grid balancing. Esbjerg and the Danish hydrogen valley concentrate electrolyzer manufacturing partnerships and project development activity.
United States
EPA hydrogen hub funding allocations attract equipment suppliers to Gulf Coast clean hydrogen production clusters. The IRA production tax credits improve project financeability for electrolyzer installations. Texas and Louisiana industrial corridors anchor regional hub development around existing pipeline and storage infrastructure.
Japan
Shipyards and engine manufacturers in Nagoya and Kobe retrofit vessels for ammonia combustion under METI hydrogen roadmap mandates. Cost reduction targets and supply chain localization requirements reshape competitive entry for foreign equipment suppliers. E-ammonia import terminals concentrate in coastal industrial zones for power generation and maritime fuel applications.
Global Power-To-X Market Competitive Environment
Listed leaders compete with private specialists across electrolyzer technology platforms, creating a tiered structure where scale advantages concentrate in system integration rather than component supply. Siemens Energy and Nel ASA anchor publicly traded positions while private industrial conglomerates retain captive technology development. Three archetypes dominate: diversified energy majors leveraging balance sheet capacity, pure-play electrolyzer specialists competing on modular architectures, and engineering contractors bundling construction risk with equipment procurement. Capacity expansion and strategic partnerships represent the dominant competitive moves, with developers prioritizing long-term offtake contracting to secure project finance.
Among European-based industrial groups, Siemens Energy, thyssenkrupp, and Nel ASA occupy positions spanning the technology spectrum from alkaline to PEM electrolyzer platforms. Siemens Energy exemplifies the diversified energy major archetype with integrated project development capabilities. Thyssenkrupp represents engineering-led system integration with in-house production of critical cell components. Nel ASA anchors the pure-play specialist tier with modular system architectures targeting distributed deployment configurations. These three companies collectively illustrate how competitive positioning fragments across technology choices and vertical scope decisions rather than consolidating around a single dominant model.
| Leading Market Players |
|---|
| Siemens Energy |
| thyssenkrupp |
| Linde plc |
| Air Liquide |
| Nel ASA |
| ENGIE |
| ITM Power |
| Valmet |
| MAN Energy Solutions |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracting locks in both electrolyzer supply access and hydrogen price visibility for industrial buyers, with German steelmakers and Dutch chemical producers securing decade-spanning agreements under EU Green Deal carbon border exposure. This contract structure compresses spot market liquidity while amplifying price transparency for creditworthy offtakers in refining and ammonia synthesis.
Pricing Analysis
Certification level creates the primary spread across electrolyzer system quotes, with ISO 19880-1-compliant fueling station components commanding premiums over uncertified industrial-grade equipment. Project-based pricing dominates megawatt-scale installations, though modular PEM systems compete on per-kilowatt transactional metrics. Cost compression in alkaline electrolyzer stacks intensifies pricing pressure as Chinese manufacturers expand export capacity. Chemical producers exhibit the highest price sensitivity due to gray hydrogen substitution economics, while aviation offtakers accept premium e-kerosene pricing for compliance certainty.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for South Korean-manufactured PEM cell stacks and Japanese precision components. Supply concentrates in Germany, Denmark, and China for electrolyzer assembly, with iridium catalyst coatings drawing from South African mining operations. Single-source vulnerability pervades iridium procurement for PEM manufacturers, exposing margins to geopolitical disruption. Distribution runs through EPC contractor networks for integrated system delivery, with direct OEM sales persisting in mature European hydrogen valleys.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-to-X deployment sits in early-cycle expansion, with aviation offtake agreements providing the adoption tailwind that de-risks project finance for synthetic fuel investments.
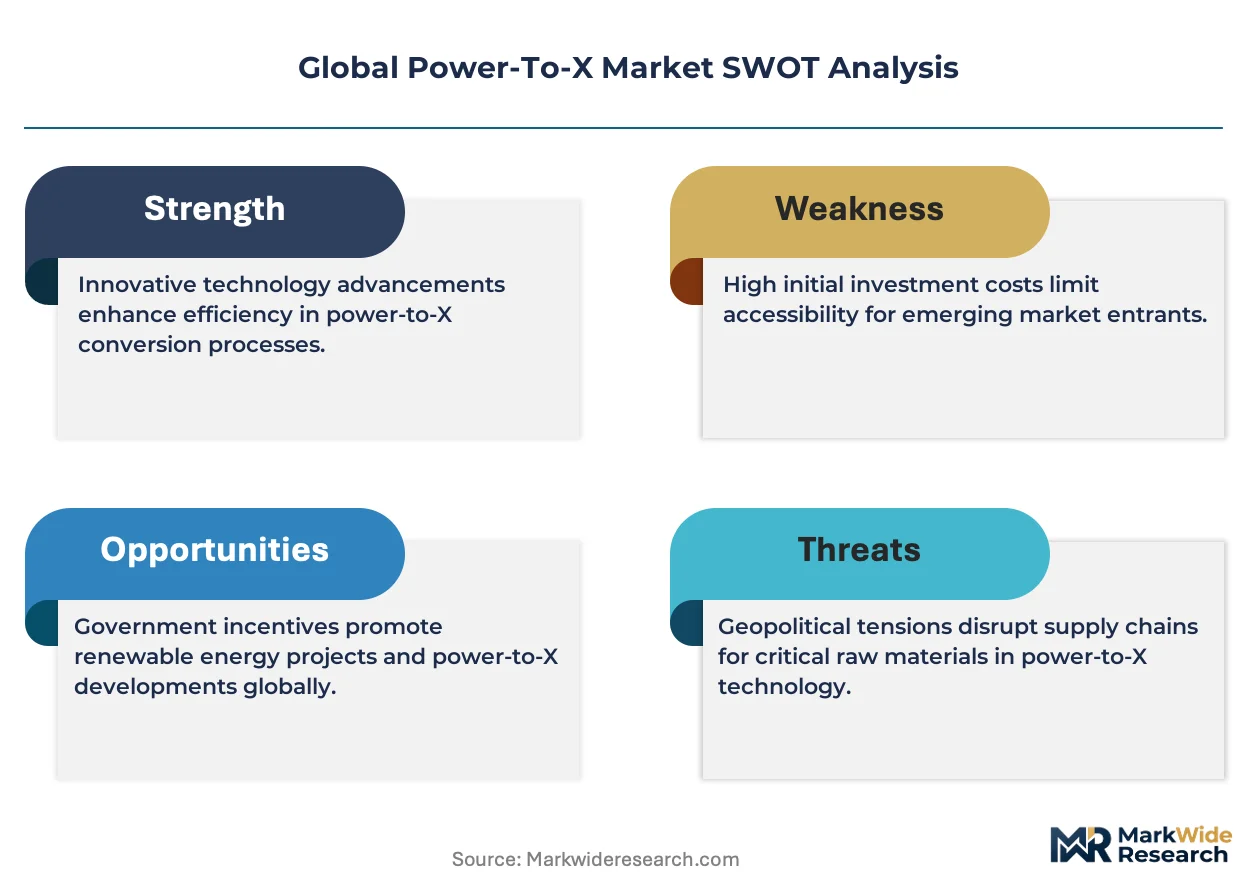
For Market Incumbents: Compound manufacturing scale advantages in alkaline electrolyzer platforms through captive iridium recycling partnerships, insulating margins from South African supply disruption. Deepen backward integration into titanium bipolar plate production to defend against emerging Chinese stack manufacturers. Prioritize certification investment for ISO 19880-1 fueling station components to lock out modular specialists from mobility infrastructure contracts. For New Entrants and Emerging Players: CE marking fast-track for PEM electrolyzer subsystems opens procurement channels with German hydrogen valley developers facing compressed deployment timelines. Target maritime ammonia retrofit projects in South Korean shipyards, the most penetrable segment given nascent e-ammonia supply and engine manufacturer qualification partnerships. Pursue joint venture structures with established offshore wind developers to bypass offtake contracting credibility gaps. For Investors and Strategic Acquirers: Engineering contractors with bundled EPC-electrolyzer capabilities represent the highest-conviction acquisition archetype for exposure to system integration margin pools. Frame long-term viability around 10-year windows where green hydrogen cost parity with gray hydrogen determines asset stranding risk. Monitor aviation offtake contract tenor extension as the inflection signal for synthetic fuels project financeability.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Capacity Buildout | Danish and German hydrogen valleys anchor pipeline injection infrastructure under EU Green Deal mandates. |
| Backward Integration into Catalyst Production | In-house iridium coating capabilities reduce PEM manufacturer exposure to South African supply concentration. |
| Long-term Offtake Contracting | Ten-year purchase agreements with Thyssenkrupp and ArcelorMittal de-risk direct reduction furnace investments. |
| Technology Licensing Partnership | SOEC platform transfers compress green-gray hydrogen cost gaps for Netherlands cement and steel applications. |
| Green Certification Program | KBA fuel quality certification unlocks German mobility infrastructure procurement for compliant station developers. |
Study Parameters
Desk research of electrolyzer manufacturing databases, offshore wind project registries, and EU regulatory filings preceded structured interviews with hydrogen valley project developers, EPC contractors, industrial offtake procurement managers, and electrolyzer OEM sales directors. Secondary validation drew from IEA hydrogen deployment trackers, FERC hydrogen hub funding disclosures, and METI roadmap documentation. Bottom-up installation capacity tallies triangulated against top-down carbon border adjustment demand projections.
Variance decomposition across technology platform, deployment configuration, and end-use application segments structured the analytical framework over the projection horizon. Modeled dimensions span electrolysis versus synthetic fuels application, hybrid versus standalone deployment, and industrial feedstock versus energy storage end-use. CAGRs derived from capacity deployment curves weighted by electrolyzer system pricing and offtake contract terms. Forecast inputs incorporated EU ETS carbon price trajectories and aviation compliance mandate stringency.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and aviation offtake contract standardization; material deviation in carbon border adjustment implementation timelines would warrant model refresh. Specific risks include iridium supply disruption, grid interconnection queuing extensions, and LOHC technology substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Multi Energy Systems Market