
 Salty Puffed Snacks Market | 2026-2036
Salty Puffed Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Salty Puffed Snacks Market Insights
Multi-pack bundling is consolidating buyer choice across the salty puffed snacks category, pushing volume commitments upward while narrowing single-unit availability. PepsiCo leverages its Frito-Lay distribution network to dominate shelf placement in mainstream retail. Kellanova anchors its position through specialized extrusion capabilities that yield consistent product texture. Mondelez International competes via premium flavor extensions that command higher unit economics in specialty channels.
Salty puffed snacks comprise aerated cereal or legume-based products manufactured through high-pressure extrusion or gun-puffing, typically containing 30–50% starch by weight and achieving bulk densities below 0.15 g/cm³ for optimal crunch retention. Corn puffs and cheese puffs sustain the largest revenue pools due to entrenched consumer familiarity and lower ingredient cost structures, while lentil puffs represent the fastest-growing product type as plant-protein positioning attracts health-conscious buyers. Pouch packaging dominates convenience-oriented channels for portion control and resealability, though bag formats sustain higher absolute volumes in club and supermarket environments.
FDA nutrition labeling requirements and the EU Green Deal packaging directives are tightening compositional and material standards, forcing reformulation of sodium profiles and accelerated migration toward recyclable or biodegradable packaging substrates. BIS fortification guidelines in India and FSSAI additive regulations add compliance layers for multinational manufacturers seeking market access. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon-footprint disclosure rules to anticipate reformulation timelines and packaging investment cycles.
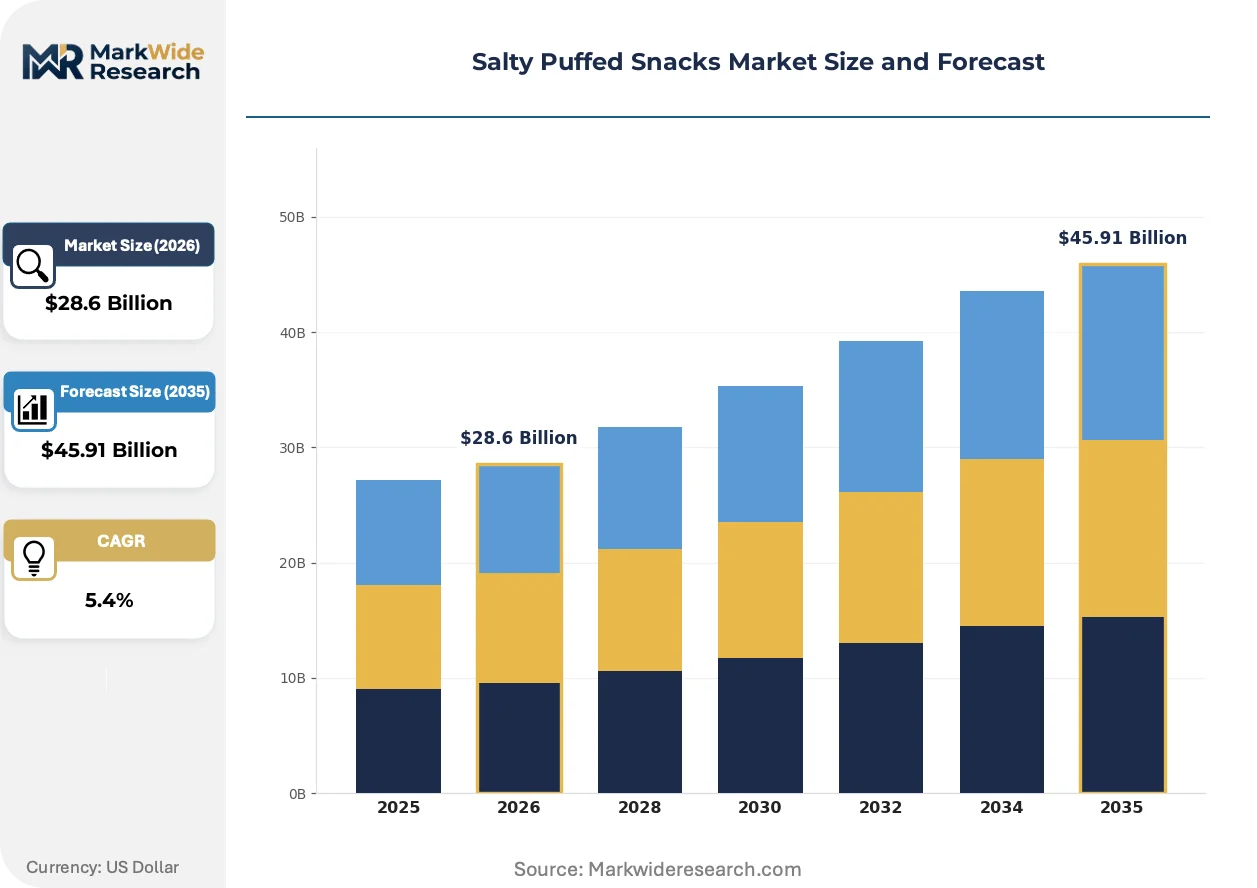
Market Dynamics
The EU Green Deal packaging mandates are compressing formulation timelines and forcing material substitutions across salty puffed snack manufacturing, while multi-pack bundling concentrates buyer commitments toward larger volume formats.
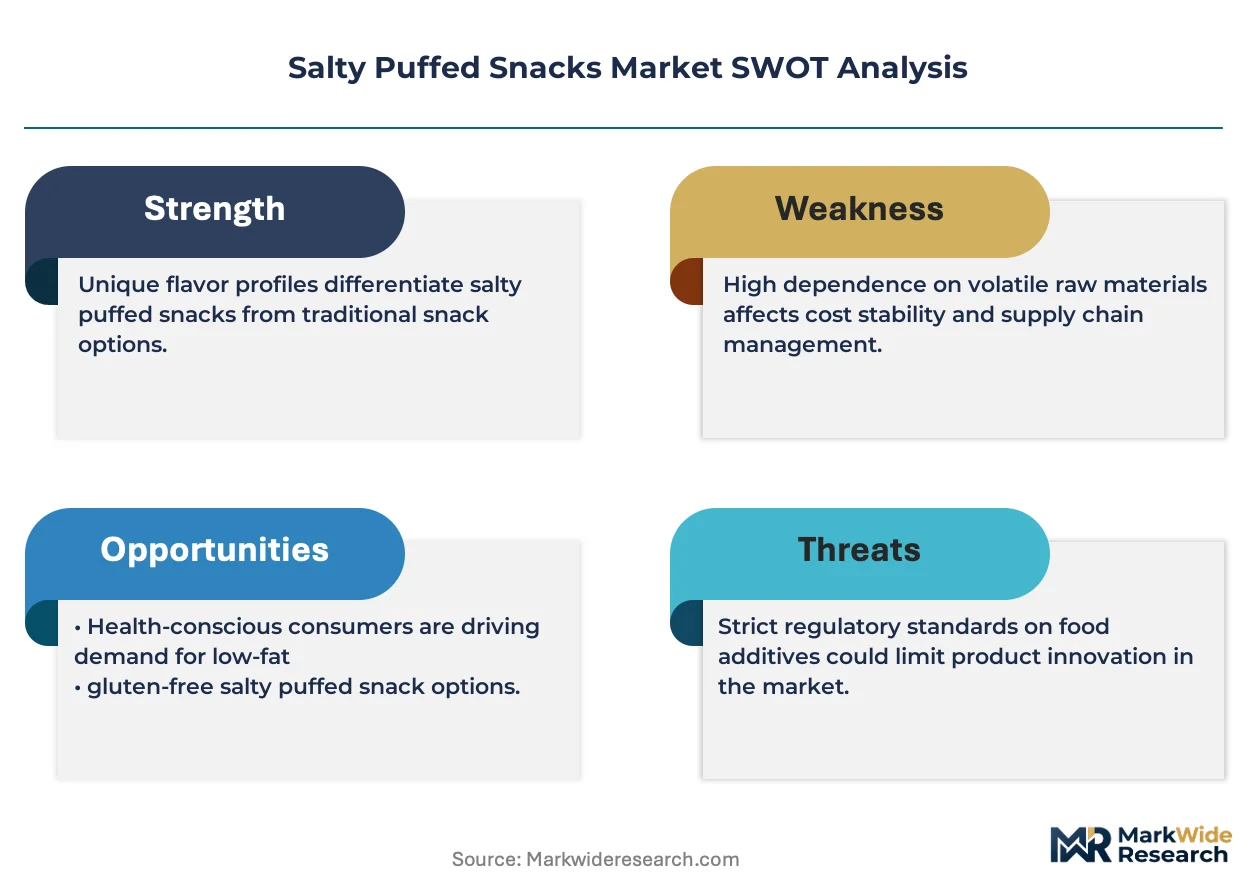
Growth Catalysts
- Convenience channel expansion:Urban retail networks in India and Brazil are extending chilled and ambient snack aisles, elevating impulse purchase frequency for single-serve pouches.
- REACH compliance migration:European manufacturers accelerating biodegradable substrate adoption are unlocking shelf space in German and French supermarket chains with strict sustainability procurement criteria.
- Extrusion technology advancement:Twin-screw high-pressure systems are reducing starch gelatinization temperatures, enabling pulse flour integration without texture degradation.
Market Restraints
- Input cost volatility:Corn and sunflower oil price swings squeeze margin structures for mid-tier producers lacking forward contracting capabilities.
- Supply concentration risk:Specialty modified starch production clusters in the US Midwest and Netherlands create single-source vulnerability for texture-modified formulations.
- Regulatory friction:India's FSSAI additive approval timelines extend 18-24 months, blocking rapid flavor innovation deployment in that market.
Strategic Opportunities
- Underpenetrated geography:Indonesia's modern trade expansion in secondary cities offers first-mover positioning before local brands consolidate distribution.
- Regulatory tailwind:The EU Green Deal's 2030 recyclable packaging targets are creating certified substrate demand that premium-positioned entrants can capture.
- Channel innovation:Direct-to-pantry subscription models in UK and US metro corridors are bypassing slotting fee barriers while building consumption data assets.
Industry Challenges
- Reformulation expertise scarcity:Sodium reduction chemistry and clean-label binding systems require food technologists with rare cross-functional formulation experience.
- Packaging line reconfiguration:Migration from multilayer films to mono-material or compostable substrates demands capital-intensive extrusion and sealing equipment upgrades.
- Front-of-pack compliance divergence:Nutri-Score, traffic light systems, and impending FDA updates force parallel label runs and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salty Puffed Snacks Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Puffs, Rice Puffs, Cheese Puffs, Lentil Puffs Flavor Profile: Cheddar, Barbecue, Sour Cream, Spicy Packaging Type: Bags, Boxes, Tubs, Pouches Sales Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores |
| Companies Covered | PepsiCo, Kellanov, Mondelez International, The Kraft Heinz Company, Utz Brands, Conagra Brands, The Hershey Company, Intersnack Group, Calbee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salty Puffed Snacks Market Trends and Innovations
Pulse flour extrusion and biodegradable packaging substrates are displacing conventional corn-based formulations and multilayer films, while procurement teams tighten sustainability verification requirements across supplier bases.
Air-classified pulse protein concentrates are decentralizing raw material sourcing for extruded snacks, allowing regional millers in Canada and Australia to supply consistent functionality previously concentrated with multinational ingredient houses. Mid-size snack brands in the UK and Netherlands are adopting these concentrates at 15-20% inclusion rates. This ingredient shift is decentralizing supply chain control from dominant grain traders toward specialized pulse processors.
The EU Green Deal's packaging performance standards are mandating minimum recycled content thresholds and end-of-life compostability certifications for food-contact materials. Manufacturers are reformulating sealant layers and migrating from aluminum oxide barriers to bio-based alternatives. German and French retail banners are enforcing these standards through procurement scorecards, accelerating compliant substrate adoption in private-label programs.
Buyer concentration among club and e-commerce channels is compressing supplier negotiation cycles and unbundling traditional brokerage relationships. Large-format retailers in the US and UK are imposing direct vendor-managed inventory requirements and real-time sales data sharing. This consolidation is most visible in North American supermarket and warehouse club procurement, where annual vendor reviews now prioritize carbon disclosure alongside unit economics.
Salty Puffed Snacks Market Segmentation
Extrusion technology and packaging substrate specifications determine margin structures across salty puffed snack categories. Manufacturers align product architecture with channel requirements and regulatory compliance timelines.
Product Type:
Starch source and protein content define processing parameters and nutritional positioning for each product format.
- Corn Puffs:Standard maize starch formulations achieve bulk densities below 0.15 g/cm³ through high-pressure extrusion. Demand concentrates in US convenience channels where established distribution networks favor familiar texture profiles and lower ingredient cost structures.
- Lentil Puffs:Pulse flour extrusion requires twin-screw systems with modified temperature profiles to prevent protein denaturation. Health-conscious buyers in UK and German markets drive adoption, attracted by plant-protein positioning and clean-label ingredient decks.
- Rice Puffs:Lower oil absorption rates suit sodium-reduced formulations targeting Asian export markets.
- Cheese Puffs:Flavor coating systems demand specialized tumbling equipment for uniform powder adhesion.
Corn puffs lead on scale; lentil puffs lead on momentum.
Flavor Profile:
Coating chemistry and seasoning application rates vary by flavor intensity requirements and regional palate preferences.
- Cheddar:Cheese powder formulations with encapsulated fat systems prevent oxidative rancidity during shelf life. US supermarket channels sustain volume concentration, though sodium reduction mandates in California and New York are forcing reformulation cycles.
- Spicy:Capsicum and pepper extract coatings require moisture barriers to prevent caking and flavor degradation. Mexican and Indian markets show steepest expansion trajectory for heat-forward profiles, with FSSAI additive regulations creating compliance complexity for imported formulations.
- Barbecue:Smoke and molasses notes demand complex seasoning matrices with higher hygroscopicity management.
- Sour Cream:Dairy-derived powder systems face shorter shelf life constraints in humid climates.
Cheddar dominates absolute volume; spicy climbs the fastest.
Packaging Type:
Material specifications and seal integrity requirements align with channel velocity and consumption occasion patterns.
- Pouches:Multilayer films with resealable zippers optimize portion control for impulse channels. Convenience stores in Brazil and India are elevating single-serve pouch placement, though EU Green Deal mandates are accelerating migration toward mono-material substrates.
- Bags:Higher gauge films support volume formats in club retail environments. Walmart and Costco procurement scorecards in the US now prioritize recycled content thresholds alongside unit economics.
- Boxes:Paperboard structures suit premium gift assortments and seasonal promotions.
- Tubs:Rigid containers enable bulk dispensing in foodservice and institutional channels.
Bags lead on scale; pouches lead on momentum.
Sales Channel:
Inventory velocity and data transparency requirements reshape supplier relationships across retail formats.
- Supermarkets:Slotting fee structures and planogram compliance dominate vendor negotiations. German and French retail banners enforce sustainability procurement criteria through annual vendor reviews, compressing supplier margins for non-compliant packaging.
- Online Retailers:Direct-to-pantry subscription models in UK and US metro corridors bypass traditional brokerage relationships while building consumption data assets. Amazon and Ocado impose real-time sales data sharing requirements.
- Convenience Stores:Chilled and ambient snack aisle expansion in Indonesian secondary cities offers first-mover positioning.
- Specialty Stores:Premium flavor extensions command higher unit economics through curated assortment strategies.
Supermarkets lead on scale; online retailers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The salty puffed snacks industry traces its modern scale to post-war American corn processing innovations, with extrusion technology spreading through European and Asian markets during the 1970s and 1980s as convenience retail networks expanded.
United States
High per-capita snack consumption and entrenched convenience store distribution sustain volume concentration, particularly for corn and cheese puff formats. FDA nutrition labeling requirements and state-level sodium reduction mandates in California and New York force reformulation cycles. The Midwest corn belt anchors ingredient sourcing, with modified starch production clusters in Iowa and Illinois creating supply concentration for texture-modified formulations.
Germany
Health-conscious buyers in German metropolitan markets drive lentil puff adoption through plant-protein positioning. REACH compliance and EU Green Deal packaging mandates accelerate biodegradable substrate migration, with retail banners enforcing sustainability procurement criteria through annual vendor scorecards. The Rhine-Ruhr industrial corridor hosts specialized extrusion equipment manufacturers serving reformulation demands.
United Kingdom
Direct-to-pantry subscription models in London and Manchester metro corridors bypass traditional slotting fee barriers while building consumption data assets. Nutri-Score front-of-pack labeling requirements create compliance complexity alongside EU packaging directives. Midlands-based pulse processors supply air-classified protein concentrates enabling regional millers to compete with multinational ingredient houses.
India
Urban retail network expansion in Mumbai, Delhi-NCR, and Bangalore elevates impulse purchase frequency for single-serve pouches in chilled and ambient snack aisles. FSSAI additive approval timelines extending 18-24 months block rapid flavor innovation deployment, while BIS fortification guidelines add compliance layers. Maharashtra and Gujarat host emerging extrusion capacity serving domestic brands and multinational market access strategies.
Indonesia
Modern trade expansion in Jakarta, Surabaya, and secondary cities offers first-mover positioning before local brands consolidate distribution. The country's national food safety regulator maintains evolving standards for snack additives and labeling. Java-based manufacturing clusters are attracting regional investment as convenience channel penetration deepens across the archipelago.
Salty Puffed Snacks Market Competitive Landscape
The competitive structure tilts toward diversified multinational food conglomerates with captive distribution networks. Consolidation pressure concentrates shelf placement leverage among three to four holding companies controlling mainstream retail planograms. Strategic archetypes include scale-driven extrusion specialists, premium flavor extension platforms, and private-label manufacturing contractors. Dominant competitive moves encompass vertical integration into pulse flour sourcing and accelerated packaging line reconfiguration for compliant substrates.
Within the diversified-snack conglomerate tier, PepsiCo and Kellanova occupy positions defined by distribution network scale and specialized processing capabilities respectively. Mondelez International exemplifies the premium-flavor-extension archetype through higher unit economics positioning in specialty channels. These three entities anchor the competitive landscape by representing distinct strategic vectors: network dominance, manufacturing specialization, and premium segmentation.
| Leading Market Players |
|---|
| PepsiCo |
| Kellanov |
| Mondelez International |
| The Kraft Heinz Company |
| Utz Brands |
| Conagra Brands |
| The Hershey Company |
| Intersnack Group |
| Calbee |
| Others |
Pricing and Supply Chain Analysis
Club and e-commerce channel buyers concentrate procurement leverage among fewer retail banners, compressing supplier margins through direct vendor-managed inventory requirements and real-time data sharing mandates. This buyer consolidation forces manufacturers to absorb cost volatility while maintaining shelf placement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates lentil-based formulations from conventional corn puffs from private-label alternatives. Price differentiation hinges on protein content certification and sustainable packaging credentials. Cost compression in the economy tier is intensifying because corn and sunflower oil price swings squeeze mid-tier producers lacking forward contracting. Convenience channel buyers exhibit highest price sensitivity; specialty store purchasers tolerate premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with specialty modified starch production clusters in Iowa and Illinois, creating concentration risk for texture-modified formulations. Raw material sourcing draws from the US Midwest corn belt, Canadian pulse processors, and Australian air-classified protein concentrate suppliers. Tariff exposure on imported pulse flours threatens margin structures for European manufacturers. Distribution runs through Frito-Lay captive networks, direct-to-pantry subscription platforms, and third-party logistics providers serving club retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The salty puffed snacks market represents a late-cycle quality story as health-conscious buyers migrate toward plant-protein positioning and clean-label ingredient decks, compressing margins for legacy corn-based formulations.
For Market Incumbents: Extend extrusion technology leadership by retrofitting twin-screw systems for pulse flour integration before specialty processors capture lentil puff share. Lock in multi-year supply agreements with Midwest modified starch producers to defend against input cost volatility. Accelerate mono-material packaging line reconfiguration to meet EU Green Deal procurement scorecards at German and French retail banners.
For New Entrants and Emerging Players: Air-classified pulse protein concentrates offer a technology-first wedge into the ingredient supply tier, enabling regional millers to bypass multinational grain traders. Target Indonesia's secondary cities before local brands consolidate modern trade distribution. Pursue direct-to-pantry subscription models in UK and US metro corridors to bypass slotting fee barriers and build proprietary consumption data assets.
For Investors and Strategic Acquirers: Diversified snack conglomerates with captive distribution networks are the most active acquirer in this space, seeking extrusion specialists and pulse flour processors. The long-term viability window favors vertically integrated manufacturers controlling upstream ingredient sourcing and downstream shelf placement. Watch FSSAI additive approval timelines in India as an inflection indicator for flavor innovation deployment and multinational market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Pulse Flour Integration | Twin-screw extrusion retrofitting enables lentil puff production without texture degradation for health-conscious buyers. |
| Mono-Material Packaging Migration | EU Green Deal compliance unlocks shelf space in German and French retail banners with strict sustainability procurement criteria. |
| Direct-to-Pantry Subscription Launch | UK and US metro corridor models bypass traditional brokerage relationships while building proprietary consumption data assets. |
| Indonesia Secondary City Expansion | Modern trade penetration in Surabaya and emerging urban centers offers first-mover positioning before local brand consolidation. |
| Backward Integration into Modified Starch | Captive supply of texture-modified formulations insulates against Iowa and Illinois production cluster concentration risk. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, India, and Indonesia, with primary inputs from each market informing cross-regional pattern identification. The analysis combines structured interviews with extrusion equipment manufacturers, category buyers at club retailers, pulse flour processors, and food technology consultants with secondary validation from FDA filings, FSSAI regulatory updates, EU Green Deal directive documentation, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation ensure consistency across estimation approaches.
Rate-of-change decomposition isolates volume drivers from price effects across the projection horizon. Segmentation dimensions include starch source, packaging substrate specification, flavor profile intensity, and channel velocity tier. CAGRs were derived from fitted trend extrapolation calibrated to historical growth patterns and regulatory compliance timeline impacts. Industry-specific forecast inputs incorporate EU packaging mandate phase-in schedules and FSSAI additive approval pipeline status.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to corn and sunflower oil commodity cycles, REACH compliance migration pace, and front-of-pack labeling mandate divergence. Forecasts reflect documented assumptions about extrusion technology adoption curves and sustainable packaging substrate cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Oat-Based Snacks Market
Snacks
Europe Snacks Food Market
Snacks
United States Children's Snack Bar Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Gluten Free Snacks Market
Snacks
South America Cereal Bar Market
Snacks
Australia Snack Bar Market
Snacks
Corn Chips Market
Snacks
Granola Bars Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Cheese Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
Protein Crisps Market
Snacks
Seaweed Snacks Market
Snacks
Baked Chips Market
Snacks
North America Snack Food Market