
 Europe Cereal Bar Market | 2026-2036
Europe Cereal Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cereal Bar Market Foresight
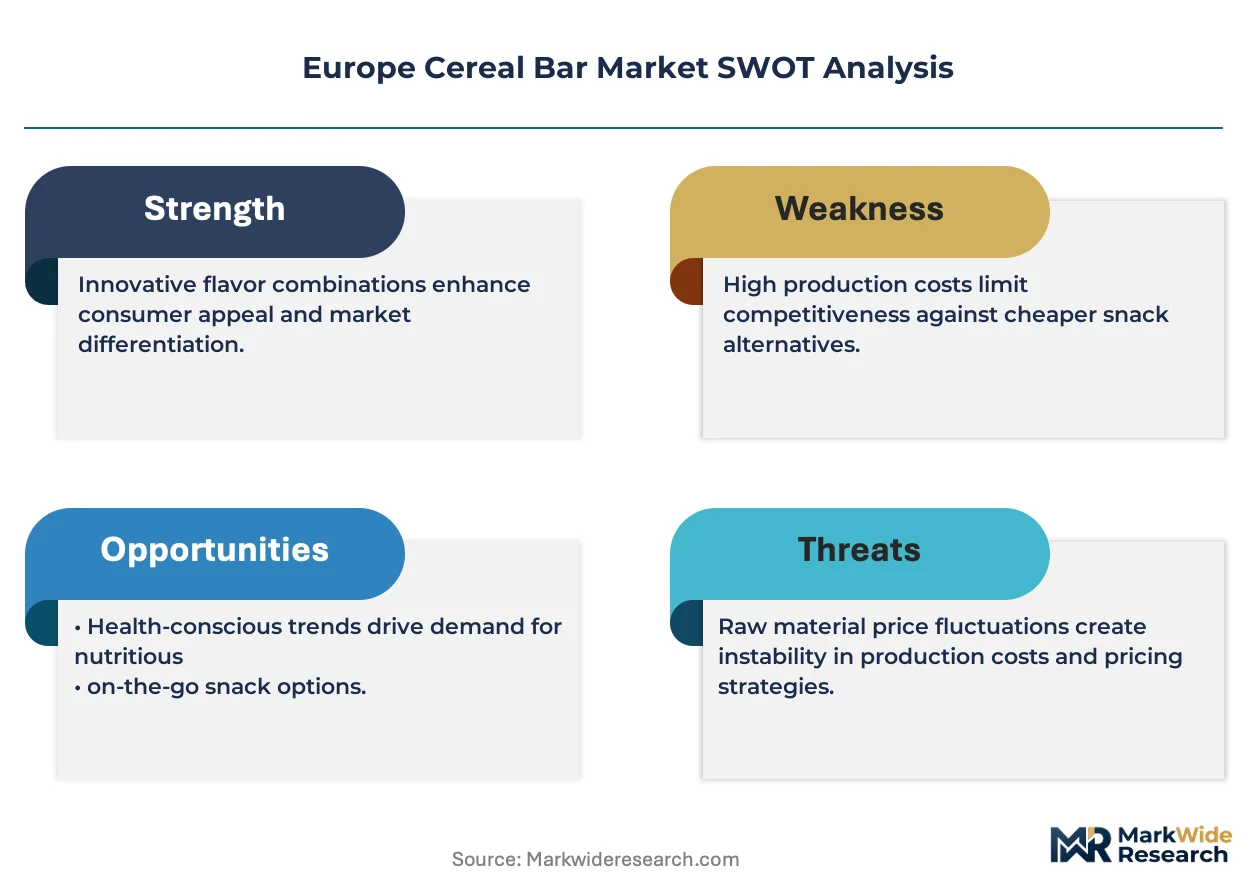
Germany is tilting toward expanded cereal bar production capacity as health-snack demand climbs across Central Europe. Mondelēz International leverages its pan-European distribution network to sustain shelf dominance in conventional retail channels. Nestlé S.A. anchors its position through specialized nutrition science applied to protein-enriched formulations. Eat Natural differentiates via clean-label recipes that navigate strict EU ingredient disclosure requirements.
A cereal bar is a compressed, shelf-stable food product typically comprising rolled grains, binding syrups, and inclusions such as nuts, dried fruit, or chocolate, formed through extrusion or cold-pressing and baked or enrobed to achieve moisture content below 10 percent for ambient stability. Granola bars occupy the mature volume core of the European market, while protein-enriched formats capture the fastest expansion as athletic and busy professional segments seek macronutrient density in portable formats. Nut-based bars concentrate margin pools through premium positioning in health food stores, whereas gluten-free variants extend addressable reach among diagnosed celiac and lifestyle-avoidance populations.
EFSA governs health claim substantiation on cereal bar packaging, while the EU Green Deal and REACH framework shape ingredient sourcing and packaging material compliance obligations across member states. The F-Gas Regulation indirectly affects cold-chain logistics for temperature-sensitive inclusions such as chocolate coatings. Stakeholders must monitor evolving ECHA guidance on novel sweeteners and anticipate how CSRD reporting requirements will cascade through supplier tiers.
Market Dynamics
The EU Green Deal is compressing reformulation timelines across European cereal bar manufacturing as binding sustainability disclosure obligations cascade through supplier tiers. REACH framework amendments on novel sweetener classifications are forcing simultaneous R&D and compliance investments.
Growth Catalysts
- Protein fortification science:Advances in extruded protein texturization enable sensory parity with conventional binders. Athletic and professional segments in Germany and France are accelerating uptake of macronutrient-dense formats.
- CSRD reporting mandates:Corporate Sustainability Reporting Directive requirements are compelling large food manufacturers to source certified sustainable ingredients. This creates preferential procurement channels for compliant cereal bar suppliers.
- United Kingdom grab-and-go breakfast concentration:Urban commuter patterns in London and Manchester are concentrating demand for shelf-stable, portion-controlled morning consumption. Retailers are expanding chilled and ambient cereal bar facings in transport hubs.
Market Restraints
- Oat and nut input cost volatility:Climate-driven yield variability in Nordic and Black Sea growing regions is compressing margin predictability for granola and nut-based bar categories.
- ECHA novel sweetener assessment timelines:Pending guidance on stevia glycoside and allulose classifications is freezing formulation decisions and delaying NPD pipelines.
- Chocolate coating cold-chain dependency:F-Gas Regulation phase-down is raising refrigeration costs for temperature-sensitive enrobing operations across Southern European production facilities.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Central European labor cost advantages and EU structural fund access are attracting greenfield production investment for export-oriented capacity.
- Clean-label certification convergence:Dual organic and carbon-neutral accreditation is opening premium shelf positioning in Dutch and Scandinavian health food channels.
- Direct-to-subscription channel innovation:Personalized nutrition platforms in Germany are creating recurring revenue models bypassing conventional retail slotting fee structures.
Industry Challenges
- Reformulation talent scarcity:Food technologists with simultaneous expertise in protein chemistry and EU regulatory navigation command premium compensation. Manufacturers face recruitment bottlenecks for hybrid R&D-compliance roles.
- Packaging material requalification timelines:Transitioning from multilayer flexible films to mono-material or paper-based structures requires 18-24 month stability testing. EFSA migration testing protocols are extending go-to-market schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cereal Bar Market |
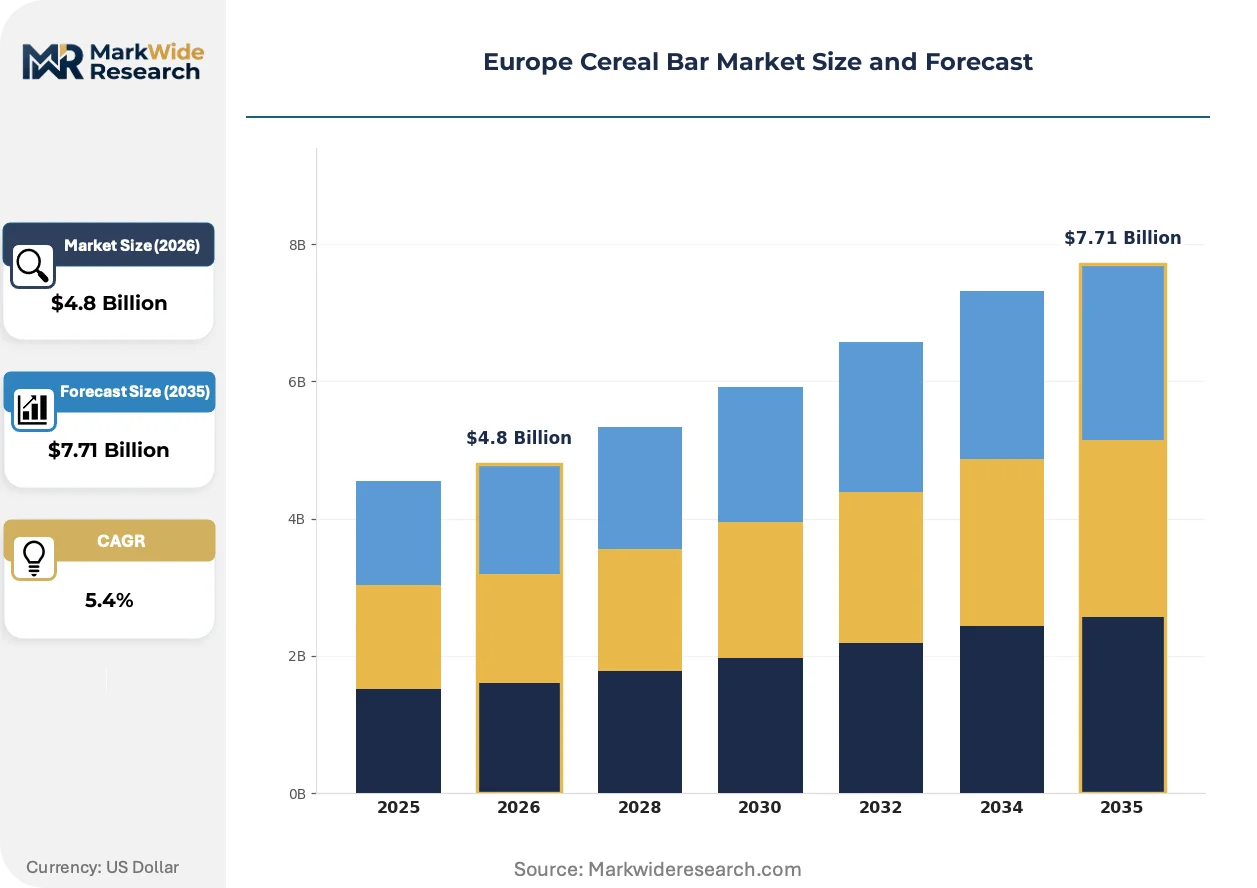
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based Bars, Chocolate Bars, Fruit Bars, Granola Bars Form: Snack Size, Meal Replacement, Protein-Enriched, Gluten-Free Customer Type: Health-Conscious Consumers, Athletes, Children, Busy Professionals Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Mondelēz International, Inc., Eat Natural, General Mills, Inc., The Kellogg Company, Weetabix Food Company, Nestlé S.A., Hero Group, Fazer Group, Mars, Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cereal Bar Market Shifts & Advancements
Cold-pressing and minimal-processing technologies are displacing conventional extrusion-bake methods across European premium cereal bar segments. Simultaneous advances in binding systems and shelf-life extension are compressing the trade-off between clean-label positioning and ambient stability.
High-pressure processing of nut and seed inclusions is rendering obsolete traditional roasting and oil-coating preservation methods. German and Swiss manufacturers are adopting HPP-treated ingredients at pilot scale. The technology is enabling 90-day ambient shelf life without synthetic antioxidants, collapsing the clean-label shelf-stability compromise that previously constrained formulation freedom.
EFSA health claim substantiation requirements are tightening evidentiary standards for protein and fiber declarations on cereal bar packaging. The 2023 guidance update demands human intervention studies rather than compositional analysis alone. Protein-enriched and digestive health segments are responding by commissioning clinical trials and reformulating to documented bioactive thresholds.
Urban professional consumption is fragmenting across occasion-specific formats rather than consolidating on multi-purpose bars. French and British buyers are separating breakfast, pre-workout, and afternoon snack occasions with distinct texture and macronutrient specifications. This occasion unbundling is forcing SKU proliferation and compressing production run lengths in contract manufacturing relationships.
Europe Cereal Bar Market Segmentation
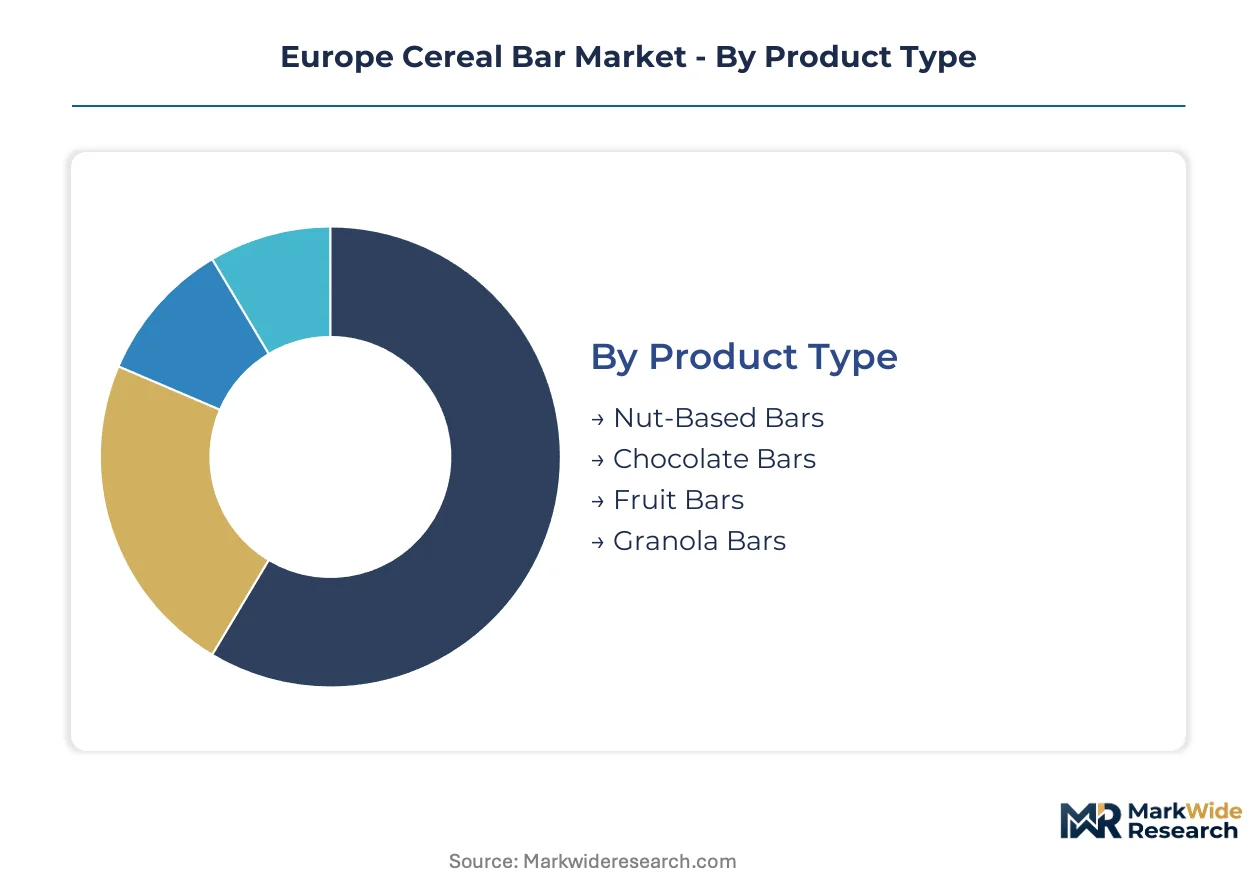
European cereal bar manufacturers engineer product portfolios around distinct consumption occasions and channel economics. Each segmentation dimension carries specific margin profiles and reformulation requirements under EFSA and REACH frameworks.
Product Type:
After-sales service intensity varies sharply across product types, with nut-based and chocolate-coated formats demanding more intensive quality assurance and cold-chain support than ambient-stable alternatives.
- Granola Bars:Rolled oat and grain clusters bound with honey or syrup, baked to sub-10% moisture for ambient shelf stability. German and British breakfast occasions concentrate volume demand, though oat input cost volatility from Nordic growing regions compresses margin predictability.
- Nut-Based Bars:Dense formulations of almonds, hazelnuts, or peanuts with minimal grain content, positioned at premium price tiers in health food channels. Dutch and Scandinavian consumers are accelerating purchases of organic-certified variants, creating dual-label accreditation requirements.
- Chocolate Bars:Grain or nut bases enrobed in cocoa-based coatings, requiring temperature-controlled logistics under tightening F-Gas Regulation phase-down schedules.
- Fruit Bars:Compressed dried fruit matrices with binding agents, targeting clean-label positioning through minimal ingredient declarations.
By volume, granola bars lead. By growth pace, nut-based formats are expanding most quickly.
Form:
Cost tier stratification drives form segmentation, with meal replacement and protein-enriched formats commanding manufacturing complexity premiums over snack-sized alternatives.
- Protein-Enriched:Extruded protein texturization achieves sensory parity with conventional binders, enabling 20-30g protein declarations. Athletic segments in France and Germany are accelerating uptake, though EFSA health claim substantiation now demands human intervention studies rather than compositional analysis alone.
- Meal Replacement:Calorie-dense formulations with complete macronutrient profiles, targeting portion-controlled consumption in urban commuter patterns. London and Manchester transport hubs are expanding chilled and ambient facings for this form.
- Snack Size:Sub-150 calorie portions for afternoon consumption occasions, dominating supermarket multipack configurations.
- Gluten-Free:Oat-substitute or grain-free bases using buckwheat or rice, extending addressable reach among diagnosed celiac and lifestyle-avoidance populations.
Snack size formats dominate unit volume. Protein-enriched bars are gaining share fastest among active consumer segments.
Customer Type:
Application-specific consumption patterns fragment the customer base, with each segment demanding distinct texture specifications and macronutrient profiles.
- Busy Professionals:Urban commuters in the United Kingdom separating breakfast, pre-workout, and afternoon snack occasions with distinct format requirements. This occasion unbundling is forcing SKU proliferation and compressing production run lengths in contract manufacturing relationships.
- Health-Conscious Consumers:Clean-label seekers navigating strict EU ingredient disclosure requirements, concentrated in Dutch and Scandinavian premium channels.
- Athletes:Performance-oriented buyers prioritizing protein density and documented bioactive thresholds, responding to tightened EFSA evidentiary standards.
- Children:Portion-controlled formats with reduced sugar profiles, subject to strict school nutrition policies across EU member states.
Health-conscious consumers represent the largest addressable base. Busy professionals show the steepest expansion trajectory as urbanization intensifies.
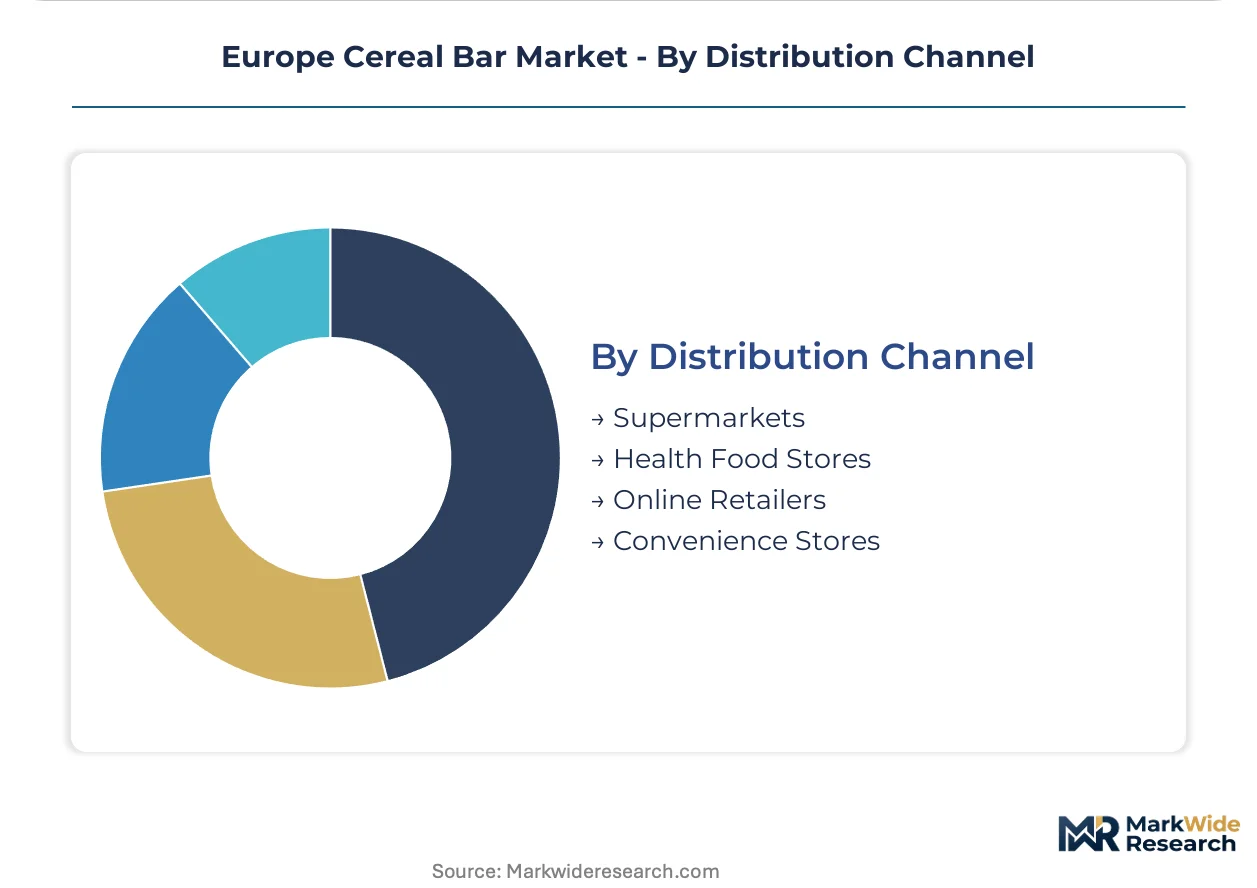
Distribution Channel:
Supply concentration determines channel economics, with supermarket and online retail commanding divergent logistics and slotting fee structures.
- Supermarkets:Conventional retail shelf dominance sustained through pan-European distribution networks, though slotting fees pressure emerging brand margins.
- Online Retailers:Direct-to-subscription platforms in Germany are creating recurring revenue models bypassing conventional retail structures, enabling personalized nutrition configurations.
- Health Food Stores:Premium positioning channels for organic and carbon-neutral accredited products, concentrated in Dutch and Scandinavian markets.
- Convenience Stores:Grab-and-go impulse placement in transport hubs and urban centers, expanding ambient cereal bar facings in London and Manchester.
Supermarkets retain volume leadership. Online retailers are climbing the fastest as subscription models penetrate German metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters across Germany, the United Kingdom, France, Poland, and the Netherlands, with each market exhibiting distinct demand drivers and regulatory exposure. REACH compliance costs and CSRD disclosure mandates are reshaping investment patterns across these production hubs.
Germany
Protein-enriched cereal bar demand from athletic and busy professional segments is accelerating factory utilization rates in Bavaria and North Rhine-Westphalia. EFSA health claim substantiation requirements are tightening evidentiary standards for packaging declarations. Mondelēz International leverages its pan-European distribution network from manufacturing sites near Hamburg to sustain shelf dominance in conventional retail channels.
United Kingdom
Urban commuter patterns in London and Manchester are concentrating grab-and-go breakfast demand for shelf-stable, portion-controlled formats. The F-Gas Regulation phase-down is raising refrigeration costs for chocolate-coated variants in Southern English production facilities. Weetabix Food Company anchors its position through specialized nutrition science applied to protein-enriched formulations targeting metropolitan professionals.
France
Health-conscious consumers in Paris and Lyon are accelerating purchases of clean-label and organic-certified variants. EU Green Deal sustainability disclosure obligations are pressing manufacturers toward certified sustainable ingredient sourcing. Occasion-specific consumption is fragmenting across breakfast, pre-workout, and afternoon snack formats with distinct texture requirements.
Poland
Central European labor cost advantages and EU structural fund access are attracting greenfield production investment for export-oriented capacity. ECHA novel sweetener assessment timelines are freezing formulation decisions for manufacturers awaiting stevia glycoside classifications. Warsaw and Łódź industrial zones are emerging as contract manufacturing hubs for Western European brand owners.
Netherlands
Dutch and Scandinavian health food channels are accelerating demand for dual organic and carbon-neutral accredited products. REACH framework amendments on packaging material compliance are extending go-to-market schedules for mono-material transitions. Rotterdam logistics clusters are enabling efficient distribution of ambient-stable formats across Northern European markets.
Europe Cereal Bar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and binding technology. The European cereal bar market exhibits consolidated shelf presence alongside fragmented innovation layers. Three archetypes dominate: multinational CPG conglomerates with pan-European distribution, regional specialists in clean-label positioning, and private-label contract manufacturers serving retail banners. Competitive moves concentrate on M&A for brand portfolio expansion and backward integration into sustainable ingredient sourcing.
Among multinational CPG conglomerates, Mondelēz International, Inc., Nestlé S.A., and General Mills, Inc. occupy positions representing scale-driven platform integration. These entities exemplify archetypes combining nutrition science capabilities with compliance infrastructure for EFSA health claim navigation. Regional specialists such as Eat Natural represent the clean-label differentiation archetype, while contract manufacturers across Poland and the Czech Republic anchor the private-label supply tier.
| Leading Market Players |
|---|
| Mondelēz International, Inc. |
| Eat Natural |
| General Mills, Inc. |
| The Kellogg Company |
| Weetabix Food Company |
| Nestlé S.A. |
| Hero Group |
| Fazer Group |
| Mars, Incorporated |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors transmit cost volatility from Black Sea and Nordic oat harvests directly into margin compression for granola-format manufacturers, while downstream price differentiation separates clean-label premium tiers from conventional multipack economy positioning across German and British retail channels.
Pricing Analysis
EFSA health claim substantiation requirements dictate the pricing tier structure across protein-enriched and fiber-declared formats. Three-tier pricing structure across premium, standard, and economy levels separates clinical-trial-backed functional claims from compositional-only declarations and private-label alternatives. Pricing pressure stems from oat and nut input cost volatility in Nordic growing regions. Health-conscious consumers in Dutch and Scandinavian channels show lowest price sensitivity, while British supermarket multipack buyers concentrate volume demand at economy tiers.
Supply Chain Analysis
Oat groats and rolled grains feed from Nordic and Black Sea agricultural regions, while almond and hazelnut inclusions draw from Mediterranean and California orchards. High-pressure processing equipment and extruded protein texturization systems hinge on German and Swiss engineering supply chains. Single-source vulnerability concentrates in stevia glycoside sweetener supply pending ECHA classification timelines. Distribution runs through pan-European retail networks anchored by Hamburg and Rotterdam logistics clusters, with direct-to-subscription platforms bypassing conventional slotting fee structures in German metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Cereal Bar Market operates as a defensive-moat arena where EFSA regulatory entrenchment and CSRD compliance infrastructure create switching costs that protect incumbent positions against agile challengers.
For Market Incumbents: Entrench shelf dominance through backward integration into certified sustainable oat and nut sourcing that satisfies CSRD disclosure mandates before supplier-tier compliance cascades tighten. Lock in contract manufacturing capacity across Poland and Czech Republic industrial zones to preempt emerging brand production reservations. Defend against clean-label specialists by accelerating mono-material packaging transitions despite 18-24 month EFSA migration testing timelines.
For New Entrants and Emerging Players: Pursue white-space opportunity in personalized nutrition subscription platforms across German metropolitan markets, where recurring revenue models bypass conventional retail slotting fees. Target dual organic and carbon-neutral accreditation gaps in Dutch and Scandinavian health food channels. Establish go-to-market presence through direct-to-consumer configuration tools that fragment busy professional consumption across occasion-specific formats.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with installed high-pressure processing capability and established EFSA health claim navigation expertise. Long-term viability rests on consolidation of Central European production capacity serving Western European brand owners. Acquisition targets should demonstrate hybrid R&D-compliance talent pools. Watch ECHA novel sweetener classification announcements as inflection indicators for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Ingredient Sourcing | CSRD disclosure mandates create preferential procurement channels for compliant suppliers. |
| High-Pressure Processing Technology Adoption | German and Swiss pilot-scale implementations enable 90-day ambient shelf life without synthetic antioxidants. |
| Mono-Material Packaging Transition | EFSA migration testing protocols extend go-to-market schedules but unlock premium shelf positioning. |
| Direct-to-Subscription Channel Launch | Bypasses conventional retail slotting fee structures in German metropolitan markets. |
| Dual Organic and Carbon-Neutral Certification | Opens premium positioning in Dutch and Scandinavian health food channels. |
Research Methodology
A standing panel of brand managers, category buyers at major retailers, supply planners, and contract manufacturing operations directors provided ongoing calibration against secondary validation from EFSA guidance documents, EU Green Deal implementation reports, REACH framework amendments, and customs trade data. Primary fieldwork combined structured interviews with plant managers at Central European production facilities and channel sales heads across German, British, and Dutch distribution networks. Bottom-up volume builds from SKU-level retail audit data triangulated against top-down macro consumption trend analysis.
Scenario-bracketing around oat and nut commodity price volatility, ECHA regulatory timeline uncertainty, and CSRD compliance cost pass-through shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, consumption occasion, distribution channel, and certification tier. CAGRs derived from trend extrapolation anchored to documented production capacity expansions and retail facing growth. Forecast inputs incorporated EFSA health claim substantiation requirements and F-Gas Regulation phase-down schedules as structural constraints.
Macroeconomic conditions sit as an overlay; deviation in eurozone consumer confidence indices, Black Sea agricultural yields, and energy cost trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline adherence and supply chain cost pass-through elasticity. Cross-checking against Nielsen retail audit data and EU customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Snacks Market
Snacks
Snack Bar Market
Snacks
Snacks Market
Snacks
Crispy Fruit Chips Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Fiber Bars Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Crackers Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Jerky Snacks Market
Snacks
Low Fat Granola Market
Snacks
No Fat Snacks Market
Snacks
South Korea Snack Bar Market
Snacks
Savory Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
Europe Frozen Snacks Market