
 Europe Hazelnut Market | 2026-2036
Europe Hazelnut Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hazelnut Market Foresight
Food service distributors and artisanal chocolate makers are reorganizing procurement priorities toward single-origin and organic-certified hazelnut streams. Ferrero Group sustains unmatched backward integration into Turkish orchards through long-term grower contracts. Besana Group competes on calibrated roasting profiles tailored to industrial bakery specifications across Northern Europe. Balsu Gida anchors its position through integrated shelling and blanching capacity near Turkey's primary growing zones.
Europe hazelnut denotes the kernel of Corylus avellana, typically harvested at moisture content below 8 percent and sorted by caliber into 11-13 mm and 13-15 mm grades for confectionery and bakery applications. Whole hazelnuts dominate volume flows into chocolate manufacturing, while hazelnut butter captures expanding margin pools in premium spreads and plant-based dairy alternatives. The confectionery end-user segment leads absolute offtake, though food service channels are gaining share as chefs deploy hazelnut oil and roasted formats in menu innovation.
EU Deforestation Regulation traceability mandates and EFSA mycotoxin thresholds shape import gatekeeping and lot-testing protocols for processors. REACH compliance on food-contact packaging and emerging CSRD disclosure requirements on agricultural supply chains add compliance layers for traders and manufacturers. Stakeholders must monitor how geolocation verification systems and carbon footprint accounting reshape supplier qualification criteria across the value chain.
Market Dynamics
The EU Deforestation Regulation is forcing a wholesale reconfiguration of hazelnut procurement protocols, compelling traders to deploy geolocation verification systems and satellite-based traceability infrastructure for every container entering European ports.
Growth Catalysts
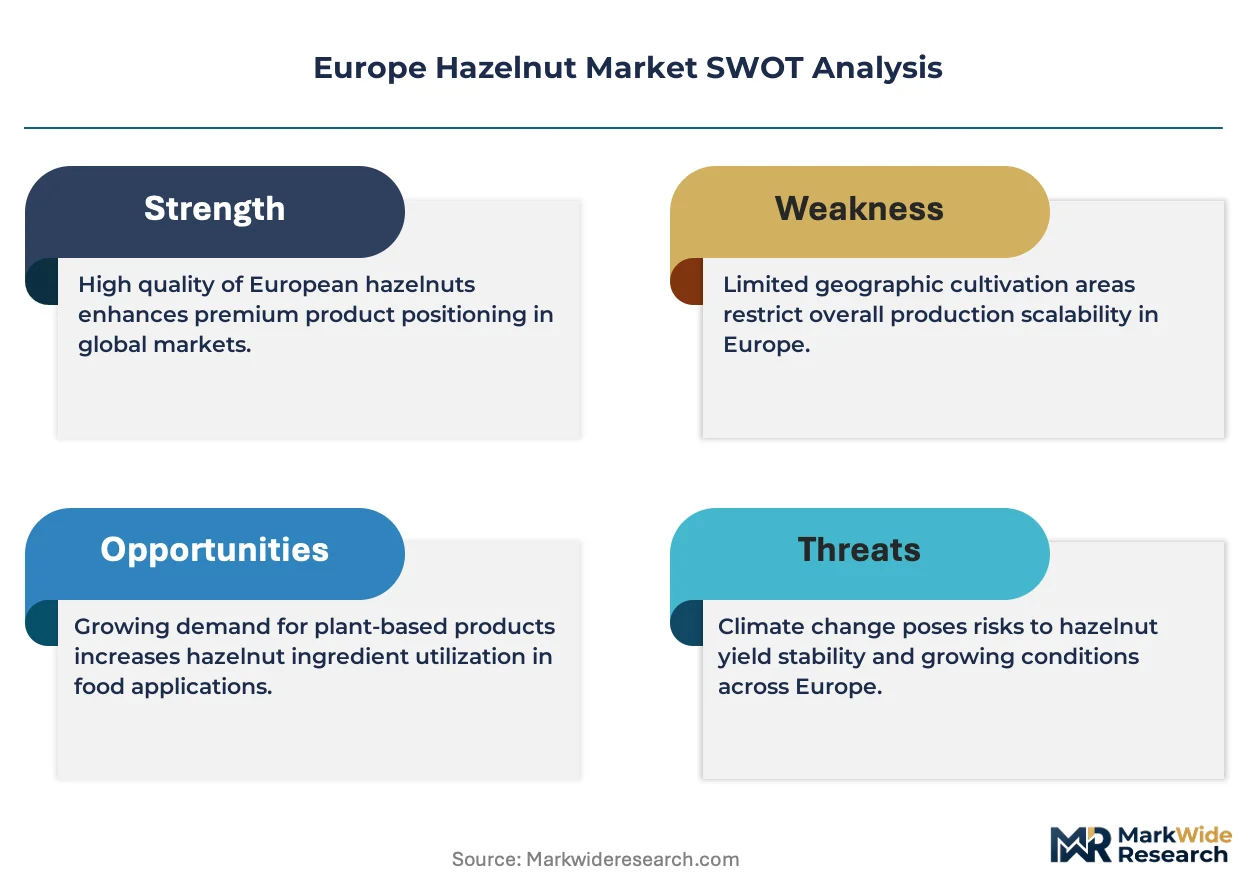
- Confectionery formulation demand:Chocolate manufacturers in Italy and Germany are expanding hazelnut inclusion rates in premium product lines, driving kernel offtake for praline and gianduja applications.
- REACH compliance infrastructure:Investment in food-contact packaging certification is unlocking access to EU retail channels for Turkish and Georgian processors upgrading their shelling and blanching lines.
- Ordu-Giresun cluster concentration:Turkey's Black Sea processing hub is capturing re-export flows through integrated port and cold-storage capacity serving Northern European distributors.
Market Restraints
- Input cost volatility:Energy-intensive roasting and blanching operations face margin compression from natural gas price swings affecting Turkey's industrial zones.
- Supply concentration risk:Overreliance on Turkish-origin kernels exposes buyers to currency fluctuation and geopolitical friction at the Bosporus chokepoint.
- EFSA mycotoxin thresholds:Strict aflatoxin and ochratoxin limits for ready-to-eat hazelnut products create lot-rejection risk and testing cost burdens for small-volume importers.
Strategic Opportunities
- Georgian origin expansion:Underdeveloped orchards in Georgia's Samegrelo and Guria regions offer untapped organic-certified supply for specialty chocolate makers seeking single-origin provenance.
- Plant-based dairy convergence:Hazelnut butter and milk formulations are displacing almond and oat in European barista applications, opening formulation partnerships with coffee chain R&D teams.
- CSRD supply chain disclosure:Mandatory carbon footprint reporting is creating first-mover advantage for processors with farm-level emissions accounting already operational.
Industry Challenges
- Geolocation verification talent scarcity:Traders struggle to recruit technicians capable of operating satellite imagery validation platforms and blockchain-based chain-of-custody systems.
- Deforestation-free certification timelines:The 18-month compliance runway for EUDR full enforcement is compressing supplier qualification cycles and straining audit capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hazelnut Market |
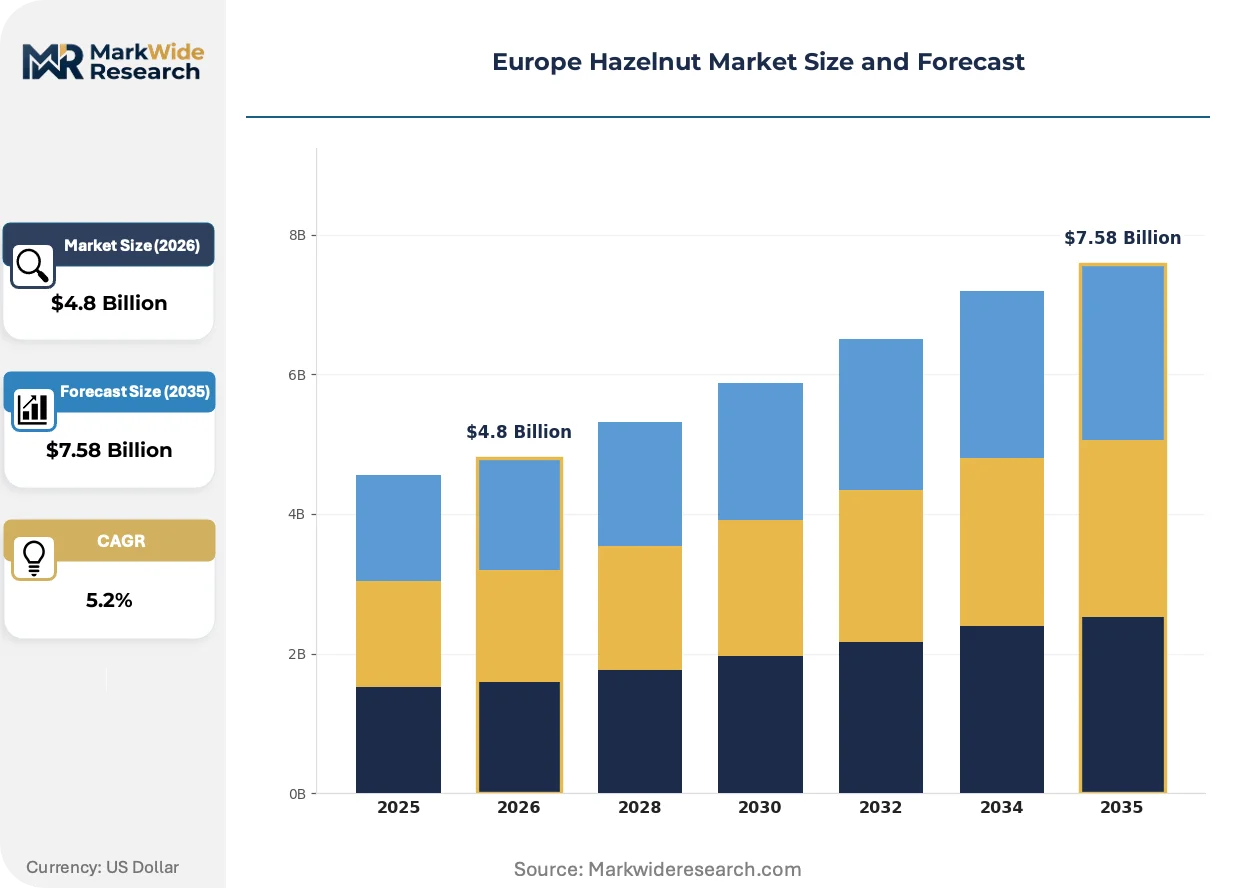
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Hazelnuts, Hazelnut Butter, Hazelnut Oil, Roasted Hazelnuts End User: Confectionery, Bakery, Snacks, Food Service Sales Channel: Retail, Wholesale, Online, Direct Sales Packaging Type: Bags, Bottles, Bulk Packaging, Cans |
| Companies Covered | Balsu Gida, Besana Group, Ferrero Group, Gürsoy Tarımsal Ürünler, DURAK FINDIK, Olam International, Chelmer Foods Ltd., Cargill Inc., Barry Callebaut AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hazelnut Market Shifts & Advancements
Digital traceability infrastructure and sustainability-linked procurement criteria are rewriting supplier qualification protocols across European hazelnut trading desks, with technology investments now treated as competitive differentiators rather than cost centers.
Optical sorting systems incorporating near-infrared spectroscopy and AI-driven defect detection are bifurcating the processing equipment market. Large-scale shelling facilities in Turkey are deploying these platforms to eliminate manual grading labor, while smaller Italian roasters retain conventional calibrator lines. The technology split is compressing margin pools for mid-tier processors unable to justify capital deployment.
CSRD disclosure requirements on agricultural supply chains are reshaping importer due diligence obligations. European traders must now document scope 3 emissions from orchard to warehouse, driving investment in farm-level data collection partnerships. Chocolate manufacturers with 2025 reporting deadlines are prioritizing suppliers with existing carbon accounting infrastructure.
Single-origin procurement contracts are displacing commodity spot purchasing among artisanal chocolate makers and specialty food distributors. Direct relationships with Ordu and Giresun grower cooperatives are replacing layered trader intermediation for premium kernel streams. This pattern is most visible in Germany's bean-to-bar segment and Netherlands-based sustainable ingredient platforms.
Europe Hazelnut Market Segmentation
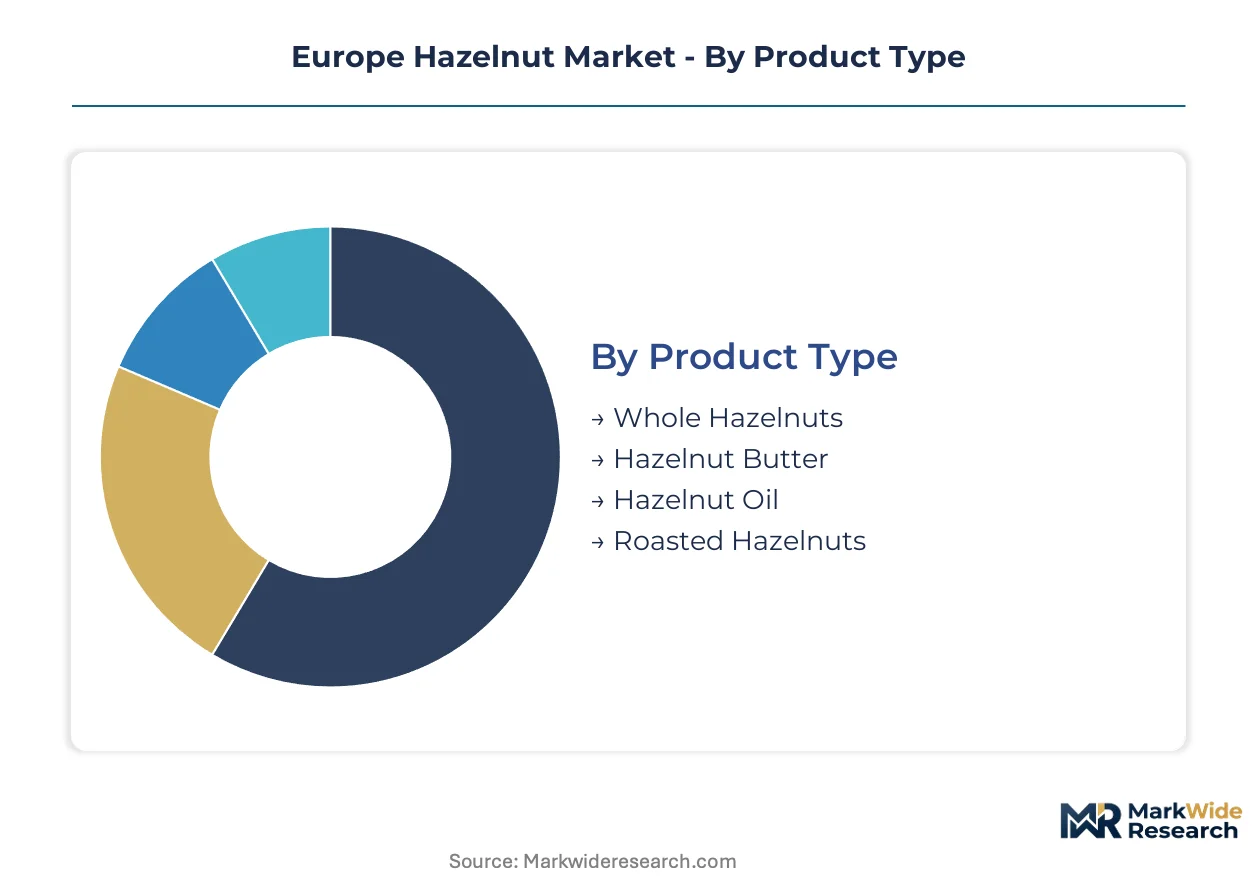
Hazelnut value chains fragment across four critical dimensions that determine margin capture and regulatory exposure. Product form dictates processing investment and shelf-life requirements. End-user concentration in confectionery shapes procurement scale, while channel and packaging choices determine traceability compliance burdens under EUDR mandates.
Product Type:
Whole kernels flow predominantly through Turkish processing clusters serving Italian and German chocolate manufacturers, while value-added formats like butter and oil increasingly originate from integrated European facilities.
- Whole Hazelnuts:Raw kernels calibrated to 11-13 mm and 13-15 mm grades dominate industrial offtake. Italian gianduja producers and German praline manufacturers anchor demand in Lombardy and Baden-Württemberg processing corridors.
- Hazelnut Butter:Finely milled paste with particle size below 20 microns for spread applications. Plant-based dairy formulators in Netherlands and Scandinavian markets are expanding butter inclusion rates as almond costs escalate.
- Hazelnut Oil:Cold-pressed and refined grades for culinary and cosmetic applications. French and Spanish food service distributors drive specialty oil procurement for finishing applications.
- Roasted Hazelnuts:Dry-roasted kernels with moisture content below 4 percent for snack and bakery integration. German industrial bakeries specify calibrated roasting profiles for consistent Maillard reaction in commercial dough systems.
Whole hazelnuts hold the largest share; momentum sits with hazelnut butter as dairy-alternative formulations expand.
End User:
Volume concentration varies sharply by margin tier, with confectionery commanding premium kernel grades while food service channels absorb smaller calibers and broken pieces at compressed pricing.
- Confectionery:Chocolate manufacturers require aflatoxin-tested kernels with sub-6 percent moisture for praline and spread production. Ferrero's captive Turkish orchard contracts lock in premium grade supply ahead of spot market competition.
- Bakery:Industrial and artisanal bakers utilize whole, chopped, and meal formats across laminated dough and inclusion applications. German and Austrian wholesale bakeries specify calibrated particle sizes for consistent dough rheology.
- Snacks:Roasted and flavored kernel packs for retail and vending channels. Private-label programs at Aldi and Lidl drive volume through Turkish-origin commodity grades.
- Food Service:Restaurants and catering operations deploy hazelnut oil and roasted formats for menu differentiation. Nordic fine-dining concepts are expanding single-origin oil programs with Georgian provenance claims.
Confectionery commands absolute volume; food service is climbing the fastest as chef-driven menu innovation accelerates.
Sales Channel:
Channel structure reflects buyer scale and compliance sophistication, with direct sales capturing traceable supply for EUDR-affected manufacturers while wholesale intermediaries serve smaller processors.
- Retail:Packaged consumer formats through supermarkets and specialty grocers. Italian and Spanish retail chains are expanding private-label roasted hazelnut SKUs in response to snacking trend acceleration.
- Wholesale:Bulk kernel and ingredient supply to processors and food manufacturers. Rotterdam and Hamburg trading desks aggregate Turkish and Georgian flows for redistribution across Northern Europe.
- Online:Direct-to-consumer and B2B platform sales for specialty and organic grades. Netherlands-based sustainable ingredient marketplaces are capturing artisanal chocolate maker procurement through single-origin listings.
- Direct Sales:Long-term contracts between processors and grower cooperatives. Ordu and Giresun cooperatives are establishing direct relationships with German bean-to-bar makers to bypass layered trader margins.
Wholesale channels handle the greatest volume; direct sales are expanding most quickly as traceability requirements compress intermediary layers.
Packaging Type:
Packaging selection correlates with supply chain position and shelf-life requirements, with bulk formats dominating processor intake and consumer-facing packaging demanding food-contact compliance certification.
- Bags:Laminated and vacuum-sealed formats for retail roasted kernels and meal. REACH-compliant barrier films are becoming mandatory for German and French retail listings.
- Bottles:Glass and PET containers for hazelnut oil retail distribution. Dark glass specifications predominate in premium segments to prevent oxidation and preserve tocopherol content.
- Bulk Packaging:25 kg and 50 kg multi-ply paper sacks for industrial kernel supply. Turkish exporters are upgrading to EUDR-compliant lot-tracking labels with geolocation QR codes.
- Cans:Metal and composite containers for roasted kernel shelf-stable retail. Italian snack brands favor nitrogen-flushed cans for extended ambient distribution.
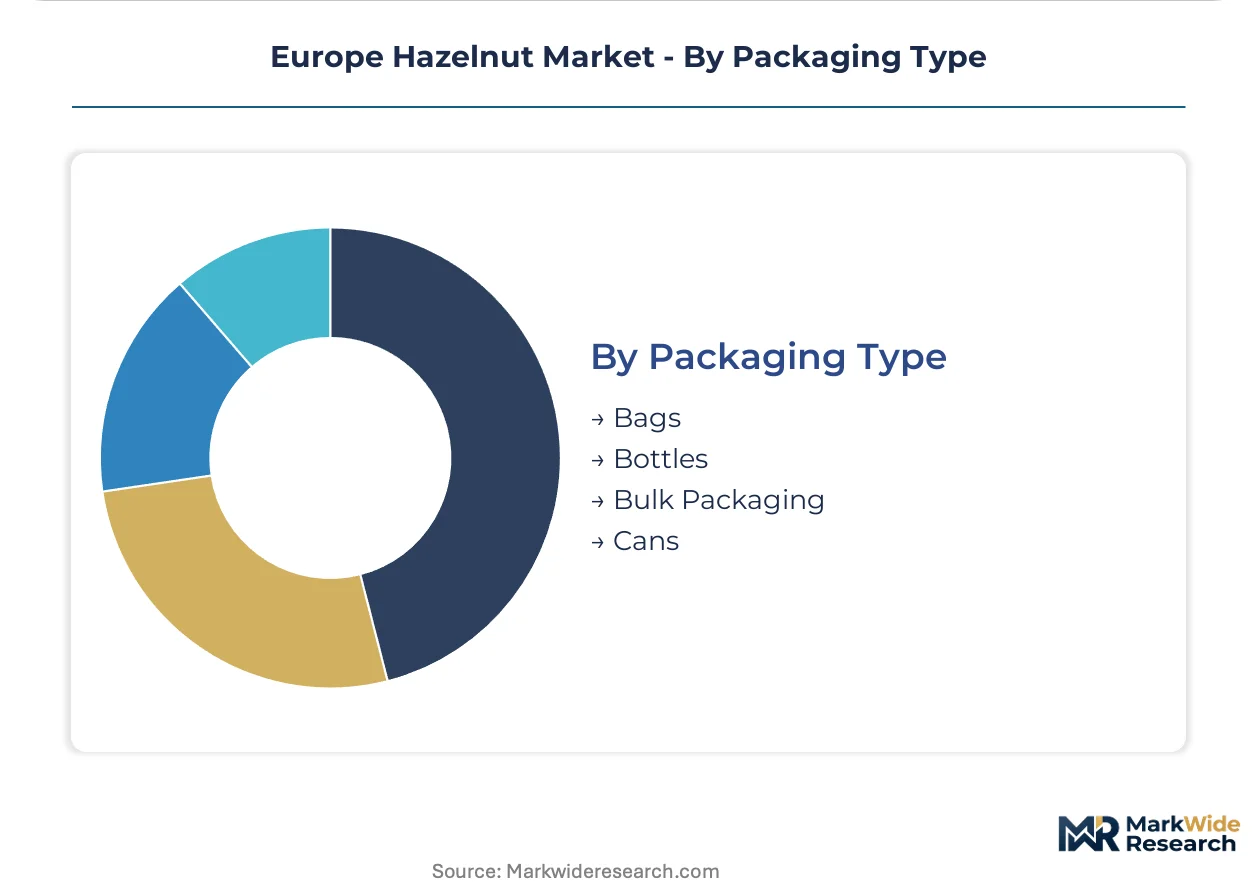
Bulk packaging holds the largest share; bags are gaining share fastest as retail snacking formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate manufacturers in Italy and Germany anchor kernel procurement, while Turkish processors serve re-export flows across Northern Europe. EFSA mycotoxin thresholds and EUDR traceability mandates shape import compliance costs. Processing gravity concentrates in Turkey's Black Sea corridor, with Ordu and Giresun anchoring shelling and blanching capacity.
Turkey
Ordu and Giresun provinces host integrated shelling, blanching, and cold-storage infrastructure serving Ferrero's captive contracts and European traders. EUDR geolocation verification systems now cover 90 percent of export-oriented orchards. The Black Sea port of Samsun aggregates container flows for Rotterdam and Hamburg redistribution.
Italy
Piedmont's gianduja manufacturers in Alba and Turin command premium-grade calibrated kernels for praline production. REACH food-contact packaging certification gates retail channel access for imported butter and paste. Lombardy-based industrial bakeries specify roasting profiles from Turkish toll processors.
Germany
Baden-Württemberg chocolate producers and Bavarian industrial bakeries drive calibrated kernel offtake through Hamburg trading desks. CSRD scope 3 disclosure requirements pressure procurement teams to document farm-level emissions. Bean-to-bar makers in Berlin bypass layered traders through direct Ordu cooperative contracts.
Georgia
Samegrelo and Guria regions offer organic-certified supply for specialty chocolate makers seeking single-origin provenance claims. EFSA aflatoxin testing protocols create lot-rejection risk for exporters building EU market access. Local processors are upgrading shelling lines to meet EUDR traceability mandates.
Netherlands
Rotterdam's port and trading infrastructure aggregates Turkish and Georgian flows for redistribution across Northern Europe. Sustainable ingredient marketplaces in Amsterdam capture artisanal chocolate maker procurement through single-origin listings. Plant-based dairy formulators expand hazelnut butter inclusion rates as almond costs escalate.
Europe Hazelnut Market Competitive Landscape
Player mix skews toward integrated Turkish processors with captive orchard access and European trading houses with sustainability certification infrastructure. Ferrero's backward integration into Turkish growing zones locks in premium-grade supply ahead of spot market competition. Mid-tier processors compete on calibrated roasting profiles and EUDR compliance readiness. Dominant competitive moves include direct grower cooperative partnerships and geolocation verification technology deployment.
Among Turkish integrated processors, Balsu Gida and Gürsoy Tarımsal Ürünler exemplify the Black Sea cluster model with shelling and blanching capacity anchored near primary growing zones. Besana Group represents the European trading house archetype, competing on calibrated roasting specifications for industrial bakery clients. Ferrero Group occupies a singular position through unmatched upstream orchard control, while Olam International and Cargill Inc. sit within the diversified agri-commodity trader tier leveraging multi-origin sourcing networks.
| Leading Market Players |
|---|
| Balsu Gida |
| Besana Group |
| Ferrero Group |
| Gürsoy Tarımsal Ürünler |
| DURAK FINDIK |
| Olam International |
| Chelmer Foods Ltd. |
| Cargill Inc. |
| Barry Callebaut AG |
| Others |
Supply & Pricing Matrix
Long-term grower contracts with Turkish cooperatives lock in kernel supply visibility while insulating Ferrero and Besana from spot price swings at the Samsun port. This contract structure concentrates pricing power among processors with backward integration into Ordu-Giresun orchards, leaving spot-dependent traders exposed to aflatoxin-related lot rejections and currency fluctuation at the Bosporus chokepoint.
Pricing Analysis
Cost-plus contracts indexed to Turkish lira volatility and natural gas input costs dominate kernel procurement for industrial chocolate manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates aflatoxin-tested organic grades from commodity kernels and broken pieces for bakery inclusion. Pricing pressure stems from energy-intensive roasting operations facing margin compression in Turkey's industrial zones. Industrial bakeries in Germany exhibit highest price sensitivity, while single-origin chocolate makers in Netherlands absorb premiums for traceable Georgian supply.
Supply Chain Analysis
Container availability constraints on the Samsun-Rotterdam trade lane are forcing traders to pre-book cold-storage capacity six months ahead of peak harvest. Supply concentrates in Turkey, Georgia, and Italy, with kernel flows drawing from Black Sea orchards, Samegrelo organic zones, and Piedmont processing corridors. Raw material dependencies include calibrated shelling equipment, nitrogen-flush packaging films, and REACH-compliant barrier materials. Single-source vulnerability concentrates at the Bosporus strait, where geopolitical friction disrupts re-export flows to Northern European distributors. Distribution runs through Rotterdam and Hamburg trading desks for redistribution across confectionery and bakery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's hazelnut market is recovering from cyclical compression driven by post-pandemic confectionery restocking and EUDR compliance investment cycles. Recovery durability hinges on sustained premium chocolate demand and successful Georgian origin development.
For Market Incumbents: Consolidate shelling and blanching capacity in Ordu-Giresun through toll-processing partnerships with cooperatives lacking EU export certification infrastructure. Lock in EUDR-compliant geolocation verification systems ahead of full enforcement deadlines, as audit capacity scarcity will disqualify uncertified competitors from German and Italian procurement tenders. Priority lever rests on captive cold-storage capacity at Samsun port. For New Entrants and Emerging Players: EUDR compliance service gaps among small-volume Georgian exporters present white-space entry points for traceability-technology providers and audit facilitation platforms. Target Samegrelo organic cooperatives seeking direct European relationships bypassing Turkish trader intermediation. Go-to-market angle centers on carbon-footprint accounting partnerships for CSRD-disclosure-ready supply chains. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier Turkish processors with existing EUDR infrastructure and underutilized roasting capacity serving German industrial bakery clients. Five-to-ten year viability favors assets with farm-level emissions accounting already operational. Signal to watch: acceleration of direct cooperative contracts displacing layered trader intermediation in Netherlands specialty ingredient platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Geolocation Verification Deployment | Satellite-based traceability infrastructure gates EU port access for Turkish and Georgian exporters. |
| Direct Cooperative Contracting | Bypassing Rotterdam traders captures margin compression for bean-to-bar makers in Berlin and Amsterdam. |
| Carbon Accounting Infrastructure Investment | Farm-level emissions data satisfies CSRD disclosure requirements for chocolate manufacturers with near-term reporting deadlines. |
| Georgian Origin Capacity Expansion | Samegrelo organic certification unlocks single-origin premium positioning for specialty chocolate segments. |
| Optical Sorting Technology Adoption | AI-driven defect detection eliminates manual grading labor in Turkish shelling facilities serving Ferrero contracts. |
Research Methodology
Desk research of EU customs trade databases, EFSA mycotoxin surveillance reports, and Turkish Ministry of Agriculture export statistics preceded structured interviews with hazelnut procurement managers at Italian chocolate manufacturers, Turkish cooperative export directors, Rotterdam commodity traders, and German industrial bakery ingredient buyers. Primary fieldwork validated secondary data on Ordu-Giresun processing capacity and EUDR compliance timelines. Bottom-up volume estimates from kernel trade flows triangulated against top-down confectionery demand models.
Variance decomposition across product form, end-use segment, and country-of-origin dimensions shaped analytical framework development over the projection horizon. Modeled segmentation captured whole kernel, butter, oil, and roasted formats; confectionery, bakery, snack, and food service demand channels; and Turkish, Georgian, and Italian supply origins. CAGRs derived from historical trade volume trajectories adjusted for EUDR implementation effects and CSRD disclosure acceleration. Industry-specific inputs included aflatoxin rejection rates at EU entry ports and natural gas cost pass-through coefficients for Turkish roasting operations.
Forecasts assume regulatory continuity in EU Deforestation Regulation enforcement and EFSA mycotoxin threshold maintenance; material policy shifts would require re-modeling of import gatekeeping costs and supplier qualification timelines. Specific risks include Bosporus geopolitical disruption, Georgian organic certification suspension, and confectionery demand contraction from cocoa price spillover effects. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Dry Fruits Market