
 North America Fruit Snacks Market | 2026-2036
North America Fruit Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fruit Snacks Market Analysis
Buyer fragmentation across health-conscious millennials and Gen Z consumers is recalibrating how fruit snack brands allocate trade spend and innovation budgets. General Mills leverages its established cereal and snack distribution network to secure shelf space in conventional grocery. Mondelēz International competes through global R&D scale, applying confectionery expertise to texture and flavor systems in chewy formats. The J.M. Smucker Company (Welch's) anchors its positioning through deep grape and fruit concentrate supply relationships built over decades.
North America fruit snacks comprise processed or minimally processed fruit-based consumables manufactured through dehydration, extrusion, or gelation, typically containing fruit puree, concentrate, or whole fruit pieces with functional additives for shelf stability and texture. These products serve commercial purposes spanning child-targeted lunchbox portions, adult workplace snacking, and senior nutrition supplementation. Chewy snacks dominate volume due to familiar mouthfeel and lower production complexity, while crispy snacks and dried fruit segments capture premium positioning through clean-label and no-added-sugar claims. Pouches lead packaging type adoption for on-the-go convenience, though multipacks sustain family and club-channel volume.
FDA nutrition labeling mandates and USDA school meal standards shape formulation requirements and permissible serving claims across the United States. Health Canada and the Canadian Food Inspection Agency enforce parallel compositional rules that determine cross-border product standardization costs. Stakeholders must monitor evolving added-sugar thresholds and front-of-package labeling proposals to anticipate reformulation timelines and portfolio rebalancing needs.
Market Dynamics
USDA school meal standards and FDA added-sugar labeling mandates are forcing simultaneous reformulation and portion resizing across manufacturer portfolios, compressing margin structures while opening compliant product lines to institutional procurement channels.
Growth Catalysts
- USDA School Nutrition Standards:K-12 meal program requirements for whole-fruit equivalents are expanding institutional procurement volumes for individually wrapped fruit snacks in the United States.
- Pacific Northwest Processing Clusters:Concentrated apple, berry, and stone fruit processing infrastructure in Washington and Oregon states reduces raw material logistics costs for regional manufacturers.
- Clean-Label Extrusion:Advanced twin-screw extrusion systems using whole fruit purees rather than concentrates enable no-added-sugar claims without texture degradation.
Market Restraints
- Concentrate Price Volatility:White grape and apple concentrate costs fluctuate with California and Washington state harvest yields, squeezing input cost predictability.
- Single-Serve Packaging Cost Premium:Pouch laminates with oxygen barrier layers cost 40-60% more per unit than bulk formats, limiting price competitiveness in value channels.
- Cross-Border Standardization Friction:Divergent Health Canada and FDA serving-size definitions force dual-label production runs for unified North American SKUs.
Strategic Opportunities
- Senior Nutrition Channels:Medicare Advantage supplemental benefit expansion for healthy snacks creates institutional procurement pathways in the United States.
- High-Pressure Processing (HPP):Cold pasteurization technology convergence with clean-label formulations enables refrigerated fruit snack segments with extended shelf life.
- Club Channel Multipacks:Costco and Sam's Club bulk formats remain underpenetrated relative to conventional grocery, offering volume scale without single-serve packaging cost burden.
Industry Challenges
- Food Science Talent Scarcity:Formulation chemists with dual expertise in fruit chemistry and extrusion rheology command premium compensation, constraining R&D expansion.
- Organic Certification Timelines:USDA Organic transition periods for orchard suppliers extend 36 months, delaying certified product line launches.
- Legacy Equipment Retrofit Costs:Converting existing confectionery extrusion lines for fruit-based formulations requires stainless steel component replacement and sanitation protocol overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fruit Snacks Market |
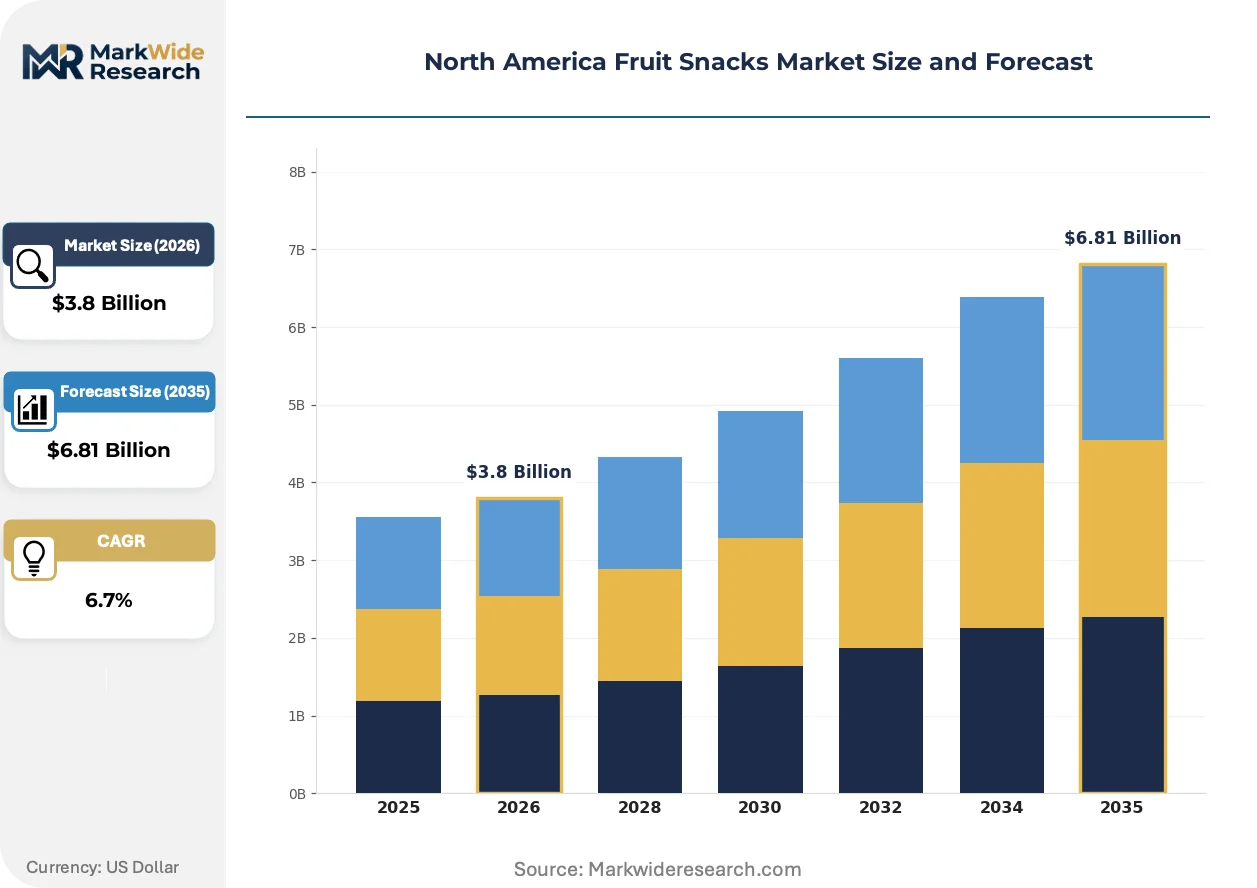
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewy Snacks, Crispy Snacks, Dried Fruit, Fruit Gels Packaging Type: Pouches, Boxes, Tubs, Multipacks Customer Type: Children, Adults, Seniors, Families Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores |
| Companies Covered | The Kraft Heinz Company, Mondelēz International, General Mills, Crispy Green, The J.M. Smucker Company (Welch's), Kellogg Company, PepsiCo (Bare Snacks), Dole Food Company, PIM Brands (Welch's), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fruit Snacks Market Emerging Trajectories
Reformulation toward whole-fruit bases and clean-label preservation methods is compressing traditional concentrate-dependent supply chains while enabling premium positioning in health-focused retail channels.
High-pressure processing (HPP) is automating cold pasteurization workflows for refrigerated fruit snack lines, eliminating thermal degradation of heat-sensitive vitamins. Target and Whole Foods Market buyers are accelerating shelf resets for HPP-treated SKUs. This technology is automating the shift from ambient-stable to refrigerated distribution, compressing conventional pasteurization equipment demand.
Health Canada's proposed front-of-package nutrition symbol regulations are mandating reformulation thresholds for sugars, sodium, and saturated fat in prepackaged foods. Manufacturers serving both Canadian and US markets face label harmonization costs or SKU proliferation. The chewy snack segment is responding fastest, deploying allulose and monk fruit blends to maintain sweetness intensity while avoiding mandatory warning symbols.
Millennial parents are consolidating lunchbox purchasing decisions through subscription and auto-replenishment platforms rather than in-store impulse selection. Amazon Subscribe & Save and Thrive Market curated boxes are displacing conventional grocery trial purchases for household fruit snack stocking. This behavioral shift is most pronounced in California and Texas metropolitan markets with high dual-income household density.
North America Fruit Snacks Market Segmentation
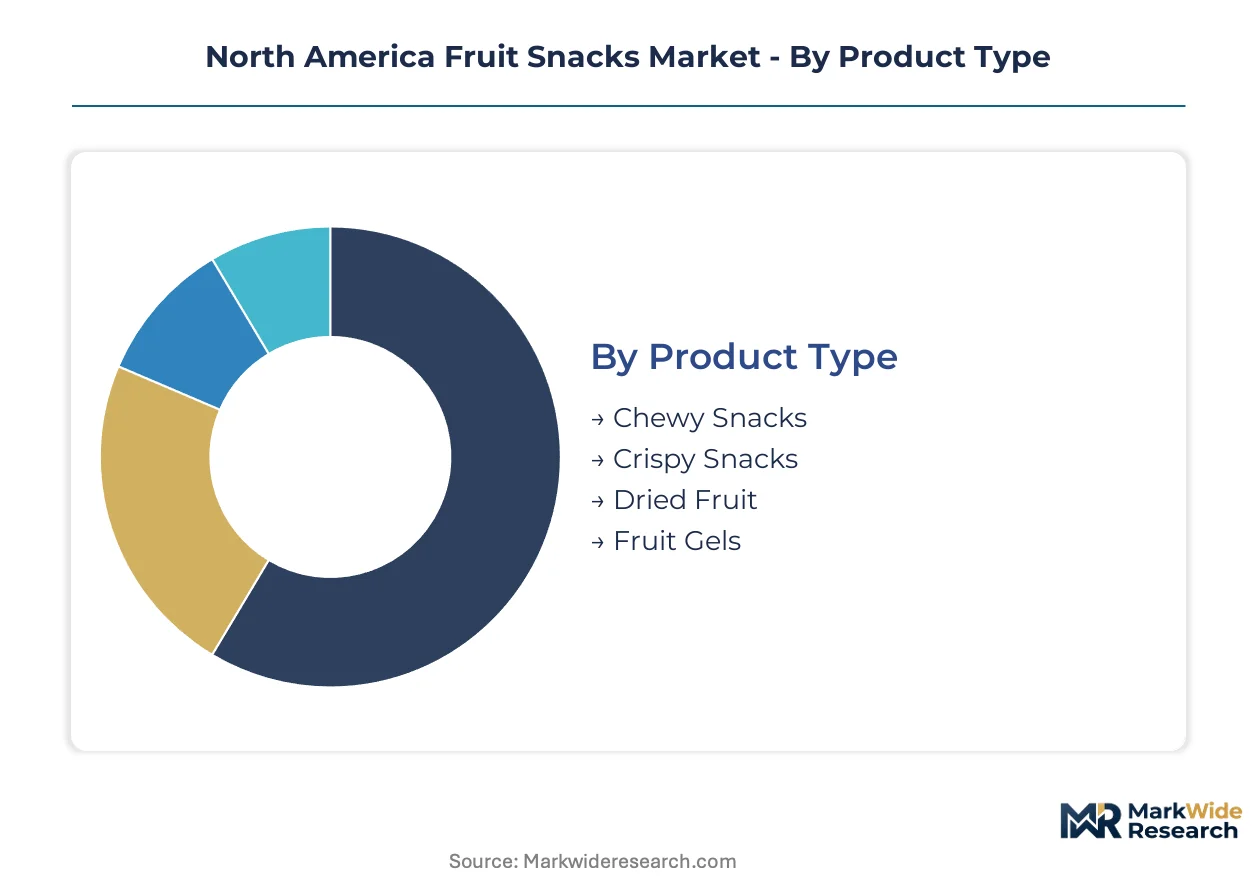
Segmentation in the North America fruit snacks market reveals how regulatory compliance costs, packaging economics, and channel access requirements fragment competitive positioning across distinct buyer clusters. Understanding these divides clarifies where formulation investments concentrate and which distribution pathways offer sustainable margin structures.
Product Type:
USDA school meal standards and FDA added-sugar labeling thresholds impose divergent certification burdens across formats, with chewy and crispy snacks facing stricter institutional procurement scrutiny than dried fruit or gel alternatives.
- Chewy Snacks:Gelatin or pectin-based matrices incorporating fruit puree or concentrate, extruded into bite-sized forms with controlled moisture content. Demand concentrates in K-12 school districts across California and Texas where individually wrapped portions satisfy USDA whole-fruit equivalent requirements, though concentrate price volatility squeezes margin predictability.
- Crispy Snacks:Dehydrated or freeze-dried fruit pieces, often combined with rice crisps or alternative grains, achieving shelf-stable crunch without frying. Pacific Northwest processing clusters in Washington and Oregon supply raw material inputs, with clean-label extrusion systems enabling no-added-sugar claims that pass Health Canada front-of-package thresholds.
- Dried Fruit:Traditional dehydration of whole fruit pieces without binding agents or added sweeteners.
- Fruit Gels:Pectin-set fruit purees with softer texture profiles targeting senior nutrition and pediatric segments.
Leading the category by volume: Chewy Snacks. Growing fastest: Crispy Snacks.
Packaging Type:
Cost tier differentiation separates premium oxygen-barrier laminates from economy bulk formats, with single-serve premiums running 40-60% above multipack per-unit economics.
- Pouches:Flexible laminate structures with oxygen and moisture barriers, enabling ambient shelf stability for 12-18 months. On-the-go consumption in metropolitan California and Texas markets drives adoption, though material costs limit competitiveness in value channels.
- Multipacks:Outer cartons containing 6-12 individually wrapped units, balancing portion control with reduced per-unit packaging overhead. Costco and Sam's Club procurement specifications favor this format for household and institutional buyers seeking volume scale without single-serve cost burdens.
- Boxes:Rigid paperboard containers for shelf-stable bulk presentation in conventional grocery.
- Tubs:Reclosable rigid containers targeting family pantry storage and foodservice back-of-house applications.
Highest volume concentration: Multipacks. Steepest expansion trajectory: Pouches.
Customer Type:
Application-specific formulation requirements separate pediatric-targeted lunchbox formats from senior nutrition products requiring softer textures and Medicare Advantage reimbursement alignment.
- Children:Portion-controlled formats with vibrant coloration and familiar fruit flavors, formulated to meet USDA school meal standards for whole-fruit equivalents. Millennial parents in dual-income California and Texas households increasingly purchase through Amazon Subscribe & Save rather than in-store impulse selection.
- Seniors:Softer gel or puree-based textures with elevated nutrient fortification, positioned for Medicare Advantage supplemental benefit coverage. Institutional procurement pathways through senior living operators and home health agencies create volume concentration distinct from retail channels.
- Adults:Workplace snacking and clean-label positioning for health-conscious millennials and Gen Z consumers.
- Families:Multipack and bulk formats balancing portion variety with household pantry economics.
Dominant volume share: Children. Gaining share fastest: Seniors.
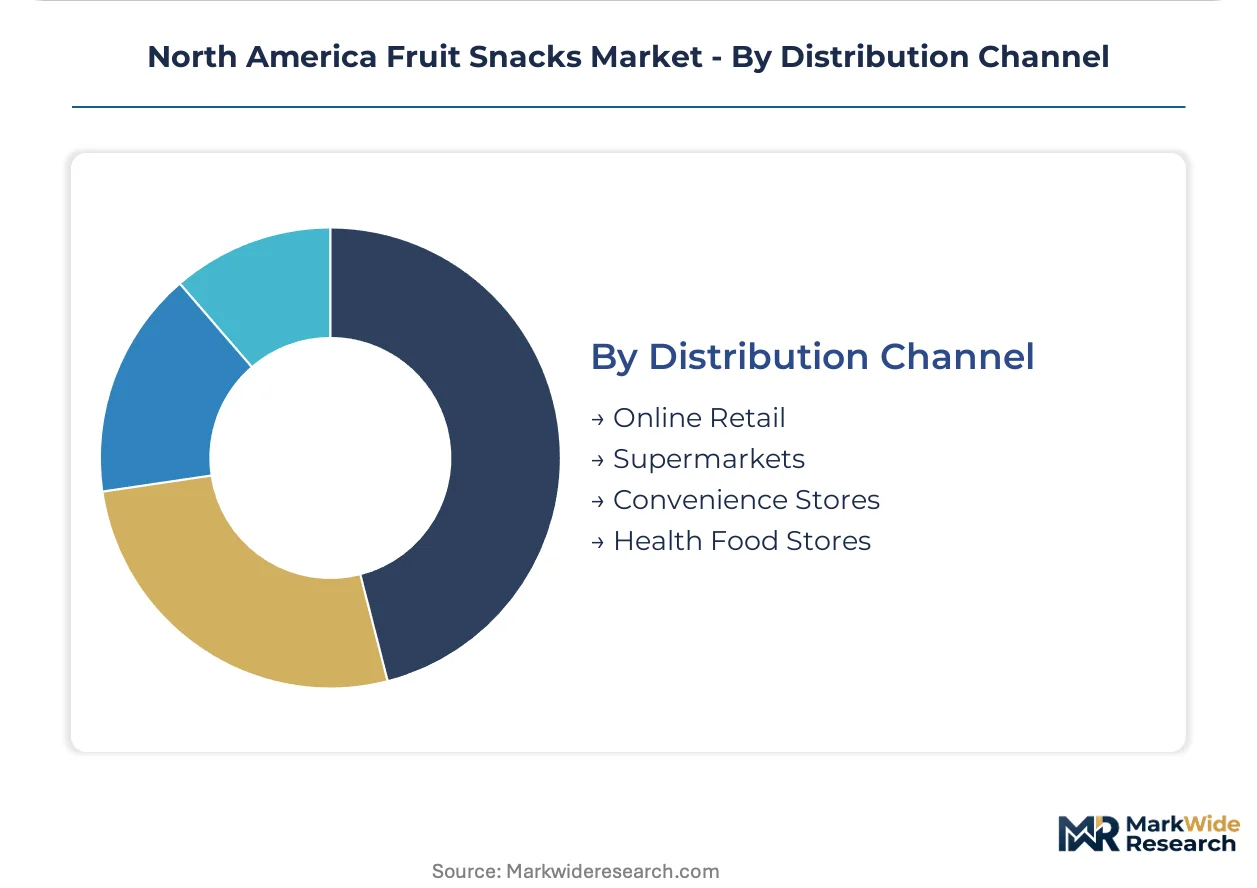
Distribution Channel:
Channel economics determine which packaging formats and price tiers achieve viable placement, with online retail compressing traditional grocery trial while health food stores command premium positioning for clean-label SKUs.
- Supermarkets:Conventional grocery chains with established snack aisle resets and promotional calendar dependencies. General Mills and Mondelēz International leverage cereal and confectionery distribution networks to secure shelf space, though slotting fees concentrate placement among scaled manufacturers.
- Online Retail:Amazon, Thrive Market, and direct-to-consumer platforms enabling subscription-based replenishment. Auto-replenishment algorithms displace in-store impulse purchasing most aggressively in California and Texas metropolitan markets with high dual-income household density.
- Convenience Stores:Single-serve impulse formats at elevated price points for immediate consumption occasions.
- Health Food Stores:Whole Foods Market and regional natural retailers prioritizing HPP-treated and certified organic SKUs with extended refrigerated distribution.
Largest volume channel: Supermarkets. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States school nutrition programs and Pacific Northwest processing infrastructure concentrate demand-side pull and supply-side capacity across the continent. Canada adds cross-border standardization complexity through Health Canada regulations. Mexico contributes manufacturing cost advantages and growing consumer markets.
United States
USDA school meal standards for whole-fruit equivalents drive institutional procurement volumes in California and Texas K-12 districts. FDA updated Nutrition Facts labeling requirements for added sugars force reformulation timelines across manufacturer portfolios. Pacific Northwest processing clusters in Washington and Oregon supply apple, berry, and stone fruit concentrates to regional extrusion facilities.
Canada
Health Canada's proposed front-of-package nutrition symbol regulations mandate reformulation thresholds for sugars in prepackaged foods. The Canadian Food Inspection Agency enforces compositional rules that create dual-label production requirements for unified North American SKUs. Ontario and Quebec retail channels concentrate demand for clean-label fruit snack imports from US manufacturers.
Mexico
Growing middle-class consumption in Mexico City and Guadalajara metropolitan areas expands retail channel penetration for pouch-format fruit snacks. Mexican food safety regulator COFEPRIS maintains labeling standards that generally align with US FDA frameworks, reducing cross-border friction. Northern border states host contract manufacturing facilities serving US private-label brands seeking cost-competitive production.
North America Fruit Snacks Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and refrigerated segments with differentiated preservation technologies. The market structure consolidates around three to five scaled manufacturers with cereal and confectionery distribution networks, while specialty operators fragment the premium dried fruit and HPP-treated segments. Strategic archetypes include diversified snack conglomerates leveraging existing retail relationships, fruit processors with captive raw material supply, and venture-backed clean-label specialists. Dominant competitive moves center on portfolio reformulation for regulatory compliance and strategic partnerships with Pacific Northwest fruit processors.
Among diversified snack conglomerates, General Mills and Mondelēz International exemplify scale-driven players with established grocery distribution infrastructure. The J.M. Smucker Company anchors the fruit processor archetype through its Welch's brand and deep grape concentrate supply relationships. Crispy Green represents the emerging clean-label specialist tier, occupying a position in freeze-dried fruit segments without added sugars.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Mondelēz International |
| General Mills |
| Crispy Green |
| The J.M. Smucker Company (Welch's) |
| Kellogg Company |
| PepsiCo (Bare Snacks) |
| Dole Food Company |
| PIM Brands (Welch's) |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with dual expertise in fruit chemistry and extrusion rheology concentrate in the Pacific Northwest, and their premium compensation requirements widen spreads between economy concentrate-based products and premium whole-fruit formulations. Labor-cost differentials between these specialized technical clusters and general food manufacturing regions directly feed into three-tier pricing stratification across the category.
Pricing Analysis
Volume concentrates in chewy snacks at compressed margins, while crispy and HPP-treated segments capture premium realization through clean-label positioning. Pricing stratifies across premium no-added-sugar certifications, standard concentrate-based formulations, and economy private-label tiers, with differentiation driven by USDA Organic status and Health Canada front-of-package compliance. Price erosion runs through standard-tier multipacks as retailers consolidate assortment around faster-moving SKUs. K-12 institutional buyers exhibit highest price sensitivity, while Medicare Advantage channels show lowest elasticity due to reimbursement coverage.
Supply Chain Analysis
Freight costs from Washington and Oregon processing clusters to Texas and California distribution centers represent a structural cost layer that regional competitors offset through proximity advantages. Raw material supply draws from concentrated apple, berry, and stone fruit processing infrastructure in the United States Pacific Northwest, with secondary sourcing from Canadian orchard operations in British Columbia. Single-source vulnerability concentrates in white grape concentrate supply chains tethered to California harvest yields. Distribution runs through conventional grocery warehouse networks, with refrigerated HPP lines requiring direct-to-retailer cold chain logistics bypassing traditional dry-grocery distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FDA added-sugar labeling mandates and concentrate price volatility force sub-scale operators toward exit or acquisition. Margin compression across standard-tier chewy snacks accelerates competitive thinning.
For Market Incumbents: To counter emerging clean-label specialists with HPP capabilities, General Mills and Mondelēz International should deepen backward integration into Pacific Northwest fruit concentrate supply through long-term procurement agreements with Washington state processors. Securing exclusive access to whole-fruit puree extrusion capacity represents a second defensive lever against texture-degradation risks in no-added-sugar reformulation. For New Entrants and Emerging Players: Medicare Advantage supplemental benefit channels for senior nutrition remain underserved by incumbent portfolios optimized for pediatric and family segments. New entrants should prioritize soft-texture fruit gel formulations with elevated nutrient fortification positioned for institutional procurement through senior living operators. A direct-to-senior-living sales force bypasses conventional grocery slotting fee barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale fruit processors possessing captive orchard supply and USDA Organic certification infrastructure, given Health Canada's proposed front-of-package regulations accelerating cross-border demand for compliant formulations. Long-term viability hinges on clean-label preservation technology ownership rather than brand equity alone. The signal to watch is accelerated shelf-reset velocity at Whole Foods Market and Target for HPP-treated SKUs as inflection indicator for technology-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pacific Northwest Fruit Supply | Long-term concentrate procurement agreements with Washington processors reduce input cost volatility exposure. |
| HPP Cold Pasteurization Technology Deployment | Refrigerated distribution partnerships with Target and Whole Foods Market unlock premium channel access. |
| USDA Organic Certification Investment | Thirty-six-month orchard transition timelines position certified product lines ahead of Health Canada regulatory thresholds. |
| Senior Nutrition Channel Development | Medicare Advantage supplemental benefit alignment creates institutional procurement pathways distinct from retail competition. |
| Club Channel Multipack Format Expansion | Costco and Sam's Club specifications favor volume scale without single-serve packaging cost premiums. |
Methodological Framework
Multi-period observation of FDA reformulation timelines, USDA school procurement volumes, and Health Canada regulatory proposal progressions anchored the trend analysis, supplemented by interviews with fruit snack brand managers, Pacific Northwest fruit processor operations directors, K-12 district foodservice coordinators, and senior living procurement officers. Secondary validation drew from FDA Nutrition Facts labeling guidance documents, USDA school meal standard updates, Health Canada front-of-package consultation records, and Nielsen retail audit data. Bottom-up SKU-level volume aggregation and top-down category expenditure estimates were triangulated to constrain forecast variance.
Segment-weighting applied differential growth assumptions across chewy, crispy, dried fruit, and gel formats, with cross-segment calibration against packaging type economics and distribution channel penetration trajectories. Modeled dimensions included product type, packaging configuration, customer demographic archetype, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to historical volume data and elasticity-adjusted for reformulation-driven substitution effects. Forecast inputs incorporated concentrate price volatility indices and school nutrition program budget appropriation trends.
Revisions become necessary when FDA added-sugar threshold modifications, Health Canada front-of-package implementation delays, or Pacific Northwest harvest yield disruptions materialize outside baseline assumptions. Forecasts reflect documented scenario parameters and elasticity estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Snack Bar Market
Snacks
Tortilla Mix Market
Snacks
Candy and Snack Food Pouches Market
Snacks
High Carb Low Fat Snack Market
Snacks
US Potato Chips Market
Snacks
Extruded Snacks Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Europe Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Better for You Snacks Market
Snacks
Snacks Market
Snacks
Saudi Arabia French Fries Market
Snacks
South America Protein Bar Market
Snacks
No Fat Snacks Market
Snacks
Energy Bar Market
Snacks
Healthy Snacks Market