
 South America Frozen Snacks Market | 2026-2036
South America Frozen Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
South America Frozen Snacks Market Analytics
Single-serve and duo-portion packaging is shifting buyer choice away from bulk family formats across South America. McCain Foods Ltd. leverages its regional production footprint to sustain consistent supply to Brazilian retail chains. BRF S.A. anchors its frozen snack portfolio through deep distribution into domestic supermarkets and foodservice outlets. JBS S.A. competes by extending its protein-processing infrastructure into value-added frozen appetizer lines.
Frozen snacks comprise pre-cooked or partially prepared food items preserved at sub-zero temperatures, typically formulated with starches, proteins, or vegetables and requiring thermal reactivation before consumption. The category serves commercial foodservice operators and retail consumers seeking extended shelf stability without fresh preparation. Appetizers and pizzas occupy the largest volume positions, while desserts represent the fastest-expanding margin pool as premium indulgence formats gain traction. Bags and boxes dominate packaging, though tray configurations capture growing share in foodservice channels where presentation standards matter.
Brazil's ANVISA governs frozen food safety standards, while Argentina's national food regulator enforces cold chain traceability requirements that shape distribution investments. Colombia's INVIMA certification protocols create compliance thresholds for cross-border suppliers entering Andean markets. Stakeholders must monitor evolving Mercosur harmonization talks, as unified sanitary standards would reshape which production facilities qualify for multi-country supply.
Market Dynamics
Cold chain infrastructure expansion across South America is compressing distribution timelines and enabling frozen snack penetration into secondary cities previously unreachable due to spoilage risk. This structural shift reconfigures competitive positioning around logistics capability rather than manufacturing scale alone.
Growth Catalysts
- ANVISA cold chain mandates:Brazil's frozen food safety standards force distributor upgrades that simultaneously reduce waste and extend product reach into underserved interior markets.
- Quick-service restaurant proliferation:Fast-casual chains from São Paulo to Buenos Aires now standardize frozen appetizer SKUs across locations, creating predictable demand pull.
- Flash-freezing technology adoption:Cryogenic tunnel systems preserve texture quality in empanadas and tequeños, elevating consumer acceptance of premium formats.
Market Restraints
- Electricity cost volatility:Cold storage operations face margin pressure from grid instability across Argentina and Venezuela, forcing diesel generator redundancy.
- Import dependency for specialty ingredients:Mozzarella and specialty starches concentrate sourcing from Mercosur trade partners, exposing producers to tariff friction.
- Last-mile refrigeration gaps:Informal retail channels in Colombian and Peruvian highlands lack consistent freezing capacity, capping addressable market size.
Strategic Opportunities
- Colombian Andean corridor penetration:Bogotá-Medellín-Cali urban clusters show frozen snack underpenetration relative to income levels, awaiting cold chain completion.
- INVIMA certification harmonization:Andean regulatory alignment would enable single-facility qualification for Colombia-Ecuador-Peru supply, collapsing compliance overhead.
- Direct-to-foodservice platforms:Digital procurement portals bypass traditional distributor markups for independent pizzerias and bars in Brazilian secondary cities.
Industry Challenges
- Cold chain engineer scarcity:Refrigeration technicians with frozen food specialization remain concentrated in São Paulo and Buenos Aires, constraining facility expansion.
- Legacy ERP integration:Mid-size Brazilian producers struggle to connect temperature-monitoring IoT sensors with existing inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Frozen Snacks Market |
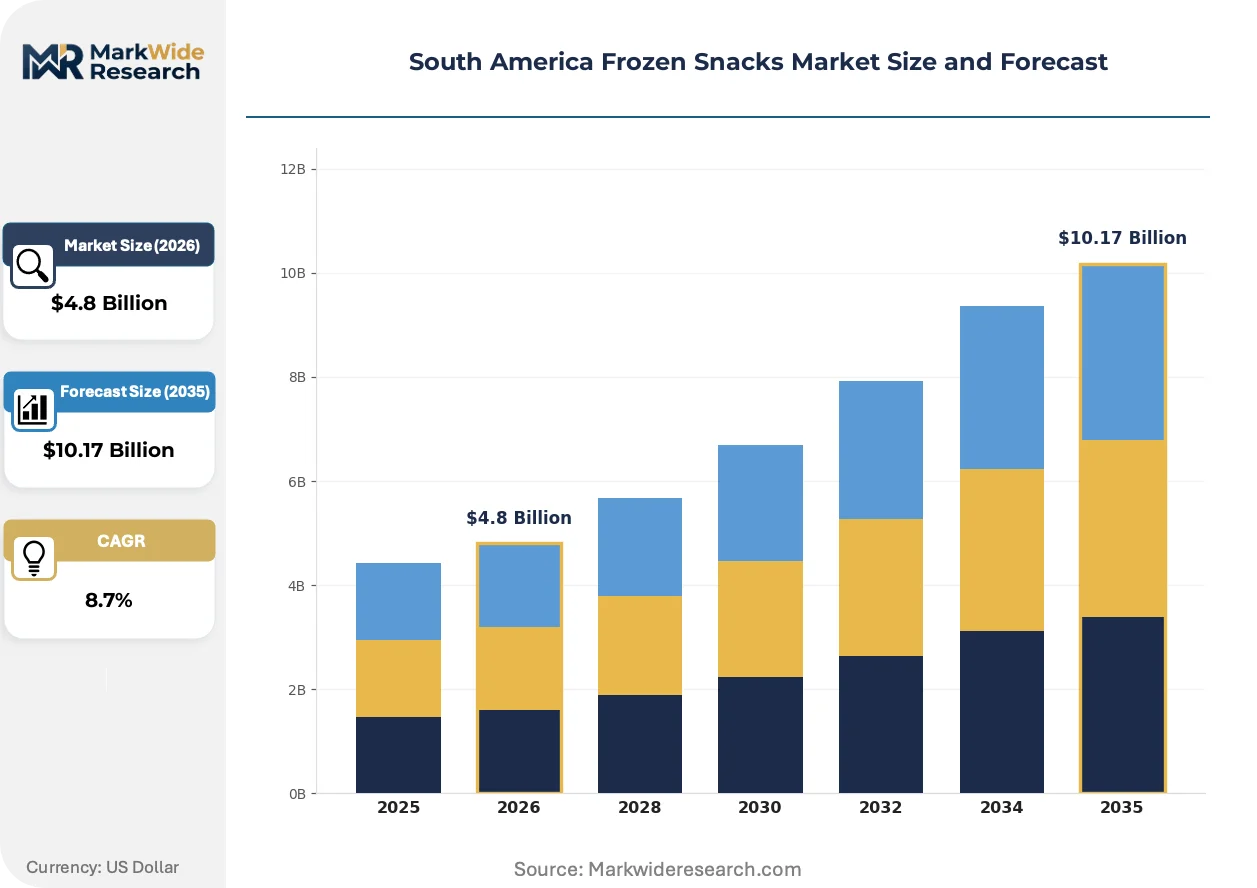
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pizzas, Vegetables, Appetizers, Desserts Packaging Type: Bags, Boxes, Trays, Tubs End User: Restaurants, Supermarkets, Convenience Stores, Home Use Distribution Channel: Online, Retail, Wholesale, Foodservice |
| Companies Covered | McCain Foods Ltd., BRF S.A., JBS S.A., Dr. Oetker, Mani Snacks Inc., Productos del Plata Inc., Forno de Minas, Alimentos Polar, Alimentos Catalina, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Frozen Snacks Market Evolving Landscape
Packaging formats and preservation technologies are converging to reshape how frozen snacks move through South American supply chains. These shifts prioritize portion flexibility, traceability compliance, and channel-specific presentation standards over traditional bulk efficiency.
Modified atmosphere packaging (MAP) with nitrogen flush systems is expanding into Brazilian retail freezer cases. Supermarket chains in São Paulo and Rio de Janeiro deploy MAP for premium appetizer lines to extend visual shelf appeal. This technology compresses the advantage window of imported European brands by matching their shelf-life claims with domestic production.
Argentina's national food regulator enforces serialized cold chain traceability that mandates GPS logging for transport vehicles above defined tonnage thresholds. Frozen snack distributors must retrofit fleet telematics or face market exclusion. The compliance burden falls heaviest on cross-border suppliers serving Buenos Aires from Brazilian plants, accelerating local production investment.
Single-serve and duo-portion formats displace family-size bags in Colombian and Chilean convenience channels. Urban consumers in Santiago and Bogotá purchase frozen snacks for immediate consumption rather than household inventory. This pattern forces reformulation of product dimensions and cooking instructions for air fryer compatibility, which now dominates apartment kitchen equipment in dense metropolitan zones.
South America Frozen Snacks Market Segmentation
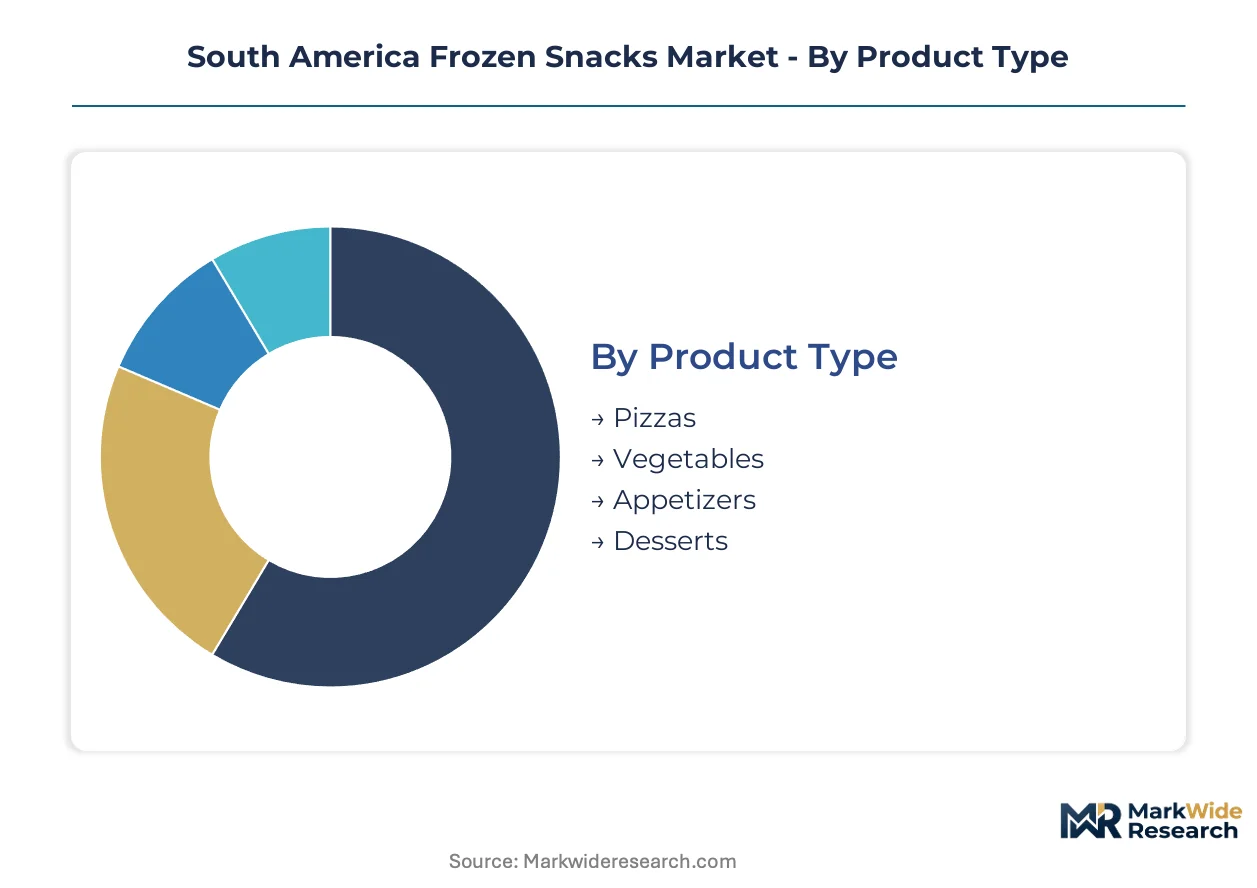
Frozen snack purchasing in South America fractures across preparation requirements, consumption occasions, and channel access. Manufacturers configure production lines and cold chain investments around these divides, with product format and packaging geometry determining freezer compatibility and margin structure.
Product Type:
Buyers choose based on meal occasion and kitchen equipment availability, with preparation time and crisping technology compatibility driving repeat purchase.
- Pizzas:Thin-crust and stuffed-crust variants dominate Brazilian retail freezers, with São Paulo households favoring 30cm diameter formats compatible with standard ovens. Quick-service chains in Rio de Janeiro specify pre-sliced rectangular formats for throughput efficiency.
- Appetizers:Empanadas, tequeños, and croquettes anchor foodservice procurement across Argentina and Colombia, with cryogenic freezing preserving textural integrity through distribution. Flash-frozen bite-sized formats climb fastest in Bogotá convenience channels.
- Vegetables:Breaded and battered vegetable strips serve institutional cafeterias seeking vegetable quota compliance without fresh prep labor.
- Desserts:Mini churros and dulce de leche-filled pastries target impulse purchase in Chilean supermarket freezer aisles.
Pizzas lead on scale; appetizers lead on momentum.
Packaging Type:
Packaging geometry determines shelf density, freezer burn protection, and foodservice presentation standards.
- Bags:Flexible polyethylene dominates bulk vegetable and appetizer formats, minimizing cube for transport efficiency while requiring rigid secondary containment in retail displays.
- Boxes:Folding carton with PE windows commands premium pizza and dessert positioning, with São Paulo supermarkets specifying shelf-ready case counts.
- Trays:CPET and aluminum configurations capture growing foodservice share where plate-up presentation matters for Argentine hotel breakfast buffets.
- Tubs:Injection-molded PP containers serve scoopable desserts and prepared dips in Colombian convenience channels.
Bags dominate volume throughput; trays gain share fastest in channel migration toward foodservice.
End User:
Cold chain capability and purchase frequency separate institutional buyers from household consumers.
- Restaurants:Independent pizzerias across Brazil's interior cities source frozen dough and pre-topped formats to bypass skilled labor scarcity.
- Supermarkets:São Paulo and Rio de Janeiro chains operate dedicated frozen aisles with temperature-monitoring displays, capturing the largest household spend concentration.
- Convenience Stores:Colombian and Chilean urban formats stock single-serve items for immediate consumption, requiring compact freezer footprints.
- Home Use:Argentine households in Buenos Aires suburbs maintain chest freezers enabling bulk purchase during promotional cycles.
Supermarkets anchor volume capture; convenience stores expand most quickly in urban densification.
Distribution Channel:
Channel selection determines margin retention, with direct relationships compressing intermediary costs.
- Retail:Hypermarket and supermarket chains in Brazil's southeastern corridor specify delivery windows and temperature documentation, absorbing the largest shipment volumes.
- Foodservice:Broadline distributors serving Argentine and Colombian restaurant groups bundle frozen snacks with protein and produce categories.
- Wholesale:Cash-and-carry formats in Peruvian and Ecuadorian markets enable small restaurant operator purchasing without credit facilities.
- Online:São Paulo-based delivery platforms experiment with dark-store freezer capacity for 30-minute frozen snack fulfillment.
Retail commands absolute volume; online experiments show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frozen snack manufacturing in South America traces its modern lineage to post-war Italian immigration into São Paulo and Buenos Aires, where industrial pasta and pizza production scaled from neighborhood bakeries into freezer-aisle staples. Cold chain infrastructure investments since the 1990s redistributed production capacity across national borders while preserving these original manufacturing clusters as technical centers.
Brazil
São Paulo state's southeastern corridor generates the continent's largest frozen snack throughput, with quick-service chains standardizing frozen appetizer SKUs across metropolitan locations. ANVISA cold chain mandates force distributor fleet upgrades that simultaneously reduce spoilage and extend product reach into interior cities. Campinas and Sorocaba industrial parks host cryogenic tunnel installations preserving empanada texture quality for export-grade production.
Argentina
Buenos Aires province maintains dense concentrations of empanada and tequeño fabricators serving both domestic freezers and cross-border foodservice. The national food regulator enforces serialized GPS logging for transport vehicles above defined tonnage thresholds, retrofitting fleet telematics across distributors. Rosario's agro-industrial belt supplies specialty starches and mozzarella inputs that concentrate Mercosur trade dependency.
Colombia
Bogotá-Medellín-Cali urban clusters exhibit frozen snack underpenetration relative to income levels, awaiting cold chain completion into Andean highland markets. INVIMA certification protocols create compliance thresholds for cross-border suppliers entering from Ecuador and Peru. Cali's Pacific corridor logistics hubs experiment with direct-to-foodservice digital procurement bypassing traditional distributor markups.
Chile
Santiago's dense metropolitan kitchen profiles favor single-serve and duo-portion formats compatible with air fryer equipment dominating apartment households. Convenience channels in Providencia and Las Condes stock frozen snacks for immediate consumption rather than household inventory. Valparaíso port infrastructure enables temperature-controlled reefer exports reaching Pacific Rim markets.
Peru
Lima's coastal foodservice operators source frozen appetizers through cash-and-carry wholesale formats enabling small restaurant purchasing without credit facilities. Informal retail channels in Andean highlands lack consistent freezing capacity, capping addressable market size despite urban demand concentration. Callao port cold storage investments target re-export positioning for Andean corridor supply.
South America Frozen Snacks Market Competitive Landscape
The competitive structure tilts toward diversified protein processors extending into value-added frozen lines. Brazilian and Argentine producers dominate volume positions through captive distribution into domestic retail chains. Three archetypes populate the field: multinational frozen food specialists with regional production footprints, integrated meatpackers backward-integrating into appetizer manufacturing, and domestic family-owned brands with hyperlocal channel relationships. Competitive moves concentrate on cold chain capability investments and direct-to-foodservice platform development.
Among multinational specialists, McCain Foods Ltd. and Dr. Oetker occupy positions exemplifying scale-driven supply consistency to supermarket chains. Integrated protein processors BRF S.A. and JBS S.A. represent the backward-integration archetype, leveraging existing refrigerated distribution infrastructure. Domestic specialists including Forno de Minas and Alimentos Polar anchor regional identity in specific national markets, with Mani Snacks Inc. and Productos del Plata Inc. occupying mid-tier positions between scale and localization.
| Leading Market Players |
|---|
| McCain Foods Ltd. |
| BRF S.A. |
| JBS S.A. |
| Dr. Oetker |
| Mani Snacks Inc. |
| Productos del Plata Inc. |
| Forno de Minas |
| Alimentos Polar |
| Alimentos Catalina |
| Others |
Value Network & Pricing Analysis
Quick-service restaurant chains across Brazil's southeastern corridor anchor demand concentration, locking in contract-based long-term offtake pricing that compresses margin flexibility for mid-tier producers serving fragmented retail channels.
Pricing Analysis
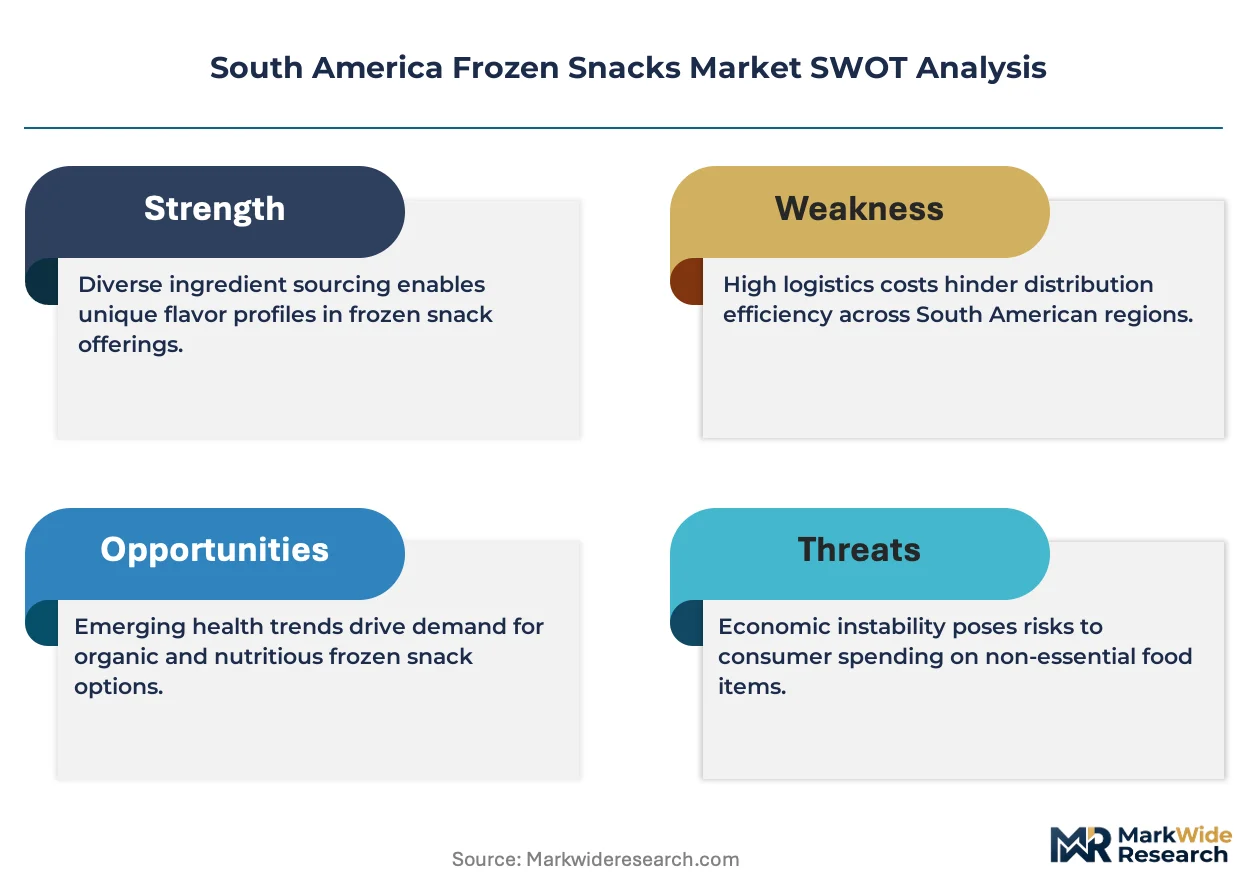
Three-tier pricing structure across premium, standard, and economy levels separates cryogenic flash-frozen appetizer lines from conventional blast-frozen formats and basic private-label offerings. Price differentiation rests on cold chain certification grade and volume scale, with ANVISA-compliant distributors commanding premium positioning. Cost compression in economy tiers is intensifying because electricity volatility across Argentina forces diesel generator redundancy into landed costs. Small independent pizzerias in Brazilian interior cities exhibit highest price sensitivity, while São Paulo-based fast-casual chains prioritize supply consistency over unit cost.
Supply Chain Analysis
Refrigeration technician scarcity in São Paulo and Buenos Aires constrains facility expansion timelines, forcing producers to bid against cold storage operators for qualified labor. Manufacturing gravity centers on Brazil, Argentina, and Colombia, with specialty mozzarella and modified starch inputs drawing from Mercosur trade partners. Single-source vulnerability concentrates in cryogenic tunnel equipment, where European and North American suppliers dominate installed base. Distribution runs through broadline foodservice distributors bundling frozen snacks with protein categories, though direct-to-foodservice digital portals are bypassing traditional markups in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Brazil's mature cold chain infrastructure and Colombia's underpenetrated Andean corridor, where regulatory compliance costs currently exceed per-capita consumption potential.
For Market Incumbents: Hedge against margin erosion by securing captive mozzarella and specialty starch supply through backward integration into Rosario's agro-industrial belt. Simultaneously defend channel position by embedding IoT temperature-monitoring systems into distributor fleets, converting ANVISA compliance burden into switching costs that lock out regional challengers.
For New Entrants and Emerging Players: Launch via direct-to-foodservice digital procurement platforms targeting independent pizzerias and bars in Brazilian secondary cities beyond São Paulo and Rio de Janeiro. The Colombian Andean corridor offers the most penetrable geography, with Bogotá-Medellín-Cali clusters awaiting cold chain completion and INVIMA certification creating temporary barriers that favor first-movers with compliance investment capacity.
For Investors and Strategic Acquirers: Integrated protein processors are the most active acquirer in this space, seeking value-added frozen appetizer lines to absorb excess refrigerated distribution capacity. Long-term viability hinges on cold chain engineer availability scaling faster than facility expansion. The signal to watch is Mercosur sanitary harmonization progress, which would collapse multi-country compliance overhead and reshape acquisition premiums for single-facility regional suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Investment | ANVISA-compliant fleet telematics extend product reach into Brazil's interior cities while reducing spoilage. |
| Backward Integration into Dairy Inputs | Rosario-based mozzarella supply anchors margin control for Argentine tequeño and empanada producers. |
| Single-Serve Format Reformulation | Air fryer-compatible dimensions capture Santiago apartment household consumption patterns. |
| Direct-to-Foodservice Platform Launch | Digital procurement portals bypass traditional distributor markups for independent Brazilian pizzerias. |
| INVIMA Certification Pre-Positioning | Early compliance investment enables single-facility qualification for Colombia-Ecuador-Peru supply. |
Research Methodology
Coverage spans Brazil, Argentina, Colombia, Chile, and Peru, with primary inputs from each market combining interviews with cold chain operations directors, frozen food category buyers at supermarket chains, quick-service restaurant procurement managers, and ANVISA compliance officers with secondary validation. Secondary sources include customs and trade flow data, ANVISA regulatory filings, INVIMA certification registries, and refrigerated logistics operator disclosures. Bottom-up volume modeling triangulates against top-down macroeconomic consumption indicators.
Granularity-level modeling disaggregates volume and value across product type, packaging format, end-user channel, and distribution mode, with additional dimensioning by metropolitan cluster density and cold chain maturity tier. CAGRs derive from segmented growth trajectory analysis incorporating urbanization rates, quick-service restaurant penetration curves, and electricity grid stability indices. Industry-specific forecast inputs include flash-freezing technology adoption rates and Mercosur regulatory harmonization probability assessments.
Several conditions sit outside the modeled scope, including Venezuela market re-entry scenarios, Pacific Rim export tariff regime shifts, and diesel fuel subsidy policy changes across Argentina. Forecasts reflect documented assumptions regarding cold chain infrastructure investment continuity and urban income growth trajectories. Material deviation in ANVISA enforcement intensity or Mercosur harmonization timeline warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Snack Products Market
Snacks
Australia Snack Bar Market
Snacks
Saudi Arabia French Fries Market
Snacks
Europe Snacks Market
Snacks
Organic Snacks Market
Snacks
Low Fat Crackers Market
Snacks
South America Energy Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
Dairy Protein Crisps Market
Snacks
Legume-Based Snacks Market
Snacks
Edible Flakes Market
Snacks
Global Rice Snacks Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Cheese Snacks Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Snack Pellets Market