
 Global Vegetable Chips Market | 2026-2036
Global Vegetable Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vegetable Chips Market Outlook
Premium clean-label certification is bifurcating the Global Vegetable Chips Market into mass-market and specialty tiers. PepsiCo leverages its retail shelf-space dominance to sustain volume leadership across conventional channels. The Hain Celestial Group differentiates through organic positioning and health-food store penetration. Rhythm Superfoods anchors the raw-dehydrated subsegment with minimal-processing claims.
Vegetable chips are thin-sliced or extruded root vegetables and leafy greens, dehydrated or fried to moisture levels below 5 percent, seasoned with salt, oil, or spice blends for shelf-stable snacking. Vacuum frying at sub-atmospheric pressure preserves carotenoid content while reducing oil uptake versus conventional atmospheric frying. Sweet potato dominates product type volume due to established consumer familiarity and lower raw-material cost volatility. Resealable pouch packaging captures margin pools through premium positioning and portion-control convenience. Health food stores represent the fastest-growing distribution channel as specialty retailers consolidate local vegan and gluten-free demand.
FDA nutrition-labeling rules and USDA organic certification requirements shape formulation transparency and ingredient sourcing across the United States. EU EFSA acrylamide benchmarks and REACH-compliant packaging mandates constrain frying chemistry and material selection for European market access. Stakeholders must monitor clean-label certification costs against private-label encroachment from vertically integrated snack manufacturers.
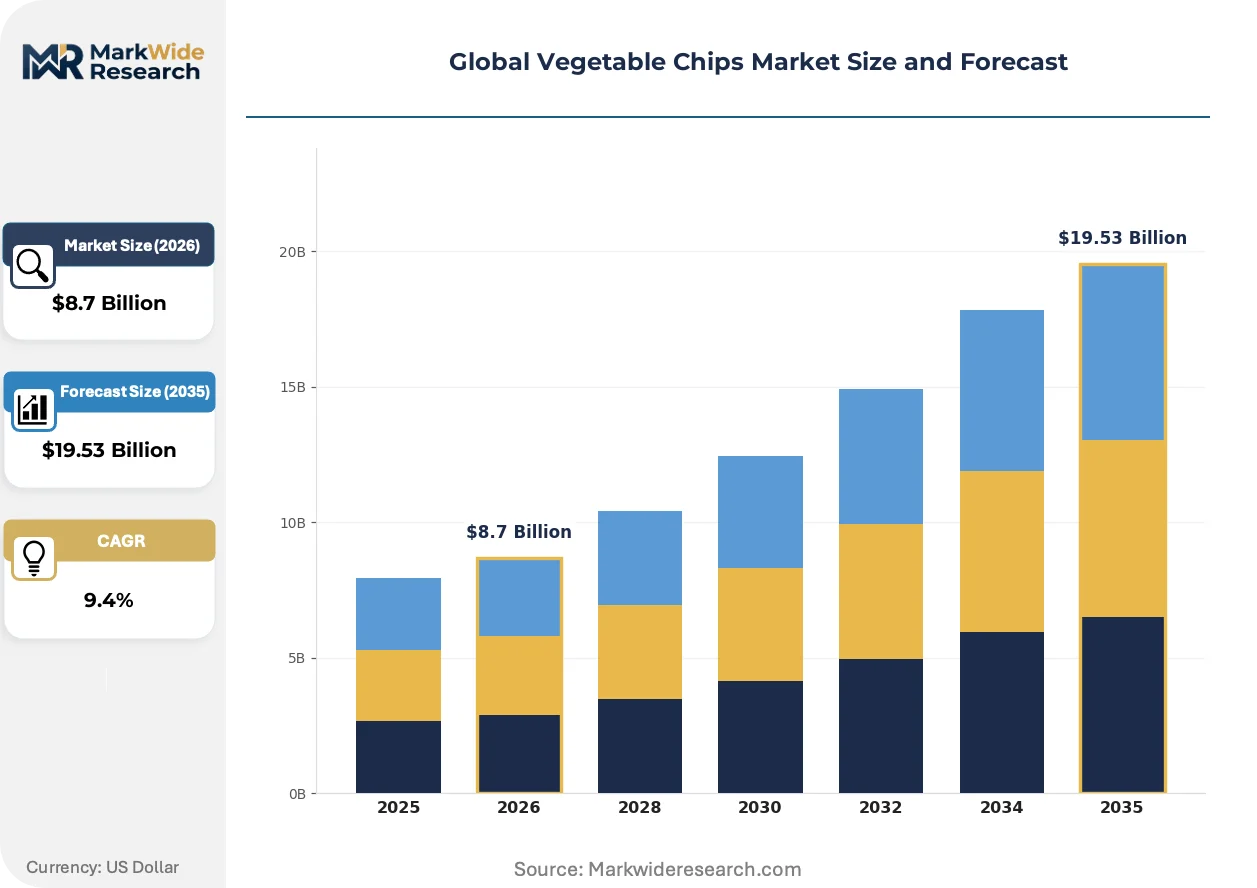
Market Dynamics
EU EFSA acrylamide benchmarks are forcing manufacturers to abandon conventional atmospheric frying, triggering capital-intensive process redesigns that favor vacuum-frying adopters with cleaner thermal profiles.
Growth Catalysts
- USDA Organic Certification:Clean-label positioning in US health-food channels commands shelf-space premiums as retailers consolidate vegan and gluten-free assortment.
- Germany:Organic retail concentration creates demand pull for certified vegetable chips through dedicated produce and specialty snack aisles.
- Vacuum Frying Technology:Sub-atmospheric pressure processing preserves carotenoid content while reducing oil uptake, satisfying reformulation pressures from EU EFSA acrylamide limits.
Market Restraints
- Sweet Potato Raw Material Volatility:Crop yield fluctuations in major producing regions compress margin predictability for volume-dependent manufacturers.
- REACH-Compliant Packaging Mandates:EU material selection constraints increase unit packaging costs and limit supplier pools for European market access.
- Conventional Potato Chip Substitution:Established salty snack alternatives retain price advantage and consumer habit formation in mass-market retail.
Strategic Opportunities
- India:FSSAI-regulated processed food sector expansion creates white space for clean-label vegetable chip introduction through modern trade and e-grocery channels.
- Raw-Dehydrated Subsegment:Minimal-processing claims attract premium positioning in specialty retail, with resealable pouch formats capturing margin pools through convenience.
- Health Food Store Channel:Consolidation of local vegan and gluten-free demand in specialty retail represents underexploited distribution architecture.
Industry Challenges
- Clean-Label Certification Timeline:USDA organic and EU organic logo compliance extends product development cycles and requires traceable ingredient sourcing systems.
- Frying Process Reconfiguration:Vacuum-frying equipment capex demands strain mid-capitalization manufacturers transitioning from atmospheric systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vegetable Chips Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Potato, Beetroot, Kale, Carrot Packaging Type: Bag, Box, Transparent Pack, Resealable Pouch Distribution Channel: Retail Stores, Online Retail, Supermarkets, Health Food Stores Customer Type: Health-Conscious Consumers, Snack Enthusiasts, Vegans, Gluten-Free Shoppers |
| Companies Covered | Rhythm Superfoods, Snak King, PepsiCo, Velocity Snack Brands, Jackson's Food Company, The Hain Celestial Group, Made In Nature, Fujian Hanwei Foods Co., Ltd., Calbee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vegetable Chips Market Strategic Shifts
Processing technology and regulatory chemistry are redefining competitive advantage in vegetable chip manufacturing, with thermal innovation and material science converging to reshape product positioning.
Vacuum frying at sub-atmospheric pressure is decomposing the conventional atmospheric-frying cost structure by enabling oil reduction and nutrient retention simultaneously. Premium and specialty manufacturers are adopting these systems to meet EU EFSA acrylamide benchmarks without sacrificing sensory attributes. The technology is compressing the traditional trade-off between health claims and processing economics.
EU EFSA acrylamide benchmarks are mandating reformulation across European manufacturing footprints, compelling thermal process redesign and raw-material selection changes. Manufacturers must document acrylamide mitigation measures through supply chain transparency and frying-parameter controls. Sweet potato and root vegetable chip categories face the steepest compliance curves due to higher natural reducing-sugar content.
Resealable pouch packaging is capturing consumer preference through portion-control convenience and premium shelf presence in specialty retail. Health food stores and organic grocers are displacing conventional supermarket snack aisles as the primary channel for clean-label vegetable chip discovery. Germany and the United States exhibit the strongest channel migration, with resealable formats commanding measurable price premiums over standard bag configurations.
Global Vegetable Chips Market Segmentation
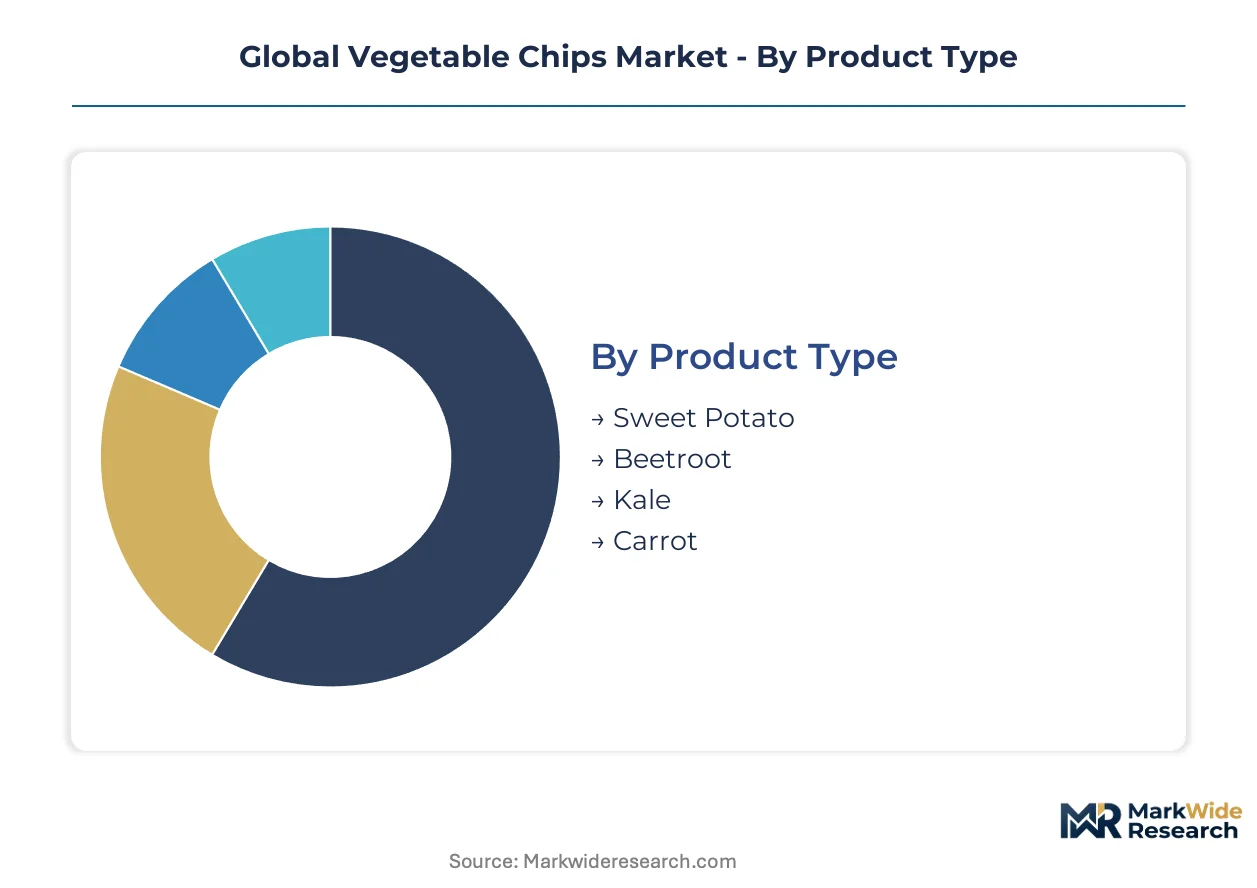
Segmentation in the vegetable chips market reveals how health claims, packaging convenience, and channel access create distinct competitive battlegrounds. Manufacturers must align formulation, format, and placement decisions with the specific purchasing logic of each consumer tribe.
Product Type:
EU EFSA acrylamide benchmarks differentiate root vegetables by natural reducing-sugar content, forcing reformulation intensity that varies sharply across varieties.
- Sweet Potato:Established consumer familiarity and lower raw-material cost volatility anchor volume leadership. Demand concentrates in United States mass retail channels where conventional salty snack substitution pressure is weakest.
- Beetroot:Higher natural sugar content elevates acrylamide formation risk during atmospheric frying, advantaging vacuum-frying adopters. Germany's organic retail sector pulls premium positioning through color differentiation and antioxidant marketing claims.
- Kale:Leafy-green dehydration preserves chlorophyll and sulfur compounds for minimal-processing positioning. Specialty health-food channels in the United States favor this segment for vegan protein halo effects.
- Carrot:Beta-carotene retention through sub-atmospheric pressure processing supports clean-label certification pathways. Carrot chips gain traction in Indian modern trade as FSSAI-regulated processed food expansion creates white-space opportunity.
Established volume favors sweet potato; emerging adoption favors beetroot.
Packaging Type:
Cost tier stratification separates commodity formats from premium convenience solutions that capture measurable shelf-space premiums.
- Resealable Pouch:Zip-lock mechanisms and multi-layer barrier films extend shelf stability while enabling portion-control marketing. Health food stores in Germany and the United States command price premiums for this format against standard bag configurations.
- Bag:Single-use polypropylene structures dominate mass-market velocity through lower unit economics. Conventional supermarket snack aisles in the United States retain this format for price-sensitive sweet potato chip volumes.
- Box:Rigid paperboard protects fragile leaf-based chips during transit and retail handling. Kale chip specialists favor this format for premium gifting occasions in North American specialty retail.
- Transparent Pack:Visual product exposure supports impulse purchase conversion in open-shelf environments. Asian convenience retail channels utilize this format for single-serve beetroot and carrot chip trial sizes.
Margin capture concentrates in resealable pouch; volume throughput depends on bag.
Distribution Channel:
Channel migration patterns reflect where clean-label discovery and habitual repurchase occur across divergent retail architectures.
- Health Food Stores:Consolidated vegan and gluten-free assortment creates curated discovery environments. United States specialty retailers expand shelf space for USDA organic certified lines faster than conventional supermarket resets.
- Supermarkets:Mass-market velocity depends on slotting fee negotiations and promotional calendar alignment. Sweet potato chip placement in German conventional retail faces pressure from private-label encroachment.
- Online Retail:Direct-to-consumer subscription models enable trial packs and flavor variety bundles. Indian e-grocery platforms create entry pathways for international clean-label brands navigating FSSAI import requirements.
- Retail Stores:Convenience-oriented independent outlets favor single-serve transparent packs for immediate consumption. Carrot and kale chips penetrate this channel through local distributor relationships in fragmented United States geography.
Fastest channel expansion occurs in health food stores; volume concentration remains with supermarkets.
Customer Type:
Purchasing motivation separates constraint-driven buyers from aspiration-driven buyers with divergent price elasticity profiles.
- Health-Conscious Consumers:Nutrient-density claims and oil-reduction specifications drive purchase decisions. United States demand for vacuum-fried sweet potato chips concentrates in this segment through clean-label certification recognition.
- Vegans:Animal-product-free verification requirements extend to flavoring systems and processing aids. German organic retail channels prioritize this segment through dedicated produce-adjacent placement.
- Gluten-Free Shoppers:Celiac-safe manufacturing protocols and cross-contamination controls command audit documentation. Health food stores consolidate this demand alongside other allergen-managed snack categories.
- Snack Enthusiasts:Sensory experience and flavor novelty override health positioning for habitual purchase. Mass-market sweet potato chip velocity in United States supermarkets depends on this segment's price tolerance.
Certification premiums align with health-conscious consumers and vegans; volume scale requires snack enthusiast conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in North American and European processing hubs where clean-label certification infrastructure and retail channel density create competitive moats. Manufacturers locate near organic raw-material sourcing regions and health-food retail corridors to minimize logistics costs and maximize shelf-space access.
United States
Health-conscious consumers in coastal metropolitan markets drive demand for USDA organic certified vegetable chips through specialty retail channels. FDA nutrition-labeling rules mandate transparent ingredient disclosure and serving-size standardization. California's Central Valley organic farming clusters supply sweet potato and kale raw materials to vacuum-frying processors in Los Angeles and San Francisco Bay Area industrial zones.
Germany
Organic retail sector concentration in Berlin, Hamburg, and Munich creates dedicated shelf-space for certified vegetable chip assortments. EU EFSA acrylamide benchmarks force atmospheric-frying manufacturers to reformulate thermal processes or exit the market. Bavaria's food technology research institutes collaborate with processors on vacuum-frying equipment optimization for root vegetable applications.
India
Rising middle-class health awareness in Mumbai, Delhi, and Bangalore generates trial demand for clean-label snacks through modern trade and e-grocery platforms. FSSAI processed food regulations establish import and manufacturing standards for international brand entry. Maharashtra's Nashik region carrot farming cooperatives supply raw materials to emerging domestic chip processors targeting urban premium retail.
Japan
Functional food positioning and portion-control packaging preferences shape consumer acceptance of vegetable chips in Tokyo, Osaka, and Nagoya metropolitan markets. METI food manufacturing standards govern additive use and processing aid documentation. Kyushu region sweet potato cultivation supports domestic vacuum-fried chip production for convenience store and premium gift channels.
United Kingdom
Free-from and plant-based snacking trends in London and Southeast England consolidate demand for vegan-certified vegetable chips. Food Standards Agency allergen labeling requirements and post-EU regulatory divergence create compliance complexity for continental suppliers. Midlands manufacturing corridor hosts co-packing facilities serving private-label vegetable chip programs for major supermarket chains.
Global Vegetable Chips Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vacuum-frying equipment mastery separating premium positioning from mass-market volume plays. The market exhibits tiered concentration: multinational snack conglomerates dominate conventional retail velocity, while specialist organic processors capture health-food channel margins. Three archetypes define competitive structure: diversified food majors with retail shelf-space leverage, organic-certified specialists with traceable supply chains, and raw-dehydrated minimal-processing purists. Dominant competitive moves include strategic partnerships with organic farming cooperatives and geographic expansion into underpenetrated Asian markets.
Within the diversified-major tier, PepsiCo and The Hain Celestial Group exemplify divergent strategic positioning—one leveraging scale economics across conventional channels, the other anchoring organic certification premiums in specialty retail. Rhythm Superfoods occupies a position within the minimal-processing specialist archetype, representing raw-dehydrated technology adoption for nutrient-retention claims. These three companies collectively illustrate how certification strategy and processing technology selection determine channel access and margin structure across the competitive landscape.
| Leading Market Players |
|---|
| Rhythm Superfoods |
| Snak King |
| PepsiCo |
| Velocity Snack Brands |
| Jackson's Food Company |
| The Hain Celestial Group |
| Made In Nature |
| Fujian Hanwei Foods Co., Ltd. |
| Calbee |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between vacuum-frying processors and California organic farming cooperatives lock in both sweet potato supply access and price visibility across the analysis window. These arrangements insulate specialty manufacturers from raw-material cost volatility while compressing margin predictability for spot-market dependent competitors.
Pricing Analysis
EU EFSA acrylamide benchmarks dictate the pricing tier structure by forcing atmospheric-frying manufacturers into costly reformulation or market exit. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-fried organic SKUs from conventional mass-market bags. Pricing pressure stems from REACH-compliant packaging mandates increasing unit costs for European market access. Snack enthusiasts in United States supermarkets exhibit highest price sensitivity; health-conscious consumers in specialty channels accept certification premiums.
Supply Chain Analysis
Inventory cycles for organic root vegetables extend lead times beyond conventional potato chip supply chains. Raw material sourcing concentrates in United States, Germany, and India, with California's Central Valley, Bavaria's farming clusters, and Maharashtra's Nashik region anchoring regional processing hubs. Manufacturing draws from organic sweet potato, beetroot, and kale inputs with strict traceability documentation. Single-source vulnerability in vacuum-frying equipment suppliers strains mid-capitalization manufacturers. Distribution runs through health food stores and organic grocers for premium tiers, conventional supermarkets for volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. EU EFSA compliance costs and USDA organic certification timelines create switching costs that protect incumbent positions against price-based challengers.
For Market Incumbents: Secure vacuum-frying equipment capacity reservations ahead of mid-cap competitors facing capex constraints. Deepen backward integration into organic farming cooperatives in California and Bavaria to defend margin position against private-label encroachment from vertically integrated snack manufacturers. For New Entrants and Emerging Players: Anchor in India's FSSAI-regulated modern trade and e-grocery channels where clean-label vegetable chips remain underpenetrated. Target raw-dehydrated kale and carrot subsegments through minimal-processing claims. Deploy direct-to-consumer subscription models with trial packs to bypass slotting fee barriers in conventional retail. For Investors and Strategic Acquirers: Capital is best deployed toward vacuum-frying technology specialists with established EU EFSA compliance documentation and health-food store shelf-space agreements. Long-term viability hinges on regulatory entrenchment rather than brand equity alone. Watch for FSSAI import standard harmonization as inflection indicator for Indian market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Frying Equipment Deployment | EU EFSA acrylamide compliance enables premium positioning in German organic retail. |
| USDA Organic Certification Investment | Clean-label recognition commands shelf-space premiums in United States health food stores. |
| Direct-to-Consumer Channel Launch | Subscription models bypass slotting fees and build health-conscious consumer loyalty. |
| Raw-Dehydrated Product Line Extension | Minimal-processing claims capture margin pools in specialty vegan and gluten-free segments. |
| Indian Market Entry Partnership | FSSAI-compliant local manufacturing or import pathways unlock modern trade distribution. |
Study Parameters
Desk research of trade databases, customs records, and regulatory filings preceded structured interviews with vacuum-frying equipment manufacturers, organic farming cooperative managers, health food store category buyers, and FSSAI compliance consultants. Primary fieldwork with processors in California, Bavaria, and Maharashtra validated secondary data on capacity utilization and raw-material sourcing patterns. Bottom-up volume modeling triangulated against top-down retail audit estimates.
Variance decomposition across product type, packaging format, distribution channel, and certification tier informed projection mechanics. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated EU EFSA enforcement trajectory, USDA organic acreage expansion, and FSSAI processed food sector growth assumptions.
Decision-makers should treat outputs as directional under sustained clean-label consumer preference and regulatory enforcement continuity; material deviation in acrylamide benchmark revisions or organic certification cost inflation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Low Fat Granola Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Kids Snacks Market
Snacks
Granola Market
Snacks
Indonesia Snack Bar Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Europe Cereal Bar Market
Snacks
Extruded Snacks Market
Snacks
South America Energy Bar Market
Snacks
Snack Bar Market
Snacks
Europe Snacks Food Market
Snacks
Energy Balls Market
Snacks
Forti Flakes Market
Snacks
South America Snack Bar Market
Snacks
North America Pretzel Market