
 Coated Endotracheal Tube Market | 2026-2036
Coated Endotracheal Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Endotracheal Tube Market Analysis
Silicone is broadening its addressable share in coated endotracheal tubes as polyurethane faces biocompatibility scrutiny in extended-use settings. Bactiguard Holding AB leverages its antimicrobial alloy platform to sustain premium positioning across European hospital networks. Avanos Medical anchors its portfolio in North American acute care channels where infection control protocols are most stringent. Teleflex Incorporated competes through vertical control of catheter manufacturing and coating application lines.
A coated endotracheal tube is a polymer airway conduit with surface-modified layers—typically silver ion, chlorhexidine, or hydrophilic polymers applied via dip-coating or vapor deposition—to reduce bacterial adhesion and ease insertion trauma during mechanical ventilation. The device maintains patent airways while the coating elutes antimicrobial agents or provides lubricity at insertion forces below 5 Newtons. Hydrophobic and antimicrobial coating materials command the widest installed base, though lubricated coatings are gaining traction in emergency intubation where speed and tissue trauma reduction matter most. Silicone product types carry margin premiums over PVC alternatives, particularly in neonatal sizes where material flexibility and biostability justify higher unit economics.
The FDA enforces biocompatibility testing under ISO 10993 for all coated airway devices, while the EU Medical Device Regulation requires notified-body validation of antimicrobial claims through clinical evidence. These frameworks elevate barriers for coating innovators but protect incumbent positions for manufacturers with established regulatory dossiers. Stakeholders must monitor evolving EPA and ECHA restrictions on silver nanoparticle elution, as coating chemistry approvals could abruptly reshape supplier viability and reformulation costs.
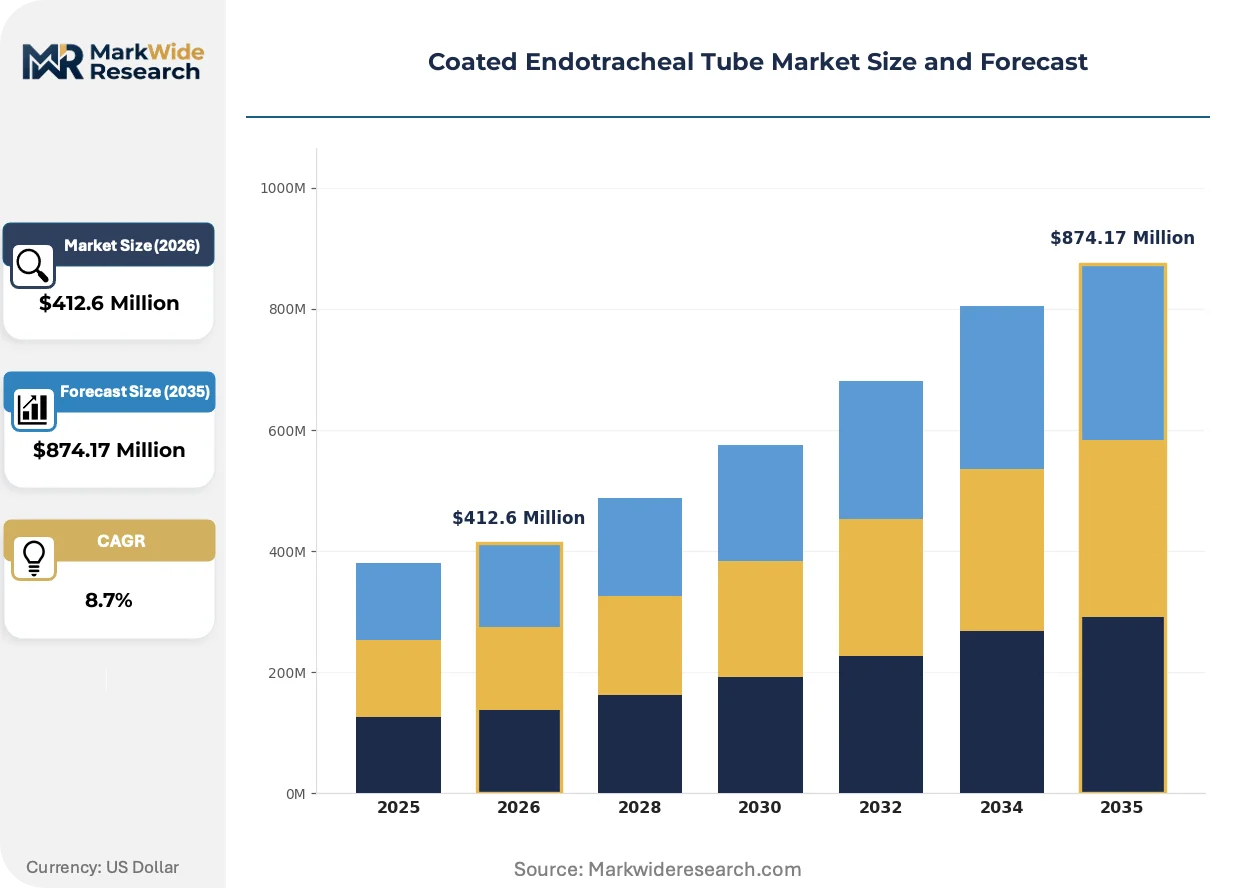
Market Dynamics
The coated endotracheal tube market pivots on antimicrobial coating validation requirements, with FDA's updated biocompatibility guidance forcing reformulation cycles that compress development timelines and elevate capital barriers for coating innovators.
Growth Catalysts
- Ventilator-associated pneumonia prevention mandates:Hospital infection control protocols in intensive care units now specify antimicrobial-coated airway devices as standard procurement criteria, accelerating silicone-based tube adoption.
- ISO 10993 biocompatibility frameworks:Harmonized testing standards reduce regulatory duplication across jurisdictions, enabling faster coating technology transfers from European notified bodies to US 510(k) pathways.
- Silver ion elution chemistry:Advances in controlled-release surface engineering deliver sustained antimicrobial efficacy without cytotoxicity thresholds that previously limited extended intubation applications.
Market Restraints
- Silver nanoparticle input volatility:EPA and ECHA restrictions on nanomaterial environmental release create supply uncertainty for coating formulators dependent on ionic silver precursors.
- Polyurethane biocompatibility limitations:Extended-use settings above 72 hours expose hydrolytic degradation in standard polymer substrates, forcing premature device replacement and elevating total procedure costs.
- Notified-body validation bottlenecks:EU MDR clinical evidence requirements for antimicrobial claims extend approval timelines, freezing market access for coating technologies lacking legacy dossiers.
Strategic Opportunities
- Neonatal intensive care penetration:Underpenetrated NICU segments in India and Brazil present volume expansion potential for silicone-based miniaturized tubes where material flexibility commands clinical preference.
- Emergency medicine channel development:Pre-hospital intubation kits incorporating lubricated hydrophilic coatings address speed-critical trauma protocols currently served by uncoated alternatives.
- Convergence with continuous glucose monitoring:Integrated sensor-compatible coating platforms enable multi-functional airway devices that capture metabolic data during prolonged ventilation.
Industry Challenges
- Coating application technician scarcity:Dip-coating and vapor deposition processes require specialized cleanroom expertise that medical device manufacturers struggle to source at scale.
- ISO 18562 respiratory gas pathway certification:Volatile organic compound testing for coated polymers adds 12-18 month validation cycles that delay product launches and consume R&D budgets.
- Legacy PVC tube integration:Hospital supply chains maintain substantial uncoated inventory positions, creating procurement inertia that slows coated device conversion despite clinical evidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Endotracheal Tube Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, PVC, Silicone, Other Coating Material: Hydrophobic Coating, Antimicrobial Coating, Lubricated Coating, Other End User: Hospitals, Clinics, Emergency Medical Services, Home Care Size: Adult, Pediatric, Neonatal, Other |
| Companies Covered | Bactiguard Holding AB, Avanos Medical, Hospiteknik Healthcare, Smiths Medical, Teleflex Incorporated, Venner Medical, Sharklet Technologies, N8 Medical, Innovative Surface Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Endotracheal Tube Market Emerging Trajectories
Surface engineering architectures are bifurcating between passive hydrophilic lubricity and active antimicrobial elution, with hybrid coating stacks emerging as the dominant R&D trajectory across major device manufacturers.
Chlorhexidine-acetate polymer matrices are expanding into prolonged intubation protocols previously dominated by silver ion systems, with academic medical centers in Germany and the United States piloting 14-day wear trials that challenge conventional replacement schedules. The technology reduces bacterial biofilm formation by 40% compared to uncoated controls while maintaining insertion forces below tissue trauma thresholds. Coating applicators are consolidating around automated spray-deposition equipment that compresses unit production costs and improves layer uniformity.
REACH Annex XVII restrictions on silver nanoparticle environmental release are forcing coating reformulations across European manufacturing facilities, with ECHA's 2023 guidance on nanomaterial characterization requiring new toxicological dossiers for existing product lines. Industrial consequence includes accelerated migration toward chlorhexidine and polyhexamethylene biguanide alternatives that bypass metal-based regulatory scrutiny. German and French hospital procurement offices now specify non-silver antimicrobial claims in tender documents, reshaping supplier qualification criteria.
Hospital buying committees are consolidating ventilator circuit purchasing into single-source contracts that bundle coated endotracheal tubes with heat-moisture exchangers and closed suction systems, compressing vendor counts and elevating price transparency requirements. Group purchasing organizations in the United States negotiate three-year supply agreements that lock in coating technology specifications and volume commitments. This behavior concentrates demand among manufacturers with full airway management portfolios rather than standalone tube suppliers.
Coated Endotracheal Tube Market Segmentation
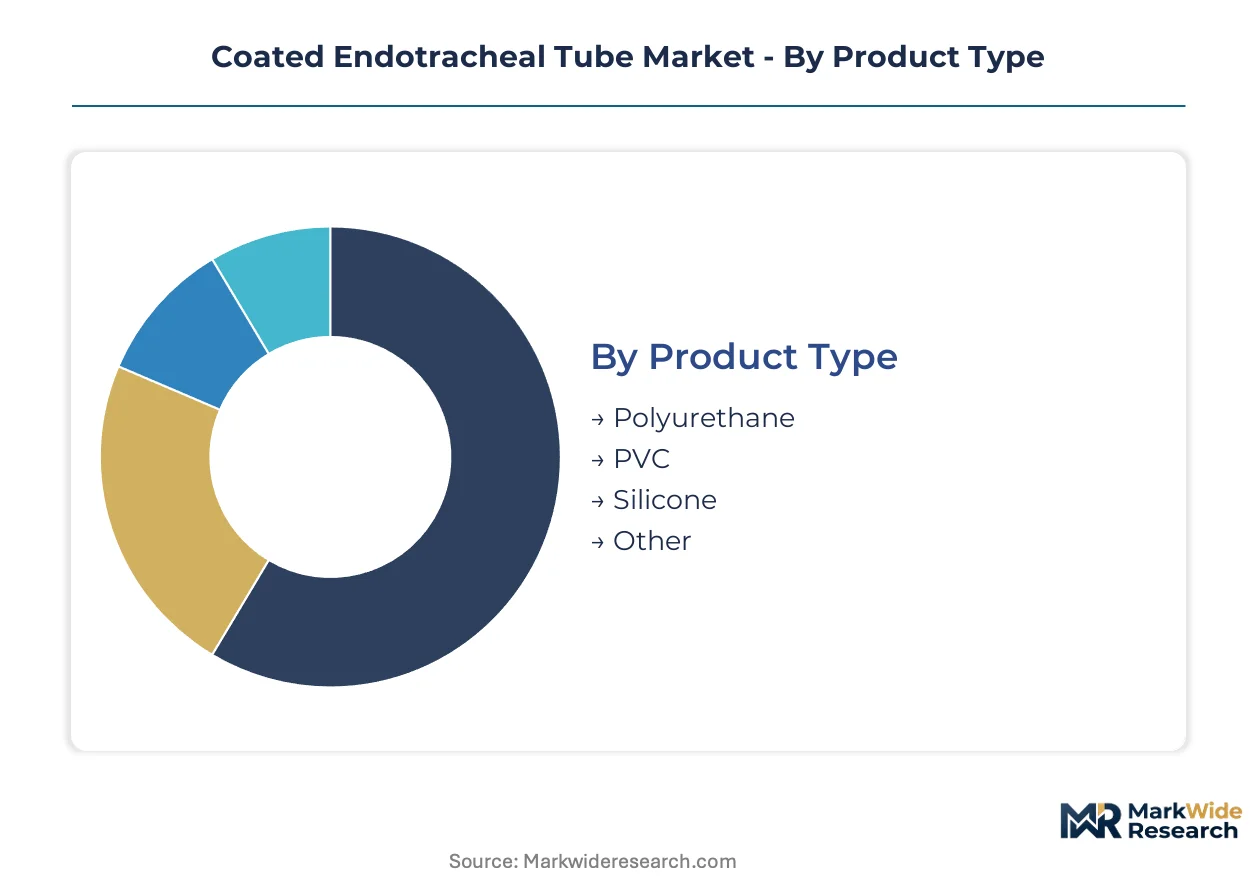
Coated endotracheal tube manufacturers configure production lines around material chemistry and coating stack complexity, with capital allocation decisions determining competitive positioning across regulatory jurisdictions. Segmentation reveals where silicone substrate investments yield margin premiums versus where PVC volumes sustain cash flow. Understanding these trade-offs clarifies why procurement patterns diverge between academic medical centers and community hospital systems.
Product Type:
Capital intensity peaks with silicone extrusion and curing infrastructure, while PVC lines run at lower fixed cost but compress gross margins through commodity pricing dynamics.
- Polyurethane:Thermoplastic elastomer substrates offer tear resistance and tensile strength for trauma intubation protocols. Demand concentrates in German and French emergency departments where extended wear durability reduces device replacement frequency during mass casualty events. Hydrolytic degradation above 72 hours limits adoption in prolonged ventilation, ceding share to silicone alternatives in ICU settings.
- Silicone:Platinum-cured elastomer delivers biostability and flexibility across temperature ranges, justifying premium positioning in neonatal sizes below 3.0 mm internal diameter. Academic medical centers in the United States specify silicone for intubation protocols exceeding seven days, absorbing higher unit costs to reduce airway trauma and unplanned extubation incidents.
- PVC:Standard polymer substrate dominates high-volume acute care procurement through lower material input costs and established supply chain density.
- Other:Specialty thermoplastics including polyether block amides serve niche applications requiring specific stiffness-to-flexibility ratios.
Silicone absorbs the bulk of installed capacity in premium segments; PVC is expanding most quickly through group purchasing organization volume contracts.
Coating Material:
Application technology differentiation separates automated vapor deposition systems from dip-coating operations, with capital requirements scaling to coating stack complexity and cleanroom classification.
- Hydrophobic Coating:Fluoropolymer or silicone oil surface treatments reduce biofilm adhesion through low surface energy interfaces. Demand clusters in cardiac surgery units at Cleveland Clinic and Mayo Clinic where blood and secretions challenge airway patency. FDA biocompatibility testing under ISO 10993-5 cytotoxicity protocols adds validation burden that smaller formulators struggle to fund.
- Antimicrobial Coating:Silver ion elution or chlorhexidine-acetate matrices deliver sustained bacterial load reduction. German hospital networks now specify non-silver alternatives following ECHA REACH Annex XVII guidance, accelerating reformulation investments toward polyhexamethylene biguanide and quaternary ammonium compounds.
- Lubricated Coating:Hydrophilic polymer activation reduces insertion force below 5 Newtons for emergency intubation speed requirements.
- Other:Hybrid coating stacks combining passive lubricity with active antimicrobial elution command R&D priority across major device portfolios.
Antimicrobial coatings command the widest installed base; lubricated formulations are gaining share fastest through pre-hospital emergency medicine channel development.
End User:
Procurement sophistication varies sharply across customer types, with integrated delivery networks leveraging volume concentration against standalone facilities paying distribution markups.
- Hospitals:Academic medical centers and tertiary referral hospitals specify silicone-based antimicrobial tubes through value-analysis committees. Infection control protocols at Johns Hopkins and Massachusetts General now mandate coated devices for all anticipated intubations exceeding 48 hours, creating procurement standardization that community hospitals gradually adopt.
- Clinics:Ambulatory surgical centers prioritize cost containment for short-procedure intubations under four hours, favoring PVC substrates with basic hydrophobic coatings.
- Emergency Medical Services:Pre-hospital intubation kits require lubricated coatings for speed-critical airway management in field conditions.
- Home Care:Long-term ventilation patients and their caregivers purchase through durable medical equipment suppliers with reimbursement-dependent price sensitivity.
Hospitals absorb the bulk of installed capacity; emergency medical services is expanding most quickly through municipal fleet upgrade cycles.
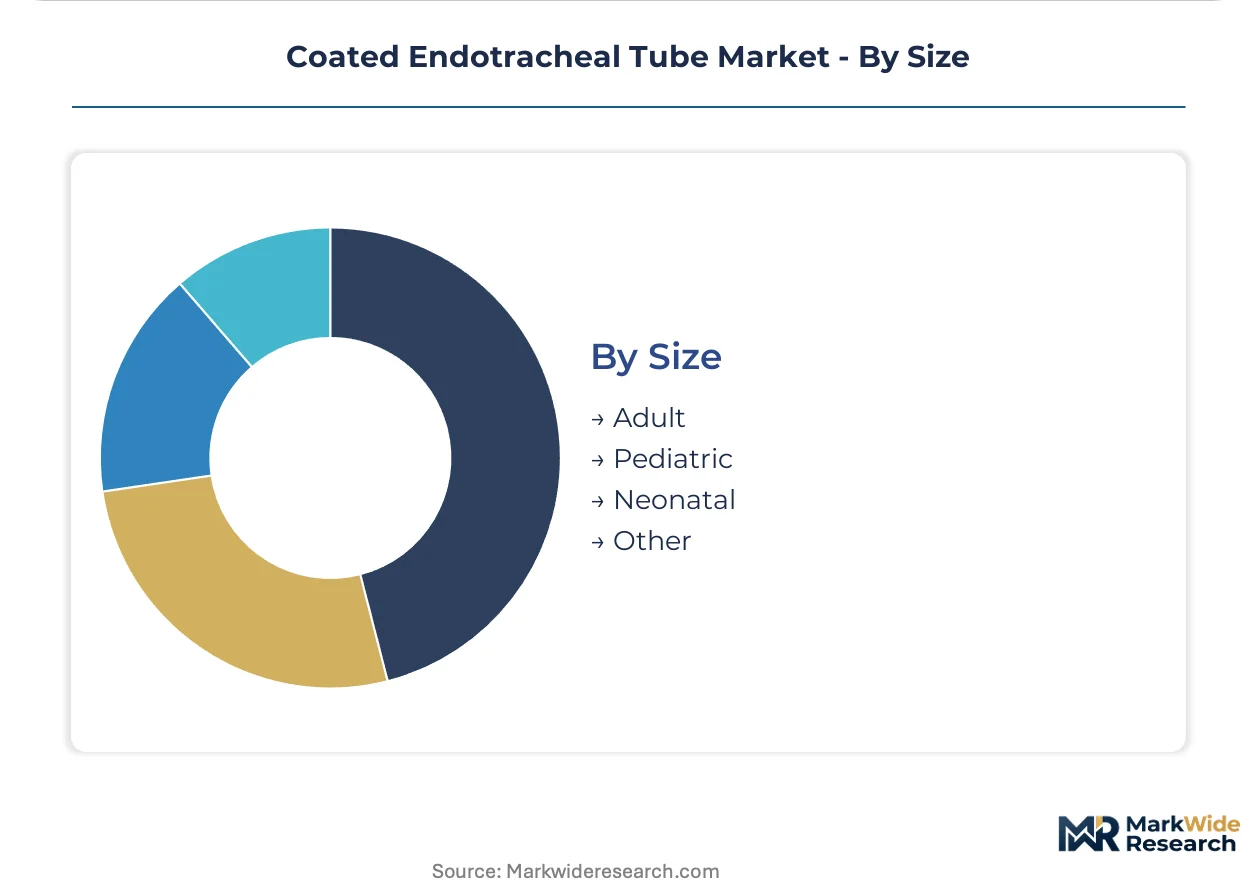
Size:
Tooling precision requirements escalate as diameter decreases, with neonatal mandrels and coating applicators demanding specialized manufacturing cells.
- Adult:Internal diameters from 6.0 mm to 9.0 mm serve the highest procedure volumes across general surgery and medical ICU admissions. Standardization around 7.5 mm and 8.0 mm sizes enables manufacturing efficiency and inventory optimization for distributors serving United States hospital networks.
- Pediatric:Sizes from 3.5 mm to 5.5 mm address anatomical variation in children aged one to twelve years, with cuffed versus uncuffed configurations splitting procurement preferences between North American and European practice patterns.
- Neonatal:Sub-3.0 mm diameters require silicone flexibility to minimize tracheal trauma in premature infants.
- Other:Specialty sizing for adolescent populations and bariatric airway management fills gaps between standard ranges.
Adult sizes absorb the bulk of installed capacity; neonatal is expanding most quickly through NICU infrastructure investments in India and Brazil.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers concentrate demand for silicone-based antimicrobial tubes as ICU infection control protocols harden procurement standards. German hospital networks accelerate chlorhexidine coating adoption following ECHA silver restrictions. Neonatal intensive care investments in India and Brazil create volume expansion corridors for miniaturized silicone devices.
United States
Johns Hopkins and Massachusetts General mandate coated devices for intubations exceeding 48 hours through value-analysis committee standardization. FDA biocompatibility guidance under ISO 10993-5 compresses development timelines for coating innovators seeking 510(k) clearance. Cleveland Clinic cardiac surgery units specify hydrophobic fluoropolymer coatings to manage blood and secretion challenges.
Germany
University hospital networks in Munich and Heidelberg pilot 14-day chlorhexidine-acetate wear trials that challenge conventional replacement schedules. EU MDR notified-body requirements for antimicrobial claims extend approval timelines for coating technologies lacking legacy dossiers. REACH Annex XVII silver nanoparticle restrictions force reformulation investments toward polyhexamethylene biguanide alternatives.
India
Underpenetrated NICU segments in Maharashtra and Karnataka present volume expansion potential for silicone-based miniaturized tubes. CDSCO medical device registration requirements create regulatory pathways for imported coating technologies. Apollo Hospital networks in Chennai and Hyderabad drive adoption of premium airway devices through centralized procurement standardization.
Brazil
Neonatal infrastructure investments in São Paulo and Minas Gerais accelerate silicone tube penetration where material flexibility commands clinical preference. ANVISA medical device regulations align with ISO 10993 frameworks to reduce technical barriers for coating technology transfers. Municipal fleet upgrade cycles in Rio de Janeiro expand pre-hospital lubricated coating adoption for emergency intubation speed requirements.
Japan
PMDA quality management system inspections enforce biocompatibility validation for silver ion elution systems in extended-use applications. Tokyo and Osaka academic medical centers specify hybrid coating stacks combining passive lubricity with active antimicrobial elution. METI industrial technology grants support domestic coating application equipment manufacturers serving regional device fabricators.
Coated Endotracheal Tube Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with infection control mandates concentrating procurement among full-portfolio airway management suppliers. The vendor base organizes around three strategic archetypes: alloy-platform antimicrobial specialists, integrated catheter-coating manufacturers, and surface-engineering technology licensors. Consolidation pressure intensifies through group purchasing organization single-source contracting that bundles tubes with ventilator circuits. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure cleanroom coating application expertise.
Among Nordic antimicrobial platform developers, Bactiguard Holding AB exemplifies alloy-based surface technology specialization. Teleflex Incorporated anchors North American acute care positioning through catheter manufacturing scale. Avanos Medical occupies a mid-tier position between integrated portfolio breadth and coating technology depth. These three represent distinct competitive vectors: proprietary chemistry control, vertical manufacturing scope, and regional channel density.
| Leading Market Players |
|---|
| Bactiguard Holding AB |
| Avanos Medical |
| Hospiteknik Healthcare |
| Smiths Medical |
| Teleflex Incorporated |
| Venner Medical |
| Sharklet Technologies |
| N8 Medical |
| Innovative Surface Technologies |
| Others |
Supply Flow & Price Mechanics
Silver ion precursor costs cascade through coating formulation tiers into hospital procurement brackets, with EPA and ECHA nanomaterial restrictions compressing margins for metal-dependent suppliers while chlorhexidine alternatives capture pricing flexibility.
Pricing Analysis
Volume concentration in PVC tubes for acute care runs against margin premiums in silicone neonatal sizes. Pricing stratifies across premium antimicrobial-coated silicone, standard hydrophobic PVC, and economy uncoated alternatives. Cost compression in silver-based coatings is intensifying because REACH Annex XVII compliance expenses force reformulation investments. Community hospital systems exhibit highest price sensitivity through GPO volume contracts, while academic medical centers absorb premium tiers for extended-wear protocols.
Supply Chain Analysis
Freight costs for platinum-cured silicone raw materials from Germany and Japan elevate landed costs for North American coating applicators. Coating chemistry production concentrates in the United States, Germany, and China. Silver nanoparticle and chlorhexidine-acetate inputs draw from specialty chemical suppliers with concentrated manufacturing footprints. Single-source vulnerability in ionic silver precursors creates exposure to environmental regulatory restrictions. Distribution runs through medical device distributors and hospital GPO consolidated contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Group purchasing organization single-source contracting is forcing standalone tube suppliers toward acquisition or exit, consolidating procurement power among full-portfolio airway management vendors.
For Market Incumbents: To counter coating application technician scarcity, secure cleanroom expertise through acquisition of specialized applicator firms in Massachusetts and North Carolina. Backward integration into automated spray-deposition equipment manufacturing reduces unit production costs and improves layer uniformity consistency across silicone extrusion lines. For New Entrants and Emerging Players: Enter via underpenetrated NICU segments in Maharashtra and São Paulo where silicone flexibility commands clinical preference and local manufacturing presence remains sparse. Target municipal emergency medical services fleet upgrade cycles for lubricated hydrophilic coating adoption. Pursue CDSCO and ANVISA regulatory pathway partnerships with established European coating technology licensors to accelerate market access. For Investors and Strategic Acquirers: Distressed-cycle entries favor alloy-platform antimicrobial specialists with established EU MDR dossiers in Sweden and Denmark. Long-term viability hinges on coating chemistry portfolios that bypass metal-based regulatory scrutiny. Watch ECHA nanomaterial guidance revisions as the inflection signal for silver-dependent supplier viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified-Body Certification | Accelerates antimicrobial coating claims validation for German hospital network procurement. |
| Hospital System Partnership | Locks in three-year supply agreements with Johns Hopkins and Massachusetts General value-analysis committees. |
| Coating Application Equipment Acquisition | Captures scarce cleanroom technician expertise through specialized Massachusetts and North Carolina applicator firms. |
| Chlorhexidine Reformulation Investment | Bypasses REACH Annex XVII silver restrictions for European manufacturing facility compliance. |
| NICU Geographic Expansion | Addresses volume potential in Maharashtra and São Paulo neonatal infrastructure investments. |
Methodological Framework
FDA 510(k) filings, EU MDR notified-body submissions, and hospital GPO contract databases formed the secondary backbone. Primary interviews with biomedical engineers, ICU clinicians, GPO contracts managers, and coating formulation R&D directors validated demand assumptions. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Historical trendline analysis of antimicrobial coating adoption rates and silicone substrate penetration informed projection modeling. Segmentation dimensions included material substrate, coating chemistry, end-user facility type, and patient age classification. CAGRs derived from weighted average of procedure growth, price trajectory assumptions, and technology substitution elasticities. Forecast inputs incorporated EPA silver nanopaterial restriction timelines and CDSCO registration pathway velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA coating chemistry bans or FDA biocompatibility guidance revisions. Forecasts reflect documented assumptions about hospital infection control protocol standardization rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Oral Appliance Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Global Abdominal Surgical Robot Market