
 Wearable Medical Technology Market | 2026-2036
Wearable Medical Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Medical Technology Market Outlook
Silicon photonics is rebalancing component economics in wearable biosensors by displacing traditional electrode materials in continuous glucose monitoring patches. Dexcom Inc. leverages captive manufacturing of applicator-integrated sensors to sustain gross margins while scaling unit volume. Abbott anchors its FreeStyle Libre ecosystem through vertical control over factory-calibrated sensor filament production. Samsung Electronics competes via multi-parameter health platforms that integrate blood pressure estimation with electrocardiography in wrist-worn form factors.
Wearable medical technology encompasses body-worn electronic devices that capture physiological data through biosensors, accelerometers, and optical photoplethysmography modules, typically operating at sampling frequencies between 128 Hz and 512 Hz for cardiac applications and transmitting encrypted data via Bluetooth Low Energy 5.0 or NFC protocols to clinical decision support systems. These devices serve the primary commercial purpose of enabling ambulatory diagnostics, chronic disease surveillance, and post-acute care transition management outside traditional facility settings. Smartwatches dominate unit economics through recurring software subscription attach rates, while ECG monitors command premium pricing in cardiology referral networks due to FDA 510(k) predicate requirements and physician liability considerations. Blood pressure monitors represent the fastest-growing product category as optical cuffless algorithms achieve validation against sphygmomanometer reference standards in ambulatory settings.
FDA software-as-medical-device guidance and HIPAA security rule enforcement shape product development roadmaps by mandating premarket submission for diagnostic algorithms and encryption standards for cloud-based health data transmission. The EU Medical Device Regulation and GDPR health data provisions create parallel compliance burdens for manufacturers seeking CE marking and European market access. Stakeholders must monitor evolving reimbursement determinations from CMS and analogous national health technology assessment bodies, as coverage decisions for remote therapeutic monitoring CPT codes will determine whether clinical wearable deployments achieve sustainable revenue models or remain constrained to direct-to-consumer channels.
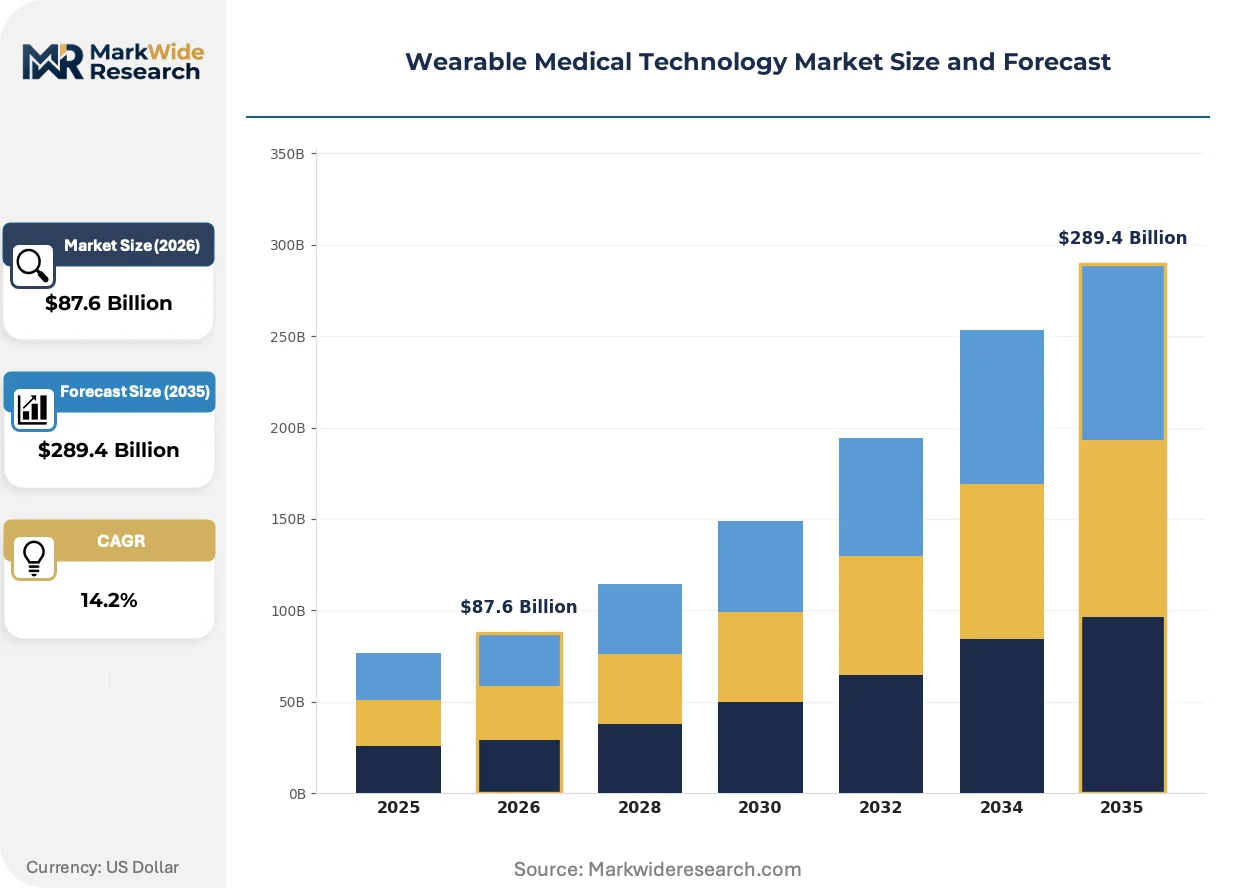
Market Dynamics
Silicon photonics is compressing component costs in continuous glucose monitoring patches while Medicare reimbursement codes for remote therapeutic monitoring accelerate clinical procurement cycles in ambulatory care settings.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage determinations for remote therapeutic monitoring CPT codes enable sustainable revenue models for hospital-deployed biosensors, shifting procurement from direct-to-consumer to institutional channels.
- FDA 510(k) Pathway Compression:Software-as-medical-device guidance reduces premarket submission timelines for algorithm-driven wearables, accelerating time-to-market for diagnostic platforms in cardiology referral networks.
- Optical Sensor Miniaturization:Photoplethysmography module density improvements enable multi-parameter health platforms in wrist-worn form factors, expanding addressable use cases beyond single-vital monitoring.
Market Restraints
- Electrode Material Concentration:Factory-calibrated sensor filament production concentrates among three specialized chemical suppliers, creating input bottlenecks for glucose monitoring patch manufacturers.
- Validation Timeline Friction:Optical cuffless blood pressure algorithms require extended ambulatory validation against sphygmomanometer reference standards, compressing gross margins for pre-revenue development cycles.
- GDPR Health Data Compliance:EU Medical Device Regulation and GDPR health data provisions impose parallel encryption and cloud-storage burdens, extending CE marking timelines for cloud-connected devices.
Strategic Opportunities
- Post-Acute Care Transition Management:Hospital-at-home programs in Germany and France create procurement demand for multi-parameter platforms that integrate ECG with accelerometry for fall-risk stratification.
- Bluetooth Low Energy 5.3 Migration:Protocol upgrades enable encrypted transmission at lower power draw, opening battery-life-sensitive applications in long-term care facilities previously served by wired telemetry.
- India PLI Scheme for Electronics:Production-linked incentives for wearable device assembly attract component sourcing shifts, creating localized supply alternatives to China-centric sensor module production.
Industry Challenges
- Algorithm Validation Talent Scarcity:Clinical data science expertise for FDA predicate device equivalence studies concentrates among contract research organizations, inflating regulatory submission costs for mid-tier manufacturers.
- Legacy Health Record Integration:HL7 FHIR interoperability requirements force custom API development for each hospital system's electronic health record vendor, fragmenting deployment engineering resources.
- ISO 13485 Certification Backlogs:Notified body capacity constraints for quality management system audits extend medical device certification timelines, delaying commercial launches for quality-dependent procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Medical Technology Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, ECG Monitors, Blood Pressure Monitors Application: Chronic Disease Management, Fitness Tracking, Emergency Response, Sleep Monitoring Technology: Bluetooth, NFC, RFID, Wi-Fi End User: Hospitals, Clinics, Health-conscious Consumers, Fitness Enthusiasts |
| Companies Covered | Apple Inc., Fitbit Inc., Samsung Electronics, Dexcom Inc., Abbott, Koninklijke Philips N.V., Garmin Ltd., Medtronic, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Medical Technology Market Strategic Shifts
Algorithmic diagnostic platforms are restructuring competitive positioning by enabling software-defined feature expansion without hardware redesign, while regulatory clarity on digital therapeutics creates new reimbursement categories for prescription-grade wearables.
Silicon photonics is overtaking traditional electrode materials in continuous glucose monitoring patches by enabling factory-calibrated optical filaments that eliminate user calibration steps. Cardiology departments in US hospital systems are adopting these platforms at accelerated procurement cycles. This technology is overtaking electrochemical sensing in premium-tier glucose monitoring by compressing manufacturing complexity and enabling applicator-integrated disposable designs.
EU Medical Device Regulation recast requirements for software-as-medical-device are forcing manufacturers to maintain technical documentation for algorithm version control across post-market surveillance obligations. Industrial consequence includes mandatory clinical evidence updates for each algorithm modification, increasing regulatory affairs headcount. Class IIa diagnostic wearables with cloud-based machine learning components face the most significant compliance burden, with manufacturers responding through captive regulatory consulting capabilities.
Institutional procurement committees are consolidating vendor selection around platforms with pre-negotiated electronic health record interoperability, displacing standalone device purchasing by individual clinical departments. Cardiology and endocrinology service lines within integrated delivery networks now mandate enterprise-wide platform standardization, replacing siloed point solutions. This concentration is most visible in United States health systems pursuing Medicare Shared Savings Program accountable care organization contracts, where data integration across sites determines quality metric reporting compliance.
Wearable Medical Technology Market Segmentation
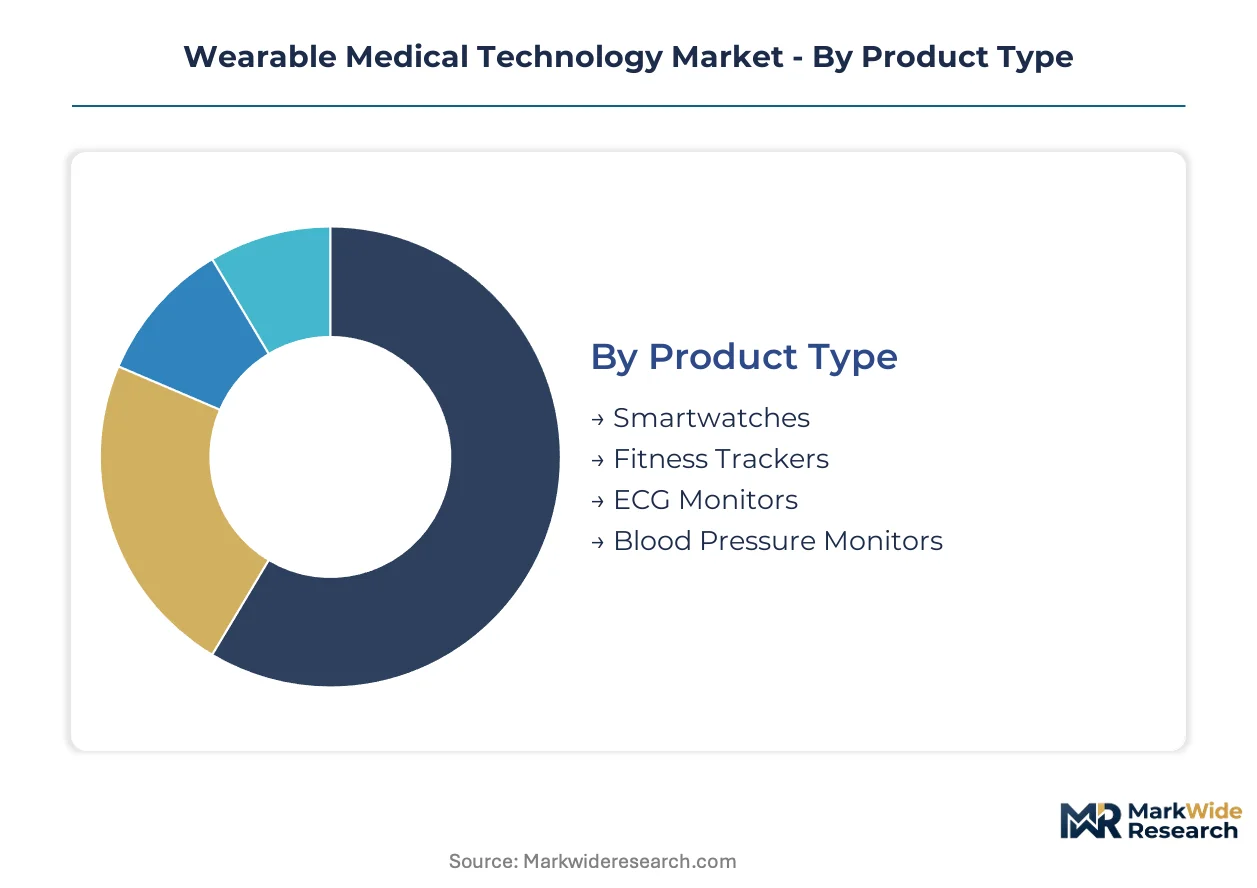
Wearable medical technology segmentation reflects divergent procurement economics between institutional buyers and direct-to-consumer channels. Product specifications, connectivity protocols, and reimbursement eligibility create distinct competitive arenas with margin structures that favor multi-parameter platforms over single-function devices.
Product Type:
Hospital procurement committees prioritize FDA 510(k) clearance status and electronic health record interoperability when selecting device categories for remote patient monitoring programs.
- Smartwatches:Multi-parameter platforms integrate electrocardiography, blood pressure estimation, and accelerometry in wrist-worn form factors operating at 128-512 Hz sampling frequencies. Demand concentrates in United States integrated delivery networks pursuing Medicare Shared Savings Program contracts, where software subscription attach rates determine lifetime customer value.
- ECG Monitors:Single-lead and multi-lead configurations transmit encrypted cardiac data via Bluetooth Low Energy 5.0 to clinical decision support systems, commanding premium pricing in cardiology referral networks due to physician liability considerations and predicate device equivalence requirements.
- Fitness Trackers:Accelerometer-based activity quantification targets health-conscious consumers through direct-to-consumer channels with minimal regulatory burden.
- Blood Pressure Monitors:Optical cuffless algorithms achieve validation against sphygmomanometer reference standards, expanding fastest among ambulatory diagnostic applications.
Volume sits with smartwatches; growth tilts toward blood pressure monitors.
Application:
Reimbursement code availability determines whether application segments achieve sustainable revenue through institutional procurement or remain confined to out-of-pocket consumer purchases.
- Chronic Disease Management:Continuous glucose monitoring and remote therapeutic monitoring deployments leverage Medicare CPT codes for sustainable hospital-at-home program economics. United States cardiology and endocrinology service lines drive procurement concentration.
- Emergency Response:Fall detection and automated alert systems integrate accelerometry with cellular connectivity for post-acute care transition management. German and French hospital-at-home programs create procurement demand for multi-parameter platforms.
- Fitness Tracking:Step counting and caloric expenditure estimation serve wellness-oriented consumers without clinical validation requirements.
- Sleep Monitoring:Photoplethysmography-derived oxygen saturation and sleep stage classification targets direct-to-consumer markets with limited reimbursement coverage.
Revenue concentrates in chronic disease management; emergency response climbs fastest as hospital-at-home programs expand.
Technology:
Power consumption and encryption capabilities determine protocol selection for battery-sensitive long-term care applications versus high-bandwidth hospital telemetry.
- Bluetooth:Low Energy 5.0 and 5.3 protocols enable encrypted transmission at reduced power draw, dominating ambulatory and residential deployments where battery life determines form factor viability.
- NFC:Near-field communication supports factory-calibrated sensor filament pairing in continuous glucose monitoring patches, eliminating user calibration steps through applicator-integrated designs.
- RFID:Passive and active radio-frequency identification serves asset tracking and patient identification in acute care settings with limited biosensor data transmission requirements.
- Wi-Fi:Higher bandwidth protocol enables real-time streaming for inpatient telemetry applications where power constraints are secondary to data throughput.
Deployment volume favors Bluetooth; NFC gains share fastest through glucose monitoring patch integration.
End User:
Procurement authority and reimbursement eligibility create divergent margin structures between institutional buyers with enterprise-wide platform standardization mandates and fragmented consumer purchasing.
- Hospitals:Integrated delivery networks mandate vendor consolidation around pre-negotiated electronic health record interoperability, displacing standalone device purchasing by individual clinical departments. United States health systems pursuing accountable care organization contracts drive platform selection.
- Clinics:Ambulatory care settings accelerate procurement cycles for remote therapeutic monitoring devices following CMS reimbursement expansion, shifting from direct-to-consumer to institutional channels.
- Health-conscious Consumers:Out-of-pocket purchasing of wellness-oriented devices operates without reimbursement support or clinical validation requirements.
- Fitness Enthusiasts:Performance optimization applications favor multi-parameter platforms with GPS and accelerometry integration for training load quantification.
Procurement volume rests with hospitals; clinic deployment expands most quickly as reimbursement codes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for electronics manufacturing is attracting component sourcing shifts, creating localized supply alternatives to China-centric sensor module production. Special economic zones in Gujarat and Tamil Nadu host emerging assembly operations for Bluetooth-enabled biosensors.
United States
Medicare reimbursement codes for continuous glucose monitoring and remote therapeutic monitoring accelerate clinical adoption of wearable biosensors across cardiology and endocrinology service lines. FDA 510(k) pathway compression for software-as-medical-device reduces premarket submission timelines for algorithm-driven wearables. Hospital systems in Greater Boston and the Pacific Northwest expand remote patient monitoring programs through integrated delivery networks pursuing accountable care organization contracts.
Germany
Hospital-at-home programs in Bavaria and North Rhine-Westphalia create procurement demand for multi-parameter platforms integrating ECG with accelerometry for fall-risk stratification. EU Medical Device Regulation recast requirements impose technical documentation burdens for algorithm version control across post-market surveillance obligations. The Eindhoven-Heidelberg corridor concentrates regulatory consulting capabilities serving CE marking timelines for cloud-connected devices.
China
Domestic demand for wrist-worn multi-parameter health platforms expands as optical cuffless blood pressure algorithms achieve validation against reference standards. NMPA medical device registration requirements shape product development roadmaps for manufacturers seeking domestic market access. Yangtze River Delta industrial clusters in Shanghai and Suzhou concentrate photoplethysmography module production for export-oriented assembly operations.
Japan
Aging demographics drive institutional procurement of long-term care telemetry solutions with Bluetooth Low Energy 5.3 protocol upgrades enabling encrypted transmission at lower power draw. PMDA consultation procedures for software-as-medical-device guide algorithm-driven wearable submissions for domestic market authorization. Kanto region medical device manufacturers in Tokyo and Yokohama specialize in miniaturized sensor packaging for battery-sensitive applications.
Wearable Medical Technology Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement committees consolidating vendor selection around platforms with pre-negotiated electronic health record interoperability. The vendor base organizes into three strategic archetypes: diversified consumer electronics conglomerates with multi-parameter health platforms, captive sensor manufacturers with factory-calibrated filament production, and pure-play diagnostics specialists with FDA-cleared algorithm portfolios. Competitive dynamics center on M&A activity targeting regulatory consulting capabilities and strategic partnerships securing HL7 FHIR interoperability across hospital system electronic health record vendors.
Within the diversified technology tier, Apple Inc. and Samsung Electronics exemplify consumer electronics conglomerates that have extended smartphone ecosystem architectures into wrist-worn health platforms. Dexcom Inc. occupies a specialist position among glucose monitoring patch manufacturers with applicator-integrated sensor designs. Abbott anchors the factory-calibrated sensor filament segment through vertical control over disposable production. Medtronic and Koninklijke Philips N.V. represent diversified medical technology incumbents with established cardiology referral network relationships and enterprise-wide platform standardization mandates.
| Leading Market Players |
|---|
| Apple Inc. |
| Fitbit Inc. |
| Samsung Electronics |
| Dexcom Inc. |
| Abbott |
| Koninklijke Philips N.V. |
| Garmin Ltd. |
| Medtronic |
| GE HealthCare |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiering bifurcates the market into premium diagnostic-grade and commodity wellness devices, with that divergence manifesting in both subscription-heavy pricing models for hospital-deployed platforms and stripped-down bill-of-materials for direct-to-consumer channels. Silicon photonics adoption in glucose monitoring patches compresses component costs at the premium tier while electrode material scarcity inflates input pricing for mid-tier manufacturers lacking captive filament supply.
Pricing Analysis
Volume concentrates in smartwatch subscriptions with software attach rates driving lifetime value, while ECG monitors command premium unit economics through predicate-device equivalence requirements and physician liability premiums. Price differentiation rests on FDA clearance tier and HL7 FHIR interoperability certification, with hospital procurement committees least sensitive to unit cost and direct-to-consumer buyers most responsive to retail price points. Pricing pressure stems from optical sensor commoditization in wrist-worn form factors, compressing margins for non-specialized hardware vendors.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks require qualified secondary suppliers for Bluetooth Low Energy modules and photoplethysmography components, forcing manufacturers to maintain redundant vendor relationships. Production concentrates in China for sensor module fabrication, Vietnam for final assembly, and Taiwan for silicon photonics foundry capacity. Raw material dependencies span factory-calibrated sensor filaments, lithium-polymer cells, and medical-grade elastomers. Single-source vulnerability in specialized chemical suppliers for glucose monitoring electrodes creates procurement risk. Distribution runs through GPO contracts for institutional buyers and direct-to-consumer e-commerce for wellness devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable medical technology sits in a technology-transition phase as silicon photonics displaces electrochemical sensing in continuous glucose monitoring, restructuring both manufacturing economics and competitive positioning.
For Market Incumbents: Acquire regulatory consulting capabilities to compress FDA 510(k) submission timelines for algorithm-driven diagnostics. Consolidate enterprise-wide platform contracts with integrated delivery networks pursuing Medicare Shared Savings Program compliance, defending against pure-play software entrants lacking hospital system relationships. Backward integration into factory-calibrated sensor filament production secures input supply against chemical supplier concentration. For New Entrants and Emerging Players: CMS reimbursement expansion for remote therapeutic monitoring CPT codes in the United States opens a window for clinic-focused platforms bypassing hospital procurement committee consolidation. Target ambulatory care settings with Bluetooth Low Energy 5.3-enabled multi-parameter devices for post-acute care transition management. Lead with HL7 FHIR interoperability pre-certification to accelerate hospital system deployment timelines. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-validation specialists given FDA software-as-medical-device guidance clarity expanding addressable diagnostic categories. Long-term viability favors platforms with sustainable institutional revenue models over direct-to-consumer hardware cycles. Watch CMS coverage determinations for additional remote monitoring CPT codes as the inflection indicator for clinical procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Software-as-medical-device pathway compression accelerates diagnostic algorithm time-to-market for cardiology platforms. |
| CE Marking Pathway | EU MDR recast requirements for algorithm version control extend compliance timelines for cloud-connected wearables. |
| Hospital System Partnership | Pre-negotiated EHR interoperability contracts displace standalone device purchasing by individual clinical departments. |
| Software Companion Development | Algorithmic diagnostic platforms enable feature expansion without hardware redesign, extending device lifecycle value. |
| Reimbursement Strategy | Medicare CPT code coverage determines whether clinical deployments achieve sustainable revenue or remain consumer-channel constrained. |
Study Parameters
Multi-period observation of Medicare reimbursement code expansions, FDA 510(k) clearance timelines, and silicon photonics patent filings anchored the trend analysis, supplemented by interviews with hospital procurement committee directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at wearable device manufacturers. Secondary validation drew from FDA 510(k) database filings, CMS Medicare coverage determinations, hospital procurement databases, and SEC filings of publicly traded device companies. Bottom-up unit shipment estimates across product categories triangulated against top-down market value reconstructions.
Segment-weighting approaches modeled smartwatch, ECG monitor, blood pressure monitor, and glucose monitoring patch categories separately, with technology adoption curves applied across the projection horizon. Connectivity protocol splits, end-user procurement channel dynamics, and regional reimbursement maturity were integrated as cross-cutting dimensions. CAGRs were derived from fitted growth curves against historical adoption benchmarks in comparable diagnostic device categories. Forecast inputs included Medicare Advantage penetration rates and EU MDR notified body capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for optical cuffless blood pressure validation would alter the outlook for wrist-worn multi-parameter platforms. Forecasts reflect assumptions regarding CMS reimbursement code stability and FDA software-as-medical-device guidance continuity. Deviation in EU MDR technical documentation requirements or notified body audit backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Hormonal Implants Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Cervical Implants Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Laser Therapy Devices Market