
 Ethiopia Renewable Energy Market | 2026-2036
Ethiopia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ethiopia Renewable Energy Market Foresight
Market Dynamics
Long-term power purchase agreements are rebalancing how generation assets get financed and operated in Ethiopia's renewable sector. Ethiopian Electric Power leverages its transmission monopoly to anchor large-scale hydro and geothermal dispatch. PowerChina sustains project momentum through engineering-procurement-construction contracts on the Grand Renaissance Dam complex. Siemens Gamesa Renewable Energy differentiates through turbine technology adapted for high-altitude wind regimes in the Ethiopian Highlands.
Technology and Segment Structure
Ethiopia renewable energy encompasses electricity generation, thermal conversion, and mechanical power extraction from hydrological, solar, wind, and geothermal resources, typically harnessed through turbine-generator sets, photovoltaic arrays, and binary-cycle plants for grid injection or isolated supply. Hydropower occupies the dominant share due to Ethiopia's 45,000 MW theoretical river potential along the Nile basin, while solar power represents the fastest-expanding segment as distributed generation and microgrids proliferate across off-grid areas. Utility-scale installations command capital concentration, though standalone systems and microgrids attract development finance for rural electrification.
Regulatory Environment and Outlook
Ethiopia's Ministry of Water and Energy, the Ethiopian Energy Authority, and the Ethiopian Electric Power Corporation shape licensing, tariff setting, and grid access protocols for independent power producers. The country's national electrification program mandates universal access targets that directly procure renewable capacity. Stakeholders must monitor feed-in tariff adjustments and currency convertibility rules that determine developer returns on dollar-denominated equipment imports.
Market Dynamics
Feed-in tariff reforms under Ethiopia's Ministry of Water and Energy are compressing developer returns while accelerating rural electrification timelines, forcing independent power producers to restructure financing around local currency instruments and state-backed guarantees.
Growth Catalysts
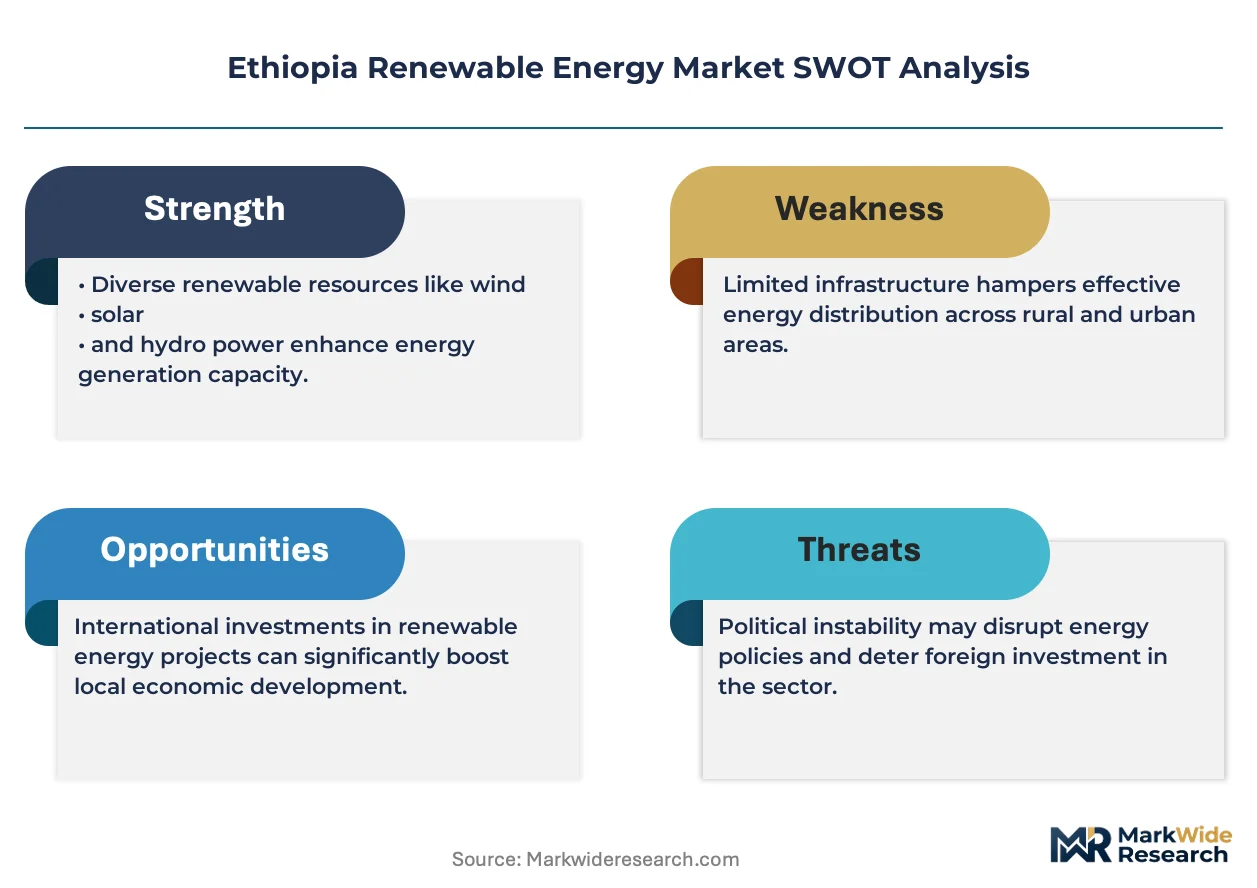
- Universal Access Targets:Ethiopia's national electrification program mandates grid extension and off-grid renewable deployment, directly procuring capacity from geothermal and solar developers.
- Rift Valley Geothermal Clustering:Proximity to the East African Rift's volcanic corridor concentrates resource extraction infrastructure, reducing exploratory drilling costs for binary-cycle plants.
- Agricultural Processing Cooperatives:Rural electrification programs target dairy and grain cooperatives in Oromia, creating distributed demand anchors for mini-grid solar installations.
Market Restraints
- Currency Convertibility Rules:Dollar-denominated equipment imports face repatriation restrictions, inflating effective capital costs for photovoltaic arrays and turbine-generator sets.
- Transmission Monopoly Concentration:Ethiopian Electric Power's exclusive control over high-voltage infrastructure limits independent dispatch options for wind projects in the Highlands.
- Hydrological Variability:Nile basin flow fluctuations constrain capacity factors for run-of-river hydro installations during drought cycles.
Strategic Opportunities
- Off-Grid Solar Microgrids:Distributed generation models bypass transmission bottlenecks entirely, serving pastoral communities in Afar and Somali regions without grid extension.
- Green Hydrogen Export Corridors:Abundant geothermal and wind resources position Ethiopia to supply electrolyzer feedstock for European industrial decarbonization mandates.
- Engineering-Procurement-Construction Partnerships:Chinese contractors dominate dam construction; joint ventures with European turbine suppliers open technology transfer pathways for local manufacturing.
Industry Challenges
- Grid Integration Complexity:Variable renewable injection from high-altitude wind farms requires synchronous condenser upgrades that Ethiopian Electric Power has deferred.
- Land Tenure Negotiations:Customary land rights in Oromia and SNNPR regions prolong site acquisition for utility-scale solar arrays, extending pre-construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethiopia Renewable Energy Market |
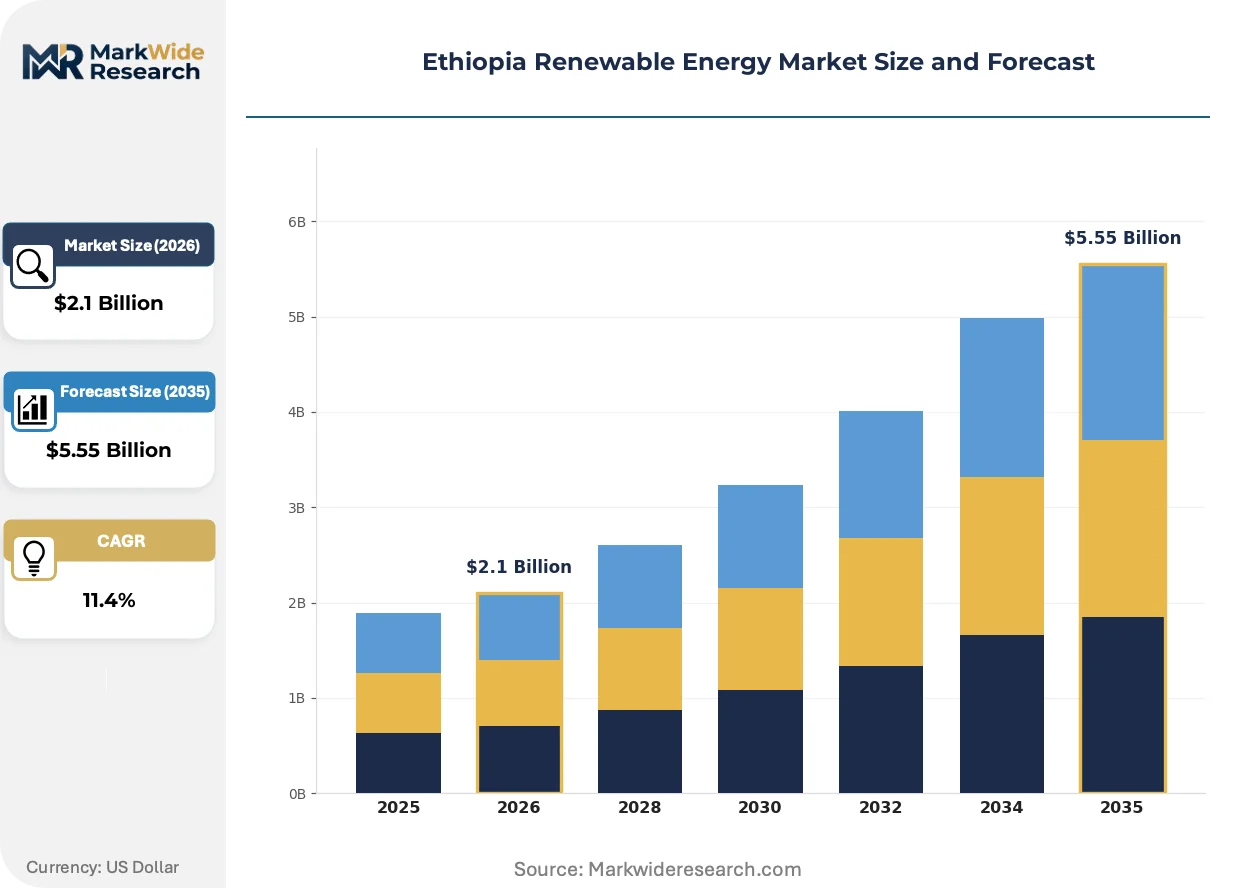
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydropower, Wind Energy, Solar Power, Biomass Application: Electricity Generation, Heating, Off-Grid Solutions, Pumping Systems End User: Residential, Commercial, Industrial, Institutional Installation Type: Utility-Scale, Distributed Generation, Microgrids, Standalone Systems |
| Companies Covered | Ethiopian Electric Power, PowerChina, China Gezhouba Group, Siemens Gamesa Renewable Energy, Tulu Moye Geothermal Operations, Enel Green Power, Green Scene Energy, Rensys Engineering & Trading, Lydetco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethiopia Renewable Energy Market Shifts & Advancements
Technology convergence and procurement model evolution are compressing deployment cycles for Ethiopian renewable assets, with distributed generation architectures displacing centralized planning assumptions that dominated the Grand Renaissance Dam era.
Hybrid solar-diesel-battery systems are electrifying agricultural value chains in moisture-stressed zones. Dairy cooperatives in the Central Rift Valley deploy these configurations to power cold storage without waiting for grid extension. The technology is electrifying rural load centers previously deemed uneconomical for conventional electrification, compressing the viable market for isolated diesel generators.
Ethiopia's Ministry of Water and Energy revised feed-in tariff schedules to differentiate capacity payments from energy payments, altering revenue predictability for independent power producers. Developers now structure power purchase agreements around availability guarantees rather than generation forecasts. Geothermal projects in the Aluto-Langano field are responding by prioritizing binary-cycle reliability over peak output maximization.
Cooperative procurement collectives are aggregating demand from agricultural processing units, displacing individual site-by-site contracting. These buyer groups negotiate standardized engineering-procurement-construction terms with Chinese contractors, reducing transaction costs for solar mini-grid deployment. The shift concentrates purchasing power in Oromia's dairy belt, where cooperatives now specify performance warranties rather than equipment specifications.
Ethiopia Renewable Energy Market Segmentation
Segmentation in Ethiopia's renewable energy market reveals how technology choice, application context, and installation scale interact with the country's dual priorities of universal electrification and export-oriented generation. Each axis exposes distinct financing requirements, regulatory pathways, and geographic clustering patterns that shape developer strategy.
Technology:
Technology selection in Ethiopia follows resource endowment geography rather than cost curves alone, with river basin hydrology and Rift Valley geothermal gradients constraining viable options by location.
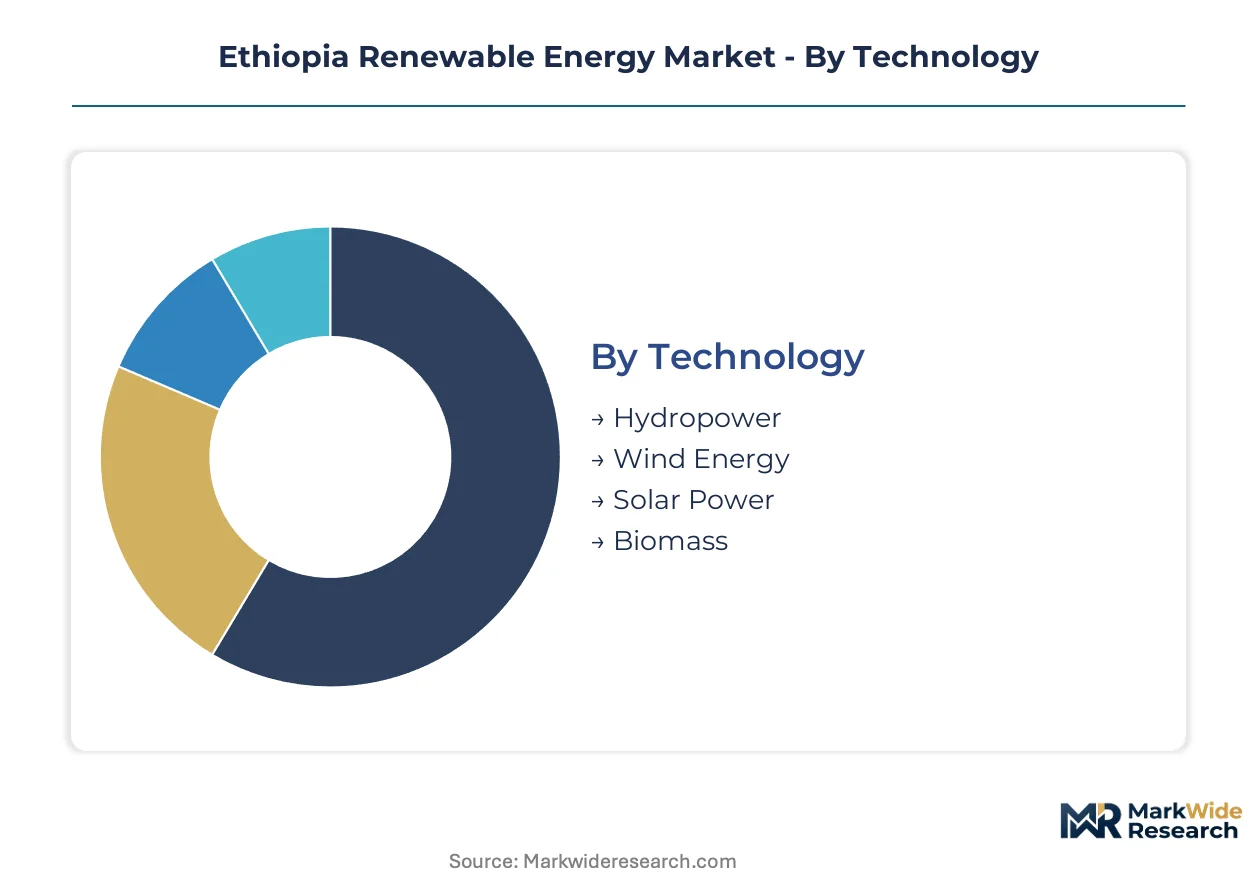
- Hydropower:Run-of-river and reservoir configurations exploit the Nile basin's 45,000 MW theoretical potential, with Ethiopian Electric Power anchoring dispatch through its transmission monopoly. Capacity concentrates on the Blue Nile and Omo River corridors, where Chinese engineering-procurement-construction contractors dominate dam construction timelines.
- Solar Power:Photovoltaic arrays range from utility-scale installations in the Afar depression to distributed rooftop systems in Addis Ababa. Demand from agricultural processing cooperatives in Oromia is accelerating mini-grid deployment, bypassing Ethiopian Electric Power's grid extension queues entirely.
- Wind Energy:High-altitude turbine installations in the Ethiopian Highlands require adapted blade designs for thin-air performance, with Siemens Gamesa Renewable Energy supplying technology optimized for these regimes.
- Biomass:Agricultural residue combustion and biogas digesters serve institutional and rural residential loads, particularly in moisture-stressed zones where crop waste availability aligns with heating demand seasonality.
Hydropower leads on scale; solar power leads on momentum.
Application:
Application segmentation tracks the divergence between grid-connected generation for industrial load centers and isolated supply for pastoral and agricultural communities.
- Electricity Generation:Grid injection from hydro, wind, and geothermal assets supplies Ethiopian Electric Power's wholesale procurement, with power purchase agreements structured around availability guarantees under revised feed-in tariff schedules.
- Off-Grid Solutions:Solar-battery microgrids electrify pastoral communities in Afar and Somali regions without transmission infrastructure, compressing deployment timelines from years to months.
- Heating:Geothermal direct-use and biomass combustion serve agro-processing thermal loads, particularly dairy pasteurization in the Central Rift Valley where cooperatives aggregate demand.
- Pumping Systems:Solar-powered irrigation pumps displace diesel generators in moisture-stressed agricultural zones, with the Ministry of Water and Energy targeting smallholder productivity gains.
Electricity generation commands capital concentration; off-grid solutions are expanding most quickly.
End User:
End user segmentation reflects Ethiopia's electrification hierarchy, with institutional and industrial loads receiving priority grid access while residential expansion relies increasingly on distributed alternatives.
- Industrial:Cement, textile, and food processing facilities anchor demand for reliable baseload power, negotiating directly with Ethiopian Electric Power for dedicated transmission capacity.
- Residential:Urban grid extension in Addis Ababa and regional capitals contrasts with rural solar home systems, where affordability constraints shape product specification toward pico-PV and pay-as-you-go financing.
- Commercial:Hotels, banking, and retail in secondary cities require backup power integration as grid reliability varies seasonally with hydrological flows.
- Institutional:Health centers and schools in Oromia and SNNPR regions receive targeted off-grid solar deployment under national electrification program mandates.
Industrial users lead on scale; residential expansion is gaining share fastest.
Installation Type:
Installation type determines financing architecture, with utility-scale projects accessing multilateral development bank debt while distributed models rely on development finance and cooperative equity.
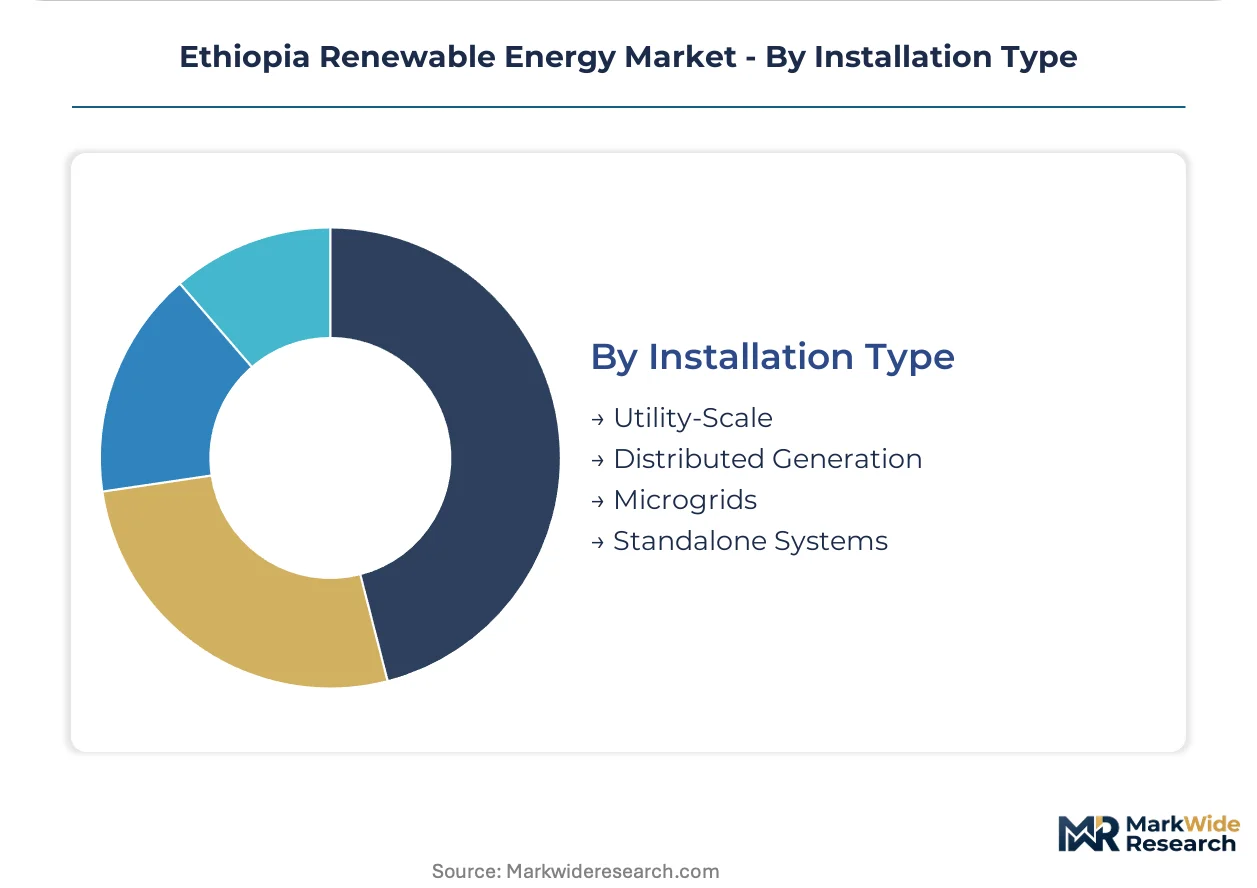
- Utility-Scale:Centralized hydro and geothermal plants exceeding 50 MW capacity feed Ethiopian Electric Power's high-voltage network, requiring sovereign guarantees and extended construction timelines.
- Microgrids:Solar-diesel-battery hybrid systems serve agricultural cooperatives in dairy and grain processing belts, with standardized engineering-procurement-construction terms reducing transaction costs through collective procurement.
- Distributed Generation:Commercial and industrial rooftop solar bypasses transmission constraints in Addis Ababa, though net metering regulations remain under development by the Ethiopian Energy Authority.
- Standalone Systems:Solar home systems and solar pumps target pastoral and smallholder populations beyond viable grid extension, with mobile money integration enabling pay-as-you-go revenue collection.
Utility-scale installations lead on scale; microgrids show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's geothermal capacity exceeds Ethiopia's operational output, though Ethiopia's hydropower potential dwarfs regional neighbors. Currency convertibility constraints in Addis Ababa diverge from Nairobi's more liberalized capital account regime. Both markets attract Chinese engineering-procurement-construction contractors, yet tariff structures and grid access protocols create distinct investment climates.
Oromia Region
Dairy and grain processing cooperatives drive distributed solar demand across the Central Rift Valley. The Ministry of Water and Energy channels rural electrification program funds toward agricultural value chain electrification. The Adama wind corridor hosts high-altitude turbine installations where Siemens Gamesa Renewable Energy has supplied adapted blade technology.
Tigray Region
Tekeze River hydropower infrastructure anchors grid supply for cement and textile industrial loads. Ethiopian Electric Power prioritizes transmission reinforcement to this northern corridor under national electrification mandates. The Tekeze Dam complex remains a focal point for Chinese contractor presence in reservoir-based generation.
Southern Nations, Nationalities, and Peoples' Region
Run-of-river hydro potential along the Omo River basin attracts multilateral development bank financing for cascade development. Land tenure negotiations under customary rights regimes prolong site acquisition for utility-scale solar arrays. The Gibe River corridor concentrates Chinese dam construction activity alongside prospective geothermal exploration.
Afar Region
Pastoral communities beyond viable grid extension create demand anchors for off-grid solar-battery microgrids. Solar irradiance levels in the Danakil Depression exceed national averages, supporting standalone system economics. Development finance institutions target this region for pay-as-you-go solar home system deployment without transmission infrastructure dependency.
Amhara Region
Blue Nile tributary hydrology supports run-of-river and reservoir hydro configurations feeding industrial load centers. The Ethiopian Energy Authority processes licensing applications for independent power producers seeking grid injection agreements. Bahir Dar and surrounding areas concentrate biomass residue availability for agricultural waste-to-energy pilot programs.
Ethiopia Renewable Energy Market Competitive Landscape
Top-tier vendors anchor state-backed generation assets, while mid-tier specialists cluster around distributed solar and geothermal services. Ethiopian Electric Power maintains transmission monopoly control that shapes competitive access for independent producers. Three archetypes dominate: Chinese engineering-procurement-construction conglomerates executing dam infrastructure, European turbine technology suppliers adapted for high-altitude regimes, and local-foreign joint ventures navigating feed-in tariff procurement. Competitive intensity centers on sovereign guarantee access and currency hedging structures rather than pure technology differentiation.
Among state-affiliated utilities, Ethiopian Electric Power occupies the central coordinating position for generation dispatch and grid access protocols. Chinese contractors PowerChina and China Gezhouba Group exemplify the engineering-procurement-construction archetype that dominates hydroelectric infrastructure development. Siemens Gamesa Renewable Energy represents the technology-supplier tier, occupying a position in wind turbine provision where altitude-adapted equipment creates distinct specification requirements.
| Leading Market Players |
|---|
| Ethiopian Electric Power |
| PowerChina |
| China Gezhouba Group |
| Siemens Gamesa Renewable Energy |
| Tulu Moye Geothermal Operations |
| Enel Green Power |
| Green Scene Energy |
| Rensys Engineering & Trading |
| Lydetco |
| Others |
Supply & Pricing Matrix
Geothermal drilling specialists concentrated in the Aluto-Langano corridor create labor-cost differentials that widen spreads between premium engineering-procurement-construction contracts and standardized solar mini-grid installations. Ethiopian Electric Power's transmission monopoly compresses margins for independent power producers while inflating premiums for sovereign-guaranteed offtake arrangements.
Pricing Analysis
Capacity additions in Oromia's Central Rift Valley are reshaping price floors for solar-battery hybrid systems serving agricultural cooperatives. Project-based long-term offtake contracts dominate, with price differentiation driven by sovereign guarantee backing and equipment origin certification. Cost compression in distributed generation segments is intensifying because Chinese contractors aggregate cooperative procurement volumes. Rural residential buyers exhibit highest price sensitivity, while cement and textile industrial facilities accept premium tariffs for dedicated transmission capacity.
Supply Chain Analysis
Photovoltaic module supply rests on Chinese manufacturers for crystalline silicon cells, with inverter components drawing from German and Japanese specialty producers. Turbine-generator sets for high-altitude wind installations hinge on European blade technology adapted for thin-air regimes. Raw material dependencies span polysilicon, rare-earth magnets, and geothermal wellhead equipment. Single-source vulnerability concentrates in Ethiopian Electric Power's exclusive high-voltage transformer procurement. Distribution runs through state-controlled transmission infrastructure with limited third-party access protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethiopia's renewable energy market functions as a regulatory compounder, with feed-in tariff reforms under the Ministry of Water and Energy accelerating capital redeployment toward local currency financing structures. Universal electrification mandates create demand visibility that transcends pure price competition.
For Market Incumbents: Extend sovereign guarantee access through Ethiopian Electric Power partnership structures before currency convertibility rules tighten further. Secure backward integration into geothermal drilling capabilities to offset Chinese contractor price pressure in the EPC segment. Prioritize binary-cycle reliability investments at Aluto-Langano to align with revised feed-in tariff availability guarantees. For New Entrants and Emerging Players: Mobile-enabled pay-as-you-go platforms offer the lowest competitive friction for solar home system deployment in Afar and Somali pastoral regions. Target agricultural processing cooperatives in Oromia's dairy belt through standardized performance-warranty offerings rather than equipment specifications. Pursue joint venture structures with established Chinese EPC contractors to bypass transmission queue bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among distributed solar developers lacking Ethiopian Electric Power offtake agreements but possessing cooperative demand aggregation capabilities. Five-to-ten year viability hinges on feed-in tariff schedule stability and birr-dollar convertibility restoration. Monitor Ministry of Water and Energy licensing backlog clearance rates as the critical inflection signal for deployment velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | Availability-based contracts under revised Ethiopian Energy Authority tariffs reshape developer returns. |
| Local Currency Financing Transition | Development finance institutions anchor birr-denominated debt to mitigate repatriation restrictions. |
| Cooperative Procurement Aggregation | Oromia dairy collectives standardize EPC terms, compressing transaction costs for mini-grid deployment. |
| Geothermal Binary-Cycle Reliability Investment | Aluto-Langano operators prioritize capacity factor guarantees over peak output maximization. |
| Off-Grid Solar Microgrid Expansion | Afar and Somali regions bypass Ethiopian Electric Power transmission queues entirely. |
Research Methodology
Direct dialogue with Ethiopian Electric Power planning officers, independent power producer project developers, Chinese engineering-procurement-construction contractors, geothermal drilling specialists, and agricultural cooperative procurement managers grounded the qualitative foundation. Secondary validation drew from Ethiopian Energy Authority licensing databases, Ministry of Water and Energy tariff filings, multilateral development bank project pipelines, and customs records for photovoltaic and turbine imports. Bottom-up capacity installation tracking and top-down electrification program budget analysis were triangulated against regional grid extension timelines.
Segmented outputs across the projection horizon reflect technology-specific deployment curves, with hydropower reservoir configurations, solar distributed generation, high-altitude wind installations, and binary-cycle geothermal plants modeled separately. CAGRs were derived from installed capacity build rates intersecting with universal access target deadlines. Forecast inputs incorporated Rift Valley exploratory drilling success rates, cooperative procurement collective formation velocity, and currency convertibility scenario assumptions.
The model assumes a particular technology adoption path; alternative pathways for green hydrogen electrolyzer feedstock export would alter the outlook toward industrial off-taker contracting rather than domestic electrification. Forecasts reflect assumptions around Ethiopian Electric Power transmission expansion schedules and Ministry of Water and Energy licensing throughput. Hydrological variability, land tenure negotiation delays, and birr depreciation trajectories constitute specific revision triggers. A small set of named triggers—feed-in tariff schedule adjustments, sovereign guarantee issuance rates, and Chinese contractor availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar EPC Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
South Africa Distributed Solar Energy Market