
 Solar Traffic Light Market | 2026-2036
Solar Traffic Light Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Traffic Light Market Insights
The EU Green Deal is realigning procurement criteria for off-grid traffic infrastructure across member states. Swarco AG leverages its Austrian manufacturing base to supply solar signal assemblies with embedded wireless modules. Siemens AG competes through intelligent controller platforms that integrate with municipal traffic management systems. Eaton Corporation anchors its position in North American markets with standalone photovoltaic signal systems engineered for extreme weather tolerance.
A solar traffic light converts photovoltaic energy into stored electrical power to illuminate LED-based signaling arrays without grid connection, typically incorporating monocrystalline panels, deep-cycle batteries, and microprocessor-driven load management. These installations serve remote intersections, temporary construction zones, and emergency routing scenarios where trenching for grid power proves economically prohibitive. LED Signals dominate product type revenue due to universal retrofit compatibility and declining semiconductor costs. Intelligent Controllers within the technology dimension command premium positioning as cities demand adaptive signal timing and remote diagnostics. Municipalities represent the most concentrated end user segment, though Smart Cities are expanding fastest where integrated IoT platforms justify higher upfront capital outlays.
The Federal Highway Administration (FHWA) Manual on Uniform Traffic Control Devices shapes product specifications in the United States, while the EU's CE marking and RoHS directives govern material composition and electromagnetic compliance for European deployments. India's Bureau of Indian Standards (BIS) and Central Electricity Authority (CEA) technical codes are accelerating domestic certification requirements for solar traffic assemblies. Stakeholders must monitor evolving battery safety standards and interoperability protocols as procurement shifts from standalone hardware toward connected infrastructure ecosystems.
Market Dynamics
Lithium-iron-phosphate battery chemistry is extending operational autonomy in monsoon climates, shifting procurement criteria across tropical and subtropical deployment zones.
Growth Catalysts
- India's Ministry of Road Transport and Highways guidelines:Municipal procurement mandates now prioritize grid-independent intersection controls, accelerating rural highway corridor deployments.
- LED semiconductor cost compression:Universal retrofit compatibility enables rapid hardware turnover without full infrastructure replacement.
- Monsoon climate adaptation:Advances in deep-cycle battery management are concentrating demand in South India's Tamil Nadu and Karnataka states.
Market Restraints
- Panel supply concentration:Monocrystalline silicon sourcing clusters in specific manufacturing geographies, exposing buyers to input volatility.
- Technical autonomy limits:Microprocessor-driven load management systems face degradation thresholds in extreme humidity cycles.
- Grid parity hesitation:Temporary construction zone buyers weigh solar capital outlay against diesel generator rental flexibility.
Strategic Opportunities
- Emergency routing scenarios:Disaster response agencies seek rapidly deployable signal infrastructure for post-catastrophe traffic management.
- EU Green Deal procurement realignment:Member state infrastructure tenders now embed lifecycle carbon thresholds favoring photovoltaic assemblies.
- IoT convergence with adaptive timing:Municipal traffic management systems demand embedded wireless modules for remote diagnostic access.
Industry Challenges
- Interoperability protocol gaps:Legacy traffic management platforms resist seamless integration with new controller communication standards.
- Battery safety certification timelines:Evolving thermal runaway testing requirements delay product qualification cycles.
- Field technician skill scarcity:Photovoltaic-electrical hybrid systems require cross-trained maintenance personnel rarely available in rural deployment zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Traffic Light Market |
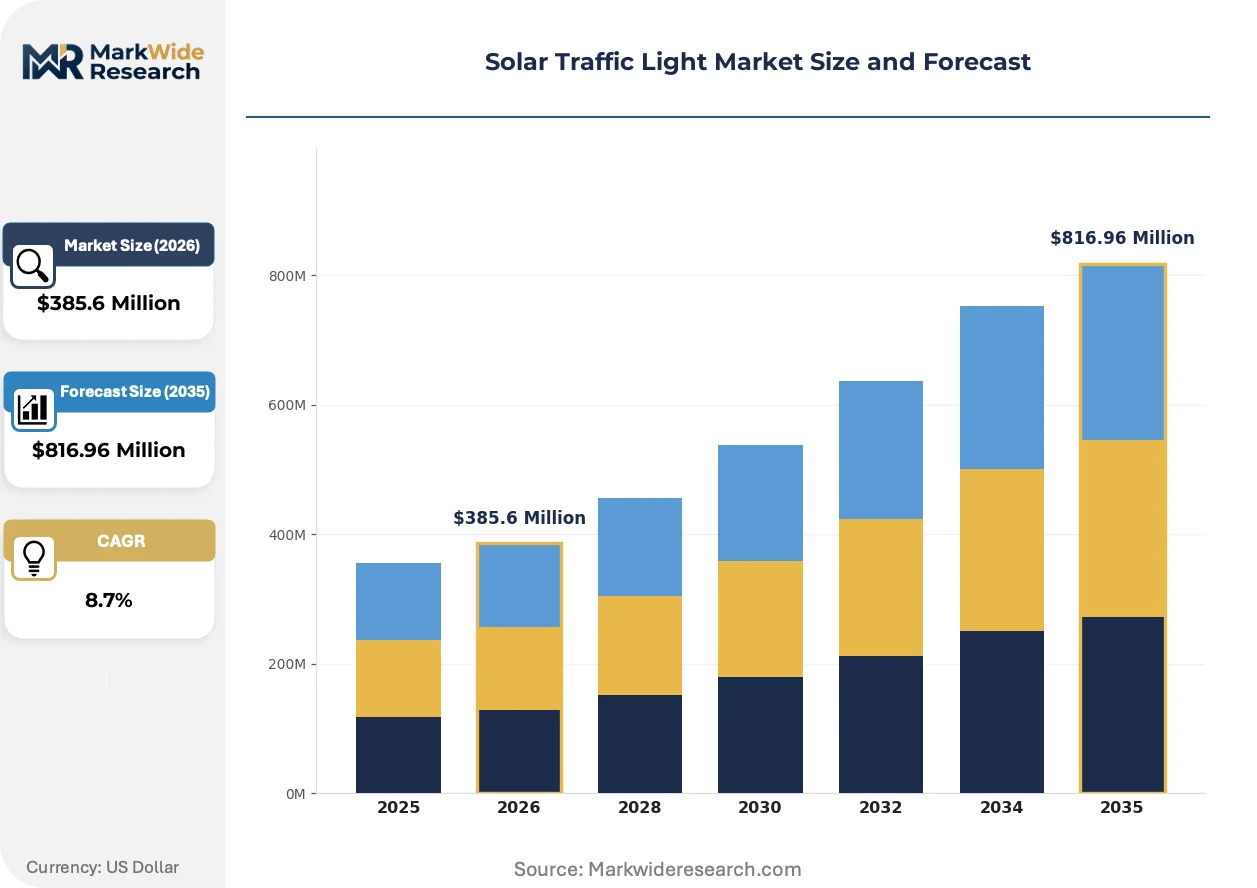
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Signals, Flashing Beacons, Pedestrian Signals, Traffic Control Devices Technology: Solar Photovoltaic, Wireless Communication, Sensor-Based, Intelligent Controllers End User: Municipalities, Transportation Authorities, Smart Cities, Construction Firms Installation Type: Standalone Systems, Integrated Solutions, Temporary Installations, Permanent Installations |
| Companies Covered | Swarco AG, Eaton Corporation, Siemens AG, Barron Lighting Group, Solar LED Solutions, Traffic Management LLC, TGS Traffic & Transport Solutions, Signalux, JINTRANIX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Traffic Light Market Trends and Innovations
Photovoltaic traffic infrastructure is pivoting from standalone hardware toward connected ecosystem integration, compressing the value chain around data-enabled service models.
Edge-computing signal controllers are decentralizing intersection management by embedding localized processing for adaptive timing algorithms. Municipal buyers in smart city programs adopt these units fastest, replacing centralized traffic management architectures with distributed decision nodes. This shift is decentralizing procurement authority from national highway agencies toward metropolitan technology departments.
India's Bureau of Indian Standards and Central Electricity Authority technical codes are tightening domestic certification requirements for solar traffic assemblies. Manufacturers must now demonstrate compliance with electromagnetic compatibility and material safety thresholds before tender eligibility. Domestic producers respond fastest, while import-dependent suppliers face extended qualification timelines.
After-sales service unbundling is fragmenting buyer-supplier relationships in the municipal segment. Cities now separate hardware acquisition from maintenance contracts, favoring vendors with localized technical support networks over integrated solution providers. This pattern concentrates in North American markets where extreme weather tolerance requirements demand rapid-response field service capabilities.
Solar Traffic Light Market Segmentation
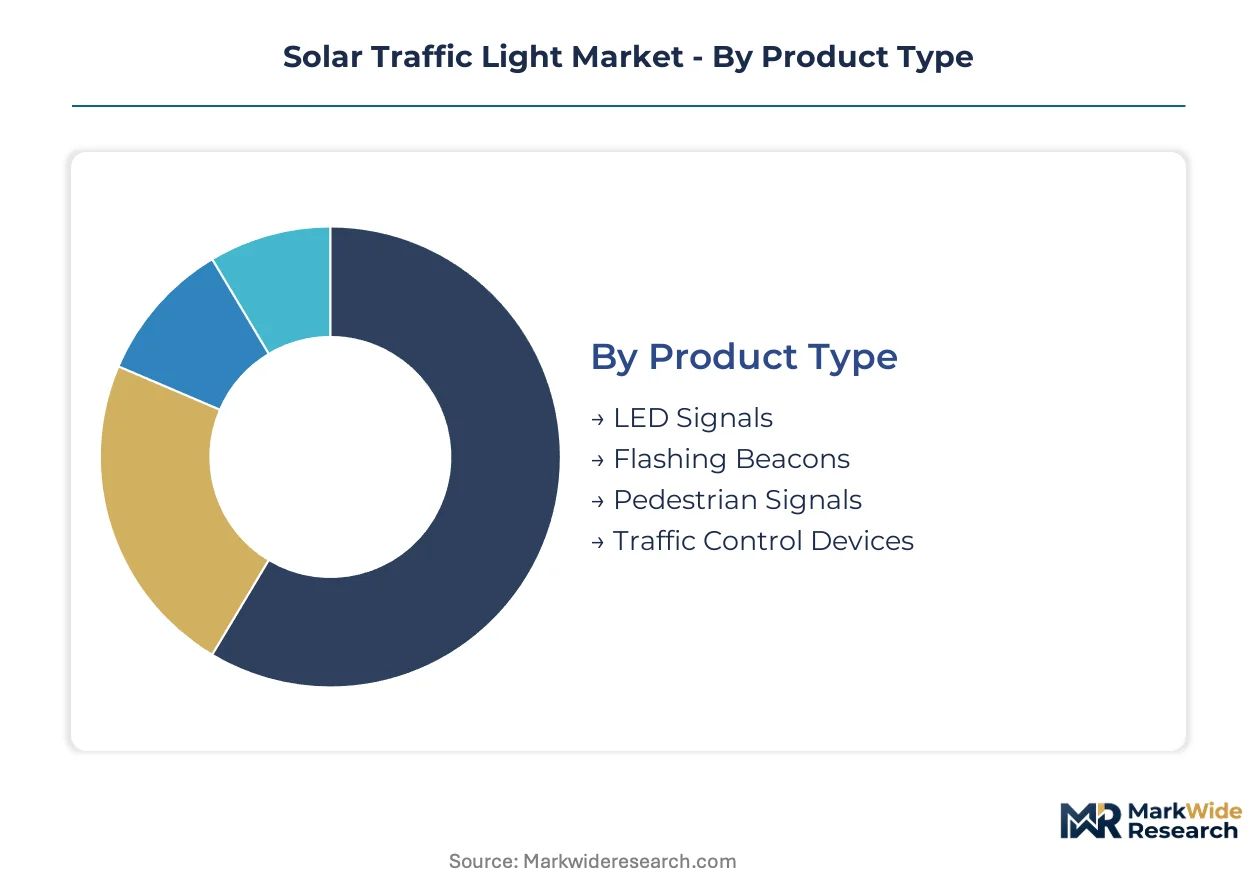
Segmentation in solar traffic infrastructure reveals how procurement authority, technical sophistication, and deployment duration reshape vendor-customer relationships. Buyers across these four dimensions exhibit divergent price sensitivity, integration requirements, and lifecycle service expectations that determine competitive positioning.
Product Type:
Cost tier separates retrofit-ready hardware from specialized signaling equipment requiring custom engineering.
- LED Signals:Semiconductor-based illumination arrays built on aluminum substrate heat sinks deliver 50,000+ hour operational life. Municipalities in Tamil Nadu and Karnataka prioritize these for rural highway retrofits where grid extension costs exceed solar capital outlay by factor of three.
- Flashing Beacons:High-intensity strobe modules with photovoltaic charging circuits serve warning applications at uncontrolled intersections and school zones. Transportation authorities in India's coastal states specify monsoon-rated enclosures with IP67 sealing against salt-laden humidity cycles.
- Pedestrian Signals:Countdown timer-integrated walk/don't walk displays with tactile pushbutton interfaces.
- Traffic Control Devices:Lane control signals, arrow indicators, and reversible flow systems for bridge and tunnel applications.
LED Signals lead volumes today; Intelligent Controllers within this hardware category are gaining share fastest.
Technology:
Application context determines whether buyers prioritize energy autonomy, data connectivity, or real-time responsiveness.
- Intelligent Controllers:Microprocessor-driven load management systems with adaptive timing algorithms and remote diagnostic telemetry. Smart Cities in EU member states embed these for congestion-responsive signal phasing under Green Deal procurement mandates with lifecycle carbon thresholds.
- Solar Photovoltaic:Monocrystalline silicon panel arrays with maximum power point tracking charge controllers and deep-cycle lithium-iron-phosphate storage. Standalone intersection deployments across India's Ministry of Road Transport and Highways corridors specify these for grid-independent operation exceeding 72 hours autonomy.
- Wireless Communication:Cellular and mesh-network modules enabling centralized traffic management system integration.
- Sensor-Based:Inductive loop, radar, and computer vision detection for vehicle and pedestrian presence activation.
Solar Photovoltaic anchors hardware procurement volumes; Intelligent Controllers are expanding most quickly as municipal buyers demand ecosystem integration.
End User:
Customer type governs contract structure, with capital availability and technical staffing determining bundled versus unbundled procurement.
- Municipalities:City and county traffic departments with established maintenance crews and centralized procurement processes. North American municipalities increasingly separate hardware acquisition from service contracts, favoring vendors with localized field technician networks over integrated providers.
- Smart Cities:Metropolitan technology departments managing IoT platform convergence across urban infrastructure systems. These buyers command premium positioning for controllers with embedded wireless modules and API-accessible diagnostic data streams.
- Transportation Authorities:State and provincial highway agencies with standardized specification regimes.
- Construction Firms:Temporary deployment buyers weighing diesel generator rental flexibility against solar capital outlay for work zone traffic control.
Municipalities concentrate procurement authority today; Smart Cities are climbing the fastest as metropolitan technology budgets expand.
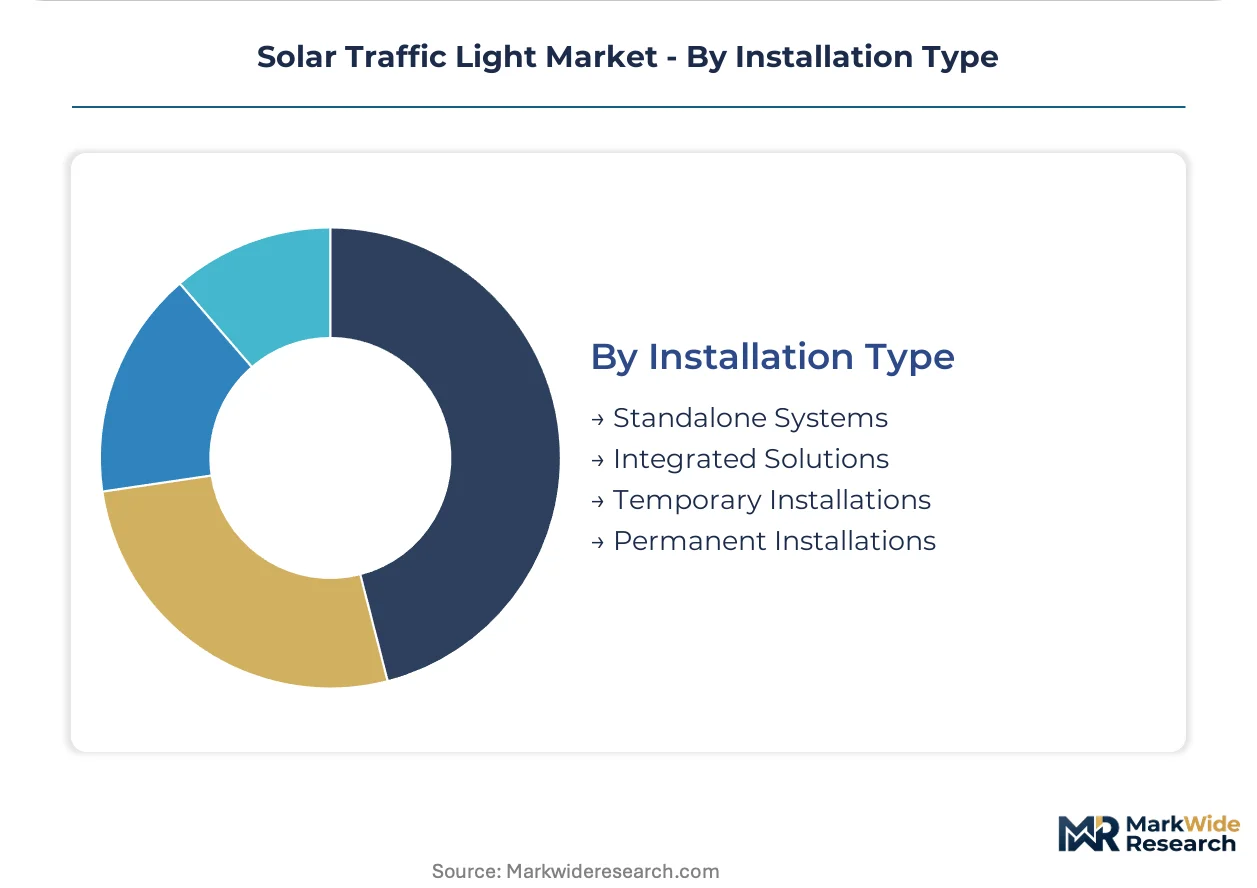
Installation Type:
Deployment duration reshapes buyer risk tolerance and vendor revenue recognition patterns.
- Standalone Systems:Self-contained photovoltaic, battery, and signal assemblies requiring no grid connection or external control infrastructure. India's rural highway corridors under Bureau of Indian Standards certification requirements specify these for locations where trenching distances exceed economic feasibility thresholds.
- Temporary Installations:Rapid-deploy trailer-mounted or skid-based systems for construction zones, emergency routing scenarios, and disaster response. Federal Highway Administration Manual on Uniform Traffic Control Devices shapes product specifications for these deployments in United States markets.
- Integrated Solutions:Photovoltaic assemblies designed for connection to municipal traffic management networks and centralized control systems.
- Permanent Installations:Fixed infrastructure with engineered foundations and utility-grade electrical enclosures for decades-long service life.
Standalone Systems lead deployment volumes today; Temporary Installations are gaining share fastest as disaster response agencies build rapidly deployable signal reserves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solar traffic infrastructure originated in European municipal experiments during the 1990s, then scaled through Indian rural electrification programs and North American emergency response procurement. Deployment patterns now diverge sharply by regulatory environment, climate adaptation requirements, and grid extension economics.
United States
Federal Highway Administration specifications under the Manual on Uniform Traffic Control Devices govern temporary installation standards for construction zone and disaster response deployments. State transportation departments in hurricane-prone Gulf Coast regions are building rapidly deployable signal reserves. Texas and Florida municipalities lead procurement volumes where grid extension costs exceed standalone solar capital outlay thresholds.
India
Bureau of Indian Standards and Central Electricity Authority technical codes are tightening electromagnetic compatibility and material safety certification requirements for tender eligibility. Ministry of Road Transport and Highways guidelines prioritize grid-independent intersection controls across rural highway corridors. Tamil Nadu and Karnataka states concentrate deployment activity where monsoon-adapted lithium-iron-phosphate battery systems extend operational autonomy.
Germany
EU Green Deal procurement mandates embed lifecycle carbon thresholds favoring photovoltaic assemblies in municipal infrastructure tenders. KBA technical standards intersect with CE marking requirements for electromagnetic compliance in traffic control device deployments. Bavarian and Baden-Württemberg metropolitan technology departments are retrofitting intelligent controllers with embedded wireless modules for adaptive signal timing.
China
MIIT industrial standards and GB certification requirements shape domestic manufacturing quality protocols for photovoltaic traffic equipment exports. Dual carbon policy targets are accelerating municipal procurement of grid-independent intersection controls in western provinces with unreliable grid infrastructure. Yangtze River Delta manufacturing clusters supply monocrystalline panel assemblies to Southeast Asian and Middle Eastern markets.
Brazil
ANVISA material safety regulations and national infrastructure concession frameworks govern traffic control device procurement for federal highway corridors. State transportation departments in São Paulo and Minas Gerais are piloting solar signals for remote intersection controls where diesel generator maintenance proves operationally prohibitive. Amazon basin deployment zones prioritize standalone systems with 72-hour battery autonomy during extended cloud cover periods.
Solar Traffic Light Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the solar traffic light value chain, creating a tiered structure where integrated solution providers face unbundled procurement pressure from municipal buyers. The vendor base separates into photovoltaic hardware specialists, intelligent controller platform developers, and full-system integrators with field service networks. Three archetypes dominate: Austrian and German engineering-led manufacturers with embedded wireless capabilities, North American standalone system engineers optimized for extreme weather tolerance, and Asian panel-battery assemblers competing on component cost. Competitive moves concentrate on geographic certification expansion and maintenance contract unbundling to capture recurring revenue streams.
Within the European engineering tier, Swarco AG and Siemens AG exemplify contrasting strategic positions—Swarco leverages Austrian manufacturing integration for wireless-enabled signal assemblies, while Siemens anchors through intelligent controller platforms designed for municipal traffic management system convergence. Eaton Corporation occupies the North American standalone system segment with engineered assemblies targeting extreme weather tolerance requirements. These three represent the dominant competitive archetypes shaping procurement outcomes across regulatory environments.
| Leading Market Players |
|---|
| Swarco AG |
| Eaton Corporation |
| Siemens AG |
| Barron Lighting Group |
| Solar LED Solutions |
| Traffic Management LLC |
| TGS Traffic & Transport Solutions |
| Signalux |
| JINTRANIX |
| Others |
Pricing and Supply Chain Analysis
Monocrystalline silicon panel costs cascade through three distinct pricing tiers before reaching municipal procurement officers, with battery chemistry grade and certification tier determining final positioning within each bracket.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates intelligent controller platforms with embedded wireless modules from basic LED signal arrays and temporary deployment hardware. Price differentiation hinges on Bureau of Indian Standards certification tier and after-sales service bundling, with unbundled maintenance contracts compressing margins for integrated solution providers. Cost compression in economy-tier flashing beacons is intensifying because Asian panel-battery assemblers are flooding export markets with non-certified alternatives. Construction firms exhibit highest price sensitivity, while Smart Cities command premium positioning for API-accessible diagnostic data streams.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta and Bavarian manufacturing clusters anchor hub-and-spoke patterns for photovoltaic assemblies and intelligent controller platforms respectively. Geographic supply concentration centers on China for monocrystalline silicon panels, South Korea for lithium-iron-phosphate cells, and Germany for microprocessor-driven load management systems. Raw material dependencies draw from polysilicon feedstock, rare-earth magnet components for charge controllers, and aluminum substrate heat sinks. Single-source vulnerability in monocrystalline silicon sourcing exposes buyers to input volatility. Distribution runs through municipal procurement channels in India, federal highway agency tenders in the United States, and metropolitan technology departments in EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in solar traffic infrastructure rests on lithium-iron-phosphate battery cost curves and the shift toward premium-tier intelligent controllers with embedded wireless capabilities.
For Market Incumbents: Anticipate unbundled procurement pressure from North American municipalities by building localized field technician networks faster than hardware commoditization erodes service revenue. Certification investment in India's tightening Bureau of Indian Standards electromagnetic compatibility requirements defends tender eligibility against domestic producers. Vertical integration into lithium-iron-phosphate cell sourcing secures supply continuity as battery chemistry becomes the primary cost determinant. For New Entrants and Emerging Players: Disaster response agencies represent the most penetrable buyer archetype, with rapidly deployable temporary installation reserves underserved by incumbent field service networks. Target Amazon basin deployment zones in Brazil where 72-hour battery autonomy requirements exceed local maintenance capabilities. Go-to-market through transportation authority pilot programs in São Paulo and Minas Gerais bypasses established municipal procurement relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where field technician skill scarcity intersects with after-sales service unbundling, favoring acquisition of asset-light regional maintenance networks over capital-heavy manufacturing assets. Long-term viability frames around connected ecosystem integration rather than standalone hardware volume. Signal to watch: interoperability protocol standardization that collapses controller platform fragmentation and rewards scale players with API-accessible data streams.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Module Integration | Embedded cellular and mesh-network capabilities enable Smart City traffic management system convergence under EU Green Deal mandates. |
| Battery Chemistry Upgrade | Lithium-iron-phosphate adoption extends operational autonomy in monsoon climates across Tamil Nadu and Karnataka corridors. |
| Regional Certification Expansion | Bureau of Indian Standards compliance unlocks tender eligibility in India's Ministry of Road Transport and Highways procurement pipeline. |
| After-Sales Service Unbundling | Separate maintenance contracts capture recurring revenue as North American municipalities fragment integrated solution relationships. |
| Edge-Computing Controller Development | Localized processing for adaptive timing algorithms displaces centralized traffic management architectures in metropolitan technology departments. |
Research Methodology
Multiple input streams — municipal procurement database analysis, regulatory filing review, and field technical documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with traffic management system engineers, municipal technology officers, highway agency specification writers, and photovoltaic system integrators were validated against secondary sources including Federal Highway Administration Manual on Uniform Traffic Control Devices revisions, Bureau of Indian Standards electromagnetic compatibility filings, and EU Green Deal procurement mandate documentation.
Data-stream reconciliation anchored volume and value outputs across product type, technology tier, end user category, and installation duration segmentation dimensions. CAGRs were derived from installed base growth trajectories and replacement cycle analysis rather than top-down market sizing alone. Forecast inputs incorporated lithium-iron-phosphate battery cost curves, LED semiconductor price compression rates, and municipal budget allocation patterns for grid-independent infrastructure.
Underlying measurement precision varies by segment; LED Signals and Solar Photovoltaic hardware carry tighter precision than emerging Intelligent Controller categories where platform standardization remains incomplete. Forecasts reflect documented assumptions around regulatory certification timelines, battery chemistry adoption rates, and interoperability protocol convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Global Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Solar Tree Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Solar Showers Market