
 Global BIPV Glass Market | 2026-2036
Global BIPV Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global BIPV Glass Market Analysis
Buyer concentration across commercial real estate developers is restructuring procurement patterns for BIPV glass installations. AGC Inc. leverages its float glass manufacturing base to supply large-format photovoltaic substrates for curtain wall projects. Saint-Gobain anchors European demand through specialized coated glass production lines serving certified green building specifications. First Solar competes in utility-scale adjacent markets but extends thin-film expertise into building-integrated applications through partner channel programs.
Building-integrated photovoltaic glass combines transparent or semitransparent solar cells laminated between tempered glass layers, typically achieving 10-20% conversion efficiency while transmitting controlled daylight. Crystalline silicon technology dominates current installations due to proven efficiency metrics and established supply chains. Thin-film BIPV glass represents the fastest-expanding technology segment as amorphous silicon and cadmium telluride formulations improve low-light performance for vertical facade applications. Semitransparent product variants command premium positioning in commercial building segments where aesthetic integration and daylight harvesting requirements overlap.
The EU Green Deal and REACH chemical compliance frameworks shape product formulation standards for BIPV glass sold across European member states. China's MIIT establishes domestic efficiency benchmarks and manufacturing quality protocols through GB standards certification. The US EPA Energy Star program and state-level stretch codes in California and New York directly influence specification requirements for photovoltaic building materials. Stakeholders must monitor evolving carbon-border adjustment mechanisms and local content thresholds that will determine competitive access across major installation markets.
Market Dynamics
The BIPV glass market is restructuring around net-zero building mandates that compel developers to embed photovoltaic capacity directly into building envelopes rather than retrofitting conventional structures. This architectural integration requirement is compressing traditional procurement cycles and forcing glass manufacturers to certify products against energy performance standards before specification.
Growth Catalysts
- EU Green Deal implementation:The EU Green Deal's building renovation targets mandate photovoltaic-ready facades for new commercial construction across member states. Developers in Germany, France, and the Netherlands must now integrate renewable generation into building designs.
- Thin-film efficiency gains:Amorphous silicon and cadmium telluride formulations now deliver viable power output in low-light vertical orientations. These chemistries outperform crystalline alternatives on east-west facades where direct sun exposure is limited.
- Commercial real estate procurement:Large-scale developers are consolidating supplier relationships to secure volume commitments for multi-project portfolios. This concentration accelerates specification of certified BIPV systems over conventional curtain walls.
Market Restraints
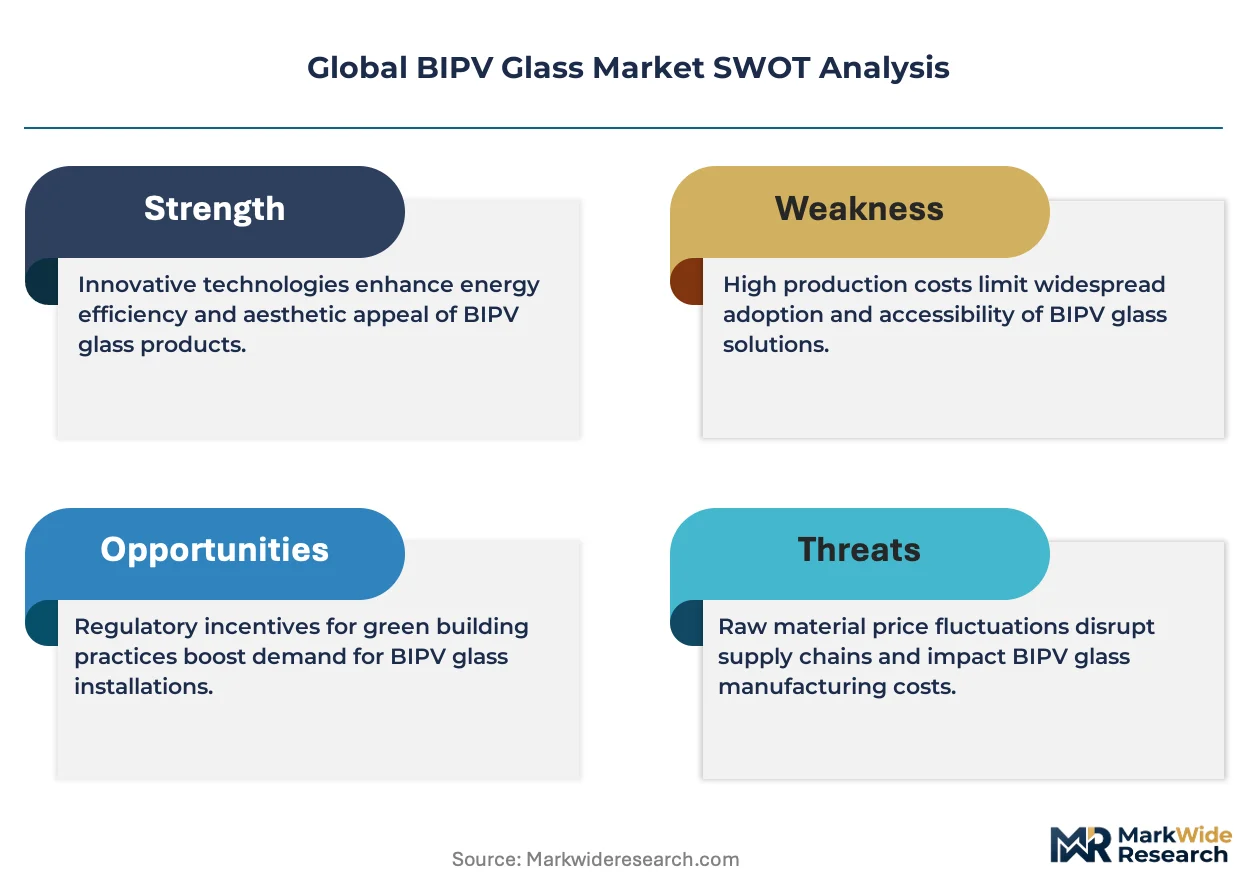
- Silver and indium input volatility:Thin-film manufacturing relies on silver for electrical contacts and indium for transparent conductive oxides. Price swings in these commodities compress margin predictability for glass laminators.
- Float glass supply concentration:High-transparency photovoltaic-grade substrates depend on a concentrated base of flat glass manufacturers. Geographic concentration of float glass capacity creates vulnerability in substrate availability.
- Electrical conversion efficiency ceilings:Semitransparent BIPV variants sacrifice power density for daylight transmission. This technical trade-off limits applicability in high-rise residential towers where envelope area is constrained.
Strategic Opportunities
- India's green building acceleration:The Bureau of Indian Standards is finalizing BIPV performance codes under its renewable energy mission. Early entrants can establish specification relationships before mandatory standards take effect.
- Automotive glass convergence:Vehicle-integrated photovoltaics are emerging as a secondary demand channel. Glass suppliers with automotive certification can extend BIPV expertise into electric vehicle sunroof applications.
- US Inflation Reduction Act incentives:The IRA's domestic content bonuses for clean energy manufacturing create favorable economics for BIPV glass produced within US supply chains. This policy tailwind supports captive production investments.
Industry Challenges
- Building physics simulation expertise:BIPV specification requires integrated thermal, optical, and electrical modeling. The shortage of engineers trained in multi-physics simulation extends project timelines and increases design risk.
- Dual certification complexity:Products must simultaneously satisfy structural glass standards and electrical safety codes. The sequential testing protocols create bottlenecks that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global BIPV Glass Market |
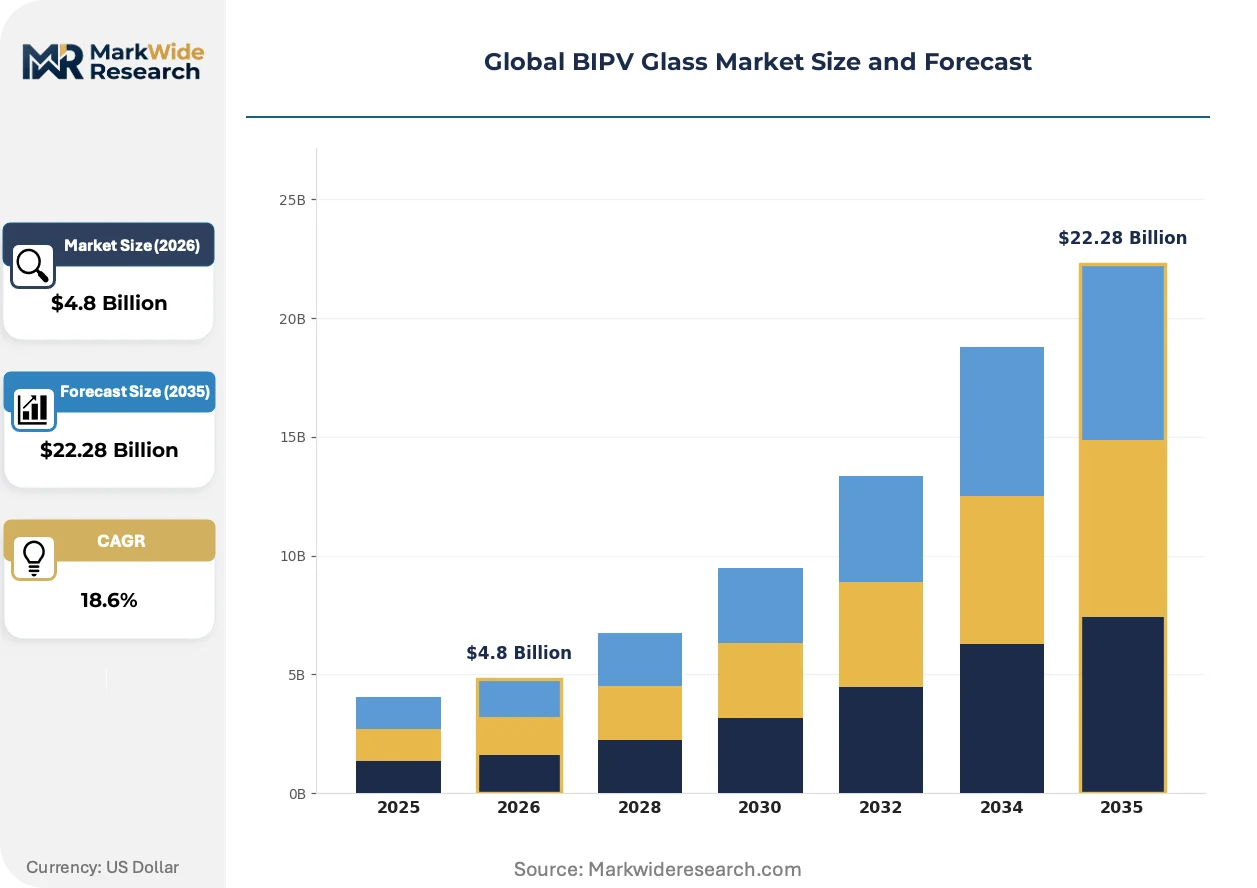
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semitransparent, Transparent, Opaque, Double-Glazed Application: Commercial Buildings, Residential Buildings, Facades, Rooftops Technology: Thin Film, Crystalline Silicon, Organic Photovoltaics, Building-Integrated End User: Architects, Builders, Developers, Homeowners |
| Companies Covered | AGC Inc., Saint-Gobain, Onyx Solar Group LLC, Canadian Solar, First Solar, Nippon Sheet Glass Co., Ltd., Wuxi Suntech Power Co., Ltd., Tesla, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global BIPV Glass Market Emerging Trajectories
Building-integrated photovoltaic technology is maturing from architectural novelty to standard envelope component. This transition is compressing product development cycles and forcing convergence between glass manufacturing and semiconductor packaging disciplines.
Perovskite-silicon tandem architectures are consolidating research investment across photovoltaic glass developers. These dual-junction cells capture broader solar spectra than single-junction alternatives. Commercial facade developers in Japan and South Korea are piloting tandem BIPV installations for 2026-2027 completion. The technology is consolidating competitive positioning around efficiency-per-square-meter rather than cost-per-watt metrics.
China's MIIT has tightened GB standards certification requirements for BIPV glass sold under national renewable energy quotas. The revised protocols mandate accelerated aging tests and fire resistance verification. Domestic manufacturers must now recertify product lines against the 2024 efficiency benchmarks. European exporters face additional conformity assessment steps to maintain market access.
Architects are specifying performance-guaranteed energy output contracts rather than component procurement. This transfers operational risk from building owners to system integrators. Large European engineering firms are absorbing this liability through captive insurance vehicles. The model is most advanced in Germany and Austria where energy service company frameworks are legally established.
Global BIPV Glass Market Segmentation
BIPV glass procurement diverges sharply across buyer types and building physics requirements. Architects prioritize optical performance and aesthetic integration, while developers optimize for energy yield per envelope dollar.
Product Type:
Transparency level determines both energy conversion efficiency and daylighting performance, forcing trade-offs between power density and occupant comfort.
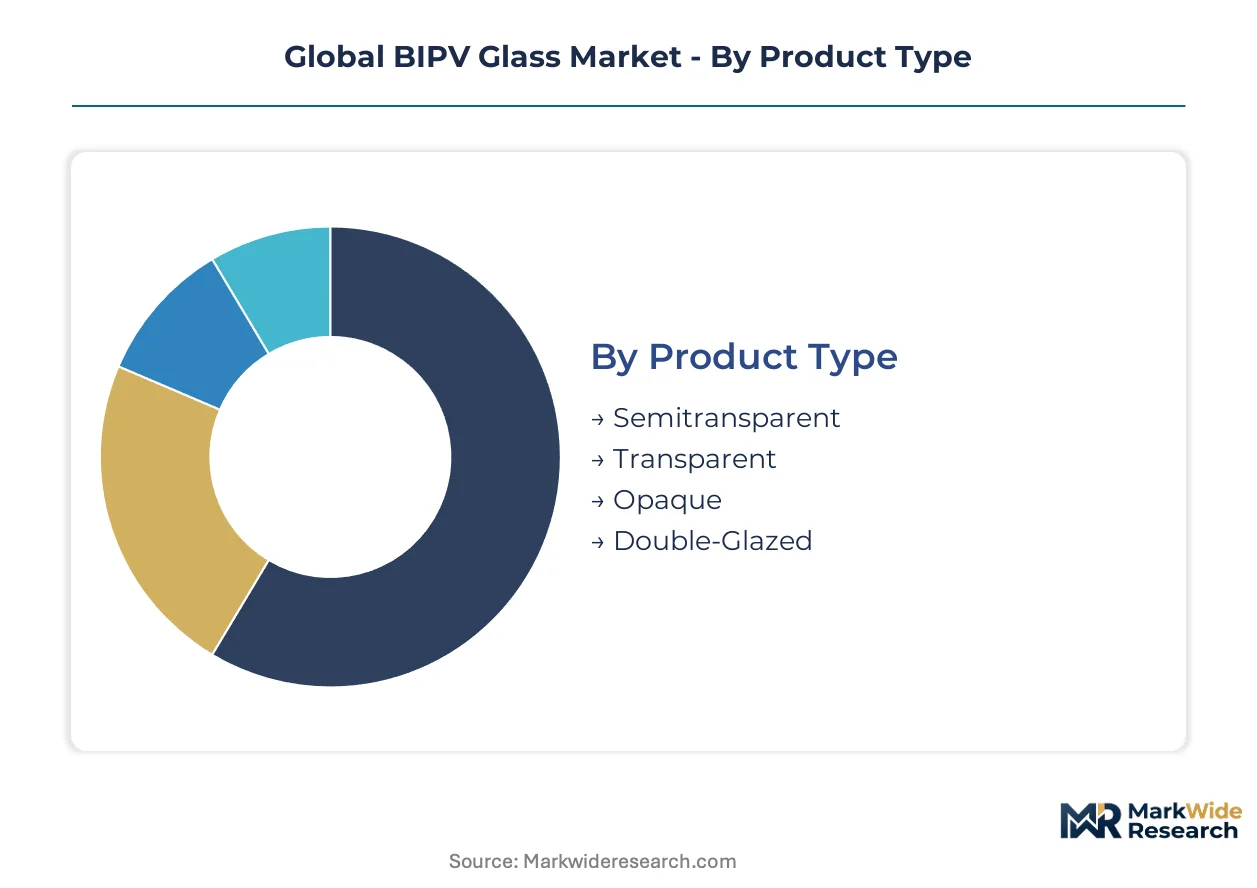
- Semitransparent:Laminated cells with patterned or partial coverage achieve 10-15% efficiency while transmitting 20-40% visible light. Demand concentrates in German and Dutch commercial facades where EU Green Deal mandates require renewable generation without sacrificing daylight access.
- Transparent:Micro-cell arrays and selective wavelength harvesting deliver see-through photovoltaic performance at 5-8% efficiency. Japanese developers specify these for high-rise atriums and lobby spaces where uninterrupted views are non-negotiable.
- Opaque:Maximum power density applications use fully covered cell configurations on spandrel panels and non-vision zones.
- Double-Glazed:Insulated BIPV units combine thermal performance with generation, targeting cold-climate retrofits in Scandinavia and Canada.
Volume sits with Opaque installations; growth tilts toward Semitransparent as facade-integrated mandates expand.
Application:
Building envelope position dictates cell orientation, thermal loading, and electrical interconnection complexity.
- Commercial Buildings:Curtain wall and skylight integration dominate procurement volumes. Large-format glass laminators in China supply standardized modules for office towers across Shenzhen, Shanghai, and Beijing under MIIT efficiency benchmarks.
- Facades:Vertical installation angles favor thin-film chemistries with superior low-light response. German KfW green building program subsidies accelerate replacement of conventional curtain walls in Frankfurt and Munich.
- Residential Buildings:Smaller project scales and distributed decision-making fragment procurement patterns.
- Rooftops:Tilted applications retain crystalline silicon dominance due to direct irradiance availability.
Commercial Buildings command current volume; Facades are climbing the fastest as net-zero codes tighten.
Technology:
Cell chemistry selection hinges on orientation, climate, and architectural constraints rather than cost-per-watt alone.
- Thin Film:Amorphous silicon and cadmium telluride formulations outperform crystalline alternatives in diffuse light and high-temperature conditions. Germany's vertical facade market anchors thin-film demand through specialized supply chains.
- Crystalline Silicon:Mature supply chains and proven 18-22% efficiency sustain rooftop and optimal-angle applications. Chinese GB standards certification reinforces manufacturing quality protocols for export markets.
- Organic Photovoltaics:Solution-processed cells enable flexible substrates and custom shapes for architectural specialty applications.
- Building-Integrated:System-level integration approaches combine multiple cell technologies with thermal and structural functions.
Crystalline Silicon holds installed base dominance; Thin Film is gaining share fastest in facade-specific specifications.
End User:
Decision authority varies across project phases, with early-stage influencers often diverging from final procurement authority.
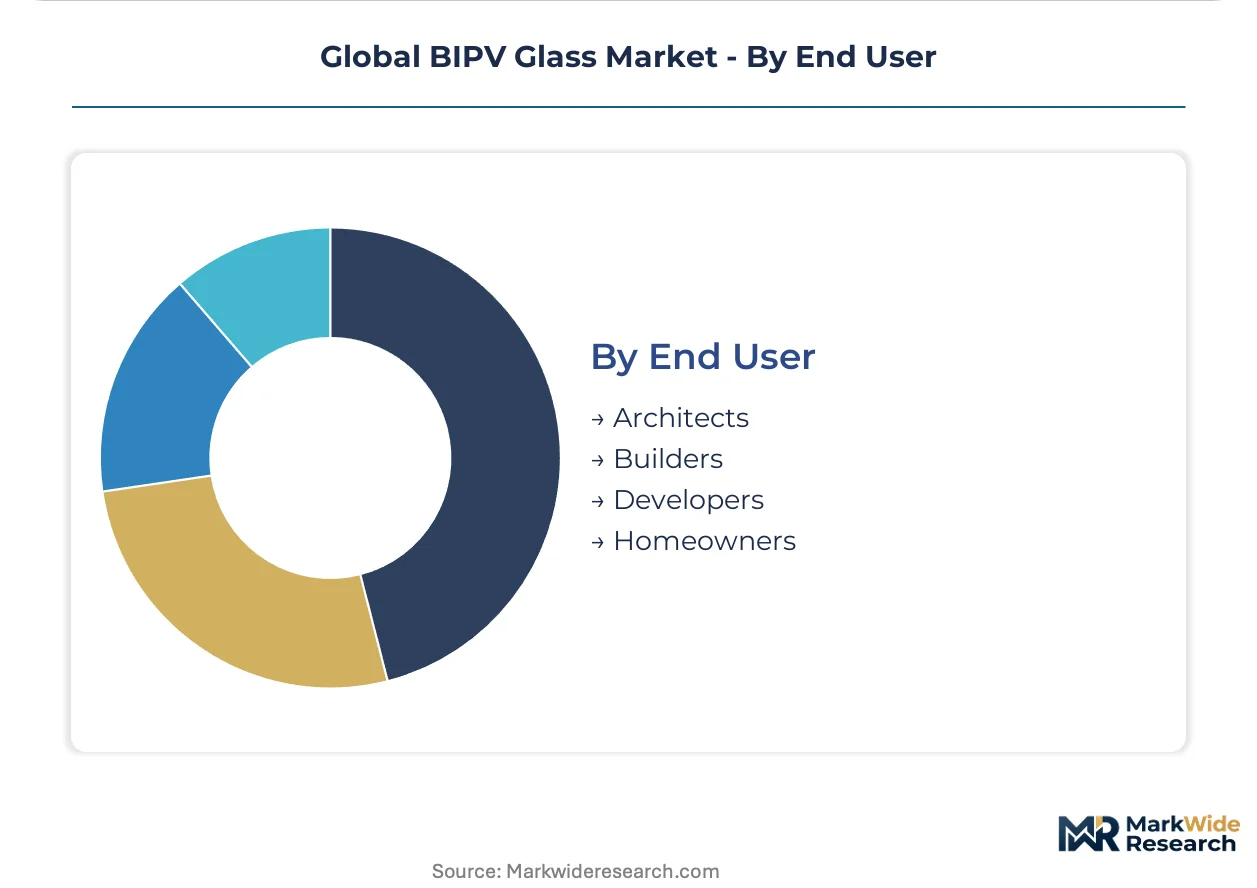
- Architects:Design-phase specification power centers on optical and aesthetic performance criteria. Japanese and South Korean firms increasingly mandate performance-guaranteed energy output contracts rather than component procurement.
- Developers:Portfolio-scale procurement concentrates supplier relationships and accelerates certified system adoption. US Inflation Reduction Act domestic content bonuses reshape sourcing decisions for multi-project pipelines.
- Builders:Installation-phase coordination requirements favor standardized module formats and simplified electrical interconnection.
- Homeowners:Distributed decision-making and information asymmetries slow adoption in residential segments.
Builders handle physical volume; Developers are driving the steepest expansion trajectory through consolidated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building developers in Germany, China, and the United States are consolidating procurement relationships for facade-integrated photovoltaic systems as net-zero mandates tighten. Demand concentration across these three markets is compressing specification cycles and forcing glass manufacturers to certify products against energy performance standards before project award.
China
MIIT efficiency benchmarks and GB standards certification drive procurement of large-format BIPV substrates for office towers across Shenzhen, Shanghai, and Beijing. The 2024 revised protocols mandate accelerated aging tests and fire resistance verification. Domestic manufacturers in the Yangtze River Delta are recertifying product lines against stricter efficiency thresholds.
Germany
The KfW green building program and local energy codes accelerate replacement of conventional curtain walls in Frankfurt and Munich. Thin-film BIPV demand concentrates here due to superior low-light performance on vertical facades. Engineering firms in Berlin and Hamburg are pioneering performance-guaranteed energy output contracts that transfer operational risk from building owners to system integrators.
United States
State-level stretch codes in California and New York directly influence specification requirements for photovoltaic building materials. The EPA Energy Star program shapes product formulation standards. The Inflation Reduction Act's domestic content bonuses for clean energy manufacturing create favorable economics for BIPV glass produced within US supply chains, supporting captive production investments in the Southwest and Southeast.
Japan
Commercial facade developers in Tokyo and Osaka are piloting perovskite-silicon tandem BIPV installations for 2026-2027 completion. METI research funding consolidates competitive positioning around efficiency-per-square-meter metrics. Architects increasingly mandate performance-guaranteed energy output contracts rather than component procurement.
India
The Bureau of Indian Standards is finalizing BIPV performance codes under the national renewable energy mission. Early entrants are establishing specification relationships in Maharashtra and Gujarat before mandatory standards take effect. Central Electricity Authority guidelines are shaping interconnection protocols for building-integrated generation.
Global BIPV Glass Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive and specialty architectural applications. The market structures around three tiers: float glass manufacturers with photovoltaic substrate capabilities, specialized coated glass producers serving certified green building specifications, and thin-film technology developers extending expertise into building-integrated formats. Dominant competitive moves include strategic partnerships between glass laminators and semiconductor packaging specialists, plus capacity expansion into domestic supply chains to capture IRA and EU Green Deal incentives.
Among Japanese and European fabricators, AGC Inc., Saint-Gobain, and Nippon Sheet Glass Co., Ltd. exemplify the established tier. AGC leverages its float glass manufacturing base to supply large-format substrates. Saint-Gobain anchors European demand through specialized production lines. Nippon Sheet Glass occupies a position within the Asia-Pacific supply concentration. Thin-film specialists like First Solar represent a distinct archetype, competing in utility-scale adjacent markets while extending expertise into building-integrated applications through partner channel programs.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain |
| Onyx Solar Group LLC |
| Canadian Solar |
| First Solar |
| Nippon Sheet Glass Co., Ltd. |
| Wuxi Suntech Power Co., Ltd. |
| Tesla |
| Trina Solar |
| Others |
Supply Flow & Price Mechanics
Captive integration into float glass manufacturing anchors both supply security and pricing power for BIPV glass laminators serving EU Green Deal and IRA-mandated projects. AGC Inc. and Saint-Gobain leverage in-house substrate production to buffer margin pressure from silver and indium volatility while commanding premium positioning for certified facade systems.
Pricing Analysis
Volume concentrates in opaque spandrel configurations where crystalline silicon dominates, while margins expand fastest in semitransparent variants for German and Dutch commercial facades. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels differentiates offerings, with EU Green Deal and MIIT GB standards certification commanding substantial premiums. Cost compression in standard tiers is intensifying as Chinese manufacturers expand float glass capacity and thin-film efficiency gains reduce per-watt production costs. Commercial real estate developers show lowest price sensitivity due to portfolio-scale procurement and net-zero mandate compliance requirements, while residential builders remain most price-constrained.
Supply Chain Analysis
The US Inflation Reduction Act's domestic content bonuses and EU Green Deal local manufacturing incentives are reshaping sourcing decisions toward captive production in North America and Europe. Float glass substrate supply concentrates in China, Germany, and the United States, with high-transparency photovoltaic-grade output tethered to concentrated flat glass manufacturing bases. Silver for electrical contacts, indium for transparent conductive oxides, and tempered glass laminates constitute critical input dependencies. Single-source vulnerability in indium supply from Chinese refineries poses structural risk to thin-film BIPV margins. Distribution runs through direct specification relationships with commercial developers and engineering firms rather than traditional building materials wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance costs under the EU Green Deal, China's MIIT GB standards, and US IRA domestic content rules erect barrier-to-entry moats favoring certified incumbents with captive manufacturing and established specification relationships.
For Market Incumbents: To counter thin-film efficiency gains by cadmium telluride specialists, crystalline silicon leaders should backward integration into perovskite-silicon tandem R&D and expand captive float glass capacity in US Southeast and Southwest to capture IRA incentives. Certification investment against evolving fire resistance and accelerated aging protocols in China and Europe reinforces specification lock-in. For New Entrants and Emerging Players: Launch via performance-guaranteed energy output contracts targeting India's pre-mandatory BIPV code window in Maharashtra and Gujarat, where Bureau of Indian Standards finalization creates first-mover specification opportunities. Automotive glass certification for electric vehicle sunroof integration offers the most penetrable adjacent channel, leveraging existing safety glass expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to float glass majors seeking photovoltaic substrate capabilities and semiconductor packaging specialists pursuing building-integrated formats. Long-term viability favors vertically integrated players with dual structural glass and electrical safety certification spanning the 5-10 year regulatory tightening horizon. Watch perovskite-silicon tandem pilot completion rates in Japan and South Korea as inflection indicators for next-generation technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Development | METI-funded Japanese pilots target efficiency-per-square-meter leadership for 2026-2027 facade completions. |
| Domestic Content Compliance Investment | IRA bonuses reward US-based float glass and laminating capacity to secure developer procurement. |
| Performance-Guaranteed Contract Structuring | German engineering firms absorb operational risk through captive insurance vehicles. |
| Automotive Glass Certification Extension | Vehicle-integrated photovoltaics open secondary demand channel for BIPV suppliers. |
| Dual Certification Acceleration | Parallel structural glass and electrical safety testing reduces market entry bottlenecks. |
Methodological Framework
Independent corroboration across primary interviews with facade engineers, commercial development procurement leads, glass laminator technical directors, and thin-film semiconductor packaging specialists underwrites the qualitative findings. Secondary validation draws from MIIT GB standards documentation, EU Green Deal building renovation target disclosures, US EPA Energy Star product specifications, and customs trade data for float glass and silver/indium inputs. Bottom-up project pipeline analysis and top-down regulatory mandate sizing triangulate market scope.
Comparable historical reference periods across building-integrated photovoltaic deployment cycles anchor the projection horizon. The analytical framework models segmentation across transparency level, application envelope position, cell chemistry technology, and end-user decision authority. CAGRs derive from regulatory mandate phasing, efficiency improvement curves, and substitution elasticity against conventional curtain walls. Forecast inputs include KfW green building program subsidy trajectories and IRA domestic content bonus utilization rates.
Silver and indium commodity volatility, perovskite-silicon tandem commercialization delays, and carbon-border adjustment mechanism implementation timing are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Autoclave Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Hybrid Power System Market