
 China Solar Photovoltaic Market | 2026-2036
China Solar Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
China Solar Photovoltaic Market Outlook
Utility-scale deployment is decoupling from distributed rooftop generation as China's state grid corporations prioritize centralized solar parks over fragmented residential arrays. LONGi Solar anchors wafer supply through in-house production of high-purity silicon ingots. JinkoSolar dominates module exports with vertically integrated cell-to-panel manufacturing. Trina Solar specializes in tracker-integrated systems for desert and agricultural dual-use installations.
China Solar Photovoltaic refers to semiconductor devices that convert sunlight into direct current electricity through p-n junction physics, with monocrystalline cells achieving conversion efficiencies above 24% through passivated emitter and rear contact architectures. These systems serve electricity generation for grid-connected power plants, commercial rooftops, and off-grid rural electrification. Bifacial modules capture reflected light from ground surfaces, extending yield per watt-peak in high-albedo environments. HJT technology commands premium positioning due to lower temperature coefficients and simplified manufacturing flows. Utility-scale application segments absorb the dominant share of annual module shipments as provincial governments auction gigawatt-scale project rights.
MIIT sets national standards for photovoltaic product quality and cell efficiency thresholds, while NMPA oversees environmental compliance across polysilicon refining operations. GB standards mandate fire resistance and mechanical load testing for modules deployed in high-wind corridors. MEE enforces carbon intensity caps that push manufacturers toward renewable-powered production lines. Stakeholders must track how provincial grid integration quotas and interconnection tariff reforms reshape project economics across China's western transmission zones.
Market Dynamics
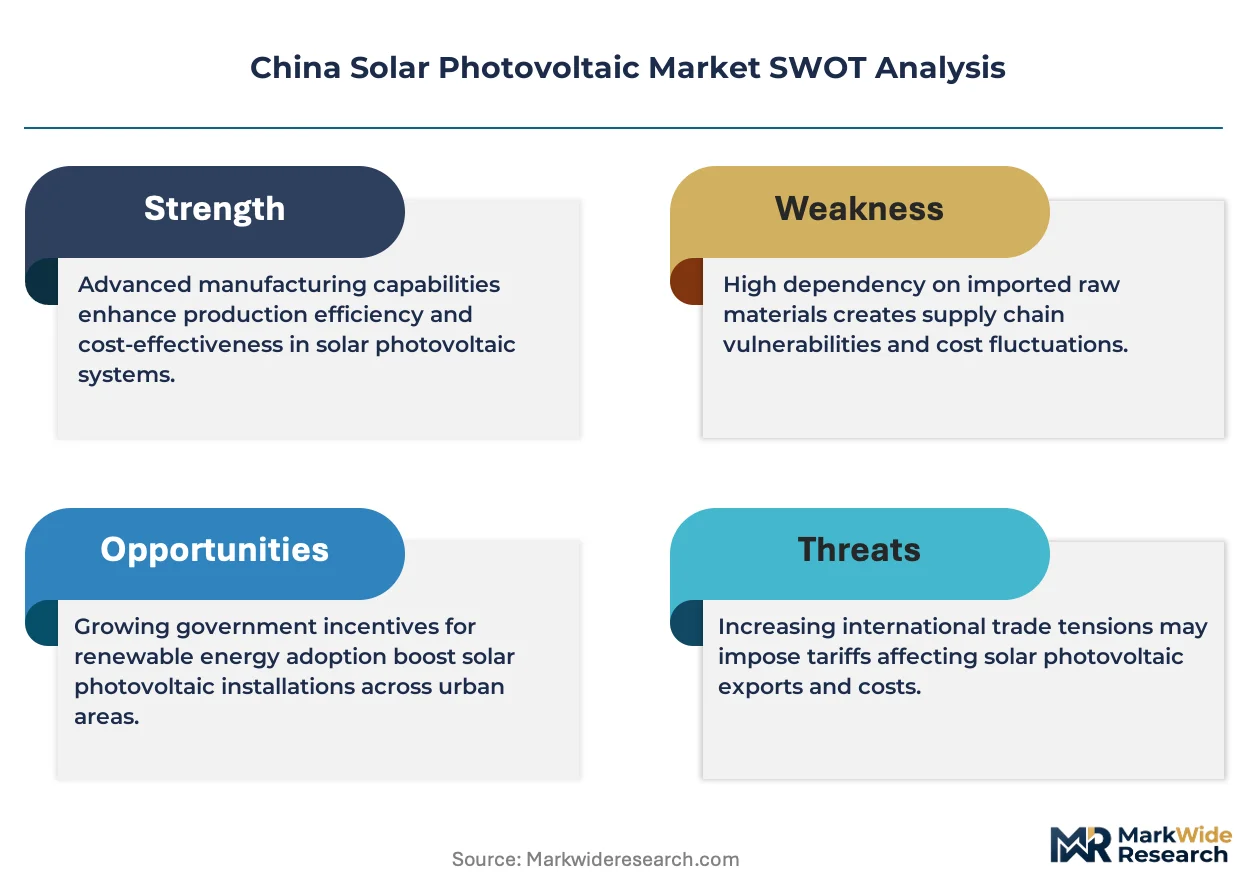
China's n-type cell migration is compressing p-type capacity economics as MEE carbon intensity caps force polysilicon smelters toward renewable-powered arc furnaces, redrawing the competitive map for wafer producers.
Growth Catalysts
- Dual Carbon Goals:MEE mandates for 2030 peak emissions are accelerating retirements of coal-powered polysilicon capacity and redirecting capital toward green hydrogen reduction furnaces.
- Utility-Scale Auctions:Provincial grid corporations in Jiangsu and Qinghai are tendering gigawatt-scale project rights with preferential interconnection tariffs for bifacial tracker installations.
- Passivated Emitter Architectures:Cell efficiency thresholds above 24% are unlocking premium pricing tiers for monocrystalline wafers with tunnel oxide passivated contact layers.
Market Restraints
- Polysilicon Input Volatility:Metallurgical-grade silicon prices swing with Xinjiang smelter output curbs, compressing margin predictability for ingot pullers.
- Western Module Tariffs:Anti-dumping duties in the US and EU are diverting export volumes toward Southeast Asian assembly plants, fragmenting shipment logistics.
- Grid Integration Bottlenecks:Ultra-high voltage transmission corridors from Gansu and Inner Mongolia face right-of-way disputes that delay project commissioning.
Strategic Opportunities
- Agricultural Dual-Use Arrays:Tracker-integrated systems over greenhouse complexes in Shandong are opening revenue streams from both electricity sales and crop yield premiums.
- HJT Technology Convergence:Heterojunction cell stacks paired with copper-plated metallization are reducing silver paste dependence while lifting conversion efficiency above 25%.
- MIIT Efficiency Standards:Mandatory module quality tiers are creating certification-driven segmentation that rewards domestic manufacturers with in-house testing laboratories.
Industry Challenges
- Process Engineer Scarcity:Talent pipelines for atomic layer deposition technicians and PERC line operators lag capacity expansion timelines in Ningxia manufacturing zones.
- GB Standards Compliance:Fire resistance testing for modules in high-wind corridors requires 12-18 month certification cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Solar Photovoltaic Market |
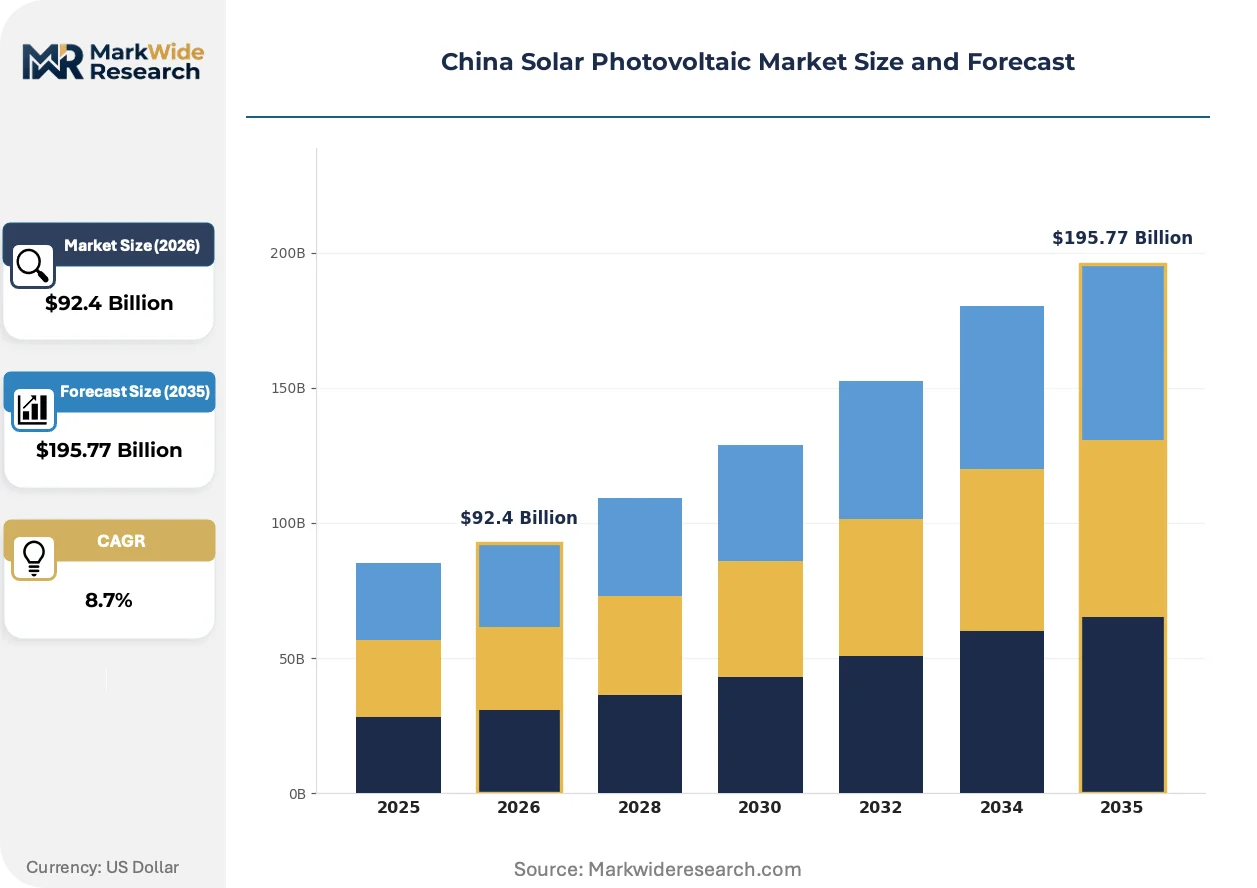
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin Film, Bifacial Application: Residential, Commercial, Industrial, Utility Scale Technology: CPV, PERC, TOD, HJT End User: Households, Businesses, Government, Energy Producers |
| Companies Covered | JinkoSolar, LONGi Solar, Trina Solar, JA Solar, Tongwei Solar, Canadian Solar, Risen Energy, GCL System Integration, Chint New Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Solar Photovoltaic Market Strategic Shifts
Cell architecture migration and procurement centralization are restructuring how capacity gets financed and deployed across China's western solar zones.
Heterojunction cell technology is electrifying the premium module segment through simplified manufacturing flows and superior temperature coefficients. State-backed energy producers in Qinghai and Xinjiang are specifying HJT stacks for desert installations where heat degradation erodes p-type yields. This architecture is compressing the cost gap against TOPCon alternatives as equipment suppliers scale deposition tool throughput.
MIIT cell efficiency thresholds are tightening quality differentiation across domestic manufacturing bases. GB standards now mandate mechanical load testing that disqualifies lightweight frames for high-altitude installations. Module assemblers with captive wafer supply are capturing preferential bankability ratings from provincial grid corporations.
Centralized procurement through state grid tenders is displacing fragmented distributor networks for utility-scale projects. Engineering-procurement-construction contractors in Jiangsu are consolidating module sourcing through framework agreements that lock annual volumes and pricing bands. This concentration is visible in coastal provinces where manufacturing clusters align with interconnection capacity.
China Solar Photovoltaic Market Segmentation
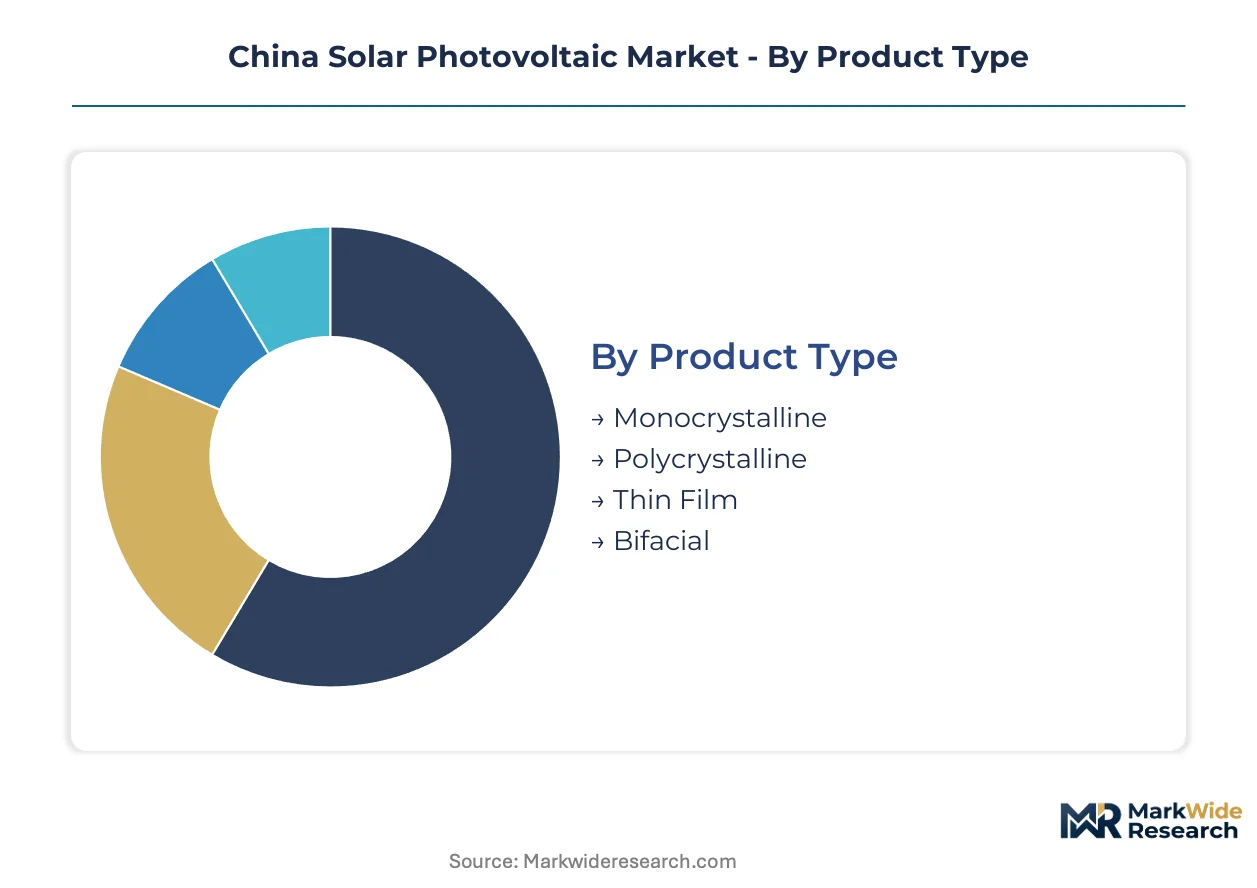
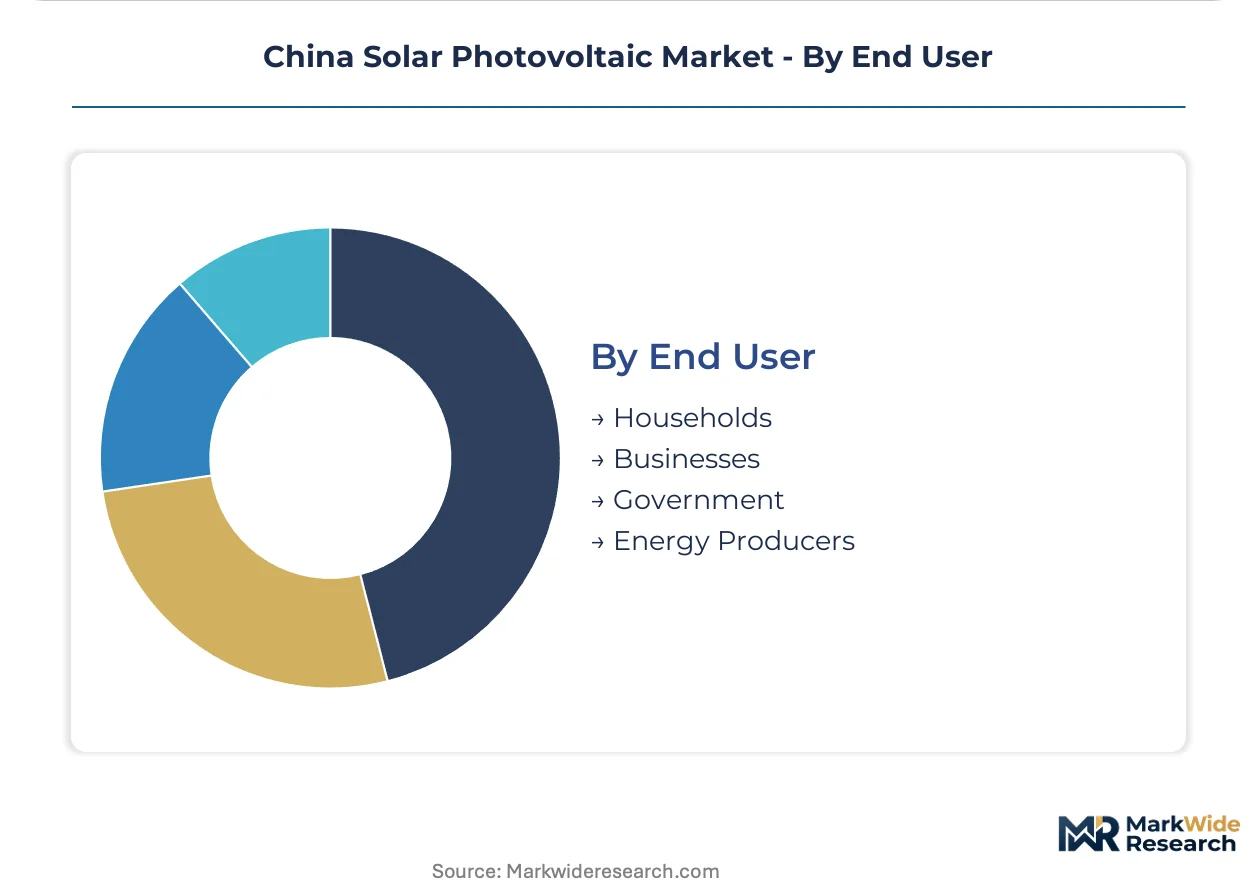
China's solar photovoltaic market segments along four axes that determine manufacturing priorities, procurement patterns, and regulatory exposure. Product type and technology choices dictate capital allocation for cell architecture migration, while application and end-user splits shape interconnection tariff negotiations and grid integration timelines.
Product Type:
Volume concentrates in high-efficiency monocrystalline wafers, while premium positioning shifts toward bifacial architectures that capture reflected irradiance.
- Monocrystalline:Passivated emitter and rear contact architectures achieve conversion efficiencies above 24% through tunnel oxide layers. Jiangsu and Zhejiang manufacturing clusters absorb dominant wafer shipments as provincial grid corporations prioritize bankable module supply for gigawatt-scale auctions.
- Bifacial:Dual-sided light capture extends yield per watt-peak in high-albedo desert environments across Qinghai and Xinjiang. State-backed energy producers specify bifacial tracker systems where ground reflectance amplifies annual energy harvest.
- Polycrystalline:Legacy p-type capacity faces accelerated retirement under MEE carbon intensity caps.
- Thin Film:Cadmium telluride and CIGS architectures occupy niche building-integrated applications.
Today's leader: Monocrystalline. Tomorrow's challenger: Bifacial.
Application:
Procurement patterns diverge between centralized state tenders and fragmented distributed generation as interconnection capacity constraints reshape project economics.
- Utility Scale:Gigawatt-scale project rights tendered through provincial grid corporations in Gansu and Inner Mongolia absorb dominant annual module volumes. Ultra-high voltage transmission corridors face right-of-way disputes that delay commissioning timelines.
- Residential:Rooftop arrays in coastal provinces encounter interconnection quota limitations that constrain deployment velocity.
- Commercial:Corporate power purchase agreements drive mid-scale installations across manufacturing zones.
- Industrial:Self-consumption models align with dual carbon goals for energy-intensive smelters.
Utility-scale deployment commands procurement volume, while distributed segments face grid integration bottlenecks.
Technology:
Cell architecture migration from p-type to n-type platforms is compressing equipment depreciation schedules and redrawing competitive positioning for wafer producers.
- HJT:Heterojunction stacks paired with copper-plated metallization reduce silver paste dependence while lifting conversion efficiency above 25%. Desert installations in Qinghai specify HJT modules where superior temperature coefficients mitigate heat degradation.
- PERC:Passivated emitter and rear contact lines dominate current capacity but face margin compression as MIIT efficiency thresholds tighten.
- TOPCon:Tunnel oxide passivated contact layers bridge cost-performance gaps during n-type transition.
- CPV:Concentrated photovoltaic systems occupy concentrated solar power demonstration zones.
HJT captures premium positioning, while PERC capacity confronts accelerated obsolescence.
End User:
Customer type determines financing structures, tariff negotiations, and regulatory compliance burdens across China's provincial energy markets.
- Energy Producers:State grid corporations and independent power producers tender framework agreements that lock annual module volumes and pricing bands. Centralized procurement displaces fragmented distributor networks for western solar zones.
- Government:Provincial authorities auction project rights with preferential interconnection terms for bifacial tracker installations.
- Businesses:Commercial and industrial offtakers negotiate corporate power purchase agreements.
- Households:Residential rooftop owners face interconnection queue delays in saturated coastal markets.
Energy producers anchor procurement volume, while government tenders set technology specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing clusters anchor China's photovoltaic output through integrated wafer-to-module production corridors serving provincial grid tenders.
Jiangsu
Utility-scale auctions from State Grid Jiangsu Electric Power absorb dominant module volumes as coastal interconnection capacity attracts gigawatt-scale project rights. MIIT efficiency thresholds mandate passivated emitter architectures for grid-connected installations. Changzhou and Wuxi manufacturing zones concentrate ingot pulling and cell metallization lines under provincial dual carbon compliance timelines.
Qinghai
Desert solar parks in Haixi Mongol and Tibetan Autonomous Prefecture specify bifacial tracker systems where high-altitude irradiance amplifies annual yield. MEE carbon intensity caps accelerate retirements of coal-powered polysilicon capacity in neighboring Gansu. Golmud industrial parks host state-backed energy producers tendering framework agreements for heterojunction module supply.
Inner Mongolia
Ultra-high voltage transmission corridors from Ordos and Baotou face right-of-way disputes delaying western zone commissioning schedules. Provincial grid corporations auction project rights with preferential tariffs for agricultural dual-use arrays. Hohhot manufacturing bases concentrate frame extrusion and junction box assembly for tracker-integrated systems.
Zhejiang
Ningbo and Hangzhou manufacturing clusters align wafer supply with coastal interconnection capacity for distributed commercial installations. NMPA environmental compliance audits polysilicon refining operations in adjacent chemical industrial parks. Provincial energy bureaus enforce rooftop quota systems that constrain residential deployment velocity in saturated urban markets.
Xinjiang
Polysilicon smelters in Shihezi and Ürümqi face output curbs from MEE emissions inspections that compress metallurgical-grade silicon input availability. State-backed energy producers in Turpan Depression specify modules with superior temperature coefficients for extreme heat degradation environments. Western transmission zones encounter grid integration bottlenecks from Gansu corridor capacity constraints.
China Solar Photovoltaic Market Competitive Environment
Capacity expansion dominates the current landscape as state grid tenders consolidate procurement through framework agreements that lock annual volumes and pricing bands. The vendor base organizes around three strategic archetypes: integrated wafer-to-module producers with captive polysilicon supply, specialist cell metallizers serving tier-two assemblers, and tracker-integrated system providers for agricultural dual-use installations. Competitive intensity concentrates on equipment depreciation schedules during n-type migration and certification cycles for GB standards compliance.
Among vertically integrated producers, LONGi Solar, JinkoSolar, and Trina Solar occupy positions that exemplify distinct competitive vectors. LONGi Solar represents the upstream-controlled archetype through in-house production of high-purity silicon ingots. JinkoSolar anchors the export-oriented tier with cell-to-panel manufacturing scale. Trina Solar sits within the system-integrated specialist category for desert and agricultural dual-use tracker deployments.
| Leading Market Players |
|---|
| JinkoSolar |
| LONGi Solar |
| Trina Solar |
| JA Solar |
| Tongwei Solar |
| Canadian Solar |
| Risen Energy |
| GCL System Integration |
| Chint New Energy |
| Others |
Value Chain & Pricing Dynamics
Metallurgical-grade silicon spot prices from Xinjiang smelters cascade through wafer and cell manufacturing stages, compressing margin predictability for ingot pullers while concentrating pricing power among polysilicon producers with captive renewable power supply.
Pricing Analysis
Input-cost pass-through dominates module pricing as polysilicon volatility feeds into three-tier pricing structure across premium, standard, and economy levels. HJT stacks with copper-plated metallization command premium positioning due to MIIT efficiency thresholds above 24%, while PERC capacity faces price erosion from n-type migration. Residential rooftop buyers exhibit highest price sensitivity due to interconnection quota limitations, whereas state grid corporations absorb cost fluctuations through framework agreements.
Supply Chain Analysis
Process engineer scarcity in Ningxia and Jiangsu manufacturing zones constrains atomic layer deposition technician pipelines, limiting capacity expansion velocity for heterojunction cell lines. Supply concentrates in China's Yangtze River Delta for wafer pulling and cell metallization, with Xinjiang anchoring polysilicon feedstock. High-purity silicon ingots, silver paste, and aluminum frames constitute critical input dependencies. Single-source vulnerability in Xinjiang smelter output curbs threatens metallurgical-grade silicon availability. Distribution runs through provincial grid corporation tenders that displace fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's solar photovoltaic market has entered a late-cycle quality phase where MEE carbon intensity caps and MIIT efficiency thresholds are redirecting procurement toward n-type cell architectures with superior bankability ratings.
For Market Incumbents: Cement upstream control over high-purity silicon ingot supply through captive polysilicon production or long-term offtake agreements with Xinjiang smelters meeting renewable power mandates. Accelerate PERC line conversion to HJT or TOPCon platforms before efficiency threshold tightening renders legacy capacity obsolete. Defend against emerging specialist cell metallizers by investing in in-house GB standards certification laboratories that shorten product launch cycles. For New Entrants and Emerging Players: Heterojunction equipment supplier partnerships offer entry paths into premium module segments where incumbent depreciation schedules lag technology migration curves. Target agricultural dual-use tracker installations in Shandong and Inner Mongolia where provincial tariffs prefer bifacial systems and EPC contractor consolidation has not yet locked supply relationships. Pursue copper-plated metallization specialization to reduce silver paste dependence and capture cost-performance advantages during n-type transition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale wafer producers possessing convertible PERC-to-TOPCon equipment platforms and proximity to Jiangsu grid interconnection capacity. Long-term viability hinges on renewable-powered production lines that satisfy MEE carbon intensity caps across the projection horizon. Monitor provincial ultra-high voltage transmission corridor commissioning schedules as inflection indicators for western solar zone project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive supply from Xinjiang smelters with renewable arc furnaces secures input cost stability under MEE caps. |
| HJT Cell Line Conversion | Copper-plated metallization reduces silver paste dependence while lifting efficiency above 25% for premium positioning. |
| GB Standards Certification Investment | In-house fire resistance and mechanical load testing laboratories compress 12-18 month product launch cycles. |
| Agricultural Dual-Use Array Development | Tracker-integrated systems over Shandong greenhouse complexes unlock revenue streams from electricity sales and crop yield premiums. |
| Provincial Grid Framework Agreements | Locked annual volumes and pricing bands with State Grid Jiangsu and Qinghai corporations displace fragmented distributor networks. |
Study Parameters
Direct dialogue with polysilicon plant managers, EPC contractors in Jiangsu and Qinghai, provincial grid planning officers, and MIIT standards committee members grounded qualitative insights in operational reality. Secondary validation drew from MIIT photovoltaic product quality filings, MEE carbon intensity compliance disclosures, State Grid tender documentation, and customs export records for module shipments. Bottom-up capacity assessments across ingot pulling, wafer slicing, cell metallization, and module assembly facilities triangulated against top-down provincial auction volume aggregates.
Bottom-up modeling of manufacturing capacity by technology node and application segment converged with top-down provincial grid interconnection quota analysis across the projection horizon. Segmentation dimensions included product architecture, cell technology platform, project scale tier, and end-user financing structure. CAGRs were derived from capacity deployment trajectories under dual carbon goal timelines and equipment depreciation schedules during n-type migration. Forecast inputs incorporated polysilicon smelter renewable power conversion rates and ultra-high voltage transmission corridor commissioning probabilities.
The model holds under sustained MEE enforcement of carbon intensity caps and provincial grid auction volume commitments; deviation in Xinjiang smelter output curbs or western transmission right-of-way resolutions would shift capacity deployment timelines. Forecasts reflect assumptions regarding HJT equipment cost convergence and TOPCon yield ramp rates. Practitioners should monitor Golmud and Haixi project commissioning schedules and Ningxia manufacturing zone talent pipeline development for early signals of supply constraint or technology migration velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Solar Chimney Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Global Artificial Photosynthesis Market