
 Europe Flock Adhesives Market | 2026-2036
Europe Flock Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flock Adhesives Market Foresight
Water-based polymer technology is reconfiguring flock adhesive formulation across European manufacturing. Kissel + Wolf GmbH leverages its German production base to dominate technical textile bonding applications. Henkel AG & Co. KGaA sustains broad portfolio coverage across automotive OEM supply chains. SwissFlock AG specializes in precision flocking systems for luxury automotive interiors.
Europe flock adhesives are bonding systems engineered to anchor short synthetic or natural fibers onto substrates, typically formulated with viscosities between 500 and 5000 mPa·s to control fiber penetration depth and anchorage strength. Their primary purpose is to create durable, velvet-like surfaces for automotive dashboards, door seals, and textile applications requiring abrasion resistance and tactile performance. Water-based formulations now lead the product type landscape as REACH restrictions on volatile organic compounds constrain solvent-based alternatives. Hot melt adhesives represent the fastest-growing technology segment, driven by automotive manufacturers seeking faster curing cycles and energy-efficient production lines. Spray application technology occupies the dominant position in technology segmentation, though roller application gains share in high-volume textile processing.
REACH regulation and the EU Green Deal framework shape chemical composition requirements, restricting hazardous substances and mandating sustainable feedstock disclosure across adhesive supply chains. ECHA substance evaluation processes directly determine market access timelines for new formulations. Germany's national chemical regulator enforces additional workplace exposure limits that influence manufacturing location decisions. Stakeholders must monitor evolving PFAS restriction proposals and bio-based content thresholds as these will determine which formulation platforms retain commercial viability.
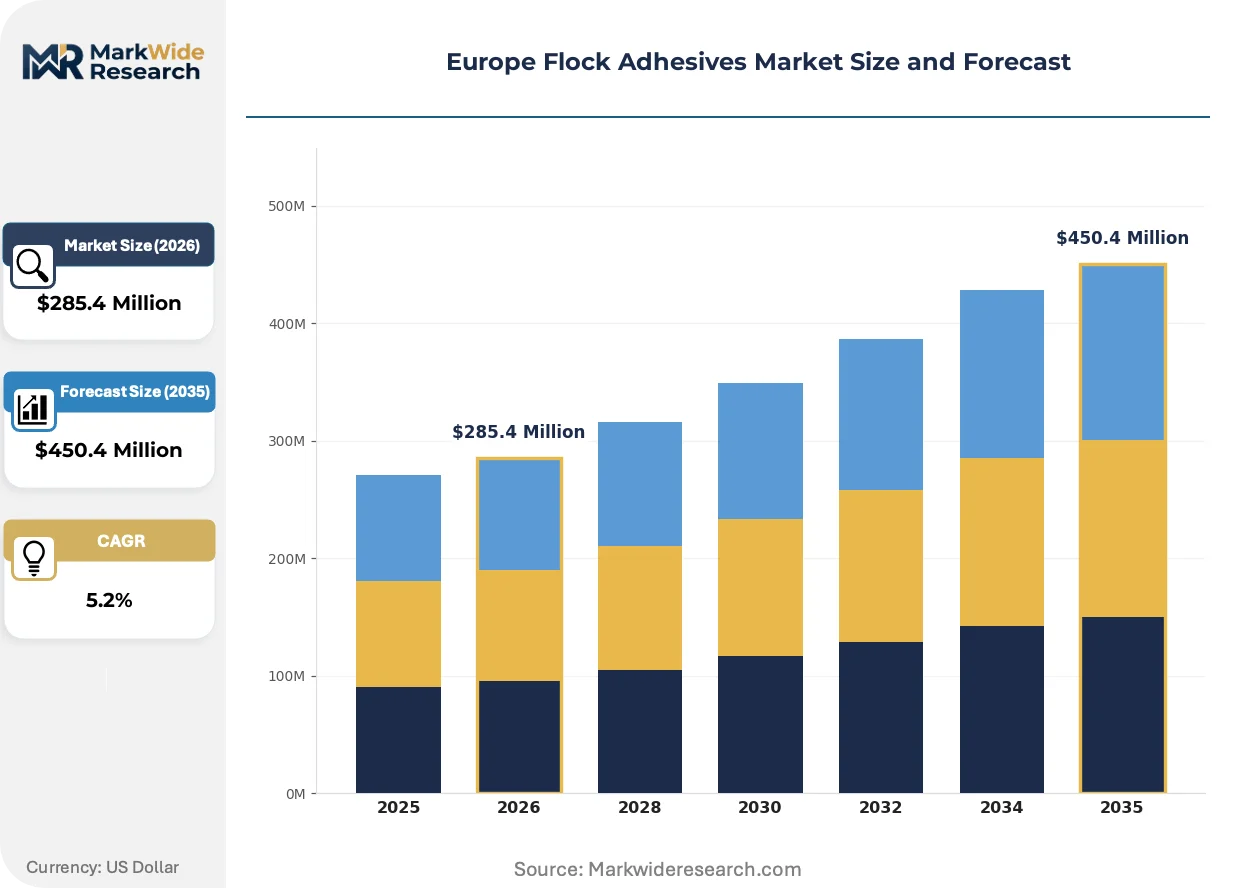
Market Dynamics
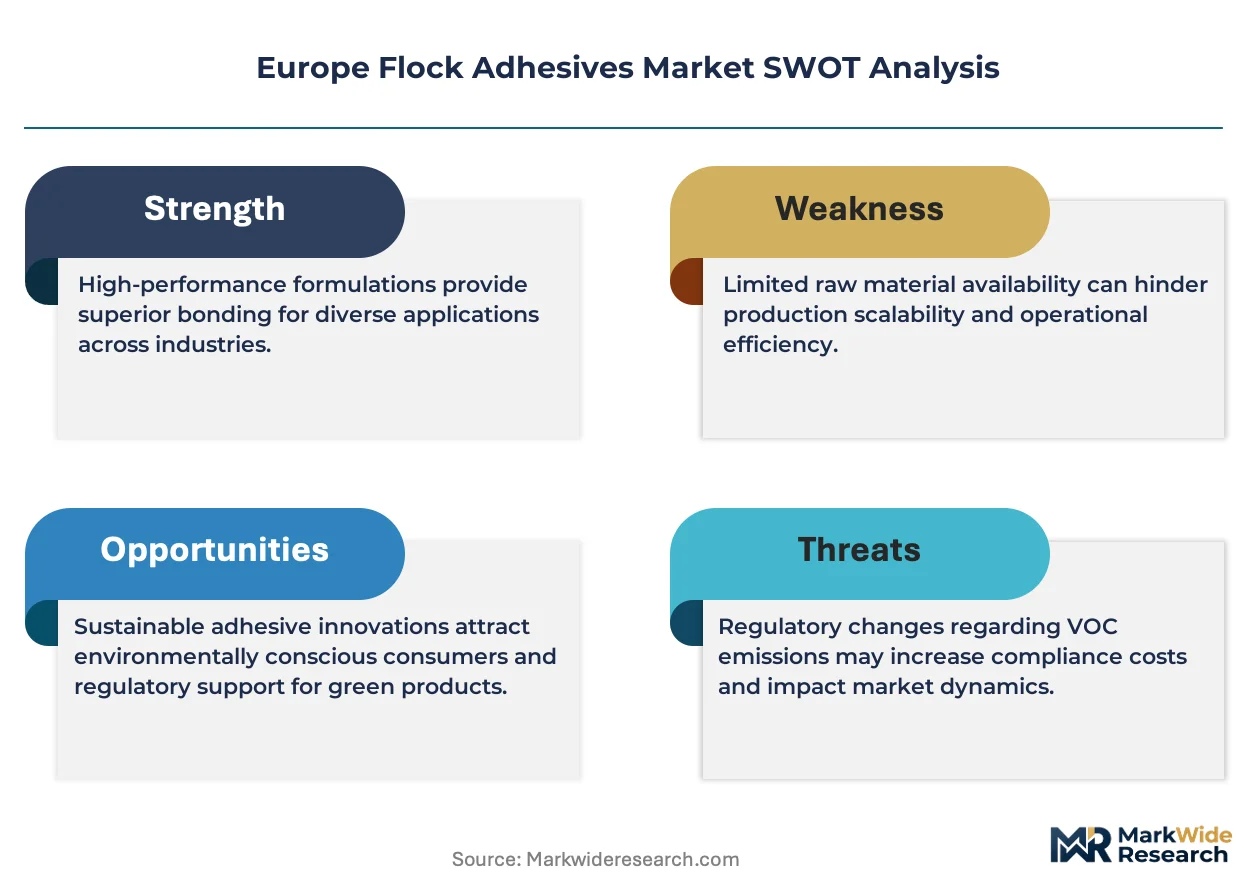
Water-based polymer migration is compressing solvent-based formulation platforms across European flock adhesive manufacturing, as REACH substance restrictions and automotive OEM sustainability mandates converge to rewire raw material sourcing and production location decisions.
Growth Catalysts
- EU Green Deal chemical safety mandates:Automotive interior manufacturers in Germany and France are expanding flocked surface applications to meet haptic quality standards, pulling demand for compliant bonding systems.
- Hot melt adhesive technology:Automotive manufacturers seeking faster curing cycles and energy-efficient production lines are accelerating adoption of this segment across assembly operations.
- Southern European textile clusters:Concentrated demand for water-based adhesives is emerging in Italy and Spain as regional REACH compliance enforcement tightens solvent-based alternatives.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin costs fluctuate with crude oil derivatives, compressing margin predictability for formulation houses.
- German chemical regulator workplace limits:Additional exposure thresholds beyond EU baselines raise compliance costs and deter manufacturing investment in certain federal states.
- Mechanical fastening substitution:Clip-based and ultrasonic welding systems compete for interior panel applications where adhesive bonding previously dominated.
Strategic Opportunities
- Eastern European automotive expansion:Czech Republic and Poland assembly plants present underpenetrated demand for localized flock adhesive supply with reduced logistics exposure.
- Bio-based content thresholds:Anticipated EU Green Deal amendments will reward feedstock transparency, creating first-mover advantage for disclosed renewable content formulations.
- Digital formulation databases:Direct platform integration with automotive OEM specification systems is emerging as a channel bypassing traditional distributor intermediaries.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise combining rheology control with REACH compliance is concentrating at mid-career specialists, constraining R&D throughput.
- ECHA substance evaluation timelines:New adhesive ingredient market access faces unpredictable approval windows, freezing capital commitment until registration certainty emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flock Adhesives Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, Hot Melt, Pressure-sensitive End User: Textile, Automotive, Paper, Packaging Technology: Spray Application, Roller Application, Coating, Foam Application Form: Liquid, Paste, Granular, Film |
| Companies Covered | Kissel + Wolf GmbH, SwissFlock AG, Henkel AG & Co. KGaA, CHT Germany GmbH, Jowat SE, Sika AG, Stahl Holdings B.V., Bostik SA, H.B. Fuller Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flock Adhesives Market Shifts & Advancements
Formulation platforms, regulatory disclosure requirements, and procurement specifications are simultaneously evolving, compressing product development cycles while expanding the technical criteria that determine supplier qualification.
UV-curable water-based hybrid systems are virtualizing traditional thermal curing processes in precision flocking operations. Luxury automotive interior suppliers in Stuttgart and Munich are piloting these platforms to eliminate drying oven energy consumption. The technology is virtualizing capital-intensive production footprints and enabling just-in-sequence adhesive application at assembly line speed.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing reformulation of stain-resistant flock finishes. ECHA evaluation processes have designated several fluorinated compounds as substances of very high concern, triggering substitution mandates. Automotive OEMs in France and Germany are accelerating supplier audits to verify PFAS-free adhesive certification ahead of formal bans.
Automotive tier-one suppliers are consolidating adhesive vendor panels from multi-source to dual-source arrangements, prioritizing formulation houses with integrated ESG disclosure platforms. This concentration is displacing smaller regional compounders lacking digital traceability infrastructure. The shift is most visible in German OEM supply chains where CSRD-aligned supplier scorecards now weight chemical transparency equally with unit pricing.
Europe Flock Adhesives Market Segmentation
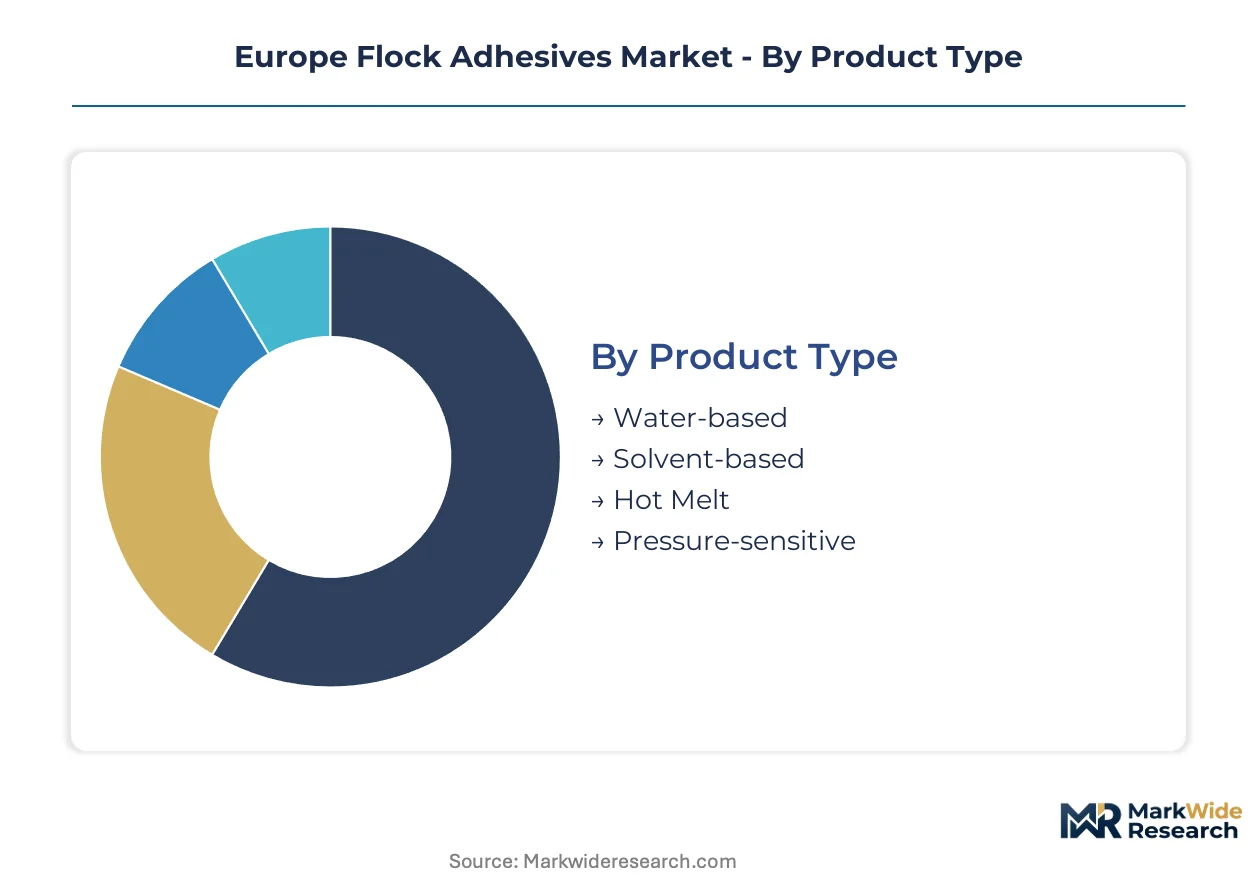
Formulation chemistry, application method, and substrate requirements fragment the Europe flock adhesives landscape into distinct competitive arenas. Each dimension carries different margin profiles, regulatory exposure, and customer concentration patterns that reshape supplier positioning.
Product Type:
Mature water-based systems dominate volume, while emerging hot melt platforms are accelerating fastest as automotive cycle times compress.
- Water-based:Acrylic and polyurethane dispersions with viscosities between 500 and 5000 mPa·s anchor fiber penetration while controlling bleed-through. German automotive interior manufacturers in Stuttgart and Munich specify these formulations to meet EU Green Deal VOC thresholds and REACH substance restrictions.
- Hot Melt:Thermoplastic polymers cure through rapid cooling rather than solvent evaporation, eliminating drying oven energy consumption. Czech Republic and Poland assembly plants are adopting these systems to match just-in-sequence production speeds and reduce thermal processing footprints.
- Solvent-based:Traditional solutions face contracting demand as ECHA substance evaluations designate additional hazardous compounds for restriction.
- Pressure-sensitive:Tackified formulations serve temporary bonding applications in textile processing where repositionability matters.
Water-based formulations retain volume leadership; hot melt adhesives hold the steepest expansion curve.
End User:
Cost tier stratification separates premium automotive specifications from commodity textile applications, with divergent compliance burdens.
- Automotive:Dashboard, door seal, and interior panel applications demand haptic quality standards under EU Green Deal chemical safety mandates. French and German OEMs are expanding flocked surface coverage to differentiate luxury vehicle interiors while auditing suppliers for PFAS-free certification.
- Textile:Southern European clusters in Italy and Spain concentrate water-based adhesive consumption as regional REACH enforcement tightens solvent-based alternatives. Velvet-like finishes for apparel and upholstery drive specification complexity.
- Paper:Decorative and functional flocking applications serve specialty packaging and publishing segments with moderate technical requirements.
- Packaging:Protective and aesthetic surface treatments compete with alternative finishing methods on cost efficiency metrics.
Automotive applications command premium pricing tiers; textile processing delivers the broadest volume base.
Technology:
Customer type differentiation separates high-mix precision operations from continuous high-volume lines, dictating equipment investment patterns.
- Spray Application:Pneumatic or electrostatic dispersion enables complex three-dimensional substrate coverage with controlled fiber density. Stuttgart and Munich luxury automotive suppliers pilot UV-curable hybrid systems through spray heads to virtualize thermal curing infrastructure.
- Roller Application:Gravure or reverse roll coaters deliver uniform adhesive films across flat textile webs at speeds matching high-volume Italian and Spanish processing lines. This method gains share as throughput requirements intensify.
- Coating:Knife-over-roll and dip coating systems serve specialized substrate geometries requiring precise thickness control.
- Foam Application:Froth techniques deposit controlled adhesive volumes onto absorbent substrates with minimal penetration.
Spray application retains installed base dominance; roller systems are climbing the fastest as textile throughput requirements intensify.
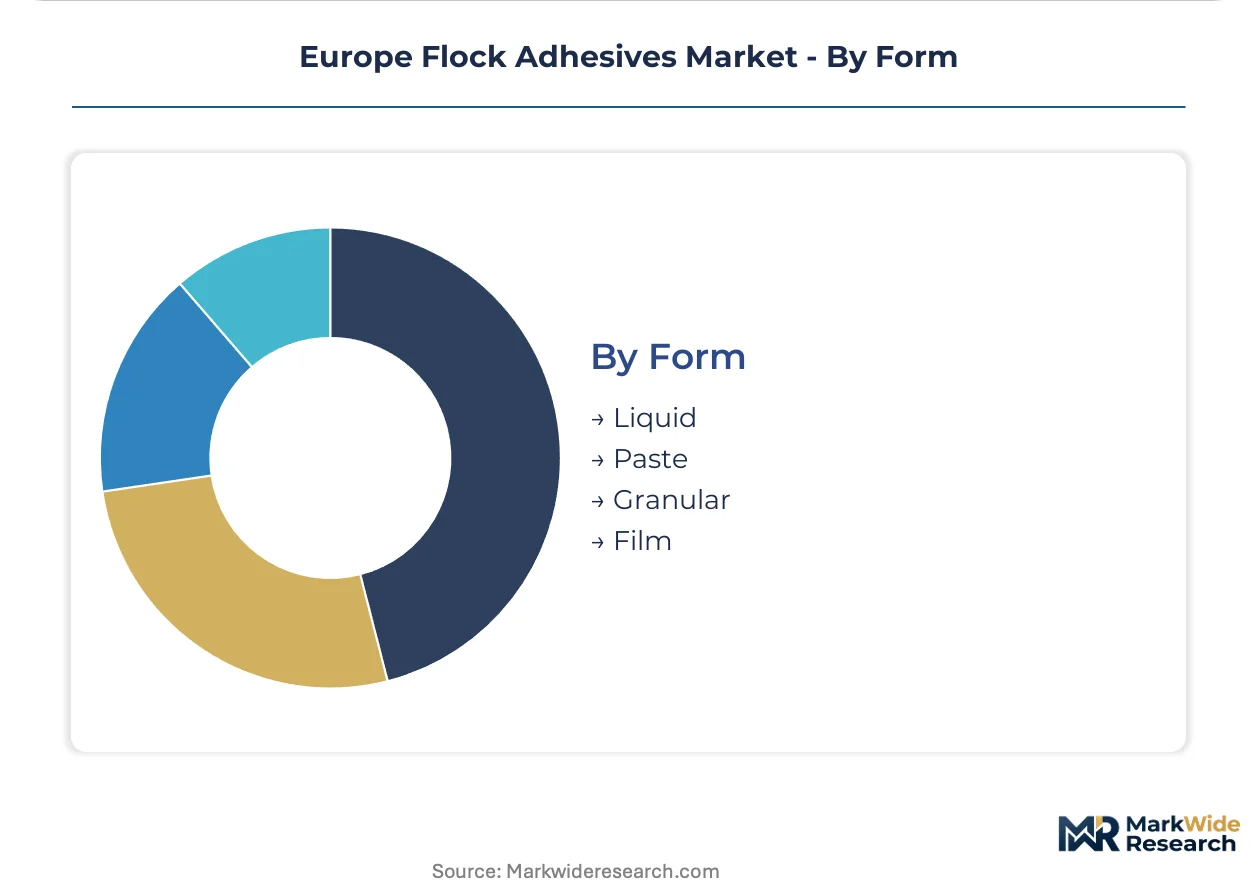
Form:
Supply concentration patterns favor liquid formats near formulation houses, while solid forms reduce logistics costs for distant customers.
- Liquid:Pumpable dispersions dominate water-based and solvent-based categories, enabling automated metering and mixing at point of application. German production facilities ship bulk liquid formulations across European automotive supply chains.
- Paste:Thixotropic formulations prevent sag on vertical automotive interior panels during assembly operations.
- Granular:Solid hot melt feedstocks reduce shipping weight and enable localized melting operations near Eastern European assembly plants.
- Film:Pre-cast adhesive layers serve niche applications requiring precise thickness control without wet processing.
Liquid formats retain volume leadership; granular hot melt feedstocks are gaining share fastest on logistics efficiency metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German flock adhesive exports flow primarily to Czech and Polish automotive assembly plants, establishing a north-central European supply corridor that concentrates formulation expertise near Stuttgart and Munich production clusters.
Germany
Automotive interior manufacturers in Stuttgart and Munich are expanding flocked dashboard and door seal applications to meet haptic quality standards under EU Green Deal mandates. The national chemical regulator enforces workplace exposure limits beyond EU baselines, raising compliance costs for solvent-based operations. Kissel + Wolf GmbH leverages its German production base to dominate technical textile bonding applications across the region.
France
French OEMs are accelerating supplier audits to verify PFAS-free adhesive certification ahead of formal ECHA bans. The country's national pharmaceutical and environmental regulator ANSM coordinates with ECHA on substance evaluation timelines. Lyon and Paris Basin automotive suppliers are consolidating adhesive vendor panels from multi-source to dual-source arrangements.
Italy
Southern European textile clusters concentrate water-based adhesive demand as regional REACH enforcement tightens solvent-based alternatives. Velvet-like finishes for apparel and upholstery drive specification complexity in Milan and Florence manufacturing belts. Italian processors are adopting roller application technology to match high-volume throughput requirements.
Spain
Spanish textile manufacturers face contracting solvent-based formulation demand as ECHA substance evaluations designate additional hazardous compounds for restriction. The country's national chemical regulator enforces disclosure requirements aligned with CSRD-aligned supplier scorecards. Barcelona and Valencia processing lines are migrating toward water-based polymer platforms.
Poland
Eastern European automotive expansion presents underpenetrated demand for localized flock adhesive supply with reduced logistics exposure. Polish assembly plants are adopting hot melt systems to match just-in-sequence production speeds. Warsaw and Krakow industrial zones attract granular hot melt feedstock distribution to minimize shipping weight.
Europe Flock Adhesives Market Competitive Landscape
On the supply side, the industry is consolidating around formulation houses with integrated ESG disclosure platforms and REACH compliance infrastructure. Mid-sized regional compounders lacking digital traceability face displacement as automotive tier-one suppliers narrow vendor panels. Three archetypes dominate: diversified chemical conglomerates with broad adhesive portfolios, specialized flocking system providers focused on precision applications, and regional formulation houses serving textile clusters. Competitive moves center on M&A to acquire REACH registration expertise and strategic partnerships with automotive OEM specification systems.
Within the specialized precision tier, SwissFlock AG exemplifies the luxury automotive interior focus, while Kissel + Wolf GmbH anchors technical textile bonding applications from its German manufacturing base. Henkel AG & Co. KGaA occupies a position representing the diversified conglomerate archetype with broad portfolio coverage across automotive OEM supply chains. These three entities collectively illustrate how geographic origin and corporate structure map onto distinct competitive positioning within the European regulatory environment.
| Leading Market Players |
|---|
| Kissel + Wolf GmbH |
| SwissFlock AG |
| Henkel AG & Co. KGaA |
| CHT Germany GmbH |
| Jowat SE |
| Sika AG |
| Stahl Holdings B.V. |
| Bostik SA |
| H.B. Fuller Company |
| Others |
Supply & Pricing Matrix
Rhine-Ruhr freight corridors connecting German formulation houses to Czech and Polish assembly plants concentrate logistics cost exposure, compressing margin structures for distant suppliers while enabling Stuttgart and Munich producers to command premium positioning through delivery reliability.
Pricing Analysis
Water-based acrylic dispersions, hot melt thermoplastics, and legacy solvent-based systems occupy distinct pricing tiers based on energy intensity and regulatory compliance burden. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered formulations with full ESG disclosure from commodity water-based alternatives and residual solvent-based volumes. Pricing pressure stems from petrochemical feedstock volatility in acrylic and polyurethane resin inputs. Automotive OEM procurement teams exhibit lowest price sensitivity due to CSRD-aligned supplier scorecard requirements, while Spanish and Italian textile processors face acute cost compression.
Supply Chain Analysis
Tariff exposure between German resin producers and Eastern European automotive assembly plants dominates supply chain risk calculations for granular hot melt feedstock distribution. Raw material sourcing draws from Belgian petrochemical hubs, German specialty chemical manufacturers, and Italian polyurethane dispersion specialists. Acrylic resin, thermoplastic polymer, and bio-based additive supplies face single-source vulnerability where ECHA substance evaluations freeze alternative registration timelines. Distribution runs through bulk liquid tanker networks for water-based formulations and regional melting facilities for solid hot melt feedstocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe flock adhesives represent a high-growth disruption as UV-curable water-based hybrid systems virtualize thermal curing infrastructure and REACH PFAS restrictions force formulation platform migrations.
For Market Incumbents: Pre-empt mechanical fastening substitution threats by embedding adhesive specification into automotive OEM digital platforms before clip-based and ultrasonic welding systems capture interior panel applications. Acquire REACH registration expertise through targeted capability purchases to compress ECHA substance evaluation timelines. Consolidate vendor panel positions through integrated ESG disclosure infrastructure that smaller regional compounders cannot replicate.
For New Entrants and Emerging Players: Eastern European automotive expansion in Czech Republic and Poland assembly plants represents the most penetrable entry point, offering localized supply advantages against German incumbents burdened by federal workplace exposure limit compliance costs. Bio-based content threshold anticipation creates formulation transparency differentiation opportunities ahead of formal EU Green Deal amendments. Partner with automotive tier-one suppliers on pilot programs for just-in-sequence hot melt application systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized flocking system providers with precision application expertise over diversified chemical conglomerates facing portfolio complexity drag. Long-term viability across the projection horizon rests on digital traceability infrastructure and direct OEM specification system integration. Monitor ECHA PFAS restriction proposal advancement as the critical signal for formulation platform obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive supply of REACH-compliant raw materials insulates margin pressure from petrochemical volatility. |
| UV-Curable Hybrid System Pilot Deployment | Stuttgart and Munich luxury automotive suppliers eliminate drying oven capital expenditure through virtualized curing. |
| Eastern European Distribution Hub Establishment | Granular hot melt feedstock melting near Polish assembly plants reduces Rhine-Ruhr freight cost exposure. |
| Digital Platform Integration with OEM Specification Systems | Direct channel access bypasses distributor intermediaries and locks in technical qualification status. |
| Bio-Based Content Certification Investment | Feedstock transparency disclosure creates first-mover advantage ahead of anticipated EU Green Deal thresholds. |
Research Methodology
A standing panel of adhesive formulation chemists, automotive Tier 1 procurement directors, textile processing plant managers, and ECHA regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from customs and trade databases, Cefic chemical industry reports, SEC 10-K filings from listed adhesive manufacturers, and vehicle production databases. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed analytical projections across the modeling period, with CAGRs derived from segment-level growth rate synthesis and cross-validation against end-use industry demand trajectories. Segmentation dimensions included formulation chemistry, application technology, substrate requirements, and regional production hub concentration. Industry-specific forecast inputs incorporated REACH substance evaluation pipeline status and automotive OEM sustainability mandate adoption curves.
Practitioners should monitor ECHA PFAS restriction proposal advancement, petrochemical feedstock price volatility, and mechanical fastening technology substitution rates for early signals of forecast revision requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Global Epoxy Tooling Board Market