
 Global Ethyl Methacrylate (97-63-2) Market | 2026-2036
Global Ethyl Methacrylate (97-63-2) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethyl Methacrylate (97-63-2) Market Foresight
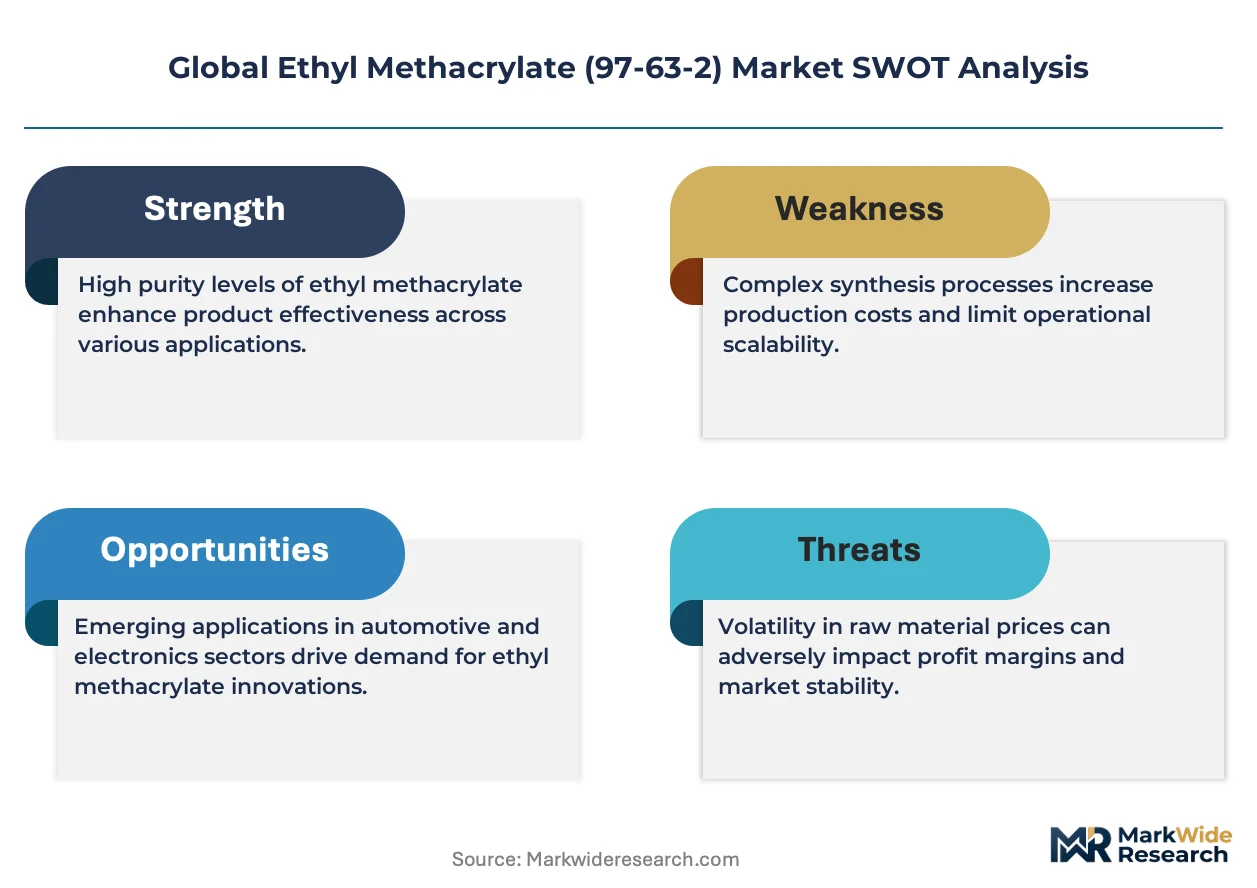
Modular packaging configurations for ethyl methacrylate is restructuring procurement patterns across specialty chemical buyers. Mitsubishi Chemical Group leverages captive acrylate feedstock capacity to sustain cost advantages in polymer resin grades. Evonik differentiates through high-purity specifications for medical device applications. Arkema anchors its position via integrated methyl methacrylate chain economics that extend into ethyl ester derivatives.
Ethyl methacrylate (EMA, CAS 97-63-2) is an acrylic ester monomer with molecular formula C6H10O2, produced through esterification of methacrylic acid with ethanol, serving primarily as a reactive building block for thermoplastic polymers and cross-linked coating systems. The monomer polymerizes readily via free-radical initiation to form homopolymers and copolymers with glass transition temperatures typically below that of methyl methacrylate, yielding softer, more flexible films. Polymer resins occupy the dominant product position due to established demand in acrylic sheet and dispersion manufacturing, while coatings capture accelerating growth from automotive refinish and protective industrial formulations. Electronics encapsulation applications concentrate margin pools, as semiconductor-grade purity requirements command premium positioning against standard industrial grades.
REACH registration obligations under ECHA govern import and formulation activities across European value chains, while EPA Toxic Substances Control Act reporting shapes domestic handling protocols in the United States. China's SAMR-administered GB standards for chemical purity and labeling influence export-competitive manufacturers supplying Asian converting industries. Stakeholders must monitor regulatory divergence between jurisdictions to align product specifications with diverging purity thresholds and notification thresholds.
Market Dynamics
Feedstock volatility in methacrylic acid and ethanol is compressing margin structures across ethyl methacrylate value chains, forcing formulators to renegotiate long-term offtake contracts and accelerate backward integration into captive esterification capacity.
Growth Catalysts
- Automotive refinish coatings:Collision repair volume recovery and OEM color-matching specifications are pulling industrial-grade EMA through dedicated distribution channels in Germany and the United States.
- REACH registration completion:Full ECHA dossier compliance for ethyl methacrylate monomer has unlocked formulation flexibility across EU-based acrylic adhesive manufacturers previously constrained by interim supply.
- Semiconductor encapsulation:Ultra-high-purity grades meeting SEMI standards are penetrating advanced packaging applications for power electronics in Japan and South Korea.
Market Restraints
- Methacrylic acid supply concentration:Production of the primary feedstock clusters among integrated petrochemical complexes on the US Gulf Coast and Northeast Asia, exposing converters to force majeure disruption cascades.
- Substitution by bio-based alternatives:Isobornyl methacrylate and other terpene-derived monomers are capturing share in premium coating formulations targeting VOC reduction mandates.
- EPA TSCA Section 5 notification:New chemical substance review timelines for modified EMA copolymers extend commercialization cycles by 12-18 months for US-focused innovators.
Strategic Opportunities
- India specialty coatings:BIS certification alignment for imported monomer grades creates first-mover positioning as domestic automotive production scales in Tamil Nadu and Gujarat.
- Photovoltaic encapsulant films:EMA-ethylene copolymers with enhanced UV stability are displacing conventional EVA in module manufacturing, with qualification activity concentrated in China and Vietnam.
- EU Green Deal chemical leasing:Servitization models converting monomer supply into polymer-as-a-service contracts reduce working capital intensity for mid-scale European converters.
Industry Challenges
- Process analytical technology deployment:Real-time quality verification for semiconductor-grade purity requires capital-intensive PAT infrastructure that smaller esterification operators struggle to finance.
- Cross-jurisdictional label harmonization:Divergent GHS classification thresholds between OSHA HazCom and EU CLP create compliance friction for multinational formulators maintaining single-SKU strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethyl Methacrylate (97-63-2) Market |
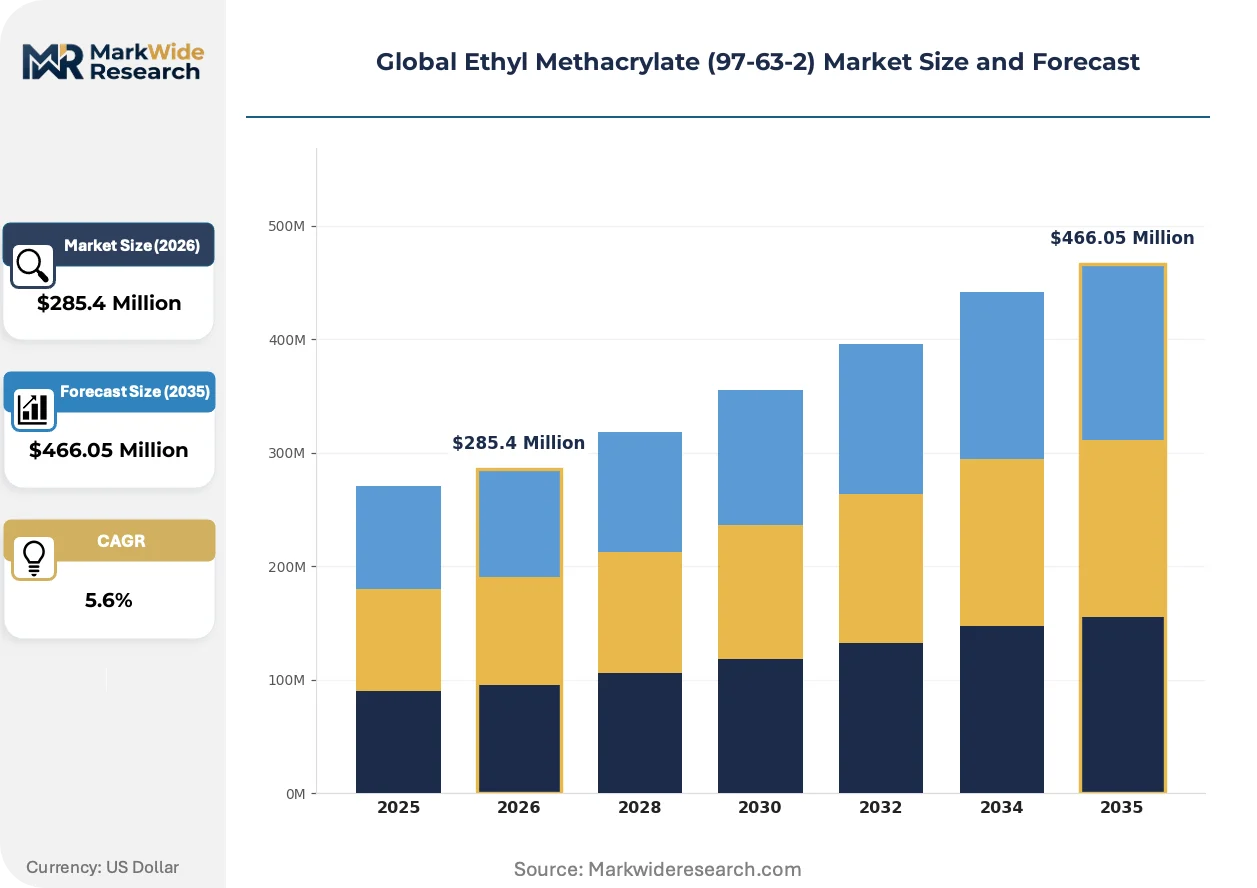
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $466.05 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Resins, Adhesives, Coatings, Sealants, Additives Application: Automotive Coatings, Electronics Encapsulation, Medical Devices, Architectural Finishes, Textile Treatments End User Industry: Vehicle Manufacturing, Consumer Electronics, Medical Equipment, Building & Construction, Apparel Production Packaging Type: Drums, Intermediate Bulk Containers, Carboys, Totes, Pails |
| Companies Covered | Mitsubishi Chemical Group, Evonik, Arkema, Merck, Thermo Fisher, Suzhou Hechuang Chemical, Wanhua Chemical, Zhejiang Satellite Petrochemical, Fushun Donglian Anxin Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethyl Methacrylate (97-63-2) Market Shifts & Advancements
Reactive diluent formulations and closed-loop monomer recovery systems are restructuring how ethyl methacrylate flows through coating and adhesive value chains, with sustainability verification becoming a procurement gate.
Continuous stirred-tank reactor (CSTR) technology with inline spectroscopic monitoring is modularizing production economics for specialty ester manufacturers. Mid-scale European chemical companies are retrofitting batch assets to hybrid continuous configurations. This modularizing approach collapses minimum efficient scale thresholds and enables toll-manufacturing arrangements for proprietary copolymer grades.
China's GB 30982-2014 standard revision for architectural coatings is tightening VOC content ceilings and accelerating waterborne acrylic dispersion adoption. Formulators are reformulating solvent-borne systems to comply with the updated limits. The enforcement wave concentrates impact on Guangdong and Jiangsu province coating clusters serving domestic construction markets.
Direct procurement from esterification operators is displacing traditional distributor intermediaries among large-volume adhesive compounders in North America. Volume buyers are negotiating frame contracts with producers holding captive methacrylic acid supply. This channel compression is most pronounced in automotive assembly adhesive applications where specification lock-in reduces supplier-switching flexibility.
Global Ethyl Methacrylate (97-63-2) Market Segmentation
Ethyl methacrylate demand fragments across formulation types, end-use specifications, and handling requirements that each carry distinct margin profiles and regulatory obligations. Understanding these segment boundaries clarifies where producers can defend pricing power versus where commoditization pressures dominate.
Product Type:
Polymer resins anchor volume throughput while coatings and adhesives capture premium positioning through specification complexity.
- Polymer Resins:Homopolymer and copolymer grades serve acrylic sheet extrusion and dispersion manufacturing. Demand concentrates in China and Japan where converting capacity for PMMA-alternative materials has expanded. Mitsubishi Chemical and Evonik maintain supply agreements with sheet producers in Osaka and Shanghai.
- Adhesives:Reactive monomer formulations for structural bonding in automotive assembly command purity premiums. Medical-grade specifications for device assembly in Germany and the United States require ECHA REACH dossier compliance and FDA master file alignment. This segment gains share fastest as electric vehicle battery module bonding specifications tighten.
- Coatings:Solvent-borne and waterborne systems for automotive refinish and industrial protection. VOC regulations in California and Jiangsu province are forcing reformulation toward higher-solids EMA-based systems.
- Sealants:Flexible joint compounds for construction and transportation applications. Building code compliance in seismic zones drives specification in Japan and California.
- Additives:Processing aids and rheology modifiers for thermoplastic compounds. Polymer compounding houses in Gujarat and Texas represent concentrated demand.
Today's leader: Polymer Resins. Tomorrow's challenger: Adhesives.
Application:
Automotive and electronics applications concentrate margin pools while medical and textile segments offer defensible niche positioning.
- Automotive Coatings:OEM and refinish formulations for color-matching and corrosion protection. Collision repair volume recovery in Germany and the United States pulls industrial-grade EMA through dedicated distribution channels. OEM specifications from Volkswagen and Ford lock in multi-year supply contracts.
- Electronics Encapsulation:Semiconductor-grade purity for power module packaging. SEMI-standard compliance qualifies suppliers for advanced packaging in South Korea and Japan. This segment climbs fastest as silicon carbide inverter deployment accelerates.
- Medical Devices:Dental prosthetics and orthopedic cement applications. FDA 510(k) pathway requirements and MDR technical documentation create regulatory moats for qualified suppliers.
- Architectural Finishes:Decorative and protective coatings for commercial and residential construction. China's GB 30982-2014 revision is tightening VOC ceilings and accelerating waterborne dispersion adoption.
- Textile Treatments:Fabric finishing and fiber bonding for technical apparel. Moisture-management specifications for athletic wear drive demand in Vietnam and Bangladesh converting clusters.
Automotive Coatings generates the highest absolute revenue. Electronics Encapsulation posts the steepest expansion trajectory.
End User Industry:
Vehicle manufacturing and consumer electronics dominate volume offtake while medical equipment sustains premium pricing through qualification barriers.
- Vehicle Manufacturing:OEM assembly adhesives and refinish coatings. Battery electric vehicle platforms in Germany, China, and the United States are specifying new adhesive chemistries for lightweight joining.
- Consumer Electronics:Smartphone and laptop component encapsulation. Assembly contractors in Shenzhen and Hanoi qualify monomer grades for optical clarity and thermal stability.
- Medical Equipment:Implantable and disposable device manufacturing. ISO 10993 biocompatibility testing requirements filter supplier pools to EMA producers with dedicated medical production lines.
- Building & Construction:Sealants and architectural coatings. Infrastructure stimulus in India and the United States is pulling material through distribution.
- Apparel Production:Technical textile finishing and fiber treatment. Performance wear brands in Italy and the United States specify treated fabric for athletic and outdoor applications.
Vehicle Manufacturing commands current volume leadership. Medical Equipment offers the most durable margin structure.
Packaging Type:
Drum and IBC formats serve high-volume chemical distributors while carboys and totes address specialized purity and handling requirements.
- Drums:Standard 200-liter steel and polyethylene containers for industrial-grade monomer. Logistics providers in Rotterdam and Houston maintain drum filling capacity for regional distribution.
- Intermediate Bulk Containers:1,000-liter flexible and rigid totes for mid-volume adhesive compounders. Returnable IBC programs reduce packaging waste for automotive assembly plants in Bavaria and Michigan.
- Carboys:Glass and fluoropolymer-lined containers for semiconductor-grade material. Cleanroom transfer protocols in Yokkaichi and Pyeongtaek require dedicated carboy handling infrastructure.
- Totes:Collapsible and rigid intermediate bulk formats for coating manufacturers. Just-in-time delivery contracts in Guangdong province specify tote return logistics.
- Pails:20-25 liter containers for small-batch formulation and laboratory supply. Distributor networks in Massachusetts and North Rhine-Westphalia stock pail formats for research and pilot-scale buyers.
Drums and IBCs dominate tonnage movement. Carboys defend the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethyl methacrylate production scaled first in German and Japanese chemical corridors during the post-war acrylics expansion, with capacity later multiplying across US Gulf Coast and Chinese coastal provinces as polymer demand globalized.
United States
Medical device manufacturers in Massachusetts and Minnesota specify high-purity EMA for dental and orthopedic applications. FDA master file requirements and EPA TSCA reporting obligations filter supplier pools to qualified producers. Houston and Baton Rouge host methacrylic acid feedstock complexes that supply regional esterification operations.
Germany
Automotive refinish coatings in Bavaria and Baden-Württemberg pull industrial-grade monomer through dedicated distribution channels serving collision repair networks. ECHA REACH dossier compliance unlocks formulation flexibility for acrylic adhesive compounders. Ludwigshafen and Marl chemical parks anchor integrated acrylate value chains.
China
Photovoltaic encapsulant film producers in Jiangsu and Zhejiang provinces qualify EMA-ethylene copolymers for module manufacturing. SAMR-administered GB standards for chemical purity govern import protocols and domestic labeling. Shanghai and Ningbo converting clusters drive dispersion demand for architectural coatings.
Japan
Semiconductor packaging houses in Yokkaichi and Pyeongtaek-adjacent operations specify SEMI-standard EMA grades for power electronics encapsulation. METI industrial policy supports advanced materials qualification for silicon carbide inverter applications. Osaka chemical manufacturers maintain supply agreements with regional sheet producers.
South Korea
Consumer electronics assemblers in Gyeonggi Province qualify monomer grades for smartphone and laptop component encapsulation. MFDS chemical safety assessments align with international purity thresholds for device-grade materials. Busan-Ulsan petrochemical complexes provide captive feedstock for domestic esterification.
Global Ethyl Methacrylate (97-63-2) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity specification and regulatory qualification dimensions. The vendor base stratifies between integrated petrochemical conglomerates with captive methacrylic acid supply and specialized esterification operators serving niche purity tiers. Three archetypes dominate: integrated acrylate chains, high-purity specialists, and regional toll manufacturers. Competitive moves concentrate on backward integration into feedstock and capacity expansion in high-growth Asian markets.
Within the integrated acrylate tier, Mitsubishi Chemical Group and Arkema exemplify players leveraging captive feedstock economics across polymer resin grades. Evonik occupies a position in the high-purity specialist archetype, with medical and semiconductor-grade specifications commanding premium positioning against standard industrial offerings. Among Chinese-based producers, Wanhua Chemical and Zhejiang Satellite Petrochemical represent scale-driven regional anchors expanding domestic esterification capacity.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Evonik |
| Arkema |
| Merck |
| Thermo Fisher |
| Suzhou Hechuang Chemical |
| Wanhua Chemical |
| Zhejiang Satellite Petrochemical |
| Fushun Donglian Anxin Chemical |
| Others |
Supply & Pricing Matrix
Automotive refinish compounders in Germany and the United States anchor pricing power through multi-year OEM specification lock-ins, while semiconductor-grade buyers accept premium positioning for SEMI-compliant material. This buyer-archetype concentration sustains contract-based offtake structures against spot-market volatility in standard industrial grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SEMI-grade semiconductor material from industrial coatings grades and bulk polymer resin feedstock. Price differentiation rests on certification tier and volume scale, with medical-grade REACH dossier compliance commanding substantial premiums over standard industrial offerings. Cost compression in standard industrial grades is intensifying because methacrylic acid feedstock volatility forces esterification operators to absorb margin erosion. Small-batch adhesive compounders show highest price sensitivity, while semiconductor encapsulation houses prioritize purity thresholds over unit cost.
Supply Chain Analysis
Freight cost differentials between drum and IBC formats are widening as Rotterdam and Houston logistics providers impose surcharges on hazardous material handling. Supply concentrates in China, Germany, and Japan, with methacrylic acid feedstock drawing from US Gulf Coast and Northeast Asian petrochemical complexes. Single-source vulnerability in semiconductor-grade carboy supply creates chokepoint risk for Yokkaichi and Pyeongtaek cleanroom operations. Distribution runs through direct procurement frame contracts that displace traditional distributor intermediaries among North American volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethyl methacrylate functions as a stable compounder anchored by irreplaceable specifications in automotive OEM color-matching and semiconductor encapsulation, where qualification barriers protect incumbent returns.
For Market Incumbents: Anchor position through captive methacrylic acid supply integration and dedicated medical-grade production line certification. Isobornyl methacrylate bio-based substitution in premium coatings threatens standard-grade volume. Capacity addition in Jiangsu province captures photovoltaic encapsulant film qualification activity. SEMI-standard compliance investment locks in semiconductor packaging houses against emerging Chinese competitors. For New Entrants and Emerging Players: BIS certification alignment in India opens a window for first-mover positioning as Tamil Nadu and Gujarat automotive production scales. Photovoltaic encapsulant film segment offers lowest penetration barriers against established semiconductor-grade specialists. Toll-manufacturing arrangements with European mid-scale esterification operators provide lowest-capital entry path. Waterborne dispersion formulation partnerships with Guangdong coating clusters accelerate domestic qualification. For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive acrylate chains are the most active acquirer in this space, targeting high-purity specialists for medical and electronics verticals. Five-to-ten year viability rests on qualification moat durability rather than commodity scale economics. Acquisition target archetype: regional esterification operators with SEMI or FDA master file positioning. Signal to watch: silicon carbide inverter deployment rates in South Korea and Japan as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylic Acid | Captive feedstock supply insulates Mitsubishi Chemical and Arkema from force majeure disruption cascades. |
| SEMI-Grade Purity Certification | SEMI-standard compliance qualifies Evonik for Yokkaichi power electronics packaging applications. |
| Photovoltaic Encapsulant Qualification | EMA-ethylene copolymer adoption in Jiangsu module manufacturing displaces conventional EVA films. |
| REACH Dossier Completion | Full ECHA compliance unlocks formulation flexibility for EU-based acrylic adhesive compounders. |
| Continuous Reactor Retrofit | CSTR technology deployment collapses minimum efficient scale thresholds for European toll manufacturers. |
Research Methodology
Coverage spans Asia-Pacific, Europe, and North America, with primary inputs from each region combined with secondary validation. Plant managers at esterification facilities, procurement leads at automotive OEMs, distribution channel partners in Rotterdam and Houston, and technical R&D directors at adhesive compounders provided operational data. Secondary sources included customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA REACH registration databases. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use industries.
Granularity-level modeling deployed grade-tier segmentation for purity specifications, end-use industry splits across automotive and electronics applications, packaging format differentiation, and regional production hub clustering. CAGRs were derived through trend extrapolation anchored in qualification timeline data and capacity expansion announcements. Forecast inputs incorporated methacrylic acid feedstock contract pricing trajectories and photovoltaic module production forecasts from Jiangsu and Zhejiang provinces.
Revisions become necessary when force majeure disruptions in US Gulf Coast methacrylic acid supply materialize or when EPA TSCA notification timelines extend beyond standard review windows. Forecasts reflect assumptions on semiconductor-grade purity threshold stability and automotive collision repair volume recovery. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Soft Skin Adhesives Market