
 Italy Adhesives Market | 2026-2036
Italy Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Adhesives Market Foresight
Aftermarket service revenue for adhesive application systems is reconfiguring margin pools away from commodity bulk sales toward technical support contracts and equipment calibration services. H.B. Fuller Company leverages its Italian distribution network to anchor premium positions in specialty construction segments. Mapei S.p.A. sustains manufacturing scale through vertically integrated cementitious and resin operations near Milan. Kerakoll differentiates through bio-based formulation leadership targeting green building certification channels.
Adhesives are non-metallic substances applied to substrate surfaces that develop structural or semi-structural bonding through chemical curing, mechanical interlocking, or diffusion mechanisms, with formulations typically comprising base polymers, tackifiers, plasticizers, and curing agents in viscosities ranging from water-thin liquids to paste-consistency compounds. Their primary industrial purpose spans permanent assembly of dissimilar materials, temporary fixation during fabrication, and sealing against environmental ingress across manufacturing and construction workflows. Water-based adhesives dominate volume in packaging and woodworking applications where emission regulations tighten fastest, while reactive polyurethane and epoxy formulations command premium positions in automotive structural bonding and electronics encapsulation where thermal cycling resistance determines specification. Hot melt segments face margin compression from energy cost volatility despite growth in e-commerce corrugated packaging demand.
Italy's adhesives sector operates under REACH registration requirements administered through ECHA, with additional pressure from EU Green Deal embodied carbon targets affecting construction material specifications. BIS-equivalent conformity assessments for imported raw materials and Italy's transposition of F-Gas Regulation restrictions on certain blowing agents in polyurethane systems shape domestic formulation strategies. Stakeholders must monitor how the EU AI Act's eventual extension to manufacturing process optimization tools reshapes adhesive dispensing automation investments and quality control protocols.
Market Dynamics
Italy's adhesives sector faces a structural pivot where REACH-mandated low-VOC reformulation intersects with the National Recovery and Resilience Plan's embodied carbon targets, forcing procurement systems to requalify supplier bases around certified bio-based feedstocks.
Growth Catalysts
- Infrastructure retrofitting programs:Northern Italy's building stock renovation wave under EU cohesion funds is pulling structural adhesives into concrete repair and seismic reinforcement applications.
- REACH Article 33 compliance deadlines:Substance of Very High Concern disclosure requirements are accelerating substitution of solvent-based systems in Milan-Turin manufacturing corridors.
- Polyurethane reactive hot melts:Automotive lightweighting specifications for battery enclosure bonding are expanding specification windows for moisture-cure PUR systems at Fiat-Stellantis supplier parks.
Market Restraints
- Propylene glycol ether volatility:Petrochemical feedstock cost swings compress margin stability for water-based acrylic formulators serving packaging converters.
- Isocyanate supply concentration:German and Belgian MDI/TDI producers anchor European supply, exposing Italian polyurethane compounders to single-source risk during force majeure events.
- Cyanoacrylate brittleness limitations:Stress-cracking susceptibility in thermoplastic bonding restricts structural load-bearing applications despite fast-cure advantages.
Strategic Opportunities
- Southern Italy construction lag:Campania and Sicily green building code adoption gaps represent whitespace for bio-adhesive distributors establishing regional technical service presence.
- EU Green Deal taxonomy alignment:Do No Significant Harm criteria for construction materials create premium positioning for EPD-certified adhesive systems in public tender pipelines.
- Digital dispensing integration:Convergence of robotics and inline viscosity monitoring enables predictive maintenance contracts displacing traditional equipment sales models.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based polymer synthesis and cure kinetics is concentrating among aging technical staff at established compounders.
- EPD certification timelines:Life cycle assessment documentation requirements for Construction Products Regulation compliance extend product launch cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Adhesives Market |
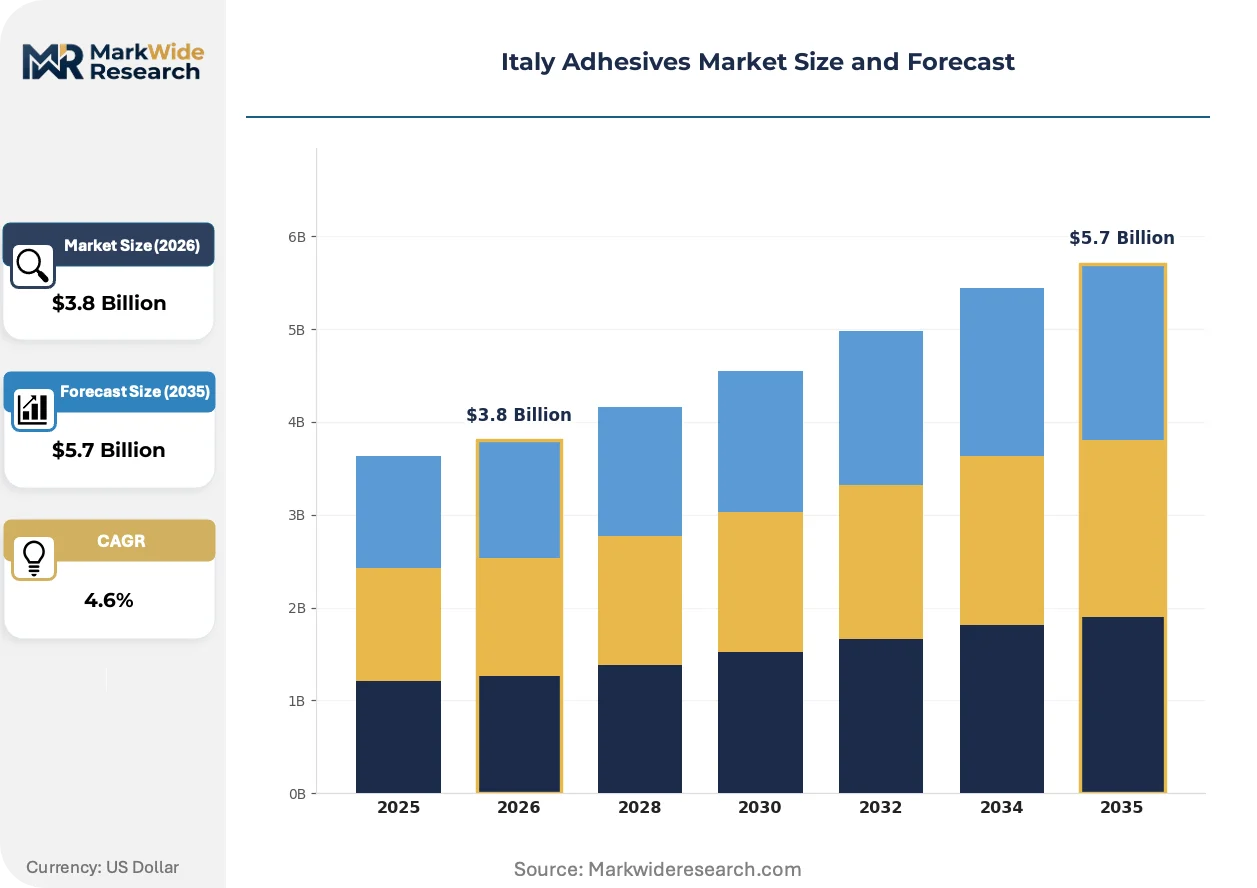
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Construction, Automotive, Packaging, Electronics End User: Manufacturers, Contractors, Retailers, Distributors Formulation: Polyurethane, Epoxy, Silicone, Acrylic |
| Companies Covered | H.B. Fuller Company, Kerakoll, Mapei S.p.A., Bostik, ARDEX, Henkel AG & Co. KGaA, Avery Dennison Corporation, Weber, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Adhesives Market Shifts & Advancements
Formulation chemistry is fragmenting along regulatory fault lines while application equipment digitizes, creating parallel innovation tracks in material science and process control.
Hybrid bio-synthetic resin systems are hybridizing performance characteristics by grafting lignin-derived oligomers onto conventional epoxy backbones. Flooring and tiling contractors in Emilia-Romagna are piloting these systems for commercial installations requiring both Green Building Council certification and heavy traffic durability. The technology is hybridizing procurement specifications by forcing architects to reconcile sustainability mandates with warranty performance clauses previously satisfied by petroleum-based standards.
Italy's transposition of the EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in polyurethane foam adhesives used for insulation panel bonding. Formulators are redirecting R&D spend toward hydrofluoroolefin and hydrocarbon alternatives, compressing development windows for next-generation construction adhesives. The regulatory pressure concentrates most acutely on cold-chain logistics facility builders in Lombardy where thermal performance specifications remain non-negotiable.
Specification authority is migrating from general contractors to facade engineering consultants who unbundle adhesive selection from broader procurement packages. Bologna-based technical consultancies now mandate third-party shear testing and accelerated aging protocols before approving structural glazing systems. This behavioral shift is most visible in high-rise residential towers across Milan's Porta Nuova district where insurance-backed performance guarantees have become standard contract terms.
Italy Adhesives Market Segmentation
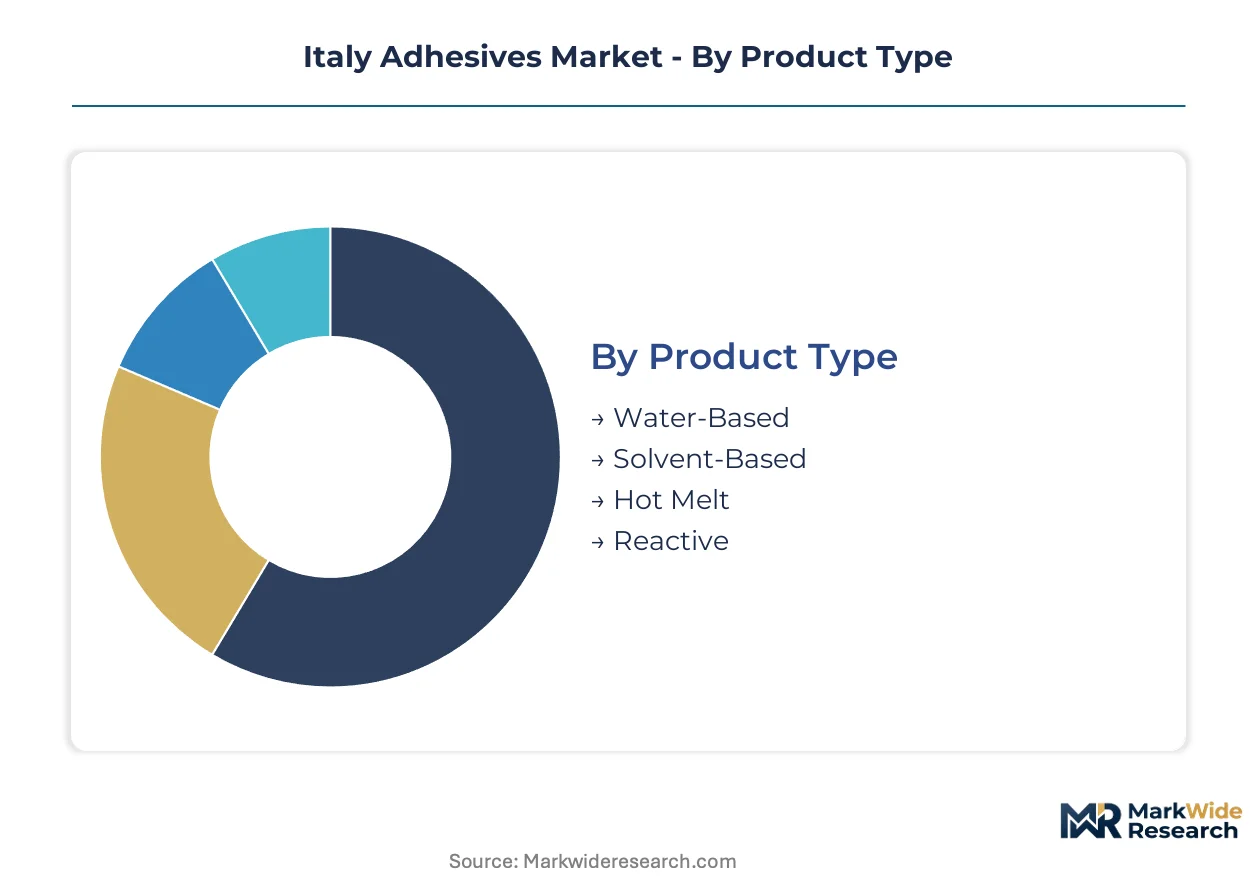
Segmentation reveals how Italy's adhesives sector fragments across incompatible technical specifications and procurement rhythms. Product chemistry and end-use certification requirements create distinct margin pools that resist cross-selling.
Product Type:
Water-based formulations turn inventory fastest in packaging corridors, while reactive systems sit longest as custom-engineered solutions.
- Water-Based:Acrylic and vinyl acetate emulsions suspended in aqueous carriers cure through moisture evaporation. Demand concentrates in Bologna packaging clusters where corrugated board converters face REACH-mandated VOC reductions.
- Solvent-Based:Solutions of natural rubber, polychloroprene, or polyurethane in organic carriers deliver aggressive tack and rapid bond formation. Automotive interior trim assembly in Turin supplier parks sustains specification despite emission compliance costs.
- Hot Melt:Thermoplastic EVA and polyolefin formulations applied molten and set on cooling. E-commerce fulfillment centers around Milan drive consumption of pressure-sensitive variants for carton sealing.
- Reactive:Two-component epoxies and moisture-cure polyurethanes polymerize through chemical crosslinking. Seismic retrofitting contracts in Genoa and Florence specify these for structural concrete bonding.
Water-based systems anchor the volume base while reactive formulations gain share at the steepest rate.
Application:
Construction applications carry the longest sales cycles due to public tender documentation, while electronics procurement operates on quarterly vendor rotations.
- Construction:Tile adhesives, waterproofing membranes, and structural bonding agents for concrete and masonry. The National Recovery and Resilience Plan's building renovation allocations in Lombardy and Veneto are redirecting specifications toward EPD-certified systems.
- Automotive:Structural adhesives for body-in-white assembly, interior trim bonding, and battery enclosure sealing. Fiat-Stellantis production at Mirafiori and Pomigliano d'Arco specifies polyurethane reactive hot melts for lightweighting targets.
- Packaging:Case and carton sealing, label application, and flexible lamination. Northern Italian converting hubs around Bologna and Modena are transitioning water-based systems to meet EU Green Deal embodied carbon thresholds.
- Electronics:Underfill encapsulation, thermal interface materials, and display bonding. Precision dispensing requirements in Veneto's semiconductor packaging subcontractors favor low-outgassing epoxy formulations.
Construction commands the revenue concentration while electronics expands most quickly as reshoring accelerates.
End User:
Manufacturer procurement runs on annual framework agreements with technical qualification gates, whereas retailer replenishment responds to seasonal construction activity.
- Manufacturers:Tier-1 automotive suppliers and appliance OEMs purchasing bulk formulations with embedded application equipment service contracts. Quality agreements specify batch traceability and REACH Article 33 disclosure documentation.
- Contractors:Flooring, tiling, and facade installation specialists procuring through construction merchant channels. Technical support availability influences brand loyalty more than unit pricing in this segment.
- Retailers:DIY chains and specialized construction material stores serving renovation professionals and consumers. Inventory turns accelerate in spring building seasons across Campania and Sicily.
- Distributors:Regional chemical distributors consolidating shipments from multiple formulators for fragmented customer bases. Logistics efficiency and just-in-time delivery capabilities differentiate positioning.
Manufacturers dominate value capture while distributors are climbing the fastest as channel consolidation proceeds.
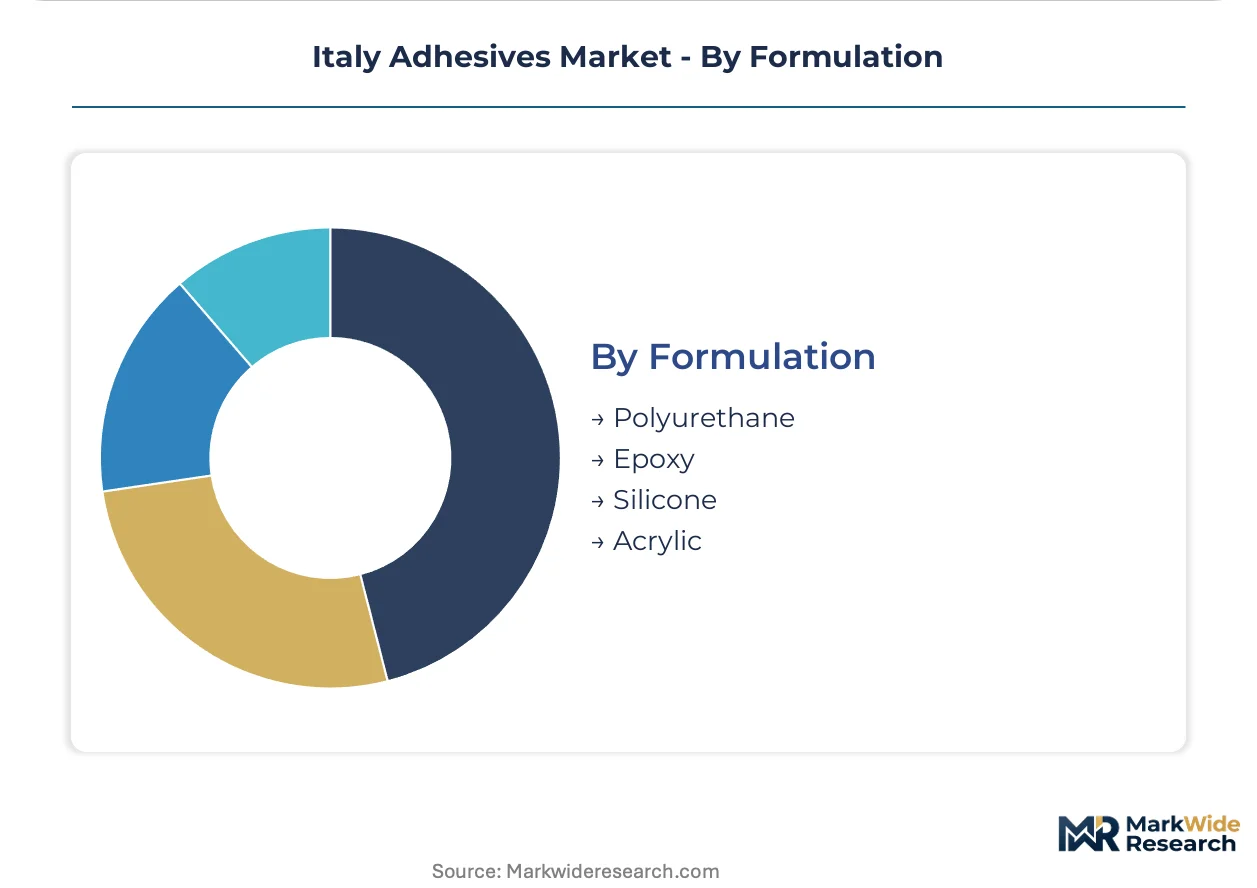
Formulation:
Acrylic systems offer the shortest reformulation cycles for regulatory adaptation, whereas silicone chemistry demands lengthier stability testing.
- Polyurethane:Versatile polymers spanning flexible foams to rigid structural adhesives through isocyanate-hydroxyl reactions. Isocyanate supply concentration from German and Belgian producers exposes Italian compounders to force majeure risk.
- Epoxy:Thermosetting resins formed from epichlorohydrin and bisphenol-A curing with amine or anhydride hardeners. Wind turbine blade manufacturing in Apulia and Sardinia specifies high-modulus variants for composite bonding.
- Silicone:Siloxane backbone polymers delivering temperature resistance and UV stability. Facade glazing consultants in Milan mandate neutral-cure formulations for structural sealant applications.
- Acrylic:Methacrylate and acrylate ester polymers offering optical clarity and rapid UV cure. Electronics display bonding in Veneto favors these for refractive index matching and low yellowing.
Polyurethane anchors the volume base while bio-based acrylic alternatives gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Italian sub-regions, with northern industrial buyers absorbing technical premiums for certified formulations while southern construction markets prioritize unit economics over sustainability credentials.
Lombardy
Automotive lightweighting and battery enclosure bonding specifications at Fiat-Stellantis facilities drive reactive polyurethane consumption. ECHA REACH Article 33 compliance deadlines force Milan-area formulators to requalify solvent-based systems. The Milan-Bergamo corridor concentrates precision electronics adhesive demand from semiconductor packaging subcontractors.
Piedmont
Turin automotive supplier parks specify moisture-cure PUR systems for body-in-white assembly amid Stellantis production targets. EU Green Deal embodied carbon thresholds redirect procurement toward EPD-certified construction adhesives. The Turin-Asti axis anchors Italy's highest concentration of automotive OEM technical qualification gates.
Emilia-Romagna
Bologna packaging clusters transition water-based acrylic systems to meet EU Green Deal VOC reduction mandates. The National Recovery and Resilience Plan's building renovation allocations pull structural adhesives into seismic retrofitting contracts. Flooring contractors in Modena pilot hybrid bio-synthetic resin systems for Green Building Council certification.
Veneto
Semiconductor packaging subcontractors in the Verona-Vicenza zone favor low-outgassing epoxy formulations for display bonding. REACH-mandated substance disclosure requirements accelerate substitution schedules among electronics assemblers. The region's precision dispensing equipment density exceeds national averages threefold.
Campania and Sicily
Green building code adoption gaps create whitespace for bio-adhesive distributors establishing technical service presence. Southern construction markets lag northern procurement sophistication, prioritizing inventory turns over formulation certification. Naples and Palermo merchant channels remain underpenetrated by EPD-certified system suppliers.
Italy Adhesives Market Competitive Landscape
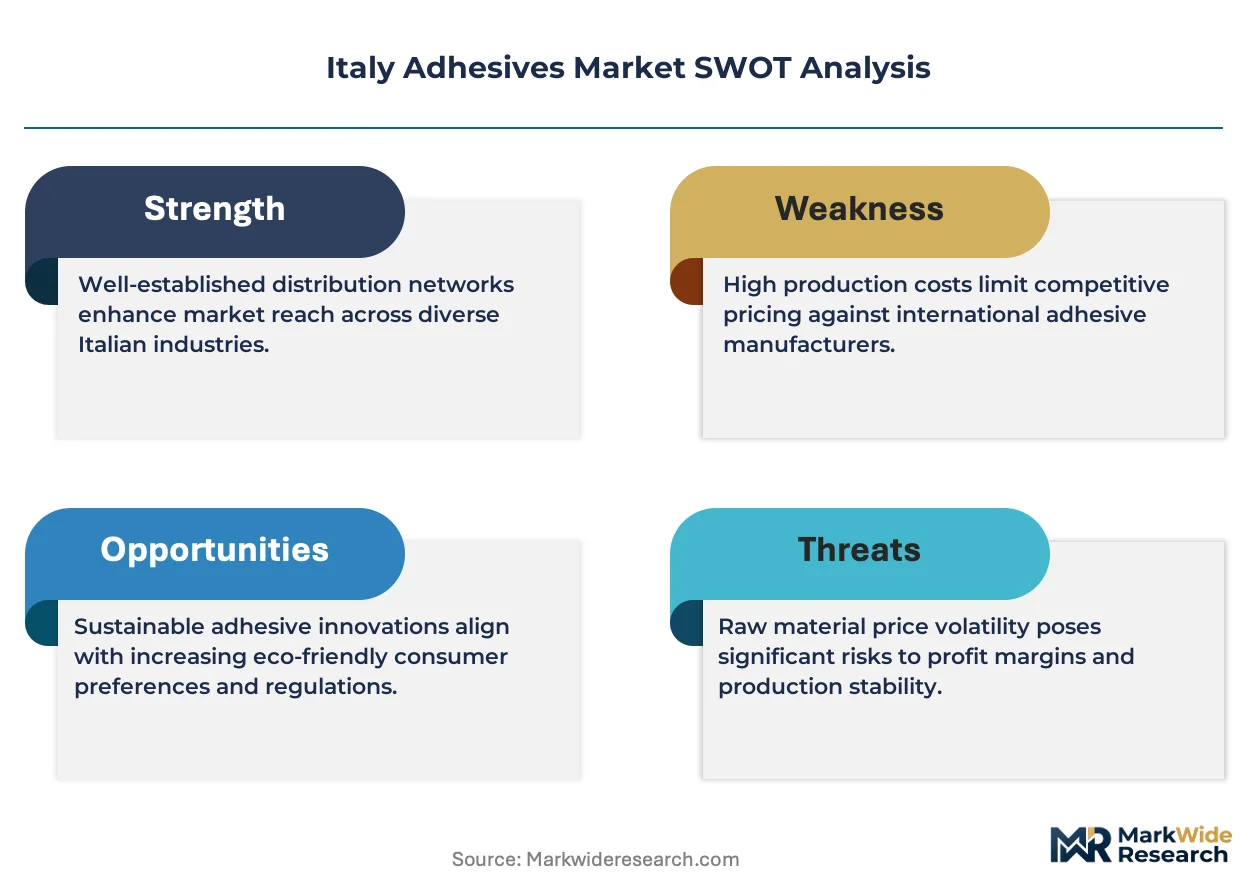
Capability concentration sits with specialty formulators possessing in-house polymer synthesis expertise; scale advantage sits with diversified chemical conglomerates commanding raw material procurement leverage. The Italian adhesives sector exhibits tiered structure with premium positions held by construction-focused specialists, mid-market share contested by multinational subsidiaries, and commodity segments served by regional distributors. Three archetypes dominate: vertically integrated cementitious compounders, bio-based formulation innovators, and application equipment-anchored service providers. Competitive moves center on EPD certification acquisition for public tender eligibility and predictive maintenance contract displacement of traditional equipment sales.
Within the specialty construction tier, Mapei S.p.A. and Kerakoll exemplify divergent strategic positions—Mapei representing manufacturing scale through captive resin operations near Milan, Kerakoll occupying bio-based formulation leadership targeting green building certification channels. H.B. Fuller Company anchors the multinational distribution archetype, leveraging Italian network infrastructure to secure premium specification positions. These three players collectively illustrate how technical qualification depth, sustainability credentialing, and service integration separate margin pools from commodity bulk sales.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Kerakoll |
| Mapei S.p.A. |
| Bostik |
| ARDEX |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Weber |
| Sika AG |
| Others |
Supply & Pricing Matrix
Isocyanate supply concentration from German and Belgian MDI/TDI producers determines both margin compression severity for Italian polyurethane compounders and the three-tier pricing structure separating premium reactive systems from commodity water-based formulations. REACH Article 33 compliance costs propagate downstream through tiered certification premiums, while energy volatility in hot melt processing feeds back into supplier selection criteria favoring regional formulators with captive power arrangements.
Pricing Analysis
Aftermarket service contracts for application equipment calibration anchor lifetime value capture, displacing transactional bulk sales as the dominant revenue model. Three-tier pricing structure across premium EPD-certified, standard REACH-compliant, and economy non-certified levels separates specification-grade construction adhesives from packaging commodity volumes. Cost compression in water-based acrylic segments intensifies because propylene glycol ether feedstock volatility erodes formulator margins. Retailer channels serving Campania and Sicily renovation markets exhibit highest price sensitivity, whereas automotive OEM technical qualification gates at Fiat-Stellantis facilities absorb premium positioning for moisture-cure polyurethane systems.
Supply Chain Analysis
Upstream petrochemical feedstock production centers on Germany, Belgium, and the Netherlands for isocyanate precursors essential to polyurethane formulation. Italian compounders draw from concentrated MDI/TDI supply anchored in northwest European production hubs, with secondary dependence on Saudi and Qatari propylene derivatives for acrylic monomer streams. Single-source vulnerability during force majeure events at Antwerp-Rotterdam chemical corridors represents the dominant structural risk. Distribution runs through regional chemical distributors consolidating multi-formulator shipments for fragmented construction merchant and automotive supplier park channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's adhesives sector sits at a platform-economics inflection where digital dispensing equipment convergence with predictive maintenance software restructures vendor-customer relationships from product transactions to outcome-based service platforms. Equipment-anchored service integration by H.B. Fuller and Mapei illustrates how interoperability standards for viscosity monitoring and robotic application systems are consolidating procurement authority around integrated solution providers.
For Market Incumbents: Insulate specification positions in northern industrial corridors by deepening backward integration into bio-based resin synthesis and acquiring EPD certification capacity for National Recovery and Resilience Plan tender eligibility. Kerakoll's bio-formulation leadership and Mapei's captive Milan-area resin operations demonstrate how upstream control over certified feedstock supply neutralizes margin pressure from REACH-mandated reformulation cycles. For New Entrants and Emerging Players: Southern Italy's green building code adoption gaps in Campania and Sicily represent the most penetrable entry point for bio-adhesive distributors establishing technical service presence ahead of regulatory harmonization. Construction merchant channels in Naples and Palermo remain underpenetrated by EPD-certified system suppliers. A regional technical service partnership model with local flooring and tiling contractor networks offers the lowest customer acquisition cost pathway. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty formulators possessing in-house polymer synthesis expertise and established green building certification channel relationships. Long-term viability across the analysis window hinges on EPD documentation capabilities and digital dispensing equipment service integration. The signal to watch is public tender pipeline share migration toward EPD-certified systems in Lombardy and Veneto infrastructure retrofitting contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Synthesis | Kerakoll's lignin-derived oligomer grafting secures feedstock independence from petrochemical volatility. |
| EPD Certification Acquisition | Do No Significant Harm criteria under EU Green Deal taxonomy unlock public tender eligibility in Lombardy. |
| Predictive Maintenance Contract Displacement | H.B. Fuller's equipment-anchored service model captures recurring revenue from Milan automotive supplier parks. |
| Regional Technical Service Expansion | Whitespace penetration in Campania merchant channels builds positioning ahead of southern green code adoption. |
| Digital Dispensing Platform Integration | Inline viscosity monitoring convergence with robotics reconfigures procurement authority toward integrated solution vendors. |
Research Methodology
Desk research of ECHA REACH substance databases, EU Green Deal regulatory filings, and Italian National Recovery and Resilience Plan procurement allocations preceded structured interviews with formulation chemists at compounders, procurement leads at Fiat-Stellantis supplier parks, construction merchant channel managers, and facade engineering consultants in Milan and Bologna. Secondary validation drew from SEC 10-K filings of multinational adhesive producers, Cefic chemical industry reports, and customs trade data for isocyanate and acrylic monomer imports. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators for Italian construction and automotive output.
Forecast assumptions held fixed the current EU regulatory framework trajectory including REACH Article 33 compliance deadlines and F-Gas Regulation transposition timelines, while varying construction sector investment intensity and automotive production volume scenarios across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry certification requirements, and regional procurement sophistication gradients. CAGRs were derived from elasticity-adjusted demand projections for each segment, incorporating formulation substitution rates driven by VOC regulation tightening and bio-based feedstock cost convergence assumptions.
Practitioners should monitor ECHA SVHC candidate list expansions, force majeure declarations at northwest European isocyanate facilities, and southern Italian green building code adoption timelines for early signals necessitating forecast revision. Cross-checking against Cefic chemical production statistics and Italian construction permit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market