
 Asia-Pacific Flock Adhesives Market | 2026-2036
Asia-Pacific Flock Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flock Adhesives Market Outlook
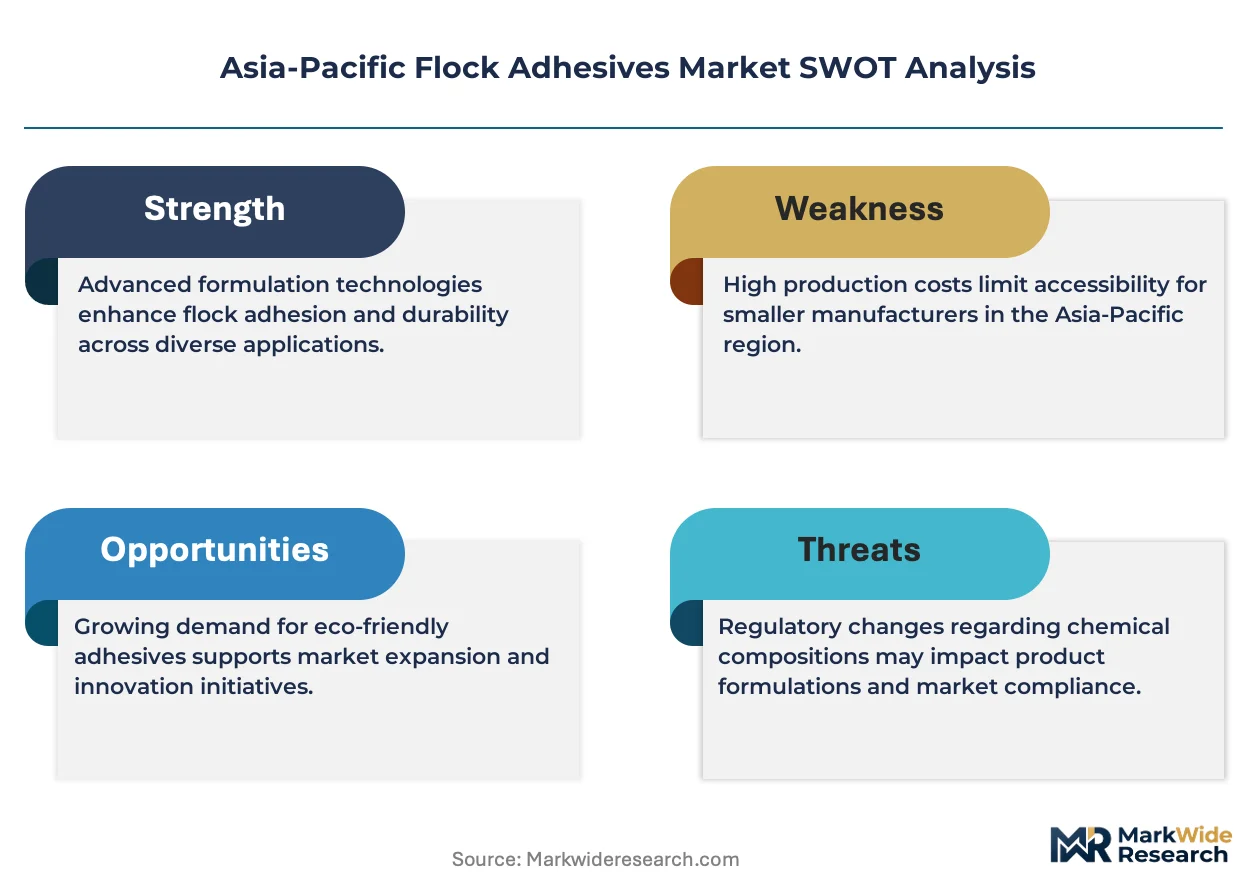
Market Dynamics
China's Yangtze River Delta manufacturing corridor is fragmenting as new adhesive compounding facilities enter production across Vietnam and Indonesia. Sika AG leverages its polyurethane technology portfolio to anchor premium automotive seating programs with Japanese OEM suppliers. Henkel AG & Co. KGaA sustains broad formulation capabilities spanning water-based and hot-melt platforms for textile flocking operations. Arkema Group differentiates through specialty acrylic chemistry tailored to Southeast Asian humidity conditions.
Technical Profile and Segment Structure
Asia-Pacific flock adhesives are bonding agents engineered to secure short fiber filaments onto substrates, typically formulated with solids content between 40% and 60% and cured through thermal or moisture-activated crosslinking to deliver abrasion resistance in interior surfaces. Water-based adhesives dominate volume consumption across textile applications in China and India, while polyurethane adhesives command premium positioning in automotive interior programs requiring heat-aging performance above 120°C. Spray application technology leads installation throughput for large-area automotive components, though roller application retains share in furniture manufacturing where edge-definition precision governs quality acceptance.
Regulatory Environment and Outlook
China's MEE enforces GB standards limiting VOC emissions from adhesive formulations, while India's BIS certification mandates product testing for industrial chemical imports. Japan's METI chemical substance reporting framework adds compliance layers for cross-border formulation shipments. Stakeholders must monitor evolving substance restrictions across multiple national frameworks to maintain formulation registrations and avoid supply interruptions.
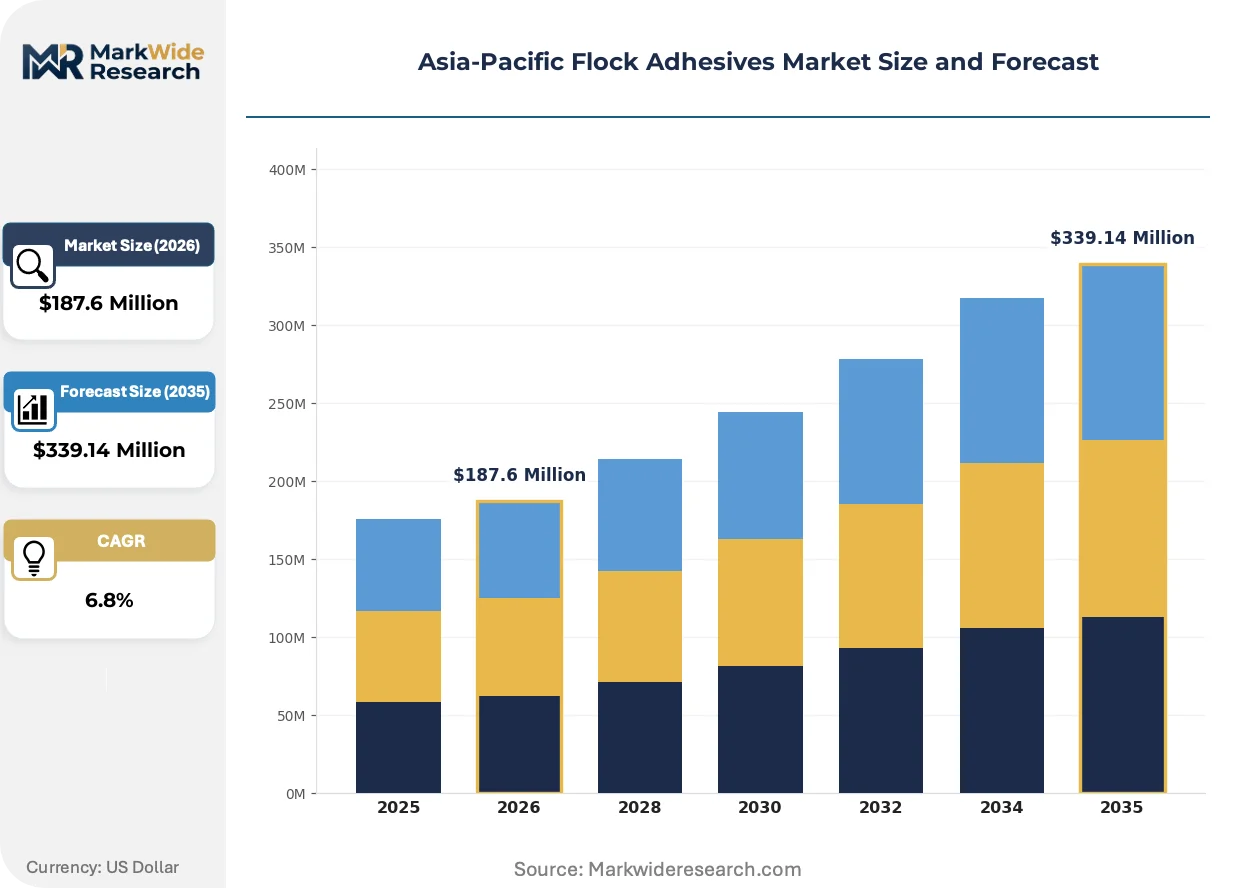
Market Dynamics
China's MEE enforcement of GB VOC emission standards is fragmenting adhesive formulation supply chains across the Asia-Pacific, forcing compounders to relocate production or reformulate water-based systems for textile and automotive applications.
Growth Catalysts
- Automotive Interior Expansion:Japanese and Korean OEMs are expanding sourcing from Thailand and Vietnam assembly plants, requiring heat-resistant polyurethane flock adhesives for seating and dashboard programs that withstand tropical aging conditions.
- GB Standards Compliance:China's MEE enforcement of VOC limits in industrial coatings is accelerating water-based adhesive substitution across Jiangsu and Zhejiang textile clusters, creating formulation upgrade demand.
- Hot-Melt Technology Maturation:Reactive polyurethane hot-melt systems are penetrating furniture manufacturing in Indonesia and Malaysia, offering solvent-free curing with bond strengths matching conventional solventborne platforms.
Market Restraints
- Isocyanate Feedstock Volatility:Polyurethane adhesive margins compress when MDI and polyol prices spike, particularly affecting automotive seating compounders in South Korea and Japan with limited backward integration into petrochemicals.
- Zhejiang Supply Concentration:Water-based acrylic adhesive production clusters heavily in eastern China, exposing downstream textile flockers in Bangladesh and Vietnam to single-source geographic risk during regional power rationing or environmental inspections.
- Curing Speed Limitations:Water-based systems require 8-12 minute thermal drying cycles that throttle automotive component throughput versus solventborne alternatives, constraining adoption in high-volume Japanese OEM just-in-sequence supply chains.
Strategic Opportunities
- Vietnam Manufacturing Absorption:Footwear and furniture OEMs are relocating from China to Ho Chi Minh City and Binh Duong provinces, creating localized adhesive blending demand that bypasses cross-border formulation import tariffs.
- India PLI Scheme Leverage:India's production-linked incentive scheme for automotive components is drawing seating suppliers to Chennai and Pune, opening specification windows for domestic flock adhesive producers to displace European imports.
- UV-LED Curing Convergence:Photoinitiator-acrylate formulations combined with UV-LED lamp arrays are enabling instant cure for small-part automotive trim, potentially displacing thermal ovens in Indonesian and Thai component plants.
Industry Challenges
- Formulation Chemist Scarcity:Southeast Asian adhesive producers face acute shortages of polymer scientists capable of balancing humidity-stable crosslinking with low-VOC compliance, particularly in Indonesia and Philippines operations.
- BIS Certification Timelines:India's Bureau of Indian Standards testing protocols for imported industrial chemicals extend 14-18 months, delaying market entry for Japanese and Korean compounders targeting automotive supply chain qualification.
- Legacy Solventborne Infrastructure:Textile flocking houses across Bangladesh and Pakistan retain capital-intensive thermal oxidizer investments optimized for solvent recovery, complicating water-based system retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flock Adhesives Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $339.14 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based Adhesives, Solvent-based Adhesives, Hot-melt Adhesives, Polyurethane Adhesives End-Use Industry: Automotive, Textiles, Packaging, Furniture Technology: Spray Application, Roller Application, Screen Printing, Hand Application Form: Liquid, Paste, Powder, Film |
| Companies Covered | Sika AG, CHT Group, Arkema Group, Henkel AG & Co. KGaA, H.B. Fuller Company, Lord Corporation, Stahl Holdings B.V., Kissel + Wolf, Bostik SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flock Adhesives Market Strategic Shifts
Formulation chemistry and application equipment are converging to eliminate solvent dependence while accelerating production throughput across Asia-Pacific manufacturing clusters.
Moisture-curing silane-terminated polyurethane technology is rendering obsolete conventional two-component solventborne systems in automotive interior applications. Korean and Japanese seating suppliers are adopting single-component pumpable adhesives that eliminate mixing stations and pot-life constraints. This shift is compressing equipment footprints and reducing volatile organic compound emissions without sacrificing heat-aging performance above 120°C.
China's MEE is tightening GB 30982-2014 enforcement for adhesive VOC content in textile and automotive applications, mandating sub-50g/L formulations in Yangtze River Delta manufacturing zones. Compounders are responding with water-based acrylic and polyurethane hybrid systems that sacrifice some initial tack for regulatory compliance. Small-batch furniture manufacturers in Zhejiang face disproportionate reformulation costs versus integrated automotive suppliers with captive R&D.
Japanese automotive OEMs are consolidating approved adhesive supplier lists from 12-15 vendors to 4-6 strategic partners, compressing qualification cycles and elevating technical service expectations. Tier-2 seating manufacturers in Thailand and Indonesia now require compounders to maintain local application laboratories and 48-hour failure-analysis response. This concentration is visible in Toyota and Honda supply chains, where specification lock-in creates multi-year revenue visibility for qualified adhesive producers.
Asia-Pacific Flock Adhesives Market Segmentation
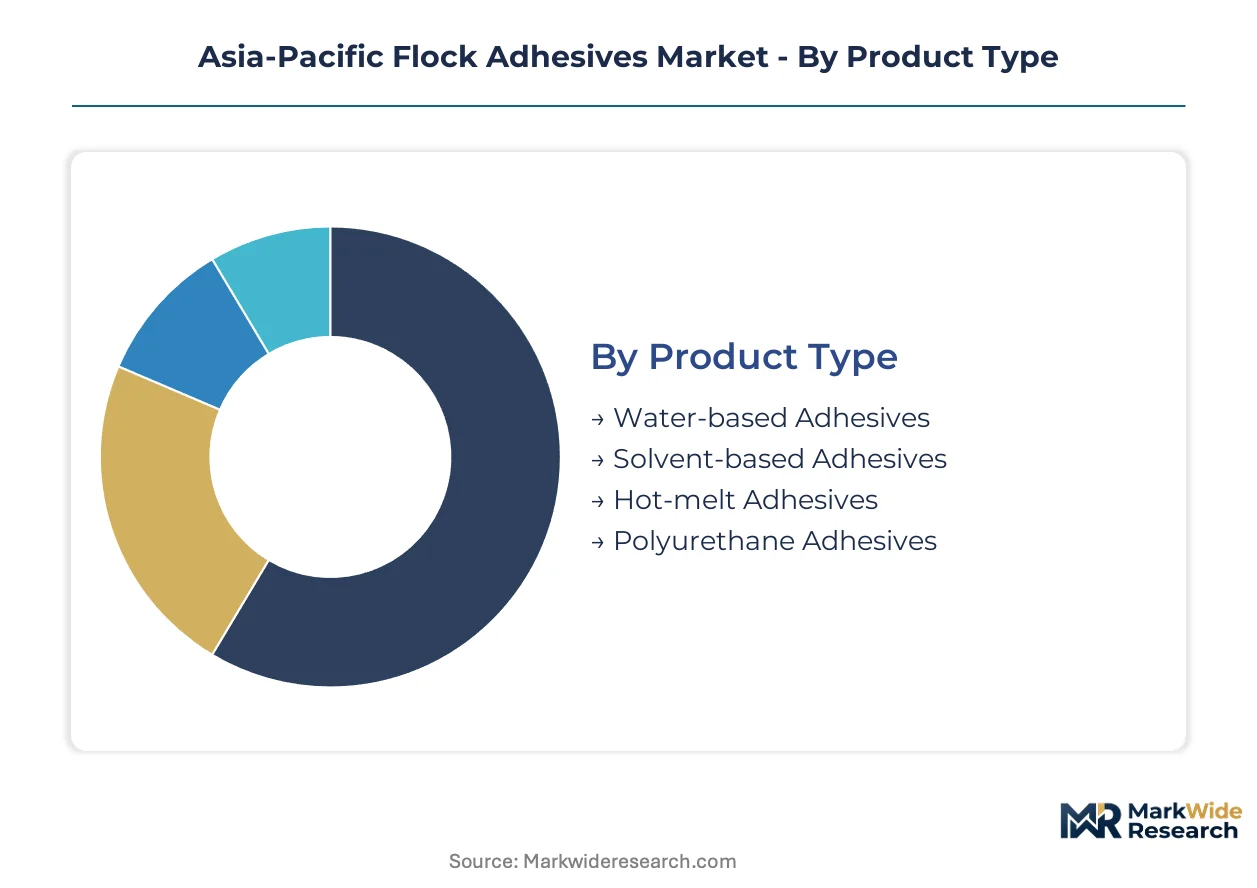
Flock adhesive segmentation in Asia-Pacific reflects divergent technical requirements across automotive seating, textile flocking, and furniture manufacturing. Formulation chemistry, application method, and physical form determine specification windows for procurement teams in China, India, and Southeast Asia.
Product Type:
Cost tier differentiation separates commodity water-based systems from premium polyurethane platforms serving heat-aging specifications.
- Water-based Adhesives:Acrylic and polyurethane dispersions with 40-60% solids content dominate textile applications in Jiangsu and Zhejiang provinces. China's MEE enforcement of GB VOC limits is accelerating substitution for solventborne systems in automotive interior programs.
- Polyurethane Adhesives:Two-component and moisture-curing formulations deliver bond strength retention above 120°C for Japanese OEM seating specifications. Korean and Thai automotive suppliers specify these for tropical aging resistance in dashboard and door panel applications.
- Solvent-based Adhesives:Declining share in China due to MEE regulatory pressure; retains niche in Bangladesh and Pakistan textile operations with legacy thermal oxidizer infrastructure.
- Hot-melt Adhesives:Reactive polyurethane systems penetrate Indonesian and Malaysian furniture manufacturing, offering solvent-free curing with instant green strength.
Water-based adhesives hold installed capacity across eastern China textile clusters. Polyurethane adhesives are rotating up the share rankings in automotive supply chains.
End-Use Industry:
Application-specific performance requirements fragment demand across mobility, apparel, and interior furnishings.
- Automotive:Dashboard, door panel, and seating applications require heat-resistant bonding with abrasion resistance for 10-year service life. Japanese OEM consolidation to 4-6 approved adhesive suppliers elevates technical service requirements for compounders.
- Textiles:Fabric flocking for apparel and upholstery drives volume consumption in China and India. Water-based acrylics serve high-throughput roller application lines in Jiangsu province.
- Furniture:Wood and synthetic substrate bonding in Indonesia and Vietnam favors hot-melt systems for edge-definition precision.
- Packaging:Decorative flocking for premium cosmetics and electronics boxes utilizes screen-printable adhesives with fine fiber control.
Automotive specifications command premium pricing. Textile applications deliver volume scale.
Technology:
Application equipment selection governs throughput economics and finish quality across manufacturing segments.
- Spray Application:Automated robotic systems coat large-area automotive components with uniform fiber deposition. Japanese OEM just-in-sequence supply chains favor spray technology for dashboard and pillar trim.
- Roller Application:Precision coating for furniture edges and textile widths retains share where definition accuracy determines quality acceptance. Zhejiang furniture manufacturers specify roller systems for consistent film thickness.
- Screen Printing:Selective flock deposition for packaging graphics and automotive emblems enables multi-color registration.
- Hand Application:Small-batch furniture and repair operations in Vietnam and Philippines utilize manual methods for custom work.
Spray application holds installed capacity in automotive Tier-1 plants. Roller application maintains share in furniture manufacturing.
Form:
Physical state determines storage, handling, and conversion economics for adhesive processors.
- Liquid:Pumpable dispersions dominate water-based and solventborne systems for automated application. China's Yangtze River Delta compounding facilities ship bulk liquid to textile flockers.
- Paste:High-viscosity formulations for screen printing and thick-film deposition in packaging applications.
- Powder:Thermoplastic adhesives for heat-activated bonding in specialty textile laminations.
- Film:Pre-cast adhesive layers for precision lamination in automotive interior trim assembly.
Liquid form holds installed capacity across Asia-Pacific manufacturing. Paste formulations are rotating up the share rankings in packaging specialty applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors regulatory momentum across the Asia-Pacific flock adhesives landscape, with GB standards enforcement cascading formulation requirements through manufacturing clusters in Jiangsu, Zhejiang, and beyond.
China
Automotive interior programs and textile flocking operations drive adhesive consumption across the Yangtze River Delta. MEE enforcement of GB 30982-2014 mandates sub-50g/L VOC formulations in Jiangsu and Zhejiang provinces, forcing water-based system upgrades. Manufacturing clusters in Suzhou and Hangzhou are absorbing reformulation costs while maintaining supply to Japanese OEM seating suppliers.
India
Dashboard and door panel applications are expanding flock adhesive procurement from automotive interior manufacturers in Chennai and Pune. BIS certification protocols extend 14-18 months for imported industrial chemicals, delaying market entry for foreign compounders. The PLI scheme for automotive components is drawing seating suppliers to domestic production bases, opening specification windows for local adhesive producers.
Japan
Heat-resistant polyurethane formulations serve OEM specifications requiring bond strength retention above 120°C for tropical aging resistance. METI chemical substance reporting frameworks add compliance layers for cross-border formulation shipments. Toyota and Honda supply chains are consolidating approved adhesive suppliers from 12-15 vendors to 4-6 strategic partners, elevating technical service requirements.
Thailand
Japanese and Korean OEMs are expanding sourcing from assembly plants in the Eastern Economic Corridor, requiring heat-resistant adhesives for seating and dashboard programs. Local component manufacturers face qualification cycles compressed by OEM consolidation strategies. Tier-2 seating suppliers now require compounders to maintain local application laboratories and 48-hour failure-analysis response.
Vietnam
Footwear and furniture OEMs are relocating from China to Ho Chi Minh City and Binh Duong provinces, creating localized adhesive blending demand. Cross-border formulation import tariffs are bypassed through domestic compounding investments. Small-batch furniture manufacturers face disproportionate reformulation costs versus integrated automotive suppliers with captive technical resources.
Asia-Pacific Flock Adhesives Market Competitive Environment
Specialty chemical conglomerates and adhesive pure-plays split the Asia-Pacific flock adhesives market between premium automotive specifications and volume textile applications. The vendor base clusters around three strategic archetypes: diversified multinational chemical groups with polyurethane technology portfolios, focused adhesive formulators with water-based platform expertise, and regional compounders serving localized furniture and footwear demand. Competitive positioning hinges on M&A activity to acquire humidity-stable formulation capabilities and capacity expansion in Vietnam and Indonesia to bypass Chinese regulatory compliance costs.
Within the diversified multinational tier, Sika AG and Henkel AG & Co. KGaA exemplify scale-driven positioning, while Arkema Group occupies a specialty acrylic chemistry niche. Among focused adhesive specialists, H.B. Fuller Company and Bostik SA represent mid-cap formulators with hot-melt and water-based platform breadth. Regional compounders include Stahl Holdings B.V. and Kissel + Wolf, which sit within the European-origin specialist tier serving automotive and textile segments. Lord Corporation and CHT Group exemplify technology-focused players with reactive chemistry portfolios. The "Others" category captures Southeast Asian domestic blenders and Chinese state-affiliated chemical groups with limited cross-border qualification.
| Leading Market Players |
|---|
| Sika AG |
| CHT Group |
| Arkema Group |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Lord Corporation |
| Stahl Holdings B.V. |
| Kissel + Wolf |
| Bostik SA |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's water-based acrylic adhesive production concentration anchors margin pools downstream, with textile flockers in Bangladesh and Vietnam absorbing geographic risk premiums during regional power rationing or environmental inspections. Automotive seating compounders in Thailand and Indonesia command pricing leverage through specification lock-in with Japanese OEMs, while furniture manufacturers in Vietnam face cost compression from cross-border tariff exposure.
Pricing Analysis
Price spreads between Chinese domestic supply and Southeast Asian import formulations run 15-25 percent after freight and duty layering. Three-tier pricing structure across premium polyurethane, standard water-based acrylic, and economy solventborne levels segments buyer archetypes by certification grade and volume scale. Pricing pressure stems from MDI and polyol feedstock volatility squeezing polyurethane adhesive margins in South Korea and Japan. Tier-2 automotive seating suppliers exhibit highest price sensitivity due to compressed qualification cycles, while Japanese OEM direct specifications show lowest sensitivity given 10-year service life requirements.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk calculus for footwear and furniture OEMs relocating to Ho Chi Minh City and Binh Duong provinces. Raw material sourcing draws from Chinese petrochemical hubs for acrylic monomers, German and Japanese suppliers for specialty isocyanates, and regional palm oil derivatives for polyurethane polyols. Single-source vulnerability concentrates in eastern China's Yangtze River Delta adhesive compounding facilities. Distribution runs through bulk liquid tanker shipments to textile clusters, with drum packaging for small-batch furniture operations across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific flock adhesives represent a high-growth disruption as China's MEE enforcement of GB VOC standards forces system-wide formulation substitution across textile and automotive supply chains. Moisture-curing silane-terminated polyurethane technology is rendering obsolete conventional solventborne platforms.
For Market Incumbents: Harden specification lock-in with Japanese OEMs through captive application laboratories in Thailand and Indonesia, compressing qualification windows for challengers. Deepen backward integration into specialty isocyanate supply to buffer MDI price volatility affecting automotive seating margins. Prioritize humidity-stable formulation R&D to defend premium positioning against Arkema's acrylic chemistry advances in Southeast Asian conditions. For New Entrants and Emerging Players: Build out localized compounding capacity in Vietnam's Binh Duong province to capture footwear and furniture OEM demand bypassing Chinese cross-border tariffs. Target India's Chennai automotive cluster where PLI scheme incentives are drawing seating suppliers and BIS certification timelines delay European import qualification. Lead with reactive polyurethane hot-melt systems offering solvent-free curing with instant green strength for Indonesian furniture manufacturers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across water-based adhesive platforms as environmental compliance costs migrate to larger integrated compounders. Five-to-ten year viability favors acquisition targets with captive humidity-stable formulation capabilities and established automotive qualification records. Watch for UV-LED curing technology adoption rates in Thai and Indonesian component plants as inflection indicator for photoinitiator-acrylate formulation displacement potential.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New compounding facilities in Vietnam bypass Chinese MEE compliance costs for footwear OEMs. |
| Backward Integration | Captive isocyanate production buffers Korean compounders against MDI price volatility. |
| Green Manufacturing Transition | Water-based system upgrades satisfy Jiangsu province GB 30982-2014 VOC mandates. |
| Long-term Supply Agreement | Strategic partnerships with Toyota and Honda create multi-year revenue visibility. |
| Joint Venture | Local laboratories in Thailand satisfy Tier-2 seating supplier technical service demands. |
Study Parameters
Cross-validation between executive interviews and customs trade data anchors the qualitative findings across the Asia-Pacific flock adhesives landscape. Primary fieldwork engaged adhesive formulators, automotive Tier-1 procurement leads, textile plant managers, and furniture manufacturing technical directors. Secondary sources included China customs export records, Japanese METI chemical substance filings, Indian BIS certification databases, and ACC regional chemical industry reports. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Calibration against historical capacity utilization and disclosed expansion timelines validates the projection framework across the analysis window. Segmentation dimensions include formulation chemistry tier, end-use industry vertical, application technology, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand curves incorporating automotive build rates and textile output indices. Feedstock price scenarios and regulatory enforcement intensity serve as sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-affiliated chemical groups would shift outcomes through price-led market share capture. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market