
 Europe Roll Forming Body in White Market | 2026-2036
Europe Roll Forming Body in White Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Roll Forming Body in White Market Foresight
Asset-light leasing models for roll-forming equipment is narrowing the capital barrier for mid-tier suppliers entering the Europe Roll Forming Body in White Market. Gestamp Automoción leverages its vertical integration across stamping and assembly to sustain cost advantages in chassis programs. Voestalpine Group anchors its position through captive steel supply and advanced metallurgy R&D in Austrian production hubs. Benteler International competes via specialized hot-formed tube and roll-formed structural expertise for premium vehicle architectures.
Roll forming Body in White denotes the production of uncoated sheet metal structural assemblies through continuous bending of coiled strip material, typically achieving tolerances within 0.5 mm for automotive crash-management applications. The process employs sequential sets of contoured rolls to progressively shape steel or aluminum into closed or open profiles, serving as the primary load-bearing skeleton before painting and final assembly. Chassis segments dominate current output value given crash-performance requirements and high-strength steel penetration, while aluminum side panels represent the fastest-expanding material category as OEMs pursue mass reduction targets. Steel-based floor structures remain the most mature segment with stable margins, whereas composite-reinforced roof applications concentrate emerging margin pools among technology-leading Tier-1 suppliers.
EU Green Deal carbon-border adjustments and REACH material compliance frameworks are reshaping raw material sourcing requirements for European BIW suppliers. ECHA substance restrictions on hexavalent chromium coatings and the F-Gas Regulation governing thermal processes in manufacturing are forcing process technology upgrades across the supply base. The EU AI Act quality-management standards for automated roll-forming lines will further filter market access. Stakeholders must monitor regulatory sequencing between material compliance deadlines and capital equipment replacement cycles to avoid stranded asset risk.
Market Dynamics
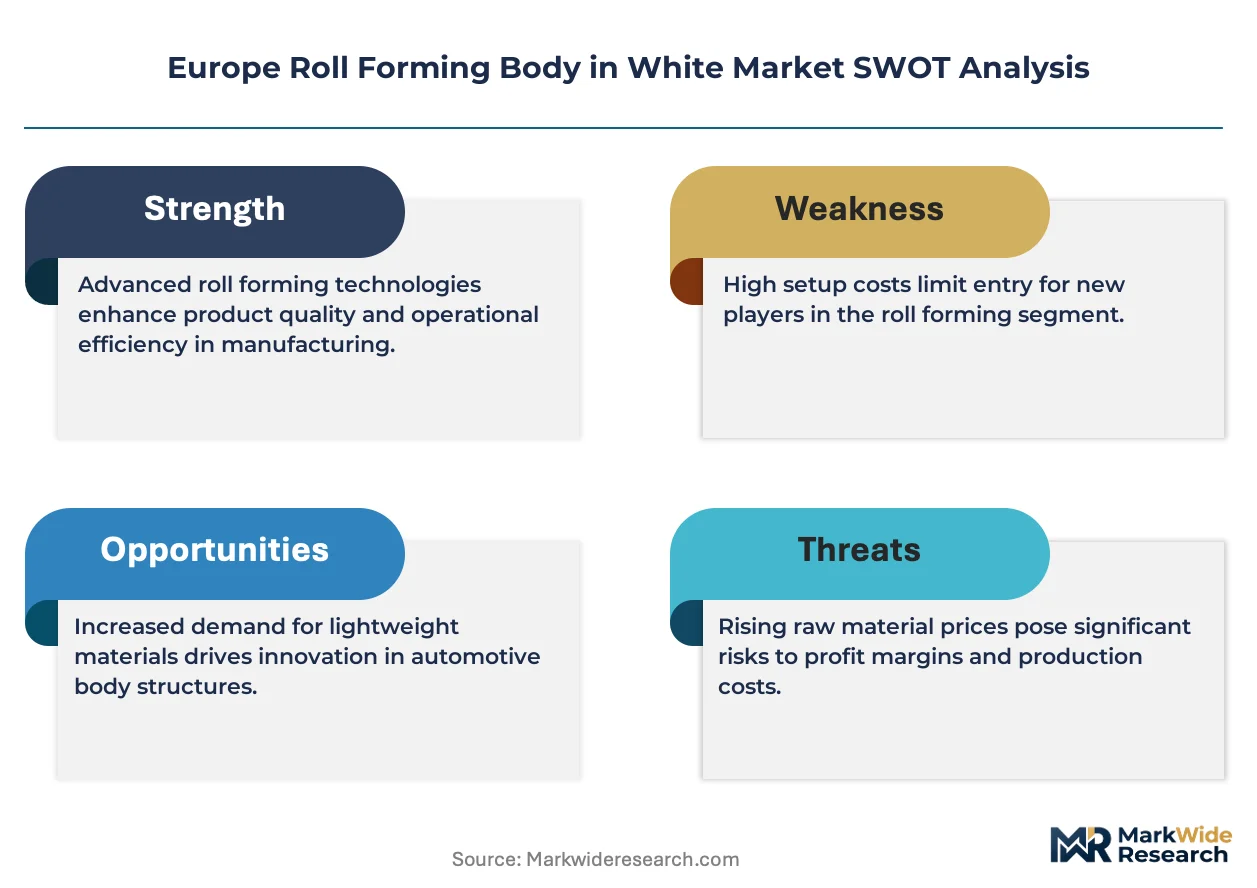
EU Green Deal carbon-border adjustments and REACH material compliance frameworks are compressing supplier margins while forcing capital-intensive process upgrades across European BIW production networks.
Growth Catalysts
- EU fleet CO2 standards:Tightened emissions mandates accelerate OEM substitution from conventional steel toward advanced high-strength grades and aluminum in chassis structures.
- Electric vehicle platforms:Battery-electric architectures demand lightweight roll-formed components for range optimization, pulling capacity expansion at specialized Tier-1 suppliers.
- Stuttgart-Wolfsburg-Munich production triangle:Concentrated automotive OEM presence anchors dense supplier ecosystems and just-in-time delivery infrastructure for roll-formed BIW parts.
Market Restraints
- Aluminum price volatility:Energy-intensive smelting costs and LME price swings compress margin predictability for suppliers expanding aluminum capacity.
- ECHA substance restrictions:Phased bans on hexavalent chromium coatings force costly surface-treatment process conversions before equipment depreciation cycles complete.
- Hot-forming technology substitution:Press-hardened steel competes for crash-critical applications, limiting roll-forming penetration in the highest-strength structural segments.
Strategic Opportunities
- Poland-Czech Republic manufacturing corridors:Lower labor and energy costs relative to Western Europe attract greenfield roll-forming investments serving German OEM supply chains.
- EU AI Act quality-management standards:Early compliance with automated line certification requirements filters market access for technology-leading suppliers.
- Composite-reinforced roof modules:Hybrid material architectures open margin pools in premium vehicle segments seeking mass reduction beyond conventional metals.
Industry Challenges
- High-strength steel metallurgy expertise:Shortage of process engineers capable of managing springback control in 1500 MPa-grade roll-formed profiles constrains output quality.
- F-Gas Regulation thermal process compliance:Replacement of industrial heating systems for aluminum roll-forming lines demands capital deployment ahead of regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Roll Forming Body in White Market |
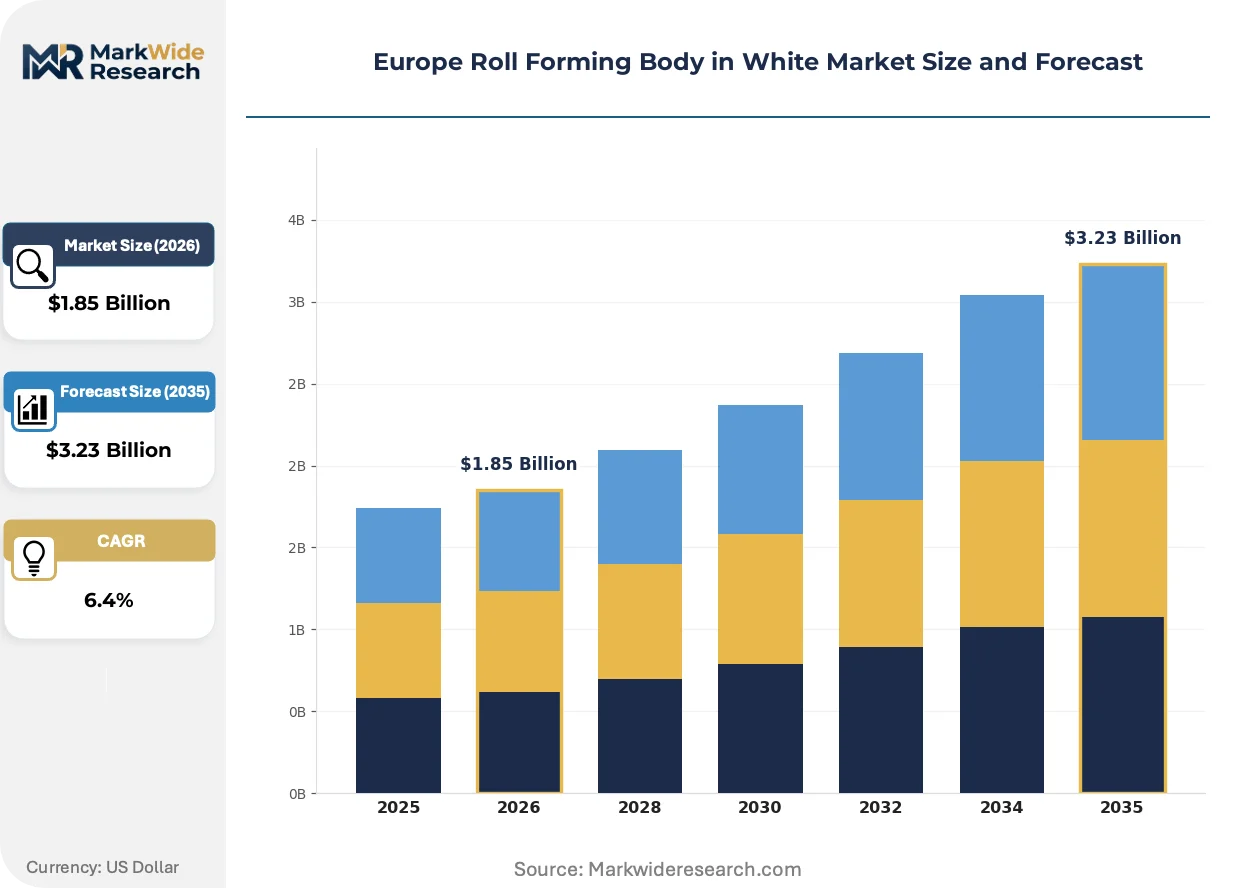
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chassis, Roof, Floor, Side Panels Material: Steel, Aluminum, Composite, Others End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Hot Rolled, Cold Rolled, Galvanized, Laser Cutting |
| Companies Covered | Gestamp Automoción, Voestalpine Group, Benteler International, KIRCHHOFF Automotive, Thyssenkrupp, Magna International, CIE Automotive, Martinrea International, Tower International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Roll Forming Body in White Market Shifts & Advancements
Process digitization and material science advances are compressing development cycles for complex profile geometries while regulatory compliance requirements fragment supplier technical capabilities.
Advanced high-strength steel with tailored tempering properties is hybridizing conventional cold-forming boundaries. Premium German OEMs are adopting these grades for battery enclosure rails and side-impact beams. The technology is hybridizing supplier capability requirements, forcing simultaneous mastery of metallurgy, simulation, and inline quality verification.
REACH authorization timelines for chromium(VI) alternatives are compressing coating technology roadmaps. ECHA sunset dates force qualification of trivalent chromium and zirconium-based pretreatments across automotive supplier tiers. Southern European stamping subcontractors face the steepest compliance cost burdens relative to integrated northern competitors.
Consolidated procurement desks at major OEMs are centralizing supplier qualification and squeezing contract durations. Long-term framework agreements are displacing spot purchasing for structural BIW components. German and French automotive procurement organizations are most advanced in this transition, compressing margin negotiation leverage for mid-tier roll-forming specialists.
Europe Roll Forming Body in White Market Segmentation
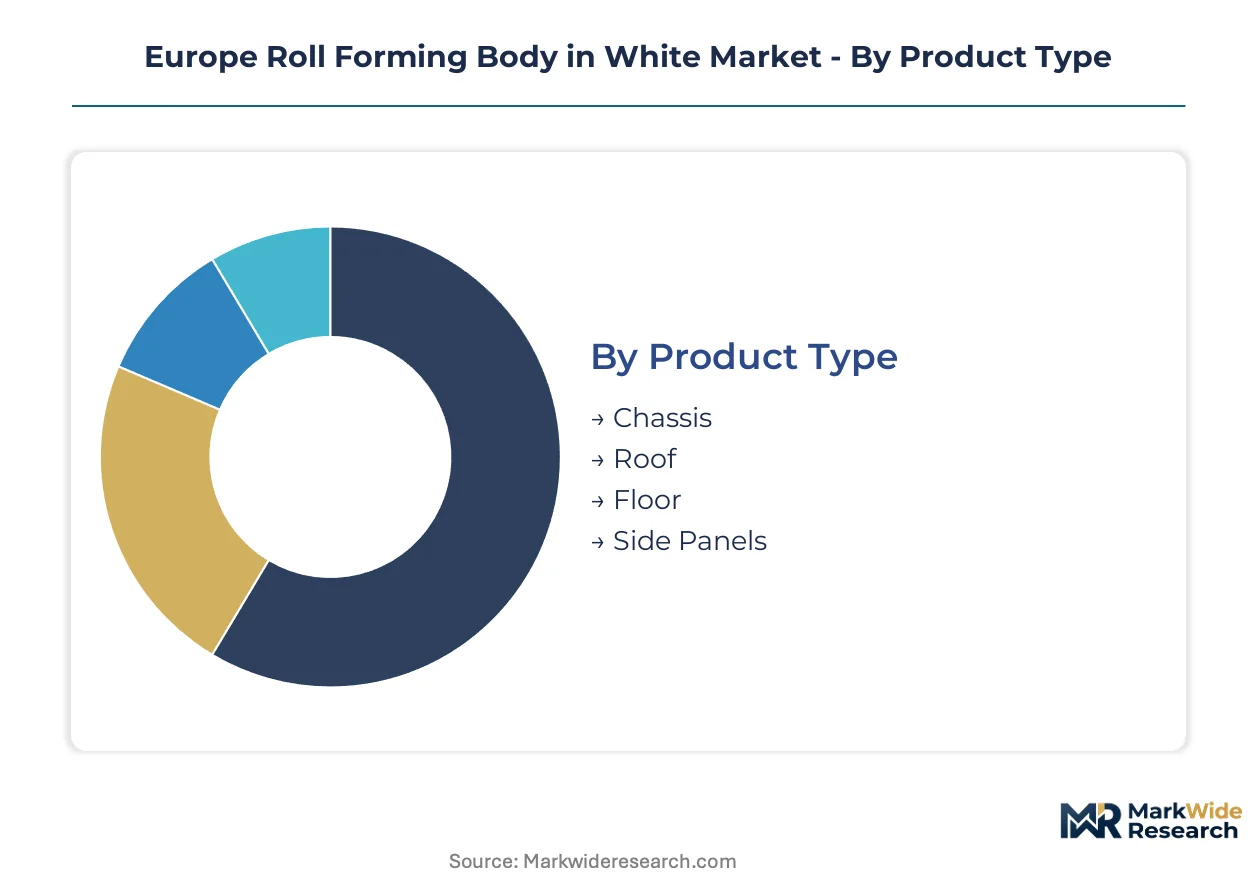
Roll-formed BIW components serve distinct functional roles across vehicle architectures, with material selection and manufacturing technology determining crash performance, mass efficiency, and compliance with EU emissions mandates. Segmentation reveals where capital deployment concentrates and where margin compression threatens supplier viability.
Product Type:
Chassis structures absorb the highest engineering investment given crash-critical performance requirements, while roof and floor modules present divergent paths for material substitution and automation intensity.
- Chassis:Closed and open profiles in advanced high-strength steel form crash-management rails, subframes, and battery enclosure structures. German OEMs at Stuttgart and Wolfsburg anchor demand as electric platforms require reinforced underbody architectures to protect battery packs.
- Roof:Composite-reinforced hybrid modules are gaining traction in premium architectures seeking mass reduction beyond conventional metals. Austrian and Bavarian production hubs concentrate emerging capacity for these specialized applications.
- Floor:Steel-based crossmembers and tunnel reinforcements remain the most mature segment with stable margins and established supply relationships.
- Side Panels:Aluminum outer skin and structural reinforcements serve aerodynamic and weight targets in battery-electric vehicle programs.
The dominant share belongs to Chassis, while Roof is closing the gap fastest.
Material:
Cost tiers separate commodity-grade feedstock from metallurgically complex grades requiring captive R&D partnerships with European steel mills.
- Steel:Conventional mild grades dominate volume, but advanced high-strength variants with tailored tempering properties are capturing value in crash-critical applications. Voestalpine Group and ArcelorMittal supply these grades to German Tier-1 roll-formers.
- Aluminum:Energy-intensive smelting costs and LME volatility compress margin predictability for suppliers expanding capacity. Side panels and battery enclosures pull demand from Norwegian and Icelandic primary aluminum sources.
- Composite:Glass- and carbon-fiber reinforced polymers hybridize with metal substrates in roof modules.
- Others:Magnesium extrusions and polymer-metal laminates serve niche mass-reduction applications in limited-volume premium vehicles.
Steel retains volume leadership, though Aluminum is expanding most quickly as OEMs pursue fleet CO2 compliance through lightweighting.
End User:
Customer type determines contract duration, technical qualification barriers, and exposure to OEM consolidation of procurement desks.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz operate captive roll-forming capacity for strategic chassis programs while outsourcing standardized floor structures.
- Tier-1 Suppliers:Gestamp Automoción, Benteler International, and CIE Automotive manage integrated stamping and roll-forming operations for just-in-time delivery to German production clusters.
- Aftermarket Providers:Crash-repair structural components serve insurance-driven demand with shorter lead times and lower metallurgical complexity.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source standardized profiles for low-volume production runs.
Tier-1 Suppliers command the largest outsourced share, while Aftermarket Providers are gaining relevance as vehicle parc age extends repair-cycle demand.
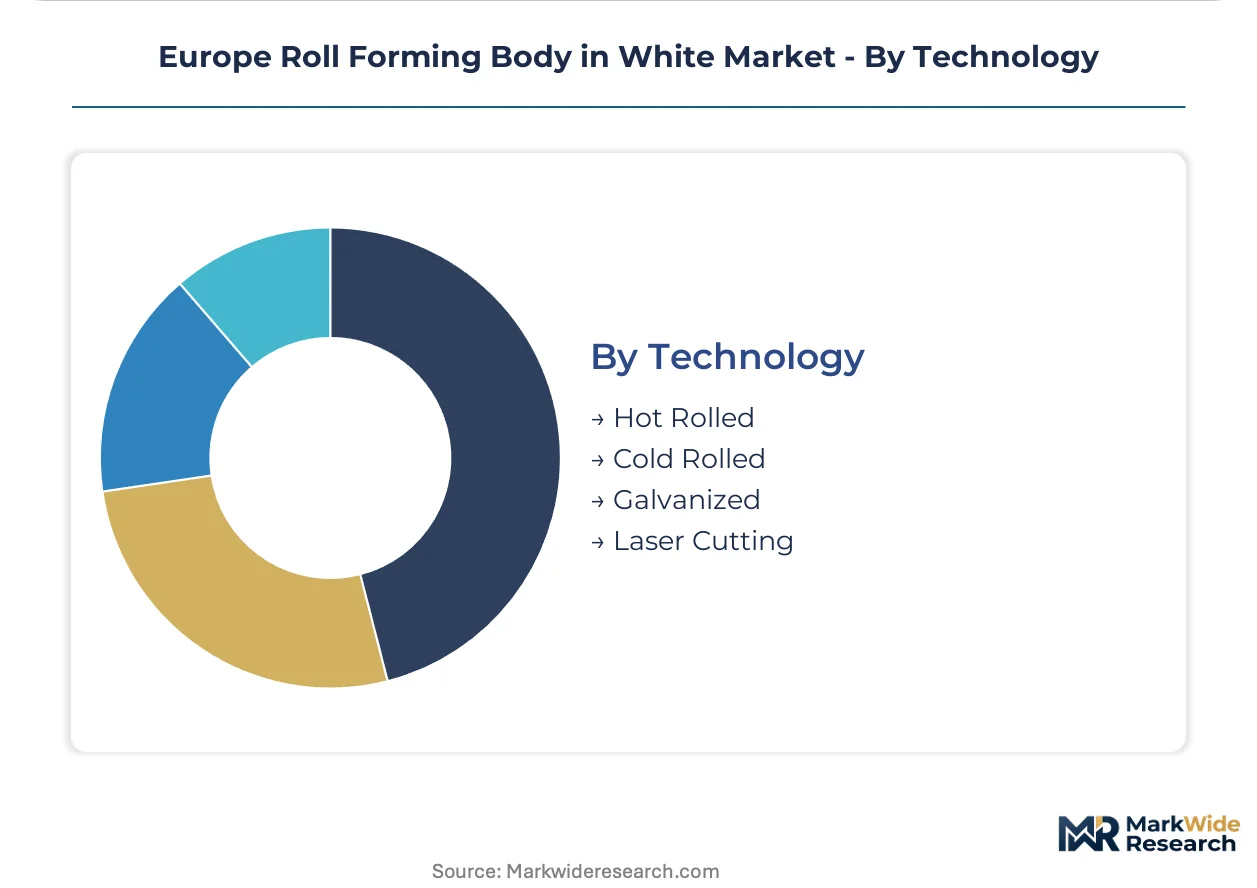
Technology:
Process maturity and capital intensity separate high-volume cold-forming from specialized thermal and precision cutting operations.
- Hot Rolled:Initial forming of thick-gauge strip for chassis rails and structural reinforcements. Polish and Czech manufacturing corridors are attracting greenfield investments in hot-rolled capacity to serve German OEM supply chains.
- Cold Rolled:Precision tolerance achievement within 0.5 mm for automotive crash-management applications defines the core roll-forming value proposition.
- Galvanized:Zinc-coated strip provides corrosion protection for exposed underbody components in markets with aggressive road salt exposure.
- Laser Cutting:Inline precision trimming of complex profile geometries enables part consolidation and assembly automation.
Cold Rolled underpins baseline output, yet Laser Cutting is climbing the fastest as inline automation requirements intensify under EU AI Act quality-management standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement desks concentrate the highest-value roll-formed BIW contracts, while Eastern European manufacturing corridors attract capacity expansion serving just-in-time supply chains.
Germany
Volkswagen Group, BMW, and Mercedes-Benz battery-electric platforms pull demand for lightweight chassis structures. KBA vehicle-type approval requirements and EU fleet CO2 standards tighten material specifications for structural components. The Stuttgart-Wolfsburg-Munich production triangle anchors dense supplier ecosystems with Voestalpine and Gestamp operating integrated facilities.
Poland
Lower labor and energy costs relative to Western Europe attract greenfield roll-forming investments from German Tier-1 suppliers. EU Green Deal carbon-border adjustments reshape raw material sourcing compliance for exported components. The Silesian and Greater Poland manufacturing corridors concentrate new capacity serving Volkswagen and BMW assembly plants.
Czech Republic
Škoda Auto and Hyundai Motor Manufacturing anchor demand for chassis and floor structures in electric vehicle programs. REACH material compliance frameworks and ECHA substance restrictions force coating technology upgrades across supplier tiers. The Moravian-Silesian Region hosts expanding roll-forming operations feeding German OEM supply chains.
Spain
SEAT and Mercedes-Benz Vitoria operations drive demand for aluminum side panels and structural reinforcements. F-Gas Regulation thermal process compliance forces heating system replacements in aluminum roll-forming lines. The Basque Country and Catalonia concentrate automotive supplier clusters with specialized hot-forming expertise.
Italy
Stellantis Mirafiori and Pomigliano plants require roll-formed battery enclosure structures for electric platform architectures. CE marking and EU AI Act quality-management standards filter automated line certification requirements. Lombardy and Piedmont engineering clusters support precision tooling development for complex profile geometries.
Europe Roll Forming Body in White Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure consolidates around integrated Tier-1 suppliers with captive metallurgy partnerships and captive OEM relationships. Three archetypes dominate: steel-mill-integrated fabricators with backward raw material control, multi-process automotive specialists combining stamping and assembly capabilities, and precision-profile engineering houses serving niche premium architectures. Competitive moves concentrate on geographic expansion into Eastern European corridors and technology licensing for composite-reinforced hybrid modules.
Among integrated European automotive suppliers, Gestamp Automoción, Voestalpine Group, and Benteler International occupy positions reflecting distinct strategic anchors. Gestamp exemplifies the multi-process specialist archetype with operations spanning forming technologies and assembly integration. Voestalpine represents steel-mill-integrated fabrication with captive metallurgy supply from Austrian production hubs. Benteler sits within the precision-profile engineering tier, anchoring specialized structural expertise for premium vehicle architectures. These three entities collectively illustrate how supplier positioning stratifies across material control, process breadth, and architectural specialization vectors.
| Leading Market Players |
|---|
| Gestamp Automoción |
| Voestalpine Group |
| Benteler International |
| KIRCHHOFF Automotive |
| Thyssenkrupp |
| Magna International |
| CIE Automotive |
| Martinrea International |
| Tower International |
| Others |
Supply & Pricing Matrix
Austrian steel production hubs anchored by Voestalpine concentrate advanced high-strength steel supply, directing margin pools toward Tier-1 suppliers with captive metallurgy partnerships and away from stamping subcontractors dependent on spot market feedstock.
Pricing Analysis
Certification level under EU AI Act quality-management standards creates the primary spread between technology-leading suppliers and mid-tier competitors. Cold-rolled precision tolerance achievement within 0.5 mm commands premium positioning for crash-critical chassis applications, while standardized floor structures trade at compressed rates. Cost compression in aluminum roll-forming lines is intensifying because energy-intensive smelting costs and LME volatility erode margin predictability. Aftermarket providers exhibit highest price sensitivity due to insurance-driven demand and shorter contract durations, whereas German OEM captive operations show lowest sensitivity given strategic program control.
Supply Chain Analysis
Extended payment terms from consolidated procurement desks at Volkswagen Group and BMW strain working capital for mid-tier roll-forming specialists. Raw material sourcing draws from Austrian steel mills, Norwegian and Icelandic primary aluminum, and German toolmaking clusters. Single-source vulnerability concentrates in advanced high-strength steel grades requiring captive R&D partnerships with European steel producers. Distribution runs through just-in-time delivery infrastructure anchored in the Stuttgart-Wolfsburg-Munich production triangle.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Press-hardened steel substitution for crash-critical applications threatens roll-forming penetration in the highest-strength structural segments, forcing incumbents to defend process-specific advantages through material science differentiation.
For Market Incumbents: Entrench metallurgical expertise in 1500 MPa-grade springback control to defend against press-hardened steel substitution for battery enclosure rails. Expand backward integration into captive steel supply through Austrian or German mill partnerships. Prioritize EU AI Act compliance certification to filter market access for automated roll-forming lines. For New Entrants and Emerging Players: Pursue Poland-Czech Republic manufacturing corridors where lower labor and energy costs relative to Western Europe attract greenfield investments serving German OEM supply chains. Target composite-reinforced roof modules in premium vehicle architectures seeking mass reduction beyond conventional metals. Lead with specialized hot-formed tube expertise for niche structural applications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-profile engineering houses in Bavarian and Austrian production hubs. Five-to-ten year viability hinges on technology licensing for hybrid material architectures and geographic expansion into Eastern European corridors. Monitor ECHA sunset dates for chromium(VI) alternatives as inflection indicator for coating technology upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive metallurgy partnerships with Voestalpine or ArcelorMittal secure advanced high-strength grade access for crash-critical programs. |
| EU AI Act Compliance Certification | Automated line quality-management standards filter market access and concentrate contracts with technology-leading Tier-1 suppliers. |
| Eastern European Manufacturing Expansion | Polish and Czech greenfield investments capture cost advantages while maintaining just-in-time delivery to German OEM clusters. |
| Composite-Reinforced Roof Module Development | Hybrid material architectures open margin pools in premium segments seeking mass reduction beyond conventional metals. |
| Chromium(VI) Coating Process Conversion | ECHA sunset date compliance forces qualification of trivalent chromium alternatives before equipment depreciation cycles complete. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, roll-forming plant managers, and aftermarket distribution heads. Secondary validation drew from KBA vehicle-type approval databases, EU ECHA substance restriction timelines, steel mill production disclosures, and automotive production registration data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Calibration against historical production volumes and disclosed capacity expansions shaped projections across the analysis window. Segmentation dimensions modeled include product type, material grade, end-user category, and manufacturing technology intensity. CAGRs derived from regression analysis of content-per-vehicle trends in battery-electric architectures and fleet CO2 compliance trajectories. Forecast inputs incorporated EU Green Deal carbon-border adjustment implementation schedules and REACH authorization timelines.
Sensitivities concentrate around aluminum price volatility, ECHA regulatory sequencing, and OEM platform standardization decisions. Forecasts reflect documented assumptions on material substitution rates and equipment replacement cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
France Commercial Vehicles Lubricants Market