
 Automotive Canister Purge Valve Market | 2026-2036
Automotive Canister Purge Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Canister Purge Valve Market Analytics
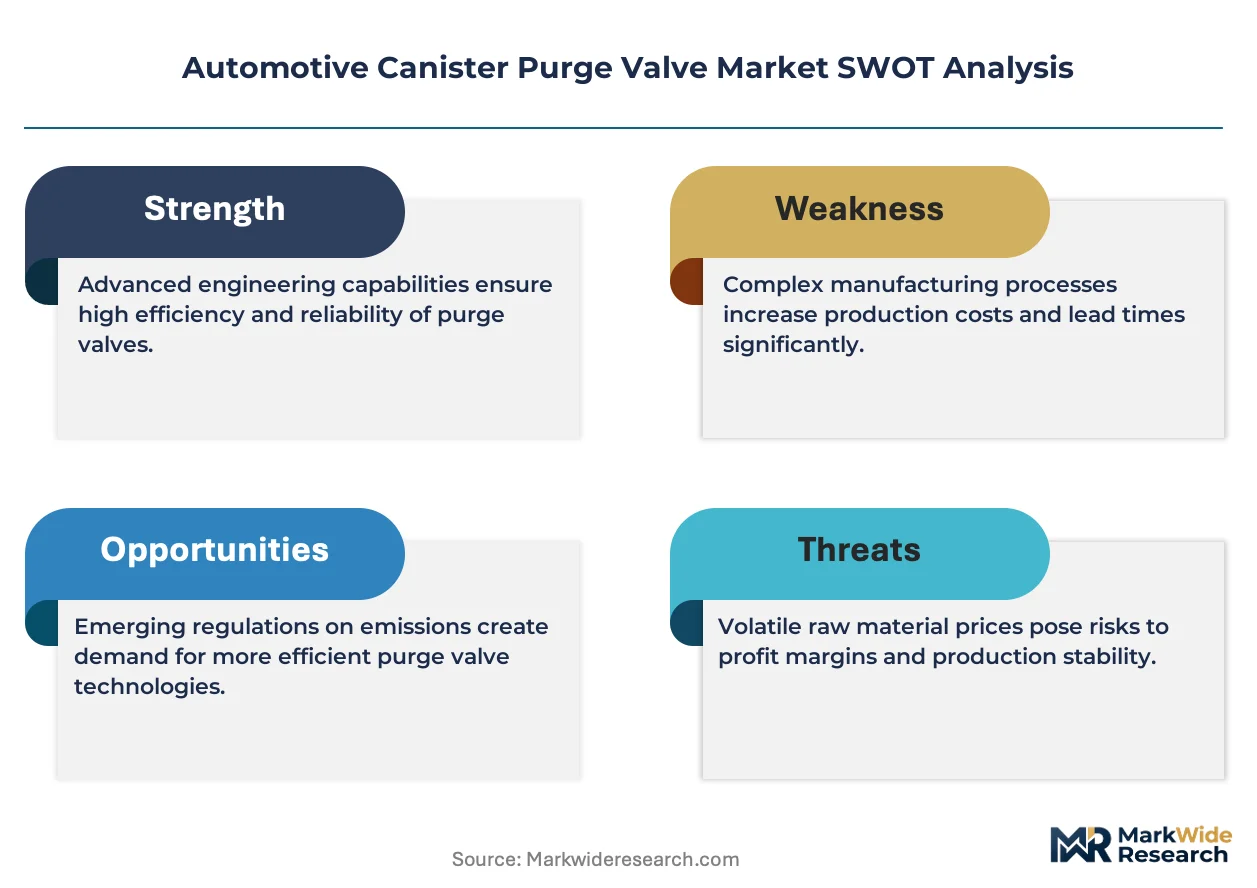
Aftermarket service revenue is narrowing as OEMs extend powertrain warranties and integrate sealed fuel vapor recovery systems. Continental AG leverages its integrated sensor-actuator platforms to control Tier-1 supplier relationships across European passenger vehicle programs. Robert Bosch GmbH sustains manufacturing scale through captive solenoid production in Germany and Mexico. Denso Corporation anchors Asia-Pacific supply chains with JIS-certified valve assemblies for hybrid powertrains.
An automotive canister purge valve is an electromechanical device, typically employing a solenoid coil with copper windings and a nitrile rubber seal, that meters fuel vapor flow between the charcoal canister and the engine intake manifold to prevent hydrocarbon release. Its primary purpose is maintaining evaporative emission compliance while optimizing air-fuel mixture ratios during cold-start and cruising conditions. Solenoid-type purge valves command the largest installed base due to proven durability in petrol applications, yet electromagnetic variants are gaining share where millisecond-precision vapor metering supports hybrid engine restart sequences. Aftermarket Providers represent a structurally distinct channel where universal-fit valves compete on price against OEM-captive custom-fit designs.
EPA Tier 3 tailpipe and evaporative standards in the United States, Euro 7 emission frameworks under EMA review, and China's GB 18352.6 national standards collectively mandate sub-20-micron leak rates that force valve seal material upgrades. NHTSA safety recalls for stuck-open purge valves in prior model years amplify OEM liability exposure and accelerate design validation cycles. Stakeholders must monitor how California Air Resources Board zero-emission vehicle mandates redistribute engineering resources between internal combustion purge systems and battery thermal management.
Market Dynamics
Stringent evaporative emission standards are forcing valve architecture redesigns as regulators tighten leak-rate tolerances below 20 microns, compressing development cycles and elevating material specification requirements across supplier tiers.
Growth Catalysts
- Euro 7 Framework:EMA review of evaporative emission limits is accelerating procurement of electromagnetic purge valves with millisecond-precision metering capability for hybrid restart sequences.
- Hybrid Powertrain Expansion:Japan and Germany OEMs are integrating advanced purge systems into gasoline-electric architectures where engine-off vapor management demands precise valve control.
- Copper Winding Demand:Solenoid coil specifications are tightening as Tier-1 suppliers specify higher-grade conductive materials to meet durability targets under thermal cycling stress.
Market Restraints
- Nitrile Rubber Supply Concentration:Seal material production clusters in Southeast Asia create vulnerability to petrochemical feedstock volatility and logistics disruption.
- EPA Tier 3 Validation Burden:Extended certification timelines for sub-20-micron leak performance are stretching R&D budgets and delaying program launches.
- Battery Electric Substitution:Zero-emission vehicle mandates in California and analogous jurisdictions are eroding addressable volume for internal combustion purge systems.
Strategic Opportunities
- India BS-VI Phase II:Stricter evaporative norms are opening procurement windows for electromagnetic valve suppliers as domestic OEMs upgrade emission hardware.
- Sensor-Actuator Convergence:Integration of pressure sensing with valve control electronics is enabling predictive diagnostic capabilities and service contract bundling.
- Aftermarket Channel Digitization:E-commerce platforms for universal-fit valves are capturing price-sensitive replacement demand outside franchised dealer networks.
Industry Challenges
- Electromagnetic Calibration Expertise:Shortage of engineers skilled in millisecond-response solenoid design is constraining supplier scaling for hybrid applications.
- Legacy System Integration:Retrofitting advanced purge valves into existing charcoal canister architectures without triggering NHTSA recall exposure requires extensive validation testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Canister Purge Valve Market |
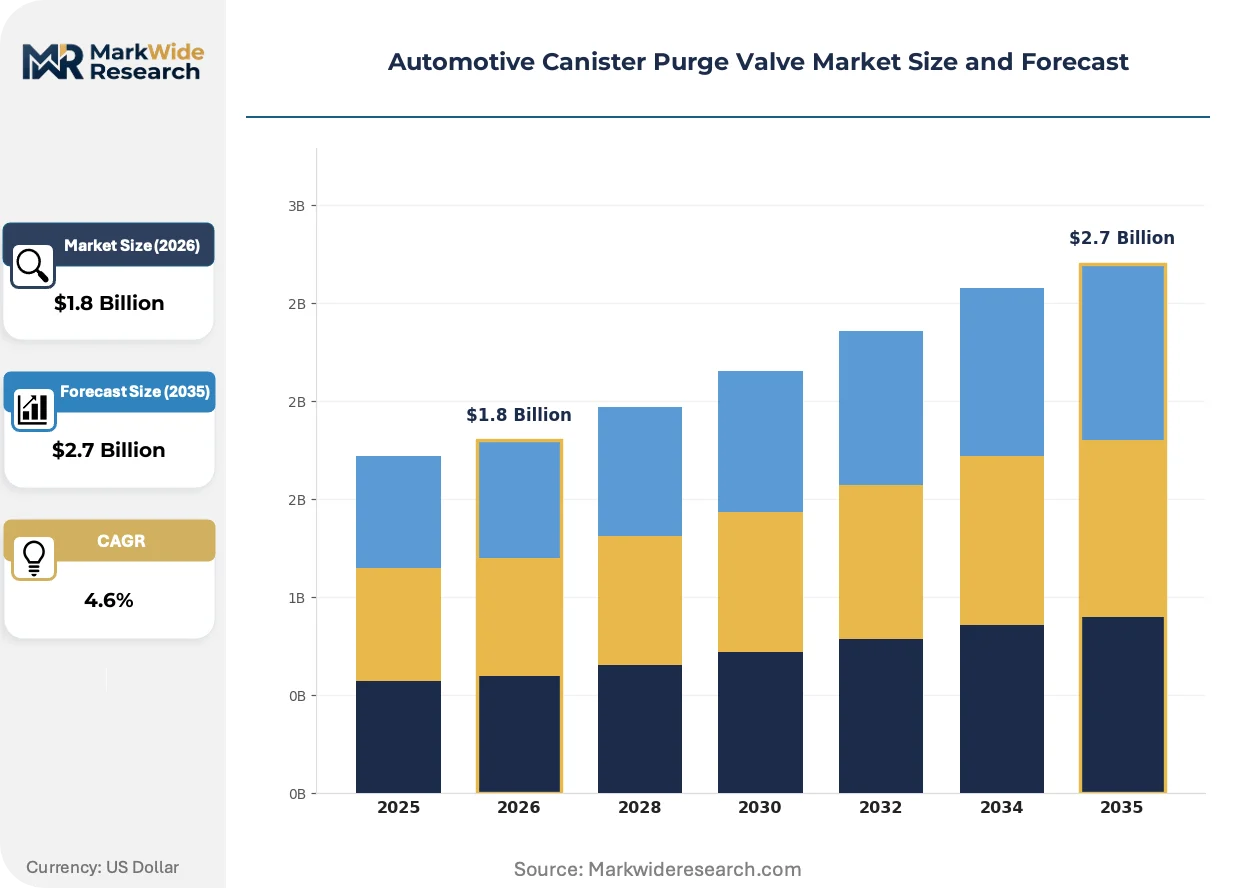
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Solenoid, Vacuum, Others End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Integrated, Standalone, Universal Fit, Custom Fit Fuel Type: Petrol, Diesel, Ethanol, Hybrid |
| Companies Covered | Continental AG, Robert Bosch GmbH, Delphi Technologies, Denso Corporation, Eagle Industry Co., Ltd., TLX Technologies, Dorman Products, Valeo, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Canister Purge Valve Market Evolving Landscape
Valve technology is bifurcating between precision electromagnetic designs for hybrid powertrains and cost-optimized solenoid variants for conventional engines, with material science and control electronics driving differentiation.
Electromagnetic purge valves with integrated position feedback are virtualizing traditional open-loop solenoid architectures by enabling real-time vapor flow modulation. Hybrid powertrain engineers in Germany and Japan are specifying these valves for engine restart sequences where air-fuel ratio precision affects emissions compliance. The technology is virtualizing the hardware-software boundary in emission control modules, compressing the distinction between mechanical actuation and electronic control.
EPA Tier 3 tailpipe and evaporative standards are mandating sub-20-micron leak rates that obsolete conventional seal designs. Valve manufacturers are upgrading to fluorocarbon elastomers and laser-welded housings to meet validation thresholds. United States passenger vehicle programs face the steepest compliance burden, with California Air Resources Board zero-emission mandates adding parallel engineering resource strain.
Fleet procurement centralization is consolidating specification authority at OEM powertrain engineering centers, marginalizing regional sourcing autonomy. Tier-1 suppliers are responding with platform-scale valve families that reduce part number proliferation. This concentration is most visible in Germany and Japan, where captive supplier relationships and JIS-certified production lines dominate hybrid system sourcing.
Automotive Canister Purge Valve Market Segmentation
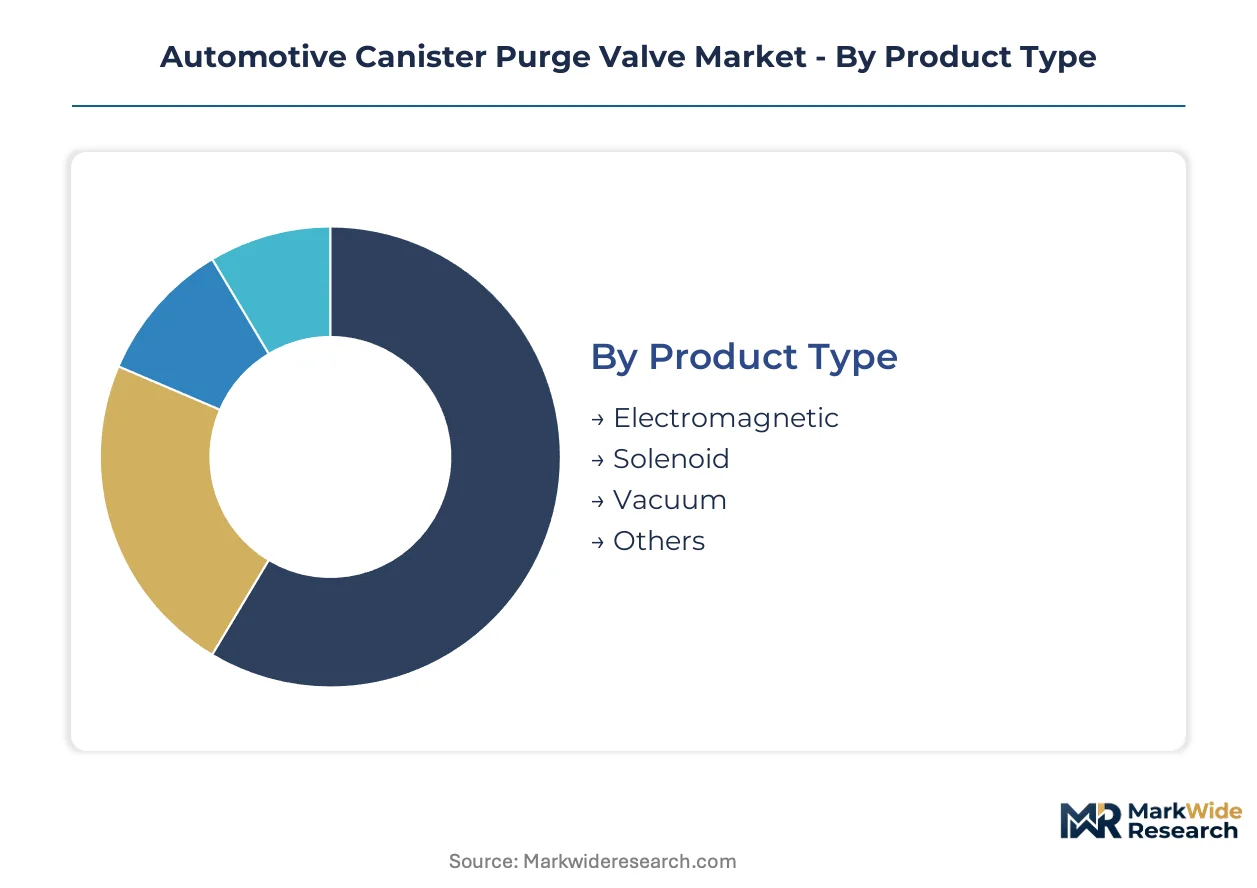
Segmentation in the automotive canister purge valve market reveals how technology specialization, procurement channel structure, and powertrain architecture create distinct competitive arenas. Each dimension carries different margin profiles, validation burdens, and supplier qualification requirements that shape strategic positioning.
Product Type:
Cost tier differentiation separates precision-engineered electromagnetic designs from commodity solenoid architectures serving conventional powertrains.
- Solenoid:Copper-wound coil assemblies with nitrile rubber seals dominate petrol engine applications through proven thermal cycling durability. Procurement concentrates in Germany and Japan where captive production lines serve high-volume OEM programs under JIS certification.
- Electromagnetic:Millisecond-response valve architectures integrate position feedback electronics for hybrid restart sequences. Demand is climbing fastest in Japan and Germany where gasoline-electric powertrains require precise vapor metering during engine-off operation.
- Vacuum:Pressure-actuated mechanical designs persist in cost-sensitive vehicle segments with simplified emission control requirements.
- Others:Pneumatic and thermally activated variants address niche retrofit and specialty vehicle applications.
Solenoid valves command the established base. The steepest expansion runs through electromagnetic designs.
End User:
Customer type determines specification authority, warranty exposure, and channel economics across the value chain.
- OEMs:Passenger vehicle manufacturers hold design control and source valves through multi-year platform contracts. EPA Tier 3 and Euro 7 validation requirements compress supplier selection to Tier-1 partners with integrated sensor-actuator capabilities.
- Tier-1 Suppliers:System integrators specify valve subassemblies for emission control modules bundled with charcoal canisters. Procurement in Germany and the United States favors suppliers with captive solenoid winding and laser-welded housing capabilities.
- Aftermarket Providers:Universal-fit valve distributors compete on price through e-commerce channels outside franchised dealer networks.
- Vehicle Assemblers:Contract manufacturers in emerging markets source valves through kit suppliers without direct Tier-1 relationships.
OEMs command the established base. Tier-1 suppliers are gaining share fastest through system integration mandates.
Installation Type:
Application architecture defines engineering validation scope and service lifecycle economics.
- Custom Fit:Application-specific valve designs with proprietary electrical connectors and mounting geometries lock in OEM-tied revenue streams. Validation cycles for sub-20-micron leak performance under EPA Tier 3 extend development timelines.
- Integrated:Valve-sensor fusion within emission control modules enables predictive diagnostics and service contract bundling. Demand concentrates in Germany and Japan where hybrid powertrain complexity rewards consolidated subsystem sourcing.
- Standalone:Discrete valve units serve legacy vehicle platforms and replacement markets with simplified installation protocols.
- Universal Fit:Standardized port configurations and electrical terminals target price-sensitive aftermarket replacement demand.
Custom fit commands the established base. Integrated designs are expanding most quickly through sensor-actuator convergence.
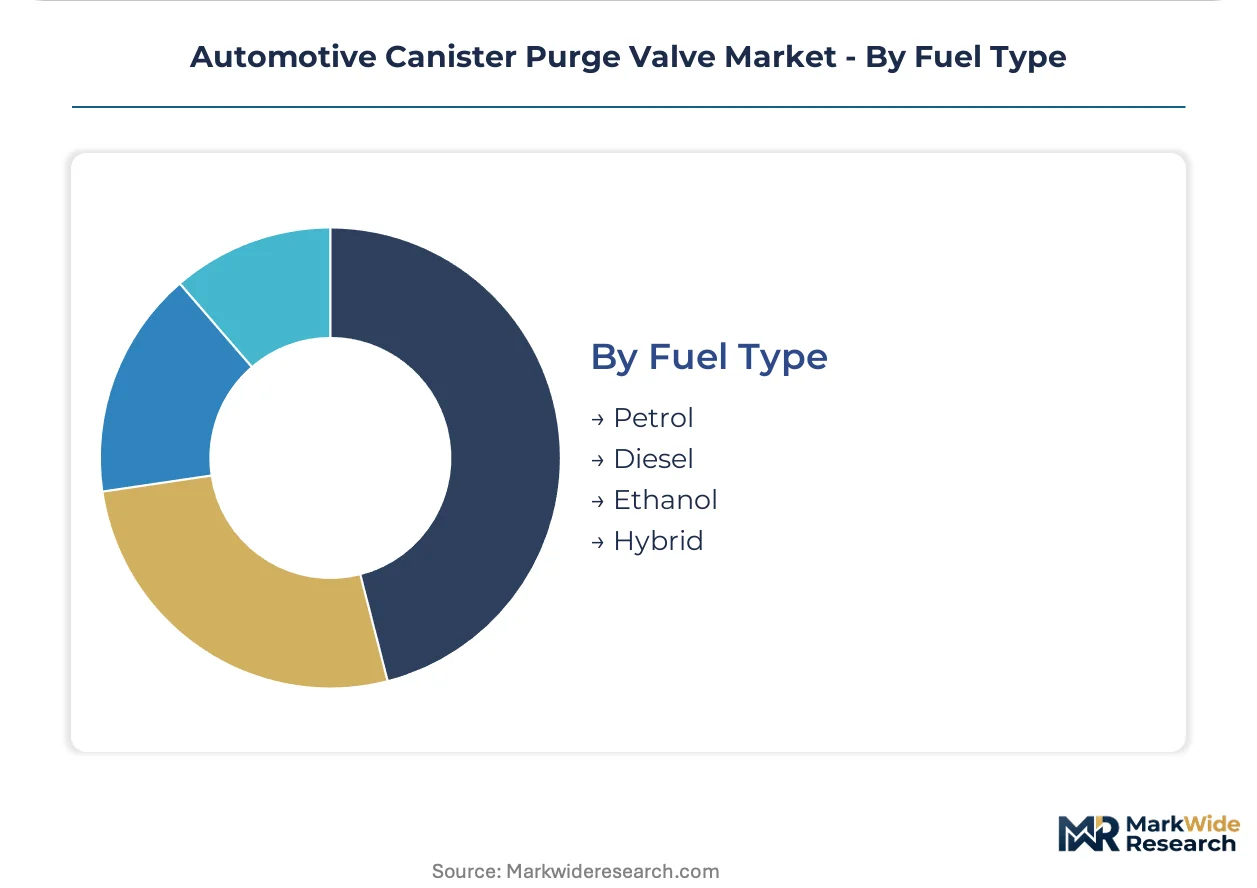
Fuel Type:
Powertrain chemistry dictates seal material specifications, thermal operating ranges, and emission compliance pathways.
- Petrol:Gasoline vapor recovery systems represent the largest installed base with mature solenoid valve technology. United States passenger vehicle production sustains volume concentration despite California Air Resources Board zero-emission mandates.
- Hybrid:Gasoline-electric architectures demand electromagnetic valves with rapid-response capability for engine restart sequences. Procurement in Japan and Germany is accelerating as OEMs expand hybrid model lines under Euro 7 preparation.
- Diesel:Compression-ignition purge systems require enhanced sealing against higher crankcase pressure differentials.
- Ethanol:Flex-fuel compatible valves use fluorocarbon elastomers to resist alcohol-induced seal degradation.
Petrol commands the established base. Hybrid applications are climbing the fastest as powertrain electrification advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hybrid powertrain adoption patterns create stark regional consumption differentials. Japan and Germany prioritize millisecond-precision electromagnetic valves for gasoline-electric restart sequences, while the United States sustains larger solenoid volumes through persistent internal combustion engine production.
United States
Passenger vehicle OEMs in Michigan and Tennessee are expanding procurement of sealed fuel vapor recovery systems under EPA Tier 3 mandates. NHTSA safety recalls for stuck-open purge valves in prior model years have compressed design validation cycles. Detroit-based engineering centers now specify sub-20-micron leak performance as baseline for platform contracts.
Germany
Bavarian and Baden-Württemberg powertrain divisions are integrating sensor-actuator valve platforms into Euro 7-compliant hybrid architectures. KBA type-approval processes for evaporative emission components have extended certification timelines. Stuttgart-area supplier parks concentrate captive solenoid winding and laser-welded housing capabilities.
Japan
Kanto and Chubu region OEMs specify JIS-certified electromagnetic valves for hybrid restart sequences requiring precise vapor metering. METI technology roadmaps prioritize engine-off emission control as gasoline-electric powertrains expand model lines. Nagoya-based Tier-1 suppliers anchor Asia-Pacific supply chains through integrated production.
China
Yangtze River Delta and Pearl River Delta vehicle assemblers are upgrading to GB 18352.6-compliant purge hardware as domestic hybrid production accelerates. MEE enforcement of national evaporative standards is tightening seal material specifications. Shanghai-area procurement offices are qualifying electromagnetic valve suppliers for platform-scale contracts.
India
Maharashtra and Tamil Nadu OEMs are opening procurement windows for advanced purge valves under BS-VI Phase II evaporative norms. Domestic engineering teams lack electromagnetic calibration expertise, creating import dependency for hybrid applications. Pune-based system integrators are validating valve assemblies for cost-optimized passenger vehicle programs.
Automotive Canister Purge Valve Market Competitive Landscape
Capability concentration sits with integrated sensor-actuator specialists; scale advantage sits with captive solenoid producers. The vendor base stratifies across three tiers: electromagnetic precision engineers serving hybrid programs, high-volume solenoid manufacturers with JIS-certified lines, and aftermarket distributors competing on universal-fit price points. Dominant competitive moves include backward integration into copper winding operations and platform-scale valve family consolidation to reduce part number proliferation.
Within the integrated systems tier, Continental AG and Robert Bosch GmbH exemplify archetypes combining sensor technology with valve control electronics. Denso Corporation anchors Asia-Pacific positioning through JIS-certified production. Among aftermarket-focused fabricators, Dorman Products occupies a position serving price-sensitive replacement demand outside franchised dealer networks.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Delphi Technologies |
| Denso Corporation |
| Eagle Industry Co., Ltd. |
| TLX Technologies |
| Dorman Products |
| Valeo |
| Eaton |
| Others |
Value Network & Pricing Analysis
Stuttgart-area supplier parks concentrate captive solenoid winding and laser-welded housing capabilities, compressing margin capture for downstream valve assemblers while concentrating pricing power with integrated Tier-1 producers. OEM platform contracts now demand sub-20-micron leak performance as baseline qualification, forcing material specification upgrades that transmit cost pressure through the value chain.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, with multi-year platform agreements locking in volume commitments against JIS-certified production lines. Price differentiation rests on certification grade and electromagnetic calibration capability, with hybrid-qualified suppliers commanding premium positioning over commodity solenoid vendors. Cost compression in the universal-fit aftermarket is intensifying because e-commerce platforms aggregate price-transparent replacement demand. Tier-1 system integrators exhibit lowest price sensitivity due to bundled sensor-actuator sourcing mandates, while aftermarket distributors face acute margin pressure from cross-border universal-fit imports.
Supply Chain Analysis
Petrochemical feedstock clusters in Thailand and Malaysia anchor nitrile rubber seal production, creating geographic concentration risk for valve manufacturers dependent on Southeast Asian elastomer supply. Copper winding specifications draw from German and Mexican captive production lines, while electromagnetic position sensors hinge on Japanese semiconductor packaging capacity. Single-source vulnerability runs through fluorocarbon elastomer qualification timelines under EPA Tier 3 validation protocols. Distribution runs through OEM platform engineering centers in Michigan, Bavaria, and Aichi Prefecture, with aftermarket channels fragmenting across regional e-commerce aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract bundling for predictive diagnostic capabilities is expanding faster than hardware procurement as OEMs monetize sensor-actuator convergence through recurring revenue streams. Valve-sensor fusion platforms enable remote monitoring subscriptions that outpace discrete valve replacement cycles.
For Market Incumbents: Build captive calibration expertise moats by acquiring electromagnetic engineering talent pools in Japan and Germany before hybrid platform sourcing decisions finalize. Consolidate backward integration into copper winding operations to defend margin position against raw material volatility. Battery electric substitution threatens addressable volume; accelerate sensor-actuator platform development to capture thermal management module opportunities alongside legacy purge systems. For New Entrants and Emerging Players: Pursue electromagnetic valve qualification for India BS-VI Phase II procurement windows where domestic OEMs lack in-house calibration capability. Target Maharashtra and Tamil Nadu vehicle assemblers seeking cost-optimized hybrid-compatible hardware without Tier-1 dependency. Anchor go-to-market strategy through Pune-based system integrators requiring validation support for platform-scale contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated sensor-actuator specialists with JIS-certified production lines and OEM platform lock-in across multiple hybrid programs. Long-term viability hinges on diversification into battery thermal management actuation as internal combustion volumes plateau. Watch California Air Resources Board zero-emission vehicle mandate acceleration as inflection indicator for internal combustion purge system investment horizons.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces part number proliferation for Tier-1 suppliers serving multi-OEM hybrid programs under Euro 7. |
| Backward Integration into Copper Winding | Secures conductive material supply for solenoid durability targets under thermal cycling stress. |
| Sensor-Actuator Convergence | Enables predictive diagnostic subscriptions that monetize valve position feedback data. |
| Geographic Manufacturing Footprint | Positions production near Stuttgart and Nagoya OEM engineering centers for platform contract access. |
| Electromagnetic Calibration Investment | Addresses engineer shortage constraining supplier scaling for millisecond-response hybrid applications. |
Research Methodology
Desk research of EPA certification filings, KBA type-approval databases, and METI technology roadmaps preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and electromagnetic calibration specialists. Secondary validation drew from vehicle production databases, customs trade records for copper winding and elastomer imports, and IHS Markit registration data across the analysis window. Bottom-up valve shipment estimates triangulated against top-down emission control module production figures.
Assumptions around EPA Tier 3 enforcement timelines, Euro 7 EMA review completion, and hybrid powertrain penetration rates were held fixed across baseline scenarios while battery electric substitution velocity and nitrile rubber feedstock pricing were stress-tested. Segmentation modeling incorporated product type, end-user procurement channel, installation architecture, and fuel type propulsion system. CAGRs were derived from production volume trajectories weighted by content-per-vehicle assumptions and regional regulatory compliance phase-in schedules. Forecast inputs included OEM platform lifecycle data and Tier-1 supplier capacity expansion announcements.
Sensitivities concentrate around California Air Resources Board zero-emission mandate acceleration, Southeast Asian petrochemical supply disruption, and electromagnetic engineer availability constraints in India. Forecasts reflect assumptions documented in regulatory compliance timelines and OEM powertrain roadmaps. Cross-checking against vehicle production forecasts from established automotive industry data providers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Global Bearing Isolators Market