
 Automotive Speedometer Market | 2026-2036
Automotive Speedometer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Speedometer Market Analysis
Fleet procurement by electric vehicle manufacturers is expanding as battery-electric platforms require integrated digital cockpit solutions. Continental AG leverages its display integration capabilities to sustain long-term supply agreements with European OEMs. Denso Corporation anchors its position in Asian markets through manufacturing scale in instrument cluster modules. Robert Bosch GmbH competes on electronic architecture expertise across hybrid and fully digital speedometer systems.
An automotive speedometer measures and displays vehicle velocity, typically employing stepper motors, Hall-effect sensors, or GPS triangulation to achieve accuracy within specified tolerances; its primary purpose is to provide real-time speed information to operators for regulatory compliance and operational safety. Digital speedometers now lead product type demand as automakers phase out mechanical gauges, while electronic technology segments capture the fastest growth due to sensor fusion with advanced driver-assistance systems. OEM end users concentrate the largest volume share, though aftermarket providers occupy a resilient niche in vehicle refurbishment and customization segments.
NHTSA enforces Federal Motor Vehicle Safety Standard 101 in the United States, mandating speedometer legibility and accuracy thresholds that shape product design requirements for market access. ECE Regulation 39 governs European type approval for speed measurement devices, while Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains parallel certification protocols through METI-coordinated standards. Stakeholders must monitor evolving harmonization between regional electromagnetic compatibility standards and cybersecurity frameworks for connected instrument clusters.
Market Dynamics
The automotive speedometer market pivots on the forced obsolescence of mechanical gauges as automakers standardize fully digital instrument clusters to satisfy connected-vehicle architectures and regulatory visibility mandates.
Growth Catalysts
- Battery-electric vehicle platforms:EV architectures eliminate mechanical drivetrain interfaces, mandating electronic speed measurement systems integrated with central cockpit controllers.
- NHTSA FMVSS 101:US legibility and accuracy standards compel OEMs to upgrade display technologies to maintain market access and avoid certification delays.
- Hall-effect sensor fusion:Integration with advanced driver-assistance systems creates bundled demand for multi-function instrument clusters.
Market Restraints
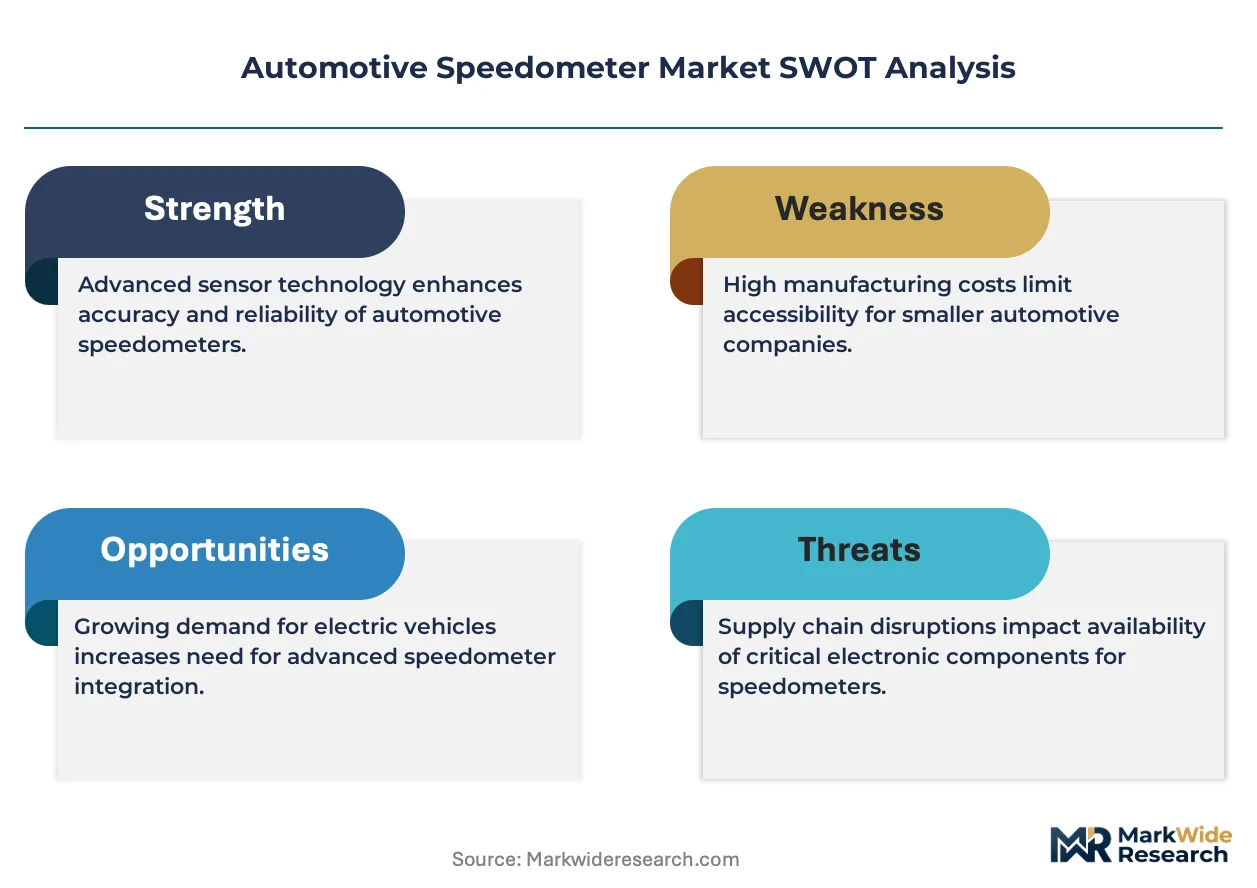
- Semiconductor input volatility:Display driver ICs and microcontrollers face concentrated fabrication in Taiwan, exposing supply continuity to geopolitical friction.
- Technical limitation of GPS-only systems:Signal degradation in urban canyons and tunnels prevents standalone GPS speedometers from achieving regulatory accuracy tolerances.
- Substitution by head-up displays:Windshield-projected speed information reduces perceived necessity of dedicated instrument cluster hardware in premium segments.
Strategic Opportunities
- India automotive market:Domestic OEMs and joint ventures accelerate localization of digital cockpit production under PLI scheme incentives for electronics manufacturing.
- Cybersecurity certification tailwinds:UNECE R155 mandates for connected vehicle security create premium pricing for speedometer systems with embedded hardware security modules.
- Aftermarket refurbishment channels:Classic vehicle digitization projects in Germany and Japan drive demand for retrofit electronic speedometer kits.
Industry Challenges
- Embedded software talent scarcity:Functional safety certification to ISO 26262 ASIL-B requires specialized firmware engineers, constraining development timelines.
- Legacy vehicle integration complexity:Analog signal emulation for older vehicle networks demands additional engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Speedometer Market |
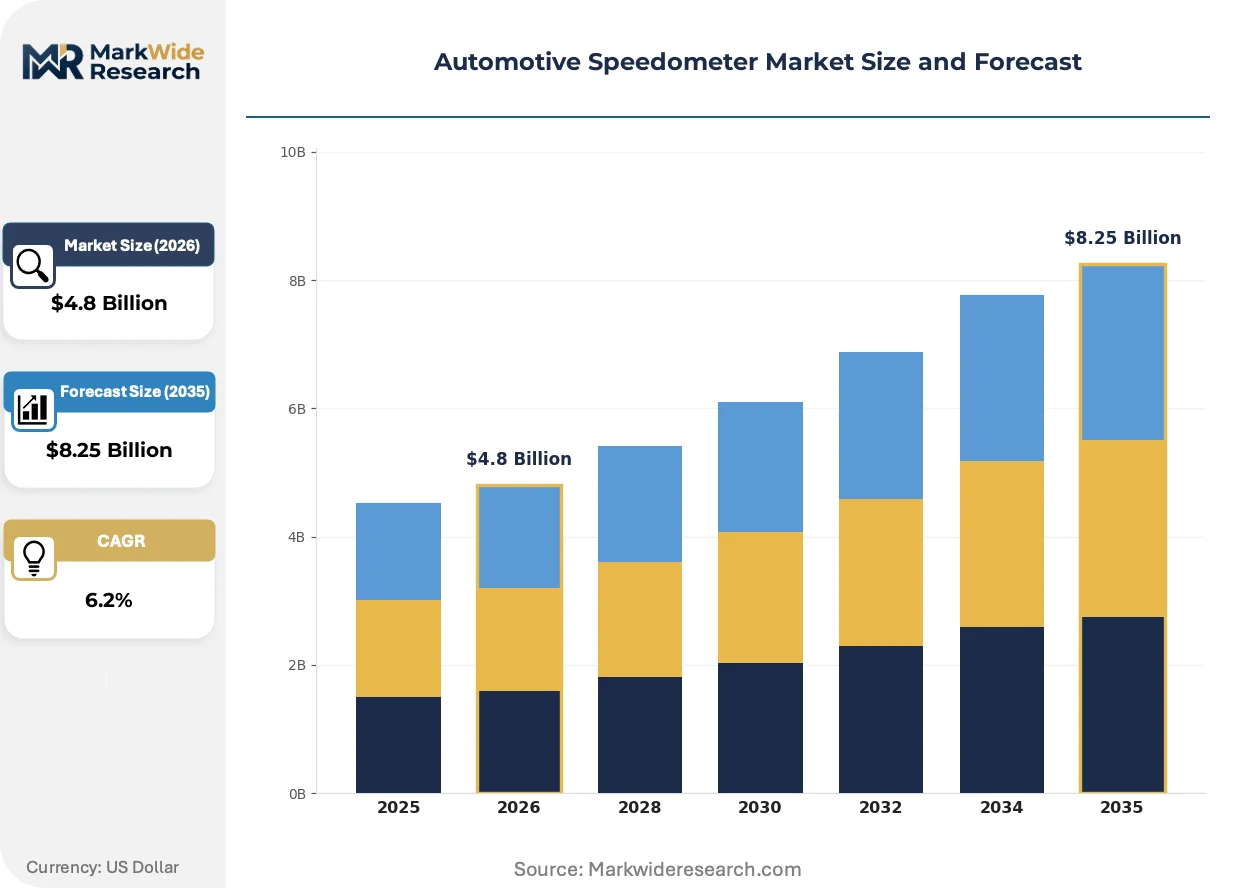
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Speedometers, Digital Speedometers, GPS Speedometers, Heads-Up Display Speedometers Technology: Mechanical, Electronic, Hybrid, Wireless End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Feature: Speed Warning System, Over Speed Alert, Integration with Navigation, RPM Display |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, Visteon Corporation, Nippon Seiki Co., Ltd., Yazaki Corporation, Pricol Limited, Varroc Group, Marelli Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Speedometer Market Emerging Trajectories
Speedometer architecture is consolidating around software-defined displays that render multiple vehicle parameters through reconfigurable graphics layers rather than fixed physical gauges.
MicroLED display technology is unifying instrument cluster and center-stack screen production through shared backplane architectures. Tier-1 suppliers adopt this technology to reduce BOM complexity across multiple OEM programs. The convergence is unifying procurement categories previously segmented by display size and resolution.
ECE Regulation 79 revision mandates specific color-coding and symbol standardization for speed-related warnings across European type approvals. This regulatory pressure forces redesign of graphical user interfaces to achieve cross-border certification efficiency. Asian OEMs exporting to Europe accelerate compliance investments.
Fleet operators now specify speedometer data logging as a contractual requirement for driver behavior monitoring and insurance liability reduction. Commercial vehicle procurement contracts embed this telemetry functionality as standard equipment. This specification pattern concentrates most visibly in German logistics and last-mile delivery vehicle segments.
Automotive Speedometer Market Segmentation
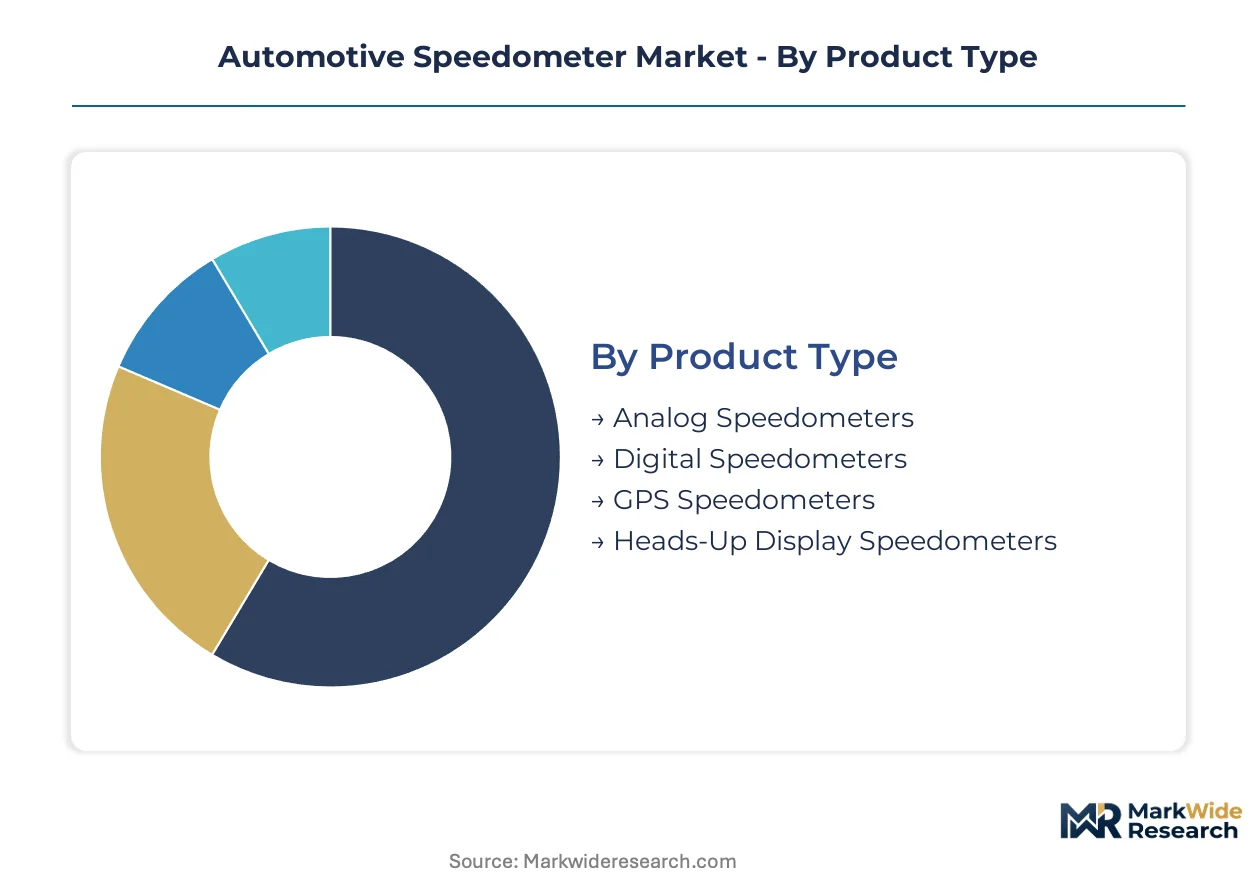
Speedometer procurement patterns diverge sharply across product architectures, sensing technologies, and supply chain tiers. OEM specification sheets now prioritize software-configurable displays over fixed hardware formats, reshaping how suppliers categorize their portfolio offerings.
Product Type:
Display architecture determines integration complexity with vehicle network electronics and central cockpit controllers.
- Digital Speedometers:Liquid-crystal or OLED panels render speed data through reconfigurable graphics layers, eliminating physical gauge mechanisms. Battery-electric vehicle platforms in Germany and Japan specify these exclusively for their streamlined dashboard designs.
- Analog Speedometers:Stepper motor-driven needle displays persist in cost-sensitive vehicle segments and classic car refurbishment projects. Demand concentrates with aftermarket providers serving heritage vehicle owners in Stuttgart and Nagoya restoration clusters.
- GPS Speedometers:Satellite triangulation calculates velocity independent of wheel speed sensors, simplifying installation in custom builds. Signal reliability limitations restrict regulatory approval to auxiliary display roles.
- Heads-Up Display Speedometers:Windshield projection systems overlay speed data within driver line-of-sight. Premium German OEMs embed these in luxury sedan configurations to reduce instrument cluster glance time.
Mature deployment sits with Analog Speedometers. Newer deployment is concentrated in Digital Speedometers.
Technology:
Sensing methodology dictates calibration requirements, electromagnetic compatibility testing scope, and functional safety certification pathways.
- Electronic:Hall-effect sensors and magnetoresistive elements generate pulse signals processed by dedicated microcontrollers. ECE Regulation 39 type approvals favor this architecture for its accuracy stability across temperature ranges.
- Mechanical:Rotating cable drives from transmission outputs spin magnetic cups against spring-restrained drums. Production volumes contract as NHTSA FMVSS 101 visibility standards obsolete purely mechanical legibility.
- Hybrid:Mechanical sensing pairs with electronic display rendering, bridging legacy vehicle electrical architectures. Tier-1 suppliers in Japan maintain limited production for specific OEM transition programs.
- Wireless:Bluetooth Low Energy or dedicated short-range communication links transmit speed data to detachable displays. Aftermarket applications in India exploit this flexibility for two-wheeler retrofit markets.
Electronic technology is climbing the fastest as ADAS integration mandates standardized digital signal outputs.
End User:
Procurement authority and volume concentration vary dramatically across the automotive supply pyramid.
- OEMs:Vehicle manufacturers specify speedometer performance requirements and validate supplier designs through production part approval processes. German OEMs consolidate digital cockpit procurement under single-source agreements with display integrators.
- Tier-1 Suppliers:Instrument cluster module specialists manage subsystem development for multiple OEM programs simultaneously. Denso Corporation and Robert Bosch GmbH anchor this tier through manufacturing scale and electronic architecture expertise.
- Aftermarket Providers:Independent distributors serve vehicle refurbishment, customization, and repair demand outside factory warranty channels. Classic vehicle digitization projects in Germany and Japan drive specialized kit procurement.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities execute final integration of supplied instrument clusters. India's PLI scheme incentives attract localization investments from this segment.
Volume leadership resides with OEMs. Margin expansion concentrates with Aftermarket Providers.
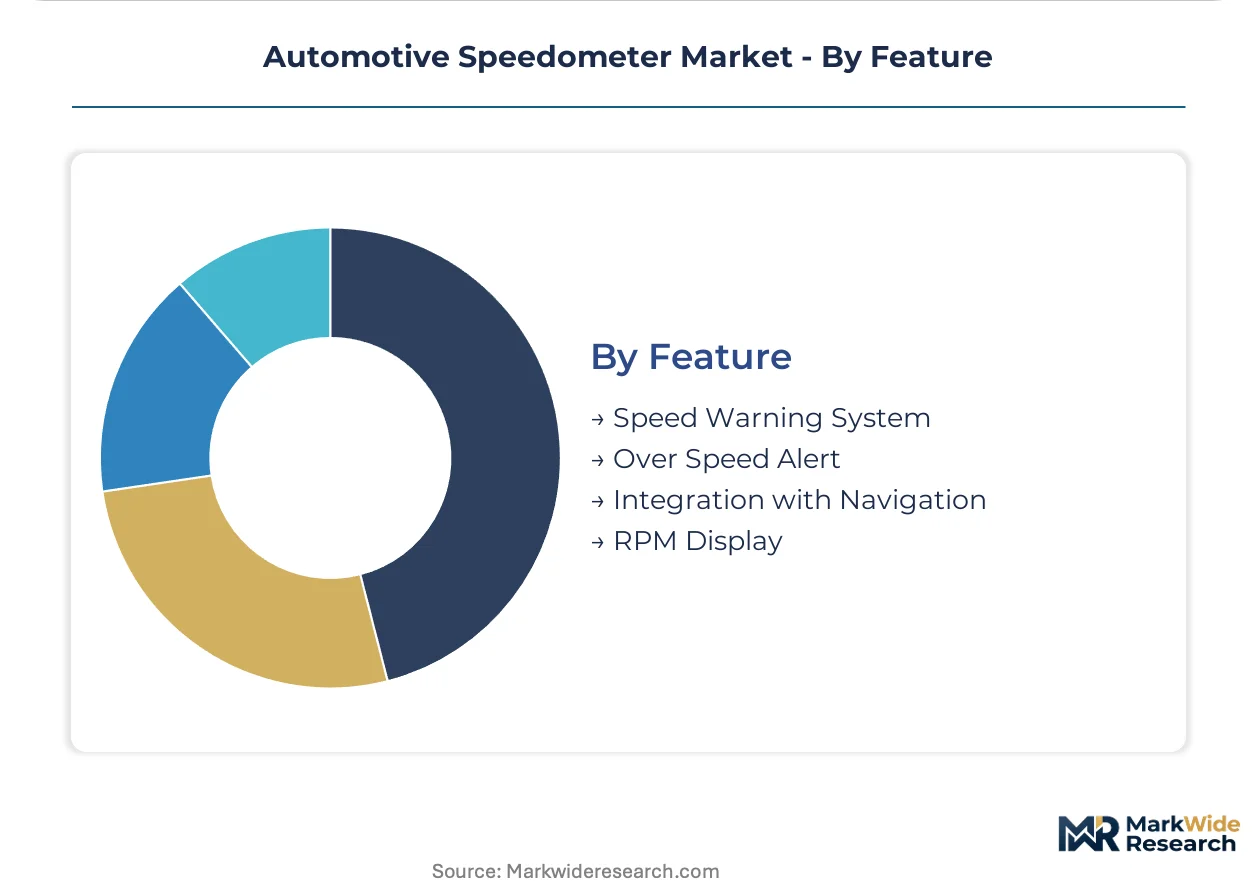
Feature:
Functional augmentation transforms speedometers from passive displays into active safety system nodes.
- Speed Warning System:Configurable threshold alerts trigger audible or haptic feedback when limits are approached. Fleet operators in German logistics segments specify this for driver behavior monitoring and insurance liability reduction.
- Integration with Navigation:Real-time speed limit database correlation enables dynamic advisory displays. ECE Regulation 79 revision mandates standardized color-coding for these warnings across European type approvals.
- Over Speed Alert:Hard-coded regulatory limit enforcement prevents vehicle operation beyond jurisdiction-specific maximums. Commercial vehicle procurement contracts embed this telemetry functionality as standard equipment.
- RPM Display:Engine speed indication supports manual transmission operation and powertrain diagnostics. Hybrid vehicle platforms integrate this with electric motor status readouts.
Basic RPM Display functions are standardizing across all segments. Integration with Navigation is gaining share fastest as connected vehicle architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement concentrates the highest volume of digital speedometer demand, while Chinese electric vehicle production and Japanese tier-1 manufacturing anchor supply-side capacity across distinct technology tiers.
United States
NHTSA FMVSS 101 legibility mandates compel Detroit automakers to upgrade display technologies for domestic market access. Michigan-based instrument cluster engineering centers validate supplier designs through production part approval processes. Fleet procurement by commercial vehicle operators in the Midwest embeds speedometer data logging for driver behavior monitoring.
Germany
Continental AG and Robert Bosch GmbH anchor European production of integrated digital cockpit systems for premium OEM programs. ECE Regulation 39 type approval requirements shape accuracy and visibility standards across export-bound vehicle platforms. Stuttgart restoration clusters sustain aftermarket demand for classic vehicle digitization kits.
Japan
Denso Corporation and Nippon Seiki Co., Ltd. manufacture instrument cluster modules at scale for Asian OEM supply chains. METI-coordinated certification protocols through the Ministry of Land, Infrastructure, Transport and Tourism maintain parallel standards to European and US regulations. Nagoya precision manufacturing clusters specialize in Hall-effect sensor integration for hybrid vehicle transition programs.
China
Domestic battery-electric vehicle platforms eliminate mechanical drivetrain interfaces, mandating fully electronic speed measurement architectures. MIIT-administered GB standards govern electromagnetic compatibility testing scope for connected instrument clusters. Yangtze River Delta display panel fabrication supplies backplane components for regional cockpit integrators.
India
Domestic OEMs and joint ventures accelerate localization of digital cockpit production under PLI scheme incentives for electronics manufacturing. BIS certification requirements align with UNECE technical standards for vehicles targeting export markets. Tamil Nadu vehicle assembly corridors attract tier-1 supplier investments for instrument cluster module integration.
Automotive Speedometer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined display architectures and cybersecurity-certified modules. The supplier base consolidates around display integration specialists with captive electronic architecture expertise. Three archetypes dominate: tier-1 system integrators managing multi-OEM programs, component specialists focusing on sensor and display technologies, and aftermarket providers serving refurbishment channels. Competitive positioning sharpens through strategic partnerships for microLED backplane sourcing and in-house production of display driver ICs to defend margin position against semiconductor input volatility.
Among German-based fabricators, Continental AG and Robert Bosch GmbH exemplify the tier-1 system integrator archetype through their positions in European OEM supply chains. Denso Corporation represents the scale-driven manufacturing model anchoring Asian market supply. These three entities sit within distinct competitive vectors—display integration, electronic architecture, and manufacturing scale—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Visteon Corporation |
| Nippon Seiki Co., Ltd. |
| Yazaki Corporation |
| Pricol Limited |
| Varroc Group |
| Marelli Holdings Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Fleet procurement contracts mandating embedded data logging and cybersecurity certification are forcing tier-1 suppliers to absorb premium component costs while defending long-term pricing agreements with German and Japanese OEMs.
Pricing Analysis
Volume leadership concentrates with OEM single-source agreements at compressed margins, while aftermarket refurbishment kits for classic vehicle digitization command premium pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates by ASIL-B functional safety certification and display resolution tier. Pricing pressure stems from semiconductor input volatility concentrated in Taiwan fabrication facilities. Aftermarket providers exhibit highest price sensitivity due to fragmented demand and import duty exposure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Continental AG and Robert Bosch GmbH, while aftermarket distributors serve refurbishment clusters in Stuttgart and Nagoya. Manufacturing concentration centers on Germany, Japan, and China for instrument cluster module assembly. Display driver ICs, microcontrollers, and microLED backplanes draw from Taiwan, South Korea, and Yangtze River Delta suppliers. Single-source vulnerability in semiconductor fabrication exposes continuity risks. Distribution runs through tier-1 integrators managing multi-OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for automotive-grade microcontrollers are propping pricing power for suppliers with captive inventory agreements and long-term offtake contracts.
For Market Incumbents: To counter head-up display substitution in premium vehicle segments, tier-1 suppliers should deepen software-defined display expertise and secure exclusive microLED backplane sourcing partnerships. Backward integration into display driver IC design defends margin position against foundry concentration risk. For New Entrants and Emerging Players: Aftermarket providers serving India's two-wheeler retrofit market represent the most penetrable buyer archetype with minimal incumbent saturation. Wireless Bluetooth Low Energy speedometer kits for custom builds offer a specialized go-to-market angle with lower certification barriers. For Investors and Strategic Acquirers: The window for entry favors tier-2 instrument cluster specialists with embedded cybersecurity certification capabilities and established UNECE R155 compliance pathways. Long-term viability hinges on software-defined vehicle architecture alignment. Watch for MIIT-administered GB standard revisions as inflection indicators for China export market access.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces BOM complexity across multiple OEM programs sharing microLED backplane architectures. |
| Software-Defined Vehicle Investment | Enables reconfigurable graphics layers replacing fixed physical gauge mechanisms. |
| Geographic Manufacturing Footprint | Tamil Nadu assembly corridors under India's PLI scheme localize production for cost-sensitive segments. |
| Cybersecurity Certification Pathway | UNECE R155 compliance creates premium pricing for hardware security module-embedded systems. |
| Aftermarket Channel Expansion | Classic vehicle digitization projects in Germany and Japan sustain resilient refurbishment demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews covering OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership operations managers. NHTSA FMVSS 101 documentation, ECE Regulation 39 type approval databases, and vehicle production statistics supplied validation benchmarks. Bottom-up segment sizing triangulated against top-down market estimates.
Granularity-level modeling captured product type, sensing technology, end-user tier, and functional feature dimensions across the projection horizon. Vehicle class and propulsion architecture splits informed content-per-vehicle assumptions. CAGRs derived from regression analysis of historical adoption curves and technology transition timelines. Semiconductor supply constraints and regulatory harmonization schedules fed scenario-weighted outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UNECE cybersecurity mandate enforcement timing and Taiwan foundry capacity allocation shifts. Forecasts reflect documented assumptions on EV platform adoption and display technology transition rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market