
 North America Rockfall Radar Market | 2026-2036
North America Rockfall Radar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rockfall Radar Market Insights
The capability gap between integrated radar manufacturers and component assemblers is collapsing as real-time processing modules become commoditized. IDS GeoRadar leverages its proprietary interferometric software to sustain premium positioning in fixed installations across Canadian rail corridors. GroundProbe competes through its specialized slope-monitoring services, while Trimble Inc. anchors its presence via GNSS-integrated deformation tracking platforms that extend its civil construction footprint.
North America rockfall radar encompasses ground-based remote sensing systems that detect millimetric rock-surface displacement using microwave interferometry, typically operating in the X-band or Ku-band frequency ranges with detection thresholds below one millimeter. These systems serve primarily to provide early warning of catastrophic slope failures along transportation corridors, open-pit mine walls, and hydroelectric facility abutments. Fixed systems dominate installed base revenue owing to their permanent power and telemetry integration, though portable systems represent the fastest-expanding category as emergency response agencies deploy rapid-deployment kits following extreme weather events. Real-time monitoring technology commands the highest margin pool because subscription-based alerting services generate recurring revenue streams that software-integrated hardware vendors increasingly capture.
FERC mandates on dam safety instrumentation and MSHA guidelines for highwall stability directly shape procurement specifications, compelling mining operators to specify certified continuous-monitoring architectures rather than periodic manual survey regimes. Transport Canada and the US Federal Highway Administration jointly influence roadside deployment standards through geohazard risk assessment protocols that favor automated detection over visual inspection cycles. Stakeholders must weigh capital deployment between proprietary sensor networks and interoperable multi-vendor platforms as procurement criteria harden around open data standards and cross-border equipment compatibility.
Market Dynamics
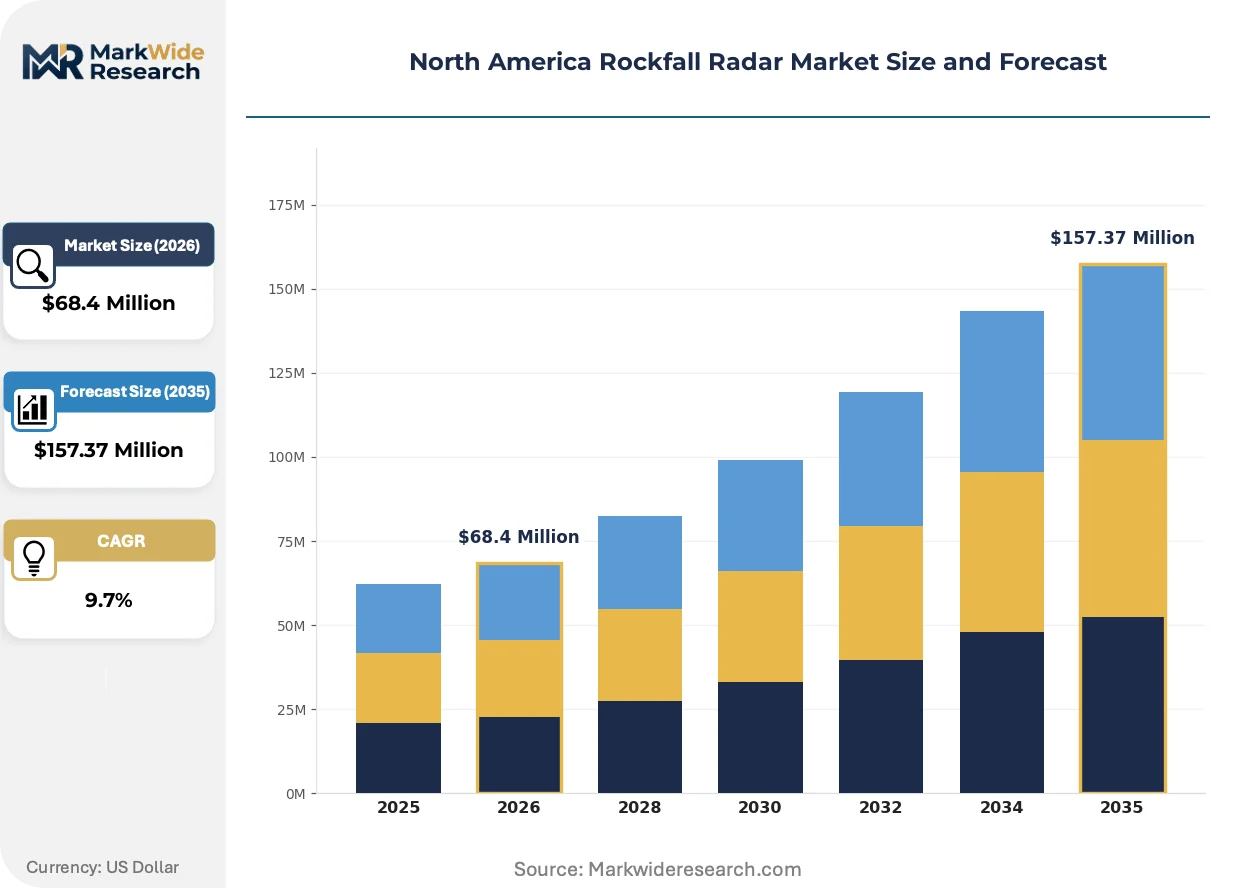
Real-time interferometric processing is collapsing the performance gap between premium integrated systems and modular assemblers, forcing vendors to compete through software-defined alerting services rather than hardware differentiation alone. FERC dam safety mandates and MSHA highwall stability guidelines are hardening procurement specifications toward certified continuous-monitoring architectures across the southwestern United States and Canadian mining corridors.
Growth Catalysts
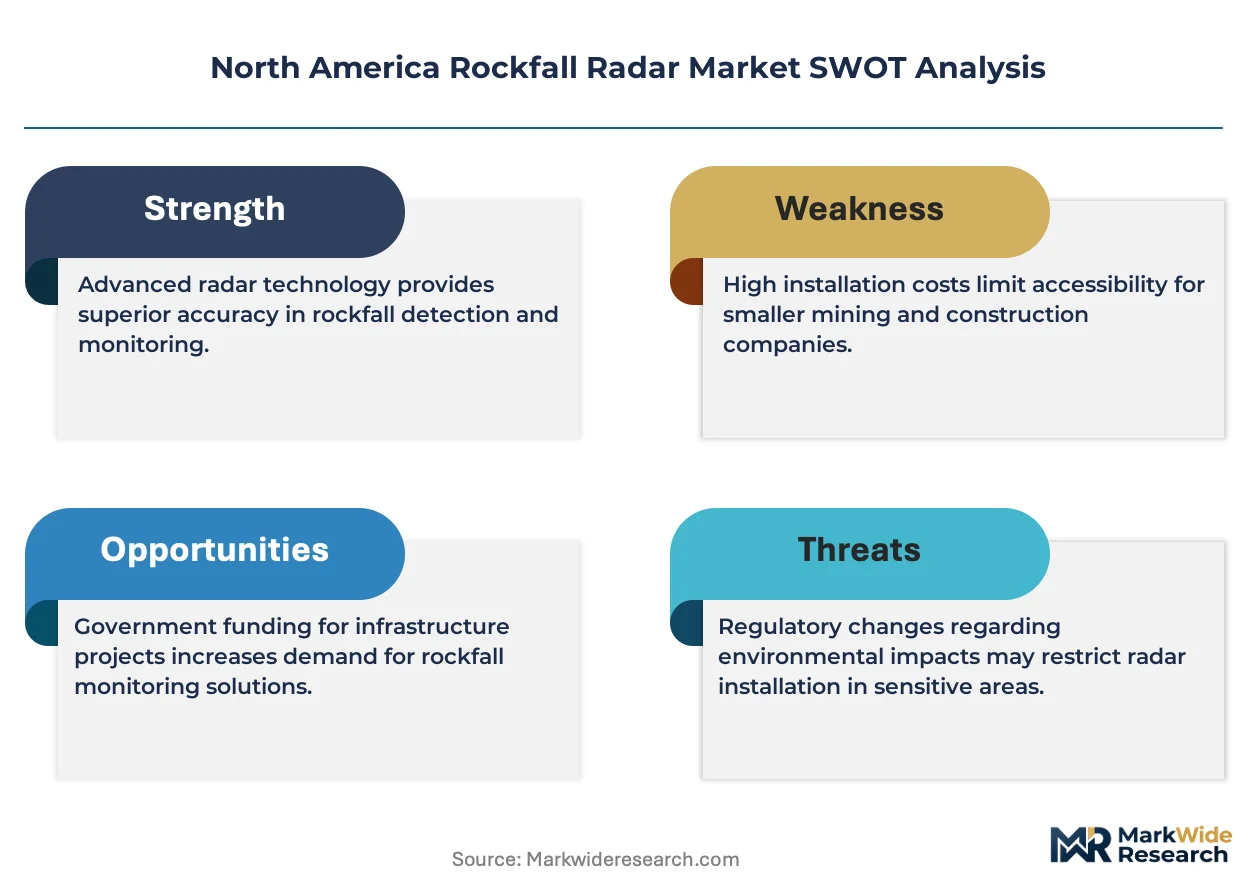
- FERC Instrumentation Mandates:Federal Energy Regulatory Commission requirements for dam safety instrumentation compel hydroelectric operators to deploy certified continuous-monitoring radar systems at facility abutments, displacing periodic manual survey regimes.
- Extreme Weather Response Protocols:Emergency management agencies in California and Colorado are stockpiling rapid-deployment portable radar kits for post-wildfire and post-flood slope stability assessment along transportation corridors.
- Open-Pit Mining Expansion:Copper and aggregate operations in Arizona and Nevada are scaling slope-monitoring coverage as pit wall heights exceed 400 meters, triggering MSHA scrutiny of highwall stability programs.
Market Restraints
- Specialized Component Supply Concentration:X-band and Ku-band microwave transceiver modules rely on a limited supplier base concentrated in defense-aerospace supply chains, creating procurement bottlenecks for commercial radar manufacturers.
- Capital Intensity of Fixed Installations:Permanent power and telemetry integration for fixed radar systems requires substantial upfront civil works, compressing adoption among smaller mining operators and municipal transportation departments.
- Intermittent Survey Substitution:Terrestrial laser scanning and UAV photogrammetry retain cost advantages for low-frequency monitoring applications, limiting radar penetration in budget-constrained geotechnical programs.
Strategic Opportunities
- GNSS-Radar Sensor Fusion:Integration of interferometric radar with Trimble and Leica GNSS deformation networks creates unified displacement monitoring platforms that capture both rapid surface motion and slow-creep accumulation.
- Subscription Alerting Services:Software-integrated vendors are capturing recurring revenue through cloud-based threshold alerting, shifting value capture from hardware margins to operational continuity guarantees.
- Mexican Mining Corridor Penetration:Sonora and Zacatecas states host expanding open-pit copper and silver operations with nascent slope-monitoring infrastructure and limited domestic radar supplier presence.
Industry Challenges
- Interferometric Signal Processing Expertise:Vendors face acute shortages of geophysicists and radar engineers capable of configuring atmospheric correction algorithms and phase-unwrapping parameters for complex terrain geometries.
- Legacy SCADA Integration Friction:Mining operators demand seamless data handoff between radar systems and existing supervisory control architectures, requiring custom protocol bridging that extends deployment timelines.
- Cross-Border Equipment Certification:Divergent FCC and Industry Canada radio frequency licensing procedures complicate unified procurement for operators with assets spanning the US-Canada frontier.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rockfall Radar Market |
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $157.37 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Systems, Hybrid Systems, Monitoring Accessories Technology: Ground Penetrating Radar, Laser Scanning, Inclinometers, Real-Time Monitoring End User: Government Agencies, Mining Operations, Construction Firms, Environmental Consultants Application: Landslide Monitoring, Infrastructure Protection, Research Studies, Risk Assessment |
| Companies Covered | IDS GeoRadar, RST Instruments Ltd, Slope Indicator, GeoSIG Ltd, Trimble Inc., Geobrugg AG, GroundProbe, Hexagon AB, Campbell Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rockfall Radar Market Trends and Innovations
Microwave interferometry is fragmenting into distinct performance tiers as software-defined processing erodes traditional hardware moats. Vendors now compete through alerting latency and false-positive suppression rather than raw detection sensitivity.
Synthetic aperture radar processing is bifurcating the installed base between research-grade systems requiring specialist interpretation and turnkey platforms with automated displacement thresholding. Mid-tier mining operators are adopting the latter en masse, compressing margins for service-intensive deployment models while expanding addressable market volume. This democratization is displacing periodic survey contracts with continuous subscription relationships.
Transport Canada and the US Federal Highway Administration are jointly advancing geohazard risk assessment protocols that favor automated detection over visual inspection cycles. These standards are cascading into state-level procurement specifications, particularly along Interstate corridor segments through topographically unstable terrain. Western state departments of transportation are responding with multi-year roadside radar deployment programs.
Buyer contracting is consolidating around performance-based service agreements that tie vendor compensation to slope failure warning efficacy rather than equipment uptime. Mining procurement departments are displacing capital purchase models with operational expenditure frameworks that transfer detection liability to equipment suppliers. This shift is most pronounced among Nevada and Arizona operators subject to MSHA highwall stability enforcement actions.
North America Rockfall Radar Market Segmentation
Rockfall radar procurement patterns diverge sharply across deployment contexts, with permanent installations commanding premium pricing while portable units expand emergency response coverage. Technology selection hinges on regulatory compliance mandates and slope geometry complexity rather than cost optimization alone.
Product Type:
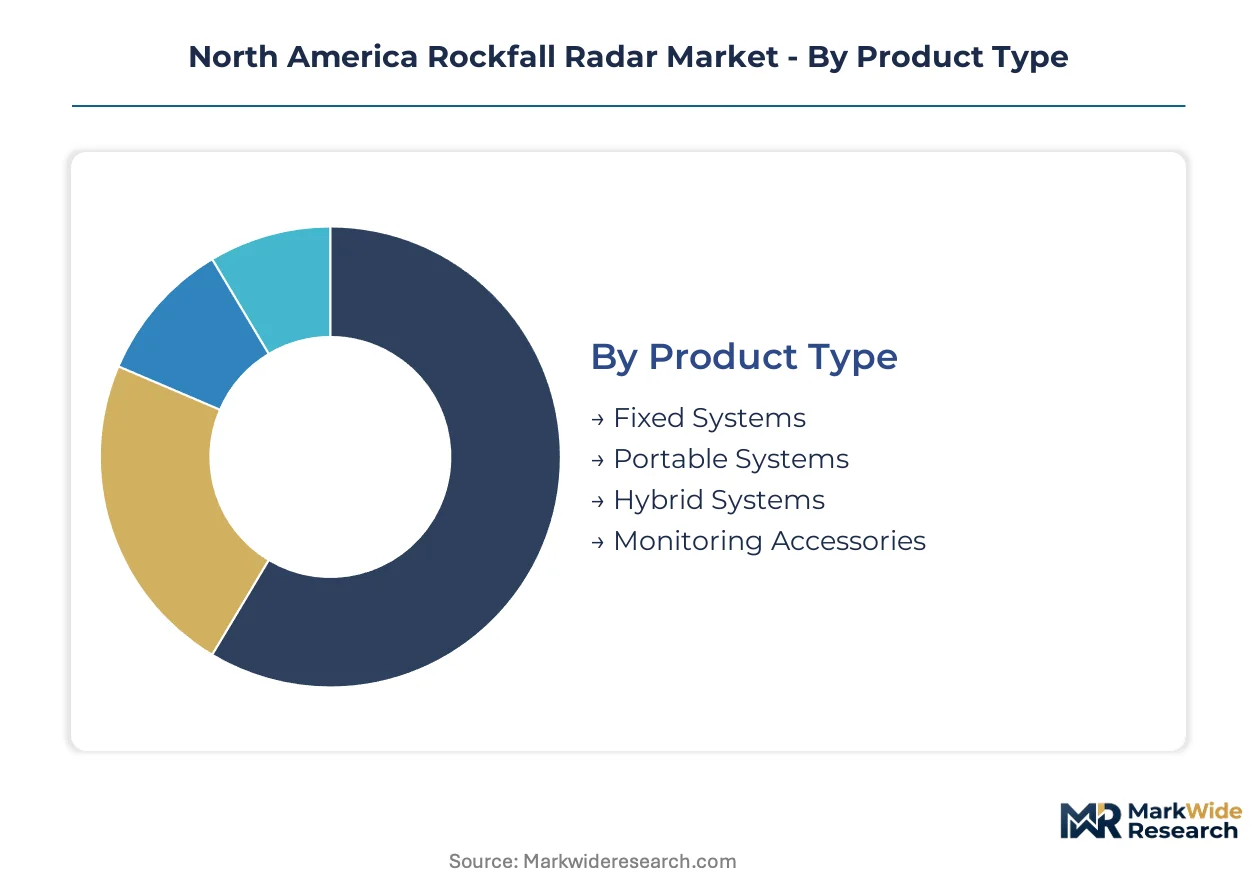
Margin pools concentrate in fixed installations where civil works integration and telemetry infrastructure create recurring service revenue streams.
- Fixed Systems:Permanent X-band and Ku-band installations with embedded power and fiber telemetry serve dam abutments and mine highwalls under FERC and MSHA continuous-monitoring mandates. Southwestern US copper operations in Arizona and Nevada represent the dominant demand concentration as pit wall heights exceed stability thresholds requiring certified instrumentation.
- Portable Systems:Rapid-deployment kits with battery power and cellular telemetry enable post-wildfire and post-flood slope assessment along California and Colorado transportation corridors. Emergency management agencies stockpile these units under extreme weather response protocols, driving the steepest expansion trajectory across the product range.
- Hybrid Systems:Configurable architectures allowing fixed-to-portable conversion address municipal budget constraints.
- Monitoring Accessories:Power enclosures, mounting hardware, and atmospheric correction modules complete installation packages.
Fixed systems hold installed capacity. Portable systems are rotating up the share rankings.
Technology:
Performance differentiation now hinges on software-defined processing rather than hardware sensitivity specifications.
- Real-Time Monitoring:Interferometric processing platforms with automated phase unwrapping and cloud-based threshold alerting command premium positioning through subscription revenue models. Mining operators in Nevada and Arizona favor these systems for MSHA compliance documentation and liability transfer to equipment suppliers.
- Ground Penetrating Radar:Subsurface imaging systems detect discontinuities and moisture accumulation behind rock faces. Canadian rail corridor operators deploy GPR for embankment integrity assessment where interferometric surface monitoring proves insufficient.
- Laser Scanning:Terrestrial LiDAR retains cost advantages for periodic survey regimes in budget-constrained geotechnical programs.
- Inclinometers:Borehole displacement sensors provide deep-seated movement data complementary to surface radar.
Real-time monitoring anchors vendor profitability. Ground penetrating radar is climbing the fastest among legacy technologies.
End User:
Procurement authority fragmentation shapes sales cycle complexity and contract structure preferences.
- Mining Operations:Open-pit copper and aggregate producers in Arizona, Nevada, and Sonora drive specification-grade demand with performance-based service agreements replacing capital purchase models. MSHA enforcement actions accelerate displacement of periodic survey contracts.
- Government Agencies:State departments of transportation in California, Colorado, and British Columbia deploy roadside radar under Transport Canada and US Federal Highway Administration geohazard protocols favoring automated detection.
- Construction Firms:Civil contractors integrate radar monitoring for temporary excavation support and adjacent structure protection.
- Environmental Consultants:Third-party geotechnical firms specify rental and service contracts for project-specific monitoring.
Mining operations concentrate procurement volume. Government agencies are gaining share fastest as federal infrastructure spending flows to state transportation departments.
Application:
Use case prioritization reflects liability exposure and regulatory inspection frequency.
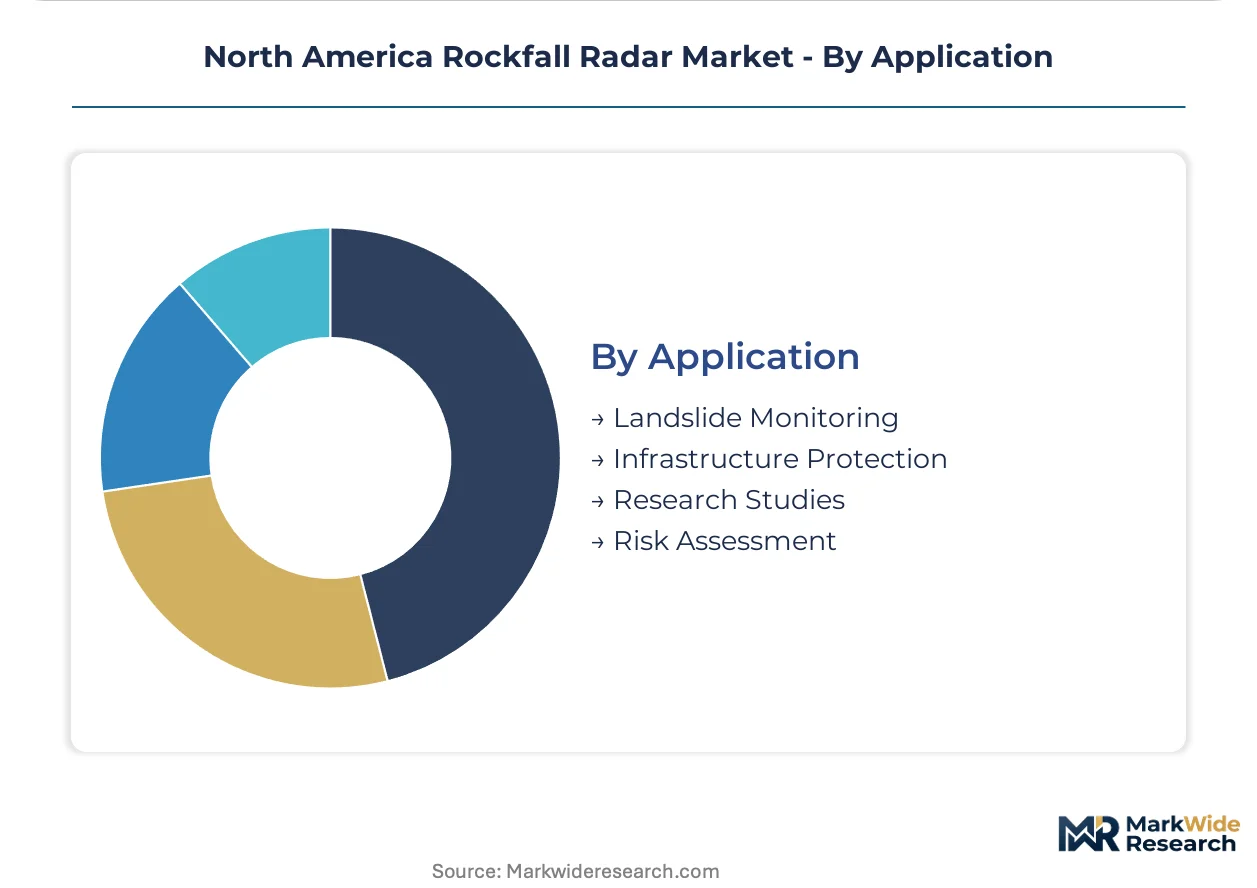
- Infrastructure Protection:Highway corridor and railway embankment monitoring commands sustained investment as western states replace visual inspection cycles with automated detection. Interstate segments through topographically unstable terrain in California and Colorado receive multi-year deployment commitments.
- Landslide Monitoring:Community-scale warning systems protect residential areas below known failure zones. Post-wildfire debris flow assessment in California drives seasonal demand spikes for portable deployment.
- Risk Assessment:Pre-construction geohazard characterization supports insurance and financing due diligence.
- Research Studies:Academic and government research programs advance interferometric algorithm development and atmospheric correction methodologies.
Infrastructure protection dominates contract value. Landslide monitoring is expanding most quickly as climate-driven slope instability intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply: southwestern US mining corridors favor permanent fixed installations under MSHA mandates, while Canadian rail operators prioritize interferometric systems for transportation embankments, and Mexican mining districts show nascent demand for rapid-deployment portable units.
United States
Open-pit copper operations in Arizona and Nevada drive specification-grade demand as pit wall heights exceed 400 meters. FERC mandates on dam safety instrumentation compel hydroelectric operators to deploy certified continuous-monitoring radar at facility abutments. California and Colorado transportation departments stockpile portable radar kits under extreme weather response protocols for post-wildfire slope assessment.
Canada
Canadian National and Canadian Pacific Kansas City railways deploy interferometric radar for rockfall detection along mountain corridors in British Columbia and Alberta. Transport Canada geohazard risk assessment protocols favor automated detection over visual inspection cycles for roadside deployment. The Thompson-Nicola region hosts concentrated slope-monitoring infrastructure serving both rail and highway corridors through topographically unstable terrain.
Mexico
Sonora and Zacatecas states host expanding open-pit copper and silver operations with limited domestic radar supplier presence. The country's national mining regulator intensifies scrutiny of highwall stability programs as foreign operators scale production. Hermosillo and Zacatecas City anchor emerging procurement activity for slope-monitoring systems serving Grupo México and Fresnillo operations.
North America Rockfall Radar Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American rockfall radar supply. The upper tier commands premium positioning through proprietary interferometric software and subscription-based alerting services, while mid-tier assemblers compete on deployment speed and open-architecture compatibility. Two strategic archetypes dominate: geotechnical instrumentation specialists with deep slope-monitoring expertise, and surveying equipment conglomerates leveraging GNSS integration capabilities. Competitive moves concentrate on sensor fusion partnerships and performance-based service agreements that transfer detection liability to equipment suppliers.
Among European-anchored specialists, IDS GeoRadar and GroundProbe exemplify the premium-tier archetype through proprietary processing platforms. Trimble Inc. represents the surveying-conglomerate vector, anchoring its presence via civil construction footprint extension. These three occupy positions across the fixed-installation and portable-deployment spectrum, with differentiated emphasis on mining compliance documentation versus transportation corridor automation.
| Leading Market Players |
|---|
| IDS GeoRadar |
| RST Instruments Ltd |
| Slope Indicator |
| GeoSIG Ltd |
| Trimble Inc. |
| Geobrugg AG |
| GroundProbe |
| Hexagon AB |
| Campbell Scientific Inc. |
| Others |
Pricing and Supply Chain Analysis
FERC dam safety instrumentation mandates and MSHA highwall stability certifications simultaneously gate supplier qualification and stratify price tiers across fixed installation and portable deployment categories. Buyers face procurement trade-offs between proprietary sensor networks and interoperable platforms as certification requirements harden around open data standards.
Pricing Analysis
Long-term service agreements displace capital purchase models as mining operators in Arizona and Nevada transfer detection liability to equipment suppliers through performance-based contracts. Three-tier pricing structure across premium, standard, and economy levels separates integrated interferometric platforms with proprietary software from modular assemblers and rapid-deployment kits. Cost compression in portable systems is intensifying as real-time processing modules commoditize and emergency management agencies consolidate procurement volumes. Municipal transportation departments exhibit highest price sensitivity due to constrained civil works budgets, while copper producers under MSHA enforcement show lowest sensitivity to secure compliance documentation.
Supply Chain Analysis
Inventory lead times for X-band and Ku-band microwave transceiver modules stretch procurement cycles as defense-aerospace supply chains prioritize military contracts over commercial radar manufacturers. Component sourcing concentrates in the United States, Germany, and Japan for precision microwave hardware, while atmospheric correction modules and cellular telemetry units draw from Taiwan and South Korea. Single-source vulnerability pervades the transceiver tier where qualified suppliers number fewer than five globally. Distribution runs through direct vendor relationships with mining operators and government agencies, supplemented by environmental consulting firms acting as rental intermediaries for project-specific deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time interferometric processing disruption is collapsing hardware moats and shifting competitive differentiation toward software-defined alerting latency and false-positive suppression algorithms.
For Market Incumbents: Shield proprietary positioning by deepening backward integration into microwave transceiver production to escape defense-aerospace supply chain bottlenecks. Anchor subscription revenue through cloud-based threshold alerting services that transfer operational liability from mining operators. Counter modular assembler encroachment by certifying seamless SCADA protocol bridging that accelerates deployment timelines.
For New Entrants and Emerging Players: Anchor in Mexican mining corridors where Sonora and Zacatecas operations lack domestic radar supplier presence and foreign operators scale production. Target rapid-deployment portable systems for California and Colorado emergency management agencies stockpiling post-wildfire slope assessment kits. Pursue GNSS-radar sensor fusion partnerships with surveying equipment providers to bypass interferometric signal processing expertise shortages.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable system manufacturing as battery power and cellular telemetry commoditize, while fixed installation civil works integration retains high capital requirements. Long-term viability favors vendors capturing recurring subscription revenue over hardware-margin-dependent assemblers. Monitor MSHA enforcement action frequency in Nevada and Arizona as the inflection signal for performance-based contract adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Partnership | GNSS-radar integration with Trimble deformation networks captures unified displacement monitoring demand. |
| Subscription Alerting Service Launch | Cloud-based threshold platforms shift value capture from hardware margins to operational continuity guarantees. |
| Geographic Expansion | Mexican mining corridor penetration addresses nascent slope-monitoring infrastructure in Sonora and Zacatecas. |
| Certification Investment | FCC and Industry Canada radio frequency licensing harmonization simplifies cross-border procurement for frontier operators. |
| Backward Integration | In-house X-band transceiver production reduces defense-aerospace supply chain dependency and procurement bottlenecks. |
Research Methodology
Desk research of FERC dam safety filings, MSHA highwall stability enforcement records, and Transport Canada geohazard protocols preceded structured interviews with mining operations directors, state transportation department procurement managers, and geotechnical instrumentation specialists. Primary fieldwork with radar system deployment engineers and emergency management agency equipment officers combined with secondary validation through SEC filings of surveying equipment conglomerates and customs records of microwave component trade flows. Bottom-up unit deployment estimates across Arizona, Nevada, California, Colorado, and Canadian mining corridors triangulated against top-down market size constraints from equipment manufacturer revenue disclosures.
Variance decomposition across product type, technology tier, end-user category, and application use case anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include fixed versus portable deployment architecture, real-time interferometric versus periodic survey monitoring modality, mining operator versus government agency procurement authority, and infrastructure protection versus landslide warning application context. CAGRs derived from slope-monitoring equipment installation trajectories, pit wall height expansion rates in southwestern copper operations, and federal infrastructure spending allocation patterns to state transportation departments.
Decision-makers should treat outputs as directional under assumptions of sustained MSHA enforcement intensity and continued FERC dam safety mandate expansion; material deviation in regulatory scrutiny levels or mining capital expenditure cycles would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Noise Control System Market
Environmental Safety
Home Decontamination Services Market