
 Signal Jamming Systems Market | 2026-2036
Signal Jamming Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Signal Jamming Systems Market Analytics
The pool of cleared radio-frequency engineers with military security clearances is collapsing across NATO defense industrial bases. BAE Systems leverages its British electronic warfare heritage to sustain classified R&D pipelines for next-generation jamming payloads. Northrop Grumman anchors U.S. Navy contracts through its dominance in shipboard counter-IED jamming suites. Elbit Systems competes aggressively in the Israeli and export markets with software-defined jamming architectures that reduce hardware refresh cycles.
Signal jamming systems are electronic warfare devices that emit radio-frequency energy to disrupt, deny, or degrade targeted wireless communications across specified frequency bands, typically operating from 20 MHz to 6 GHz with output power levels from milliwatts for personal privacy devices to kilowatts for military area denial systems. Their primary purpose spans military force protection, law enforcement counter-surveillance, and controlled environment security where unauthorized wireless transmission presents operational risk. Drone jammers command premium pricing due to rapid proliferation of unmanned aerial threats in conflict zones and critical infrastructure defense. Software-defined technology is displacing analog architectures fastest, enabling waveform agility and multi-target engagement without hardware swaps. Military end users retain the deepest procurement budgets, though law enforcement adoption broadens as civil authorities acquire portable cell and GPS denial capabilities for hostage and prison security scenarios.
The U.S. FCC enforces strict Part 15 and Communications Act prohibitions on civilian jammer marketing, creating a bifurcated market where lawful demand channels almost exclusively through federal procurement. Israel's Ministry of Defense and the U.K. Ministry of Defence coordinate closely with domestic suppliers on export-controlled electronic warfare specifications, reinforcing national industrial bases. Stakeholders must monitor how emerging autonomous swarm threats and corresponding countermeasures reshape procurement priorities for software-defined hybrid platforms.
Market Dynamics
Software-defined radio architectures are collapsing hardware refresh cycles and compressing procurement timelines across military and law enforcement channels, forcing suppliers to restructure R&D pipelines around firmware-centric delivery models.
Growth Catalysts
- Autonomous swarm proliferation:Drone swarm threats in Ukraine and Gaza are accelerating NATO procurement of multi-target engagement systems capable of simultaneous denial across distributed frequency bands.
- FCC Part 15 enforcement:Strict U.S. prohibitions on civilian jammer marketing channel lawful demand exclusively through federal contracts, insulating defense suppliers from price competition.
- Electronic warfare modernization:British, Israeli, and U.S. defense budget reallocations prioritize counter-GPS and counter-IED capabilities for force protection in contested electromagnetic environments.
Market Restraints
- Gallium nitride supply concentration:High-power amplifier substrates depend on Chinese and Taiwanese foundry capacity, exposing procurement to export control volatility and geopolitical disruption.
- Security clearance scarcity:The collapsing pool of cleared radio-frequency engineers across NATO defense industrial bases constrains classified program staffing and extends development timelines.
- Spectrum licensing fragmentation:National regulatory divergences in frequency allocation and power limits complicate cross-border system deployment and certification reciprocity.
Strategic Opportunities
- Law enforcement portable systems:U.S. state and municipal agencies are acquiring cell and GPS denial capabilities for prison security and hostage response, broadening the buyer base beyond federal channels.
- Hybrid software-defined platforms:Convergence of artificial intelligence-driven threat detection with adaptive jamming waveforms enables autonomous engagement without operator intervention.
- U.K. export coordination:Ministry of Defence alignment with domestic suppliers on export-controlled specifications creates captive demand for British electronic warfare heritage products.
Industry Challenges
- Radio-frequency engineering talent gap:Military security clearance requirements and specialized analog-digital hybrid design skills limit workforce expansion across NATO suppliers.
- Legacy system integration friction:New software-defined architectures must interface with existing shipboard and vehicle-mounted counter-IED suites, complicating field deployment and operator training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Signal Jamming Systems Market |
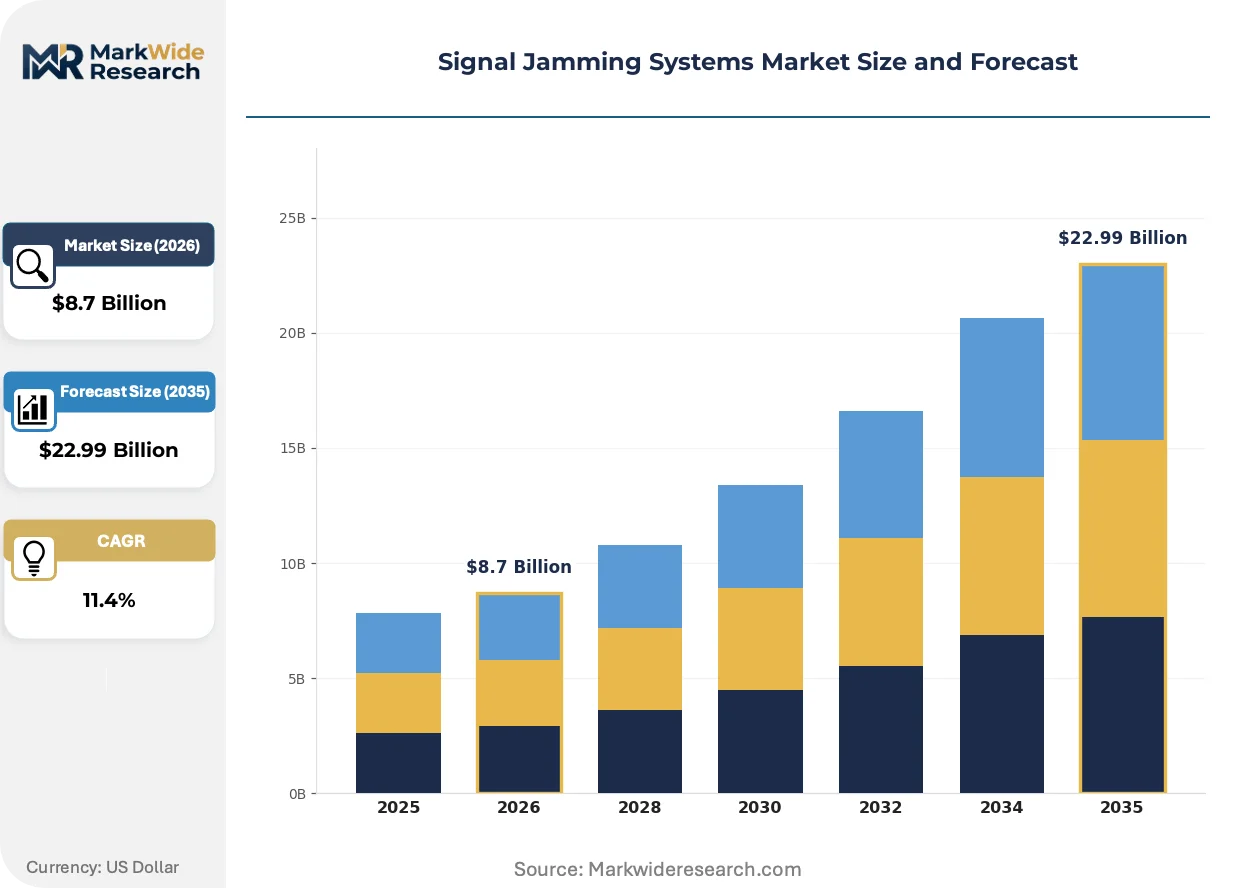
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cell Phone Jammers, GPS Jammers, Wi-Fi Jammers, Drone Jammers Technology: Analog, Digital, Software-Defined, Hybrid End User: Military, Law Enforcement, Corporate, Educational Institutions Application: Counter-Terrorism, Security Operations, Privacy Protection, Event Management |
| Companies Covered | Raytheon Technologies, BAE Systems, Northrop Grumman, L3Harris Technologies, Lockheed Martin, Thales Group, Elbit Systems, Leonardo S.p.A., Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Signal Jamming Systems Market Evolving Landscape
Waveform agility and firmware-upgradable platforms are displacing fixed-function hardware, compressing supplier margins while enabling rapid threat response without physical retrofit.
Software-defined jamming architectures are fragmenting the traditional hardware refresh cycle by enabling multi-band, multi-target engagement through firmware updates rather than module replacement. Military end users in the United States and Israel are adopting these platforms fastest, demanding programmable systems that adapt to emerging drone and swarm threats within weeks rather than years. This capability is fragmenting supplier market power by reducing customer lock-in to proprietary hardware ecosystems.
EU dual-use export controls and U.S. International Traffic in Arms Regulations are tightening classification and licensing requirements for electronic warfare components with civilian crossover potential. Industrial consequence includes extended compliance timelines and bifurcated product lines separating export-restricted from commercially available variants. Israeli and British suppliers are responding by deepening domestic content requirements and securing national industrial security agreements.
Defense procurement offices are compressing development cycles and demanding spiral upgrade pathways rather than single-platform acquisitions. Prime contractors are disaggregating system integration from subsystem supply, opening tier-two opportunities for specialized waveform and antenna suppliers. This pattern is most visible in U.S. Navy shipboard programs and Israeli Ministry of Defense rapid fielding initiatives.
Signal Jamming Systems Market Segmentation
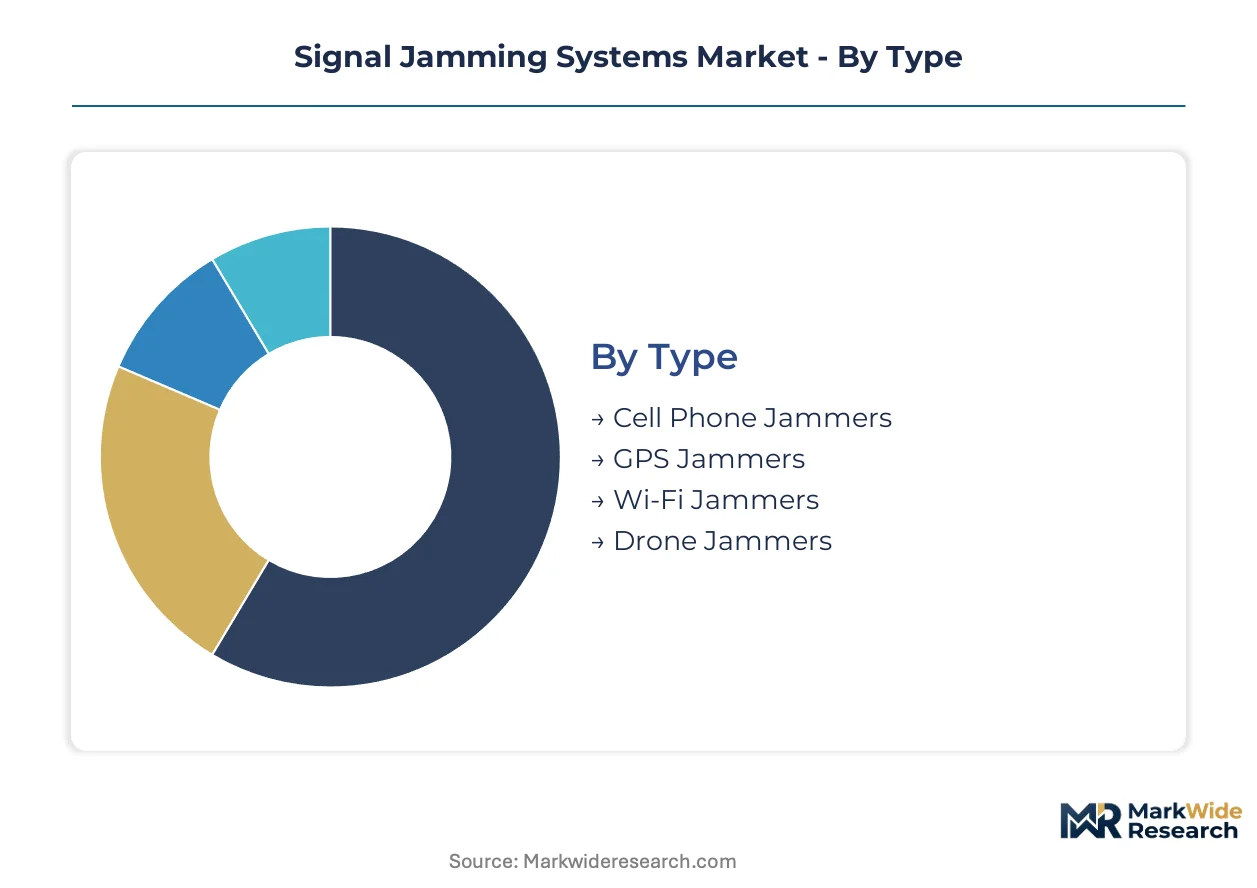
Signal jamming systems fragment across four critical dimensions where procurement channels, technical specifications, and regulatory constraints diverge sharply. Understanding these splits reveals where defense budgets concentrate versus where civil demand encounters legal barriers.
Type:
Channel flow varies dramatically by jammer type, with military procurement dominating drone and GPS denial systems while law enforcement channels absorb portable cell phone units.
- Drone Jammers:Multi-band RF denial systems operating across 2.4 GHz, 5.8 GHz, and GNSS frequencies to neutralize unmanned aerial threats. Demand concentrates in Israeli and British defense procurement for border security and force protection, driven by autonomous swarm proliferation in Ukraine and Gaza conflict zones.
- GPS Jammers:Satellite navigation denial systems emitting L1/L2/L5 band interference to degrade precision guidance. U.S. Navy shipboard programs anchor procurement volume, constrained by FCC Part 15 prohibitions that channel lawful civilian demand exclusively through federal contracts.
- Cell Phone Jammers:Cellular frequency blockers targeting 700 MHz through 2.6 GHz bands for controlled environment security. U.S. state prison systems and municipal hostage response teams drive law enforcement adoption despite strict marketing prohibitions.
- Wi-Fi Jammers:2.4 GHz and 5 GHz denial systems for corporate data protection and examination security. Educational institutions in the United Kingdom acquire limited deployments for standardized testing integrity.
By volume, cell phone jammers lead through broad law enforcement penetration. By growth pace, drone jammers are climbing the fastest.
Technology:
Cost tier stratification separates legacy analog hardware from premium software-defined platforms that compress refresh cycles through firmware agility.
- Software-Defined:FPGA and DSP-based architectures enabling waveform reprogramming without hardware swaps. Israeli Ministry of Defense rapid fielding initiatives and U.S. Navy spiral upgrade pathways drive procurement, collapsing traditional multi-year development timelines.
- Hybrid:Mixed-signal platforms combining analog RF front-ends with digital baseband processing. British Army electronic warfare modernization programs prioritize these systems for legacy counter-IED suite integration.
- Digital:Fully digitized signal generation with precise frequency agility. Corporate security buyers in data-sensitive sectors adopt these for facility protection where regulatory compliance permits.
- Analog:Fixed-frequency hardware with dedicated oscillator circuits. Budget-constrained educational and small-scale corporate users sustain residual demand despite obsolescence pressure.
By installed base, analog systems still dominate. By procurement momentum, software-defined platforms are gaining share fastest.
End User:
Customer type determines pricing power and regulatory pathway, with military buyers commanding custom specifications while corporate users face strict deployment constraints.
- Military:Nation-state procurement of area denial and force protection systems with kilowatt-scale output power. NATO electronic warfare modernization budgets in the United States, United Kingdom, and Israel sustain the deepest procurement pipelines.
- Law Enforcement:Federal, state, and municipal agencies acquiring portable cell and GPS denial for prison security, hostage response, and counter-surveillance. U.S. Bureau of Prisons and British Ministry of Justice coordinate specifications with domestic suppliers.
- Corporate:Commercial security departments in critical infrastructure, finance, and data centers. Deployment remains severely constrained by FCC enforcement actions and national spectrum licensing fragmentation.
- Educational Institutions:Universities and examination boards acquiring limited Wi-Fi and cell denial for academic integrity. U.K. examination regulators permit restricted deployments where interference containment is demonstrable.
By absolute spend, military end users command the largest share. By channel expansion, law enforcement represents the steepest trajectory.
Application:
Application focus shifts system specifications toward either persistent area denial or targeted tactical deployment, with corresponding divergence in power, portability, and operator training requirements.
- Counter-Terrorism:Multi-target engagement systems for improvised explosive device neutralization and drone threat denial. U.S. Joint Improvised-Threat Defeat Organization and Israeli counter-terror units drive specifications for rapid fielding.
- Security Operations:Persistent perimeter protection for critical infrastructure, government facilities, and diplomatic compounds. British Ministry of Defence and U.S. Department of State security programs anchor demand.
- Privacy Protection:Personal and small-scale RF denial for sensitive conversations and data protection. Civilian marketing prohibitions in the United States and European Union constrain lawful channels.
- Event Management:Temporary deployment for executive protection, high-profile gatherings, and secure facility operations. Licensed frequency coordination with national regulators determines deployment feasibility.
By system count, security operations leads through installed base expansion. By specification intensity, counter-terrorism commands the most rapid capability advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Military procurement dominates in Israel and the United Kingdom, while the United States channels nearly all lawful demand through federal contracts due to strict marketing prohibitions.
United States
U.S. Navy shipboard programs and Joint Improvised-Threat Defeat Organization contracts anchor procurement volume for counter-IED and GPS denial systems. FCC Part 15 enforcement actions and Communications Act prohibitions block civilian marketing, insulating defense suppliers from price competition. Washington D.C. and San Diego defense clusters concentrate prime contractor activity for electronic warfare modernization.
Israel
Ministry of Defense rapid fielding initiatives drive demand for software-defined architectures that adapt to drone swarm threats within weeks. Export-controlled specifications coordinate closely with domestic suppliers, reinforcing national industrial base capture. Haifa and Tel Aviv metropolitan areas host concentrated R&D activity for next-generation jamming payloads.
United Kingdom
British Army electronic warfare modernization and Ministry of Defence security programs prioritize hybrid systems for legacy counter-IED suite integration. Ministry of Justice coordinates prison security specifications with domestic suppliers for portable cell denial capabilities. South East England and Bristol defense corridors sustain classified development pipelines.
Germany
Bundeswehr electronic warfare procurement accelerates following NATO capability targets for electromagnetic spectrum operations. Federal Office for Information Security and national spectrum regulators enforce strict civilian deployment constraints. Munich and Stuttgart industrial clusters specialize in high-power amplifier components for military area denial systems.
Australia
Australian Defence Force electronic warfare roadmaps prioritize force protection systems for Indo-Pacific contested environments. Defence Export Controls and national security regulations channel procurement through approved supplier frameworks. Adelaide and Canberra defense hubs concentrate system integration activity for regional alliance requirements.
Signal Jamming Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer structure where prime contractors control system integration while component suppliers compete for subsystem awards. The upper tier consolidates around defense conglomerates with cleared facility infrastructure and long-term government relationships. Three archetypes dominate: heritage electronic warfare houses with classified R&D pipelines, diversified aerospace primes leveraging platform integration advantages, and agile specialists in software-defined architectures. Competitive intensity centers on spiral upgrade contracting and rapid fielding partnerships rather than price-based rivalry.
Within the heritage electronic warfare tier, BAE Systems and Elbit Systems occupy positions shaped by national industrial security agreements and export-controlled development pipelines. Northrop Grumman anchors the diversified prime segment through shipboard program dominance. These three exemplify how geographic origin and domestic procurement alignment determine competitive positioning in a market where lawful demand channels almost exclusively through defense ministries.
| Leading Market Players |
|---|
| Raytheon Technologies |
| BAE Systems |
| Northrop Grumman |
| L3Harris Technologies |
| Lockheed Martin |
| Thales Group |
| Elbit Systems |
| Leonardo S.p.A. |
| Israel Aerospace Industries |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month lead times for gallium nitride high-power amplifier substrates concentrate procurement leverage with Taiwanese and Chinese foundries, compressing margin flexibility for system integrators while amplifying price volatility for NATO defense suppliers locked into long-term electronic warfare modernization contracts.
Pricing Analysis
Long-term offtake agreements dominate military procurement channels, insulating prime contractors from spot-market fluctuations while tier-two waveform suppliers face project-based pricing pressure. Three-tier pricing structure across software-defined, hybrid, and analog architectures reflects certification grade and customization depth. Cost compression in analog tiers intensifies because firmware agility renders fixed-frequency hardware obsolete. Corporate security buyers exhibit highest price sensitivity due to strict FCC Part 15 constraints that limit lawful deployment scale.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes gallium nitride substrate flows to geopolitical disruption, compelling defense primes to diversify foundry relationships. High-power amplifier substrates, FPGA chipsets, and specialized antenna arrays draw from Taiwan, China, and South Korean manufacturing clusters. Single-source vulnerability concentrates in epitaxial wafer supply where domestic alternatives remain immature. Distribution runs through defense ministry procurement offices with cleared-facility requirements rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined radio architectures are collapsing hardware refresh cycles, creating a high-growth disruption where firmware-centric delivery models reward agile suppliers and strand analog-dependent incumbents.
For Market Incumbents: Fortify classified R&D pipelines through captive gallium nitride substrate agreements with domestic foundries, neutralizing Taiwanese supply concentration risk. Deepen Ministry of Defence alignment on export-controlled specifications to lock out non-national competitors. Prioritize spiral upgrade contracting pathways that embed recurring firmware revenue streams.
For New Entrants and Emerging Players: Anchor in law enforcement portable systems where FCC Part 15 prohibitions have preserved pricing power against federal procurement benchmarks. Target U.S. state prison systems and municipal hostage response teams with software-defined cell denial units. Pursue rapid fielding partnerships with Israeli Ministry of Defense initiatives as the fastest qualification pathway.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-industrial consolidation play because electronic warfare modernization budgets are concentrating procurement with heritage suppliers possessing cleared facility infrastructure. Acquisition targets should display software-defined waveform expertise and existing national industrial security agreements. Monitor autonomous swarm threat proliferation in Ukraine and Gaza as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Spiral Upgrade Contracting | Firmware-centric revenue streams align with U.S. Navy electronic warfare modernization priorities. |
| Domestic Gallium Nitride Foundry Investment | Backward integration into substrate supply mitigates Taiwanese export control exposure for NATO suppliers. |
| Law Enforcement Channel Expansion | State prison system procurement broadens buyer base beyond federal defense ministry concentration. |
| AI-Driven Threat Detection Integration | Autonomous engagement capabilities differentiate hybrid platforms in Israeli rapid fielding initiatives. |
| National Industrial Security Agreement Deepening | Export-controlled specification alignment with British Ministry of Defence creates captive demand capture. |
Research Methodology
Operator-level perspectives from electronic warfare program managers, RF engineering directors at defense primes, FCC enforcement attorneys, and Israeli Ministry of Defense procurement officers anchored the qualitative base. Primary interview findings triangulated against secondary sources including U.S. Navy budget justification documents, NATO electromagnetic spectrum capability targets, Israeli export control filings, and British Ministry of Defence equipment plans. Bottom-up segmentation modeling cross-validated with top-down defense budget allocation analysis.
Sensitivity analysis tested forecast robustness across gallium nitride supply disruption scenarios and regulatory enforcement intensity variations. The analytical framework disaggregated volume and value across jammer type, technology architecture, end-user category, and application focus throughout the forecast period. CAGRs derived from procurement pipeline velocity indicators and spiral upgrade adoption curves. Drone swarm threat proliferation rates and software-defined platform refresh frequency served as key demand-side inputs.
Decision-makers should treat outputs as directional under sustained NATO electronic warfare modernization commitment and stable Taiwan Strait logistics; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FCC Part 15 enforcement intensity and autonomous swarm threat evolution reshape procurement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Security Services Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
North America Security Services Market