
 Global Cargo Inspection Market | 2026-2036
Global Cargo Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cargo Inspection Market Foresight
India is narrowing its technology gap in cargo screening infrastructure through domestic manufacturing incentives and port authority modernization programs. SGS Group leverages its transcontinental laboratory network to sustain certification throughput across high-volume trade lanes. Bureau Veritas anchors its maritime inspection franchise on classification society protocols and port-state control mandates. Intertek Group competes through specialized petroleum and agricultural cargo testing protocols in emerging trade corridors.
Cargo inspection encompasses the non-destructive verification of container contents, bulk commodities, and packaged freight using radiation-based, acoustic, or electromagnetic detection methods to identify contraband, verify trade documentation, and enforce safety standards. X-ray and gamma ray scanners dominate installed port capacity due to throughput economics and mature regulatory acceptance, while computed tomography systems capture premium replacement cycles as customs agencies pursue three-dimensional imaging resolution for dense cargo discrimination. Radiography maintains the largest technology footprint across border security applications, though infrared scanning gains traction in warehouse security deployments where chemical signature detection supplements physical screening.
The World Customs Organization SAFE Framework and national implementations by US CBP, EU DG TAXUD, and India's Central Board of Indirect Taxes and Customs collectively mandate escalating inspection coverage ratios and data interoperability standards that directly determine equipment procurement cycles and service contract durations. ISO 17020 and ISO 17025 accreditation requirements further stratify vendor eligibility for government tenders across major trade economies. Stakeholders must weigh capital intensity against multi-year service revenue streams when evaluating port authority digitalization timelines and customs modernization funding commitments.
Market Dynamics
Computed tomography systems are compressing inspection cycle times at high-throughput terminals while customs agencies mandate three-dimensional imaging resolution for dense cargo discrimination, forcing equipment refresh decisions at Rotterdam, Singapore, and Los Angeles port authorities.
Growth Catalysts
- Union Customs Code modernization:The EU's updated code drives automated scanning compliance mandates across Rotterdam, Hamburg, and Antwerp terminals.
- Non-intrusive inspection expansion:Southeast Asian customs agencies scale containerized freight screening programs at Singapore, Port Klang, and Tanjung Pelepas.
- Domestic manufacturing incentives:India's PLI scheme narrows technology gaps in cargo screening infrastructure through port authority modernization programs.
Market Restraints
- Capital intensity barriers:Gamma ray scanner deployment requires substantial upfront investment at mid-tier port terminals.
- Regulatory fragmentation:Divergent national implementations of the WCO SAFE Framework create compliance complexity across multi-jurisdictional trade lanes.
- Technical throughput ceilings:Legacy radiography systems face resolution limitations when discriminating densely packed container contents.
Strategic Opportunities
- Indian port corridor expansion:Jawaharlal Nehru Port Trust and Mundra Port modernization programs create equipment replacement demand.
- Infrared-physical screening convergence:Warehouse security deployments integrate chemical signature detection with electromagnetic scanning.
- ISO 17020 accreditation premium:Vendor eligibility stratification for government tenders creates service contract differentiation.
Industry Challenges
- Certification timeline compression:ISO 17025 laboratory accreditation requirements extend vendor qualification periods for customs tenders.
- Legacy system integration friction:Port authority digitalization timelines must accommodate existing scanner infrastructure and data architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cargo Inspection Market |
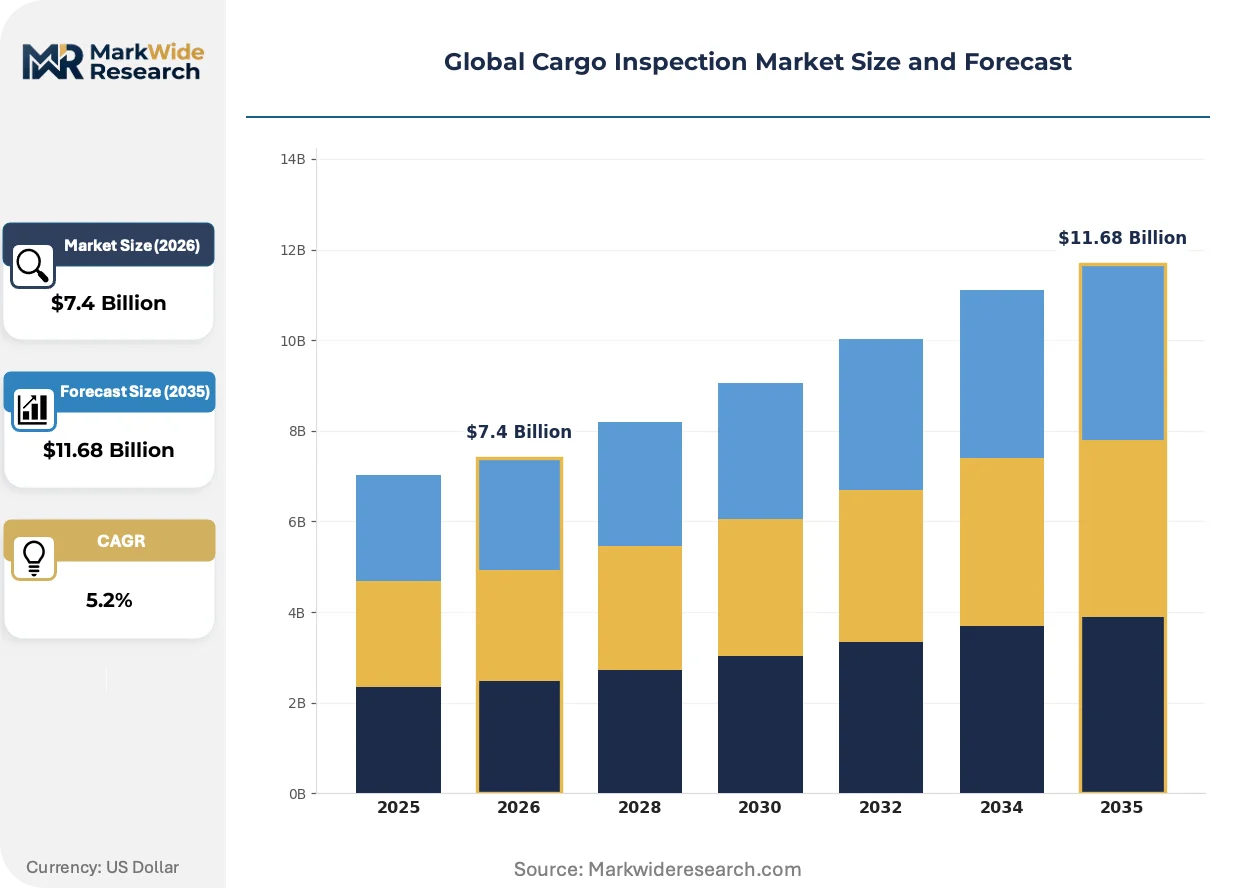
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.68 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Scanners, Gamma Ray Scanners, Metal Detectors, Explosive Trace Detectors, Optical Scanners Technology: Computed Tomography, Radiography, Ultrasound Imaging, Magnetic Resonance, Infrared Scanning Application: Border Security, Transportation Hubs, Ports & Terminals, Postal Inspection, Warehouse Security End User: Customs Agencies, Shipping Operators, Freight Forwarders, Logistics Providers, Security Contractors |
| Companies Covered | Cotecna Inspection SA, TÜV SÜD, SGS Group, DNV GL AS, DEKRA SE, Bureau Veritas SA, ALS Limited, AmSpec Group, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cargo Inspection Market Shifts & Advancements
Inspection workflows are reconfiguring around real-time data interoperability and predictive risk targeting, compressing the traditional sequence of physical screening, documentation verification, and customs release into synchronized operations.
Dual-energy X-ray detection is virtualizing the cargo inspection process by distinguishing organic from inorganic materials through spectral analysis. Terminal operators at Los Angeles and Long Beach deploy these systems to reduce manual container opening rates. The technology is virtualizing traditional customs inspection labor pools into remote image analysis centers.
REACH chemical compliance mandates in Europe now extend to cargo inspection protocols for hazardous material documentation verification. Industrial consequence includes mandatory testing certification for bulk chemical shipments entering Rotterdam and Antwerp. Petrochemical terminals are responding by embedding laboratory sampling into standard unloading workflows.
Buyer concentration at mega-terminal operators is compressing vendor negotiation cycles from multi-year equipment leases toward performance-guaranteed service agreements. Traditional inspection equipment distributors face disintermediation as port authorities contract directly with technology integrators. This pattern is most visible in Singapore's PSA International procurement framework.
Global Cargo Inspection Market Segmentation
Segmentation in cargo inspection reveals how equipment procurement cycles diverge across regulatory environments and operational scale. Understanding these divisions exposes where service revenue concentrates versus capital equipment sales.
Product Type:
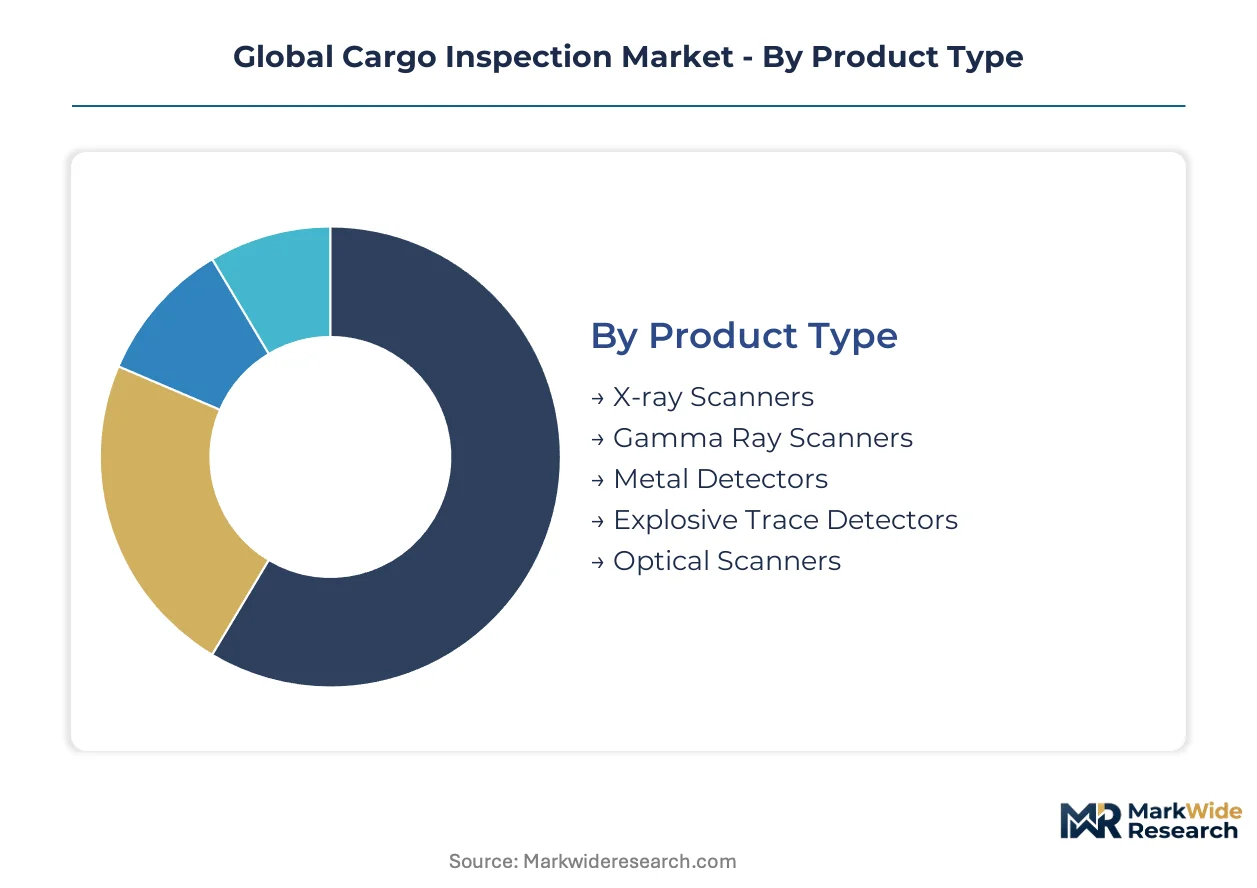
After-sales-service intensity varies sharply across scanner categories, with radiation-based systems demanding specialized maintenance contracts that extend vendor relationships far beyond initial deployment.
- X-ray Scanners:Dual-energy systems distinguish organic from inorganic materials through spectral differentiation. Demand clusters at Los Angeles and Long Beach terminals where US CBP mandates reduced manual inspection rates; throughput economics favor 24/7 operational models requiring intensive field service networks.
- Gamma Ray Scanners:Cobalt-60 or cesium-137 isotope sources penetrate dense steel containers at higher rates than X-ray alternatives. Deployment concentrates at Singapore's PSA International and Rotterdam terminals where customs agencies prioritize cargo density penetration over scan speed; isotope replacement cycles create predictable recurring revenue streams.
- Metal Detectors:Electromagnetic induction systems screen personnel and vehicle access points at port perimeters.
- Explosive Trace Detectors:Ion mobility spectrometry identifies vapor-phase chemical signatures at checkpoint screening stations.
- Optical Scanners:High-resolution imaging verifies container seal integrity and external damage documentation.
X-ray scanners hold the largest share; momentum sits with gamma ray systems at mega-terminal expansions.
Technology:
Technology selection tracks the trade-off between imaging resolution and container throughput, with premium terminals accepting slower scan cycles for enhanced detection accuracy.
- Computed Tomography:Three-dimensional reconstruction algorithms eliminate cargo overlap ambiguities inherent to two-dimensional radiography. Rotterdam, Singapore, and Los Angeles port authorities are forcing equipment refresh decisions as customs agencies mandate depth-resolved imaging for dense cargo discrimination; installation complexity drives multi-year integration timelines.
- Radiography:Projection imaging maintains the largest installed base across border security applications due to mature regulatory acceptance and lower capital thresholds. Legacy systems at mid-tier Indian and Southeast Asian terminals face resolution limitations when discriminating densely packed container contents; upgrade cycles lag behind premium corridor modernization.
- Ultrasound Imaging:Acoustic penetration assesses liquid bulk cargo integrity without container breach.
- Magnetic Resonance:Spectroscopic analysis identifies chemical compositions in specialized hazardous material screening.
- Infrared Scanning:Thermal and spectral detection gains traction in warehouse security deployments where chemical signature detection supplements electromagnetic screening.
Radiography dominates installed capacity; computed tomography is climbing the fastest at high-throughput terminals.
Application:
Application segmentation maps directly to procurement authority structures, with government-funded border security operating on different budget cycles than private terminal operator investments.
- Ports & Terminals:Containerized freight screening at berth-side and gate-line positions constitutes the revenue core. Singapore's PSA International, Rotterdam, and Jawaharlal Nehru Port Trust drive replacement demand through authority-level digitalization programs; performance-guaranteed service agreements are compressing traditional equipment lease structures.
- Border Security:Land crossing inspection stations require mobile and fixed-site systems for truck and rail cargo verification. US CBP and India's Central Board of Indirect Taxes and Customs procurement follows federal budget cycles with multi-year appropriation dependencies; equipment standardization across stations creates volume purchasing leverage.
- Transportation Hubs:Airport and intermodal freight facilities integrate screening into baggage and cargo handling workflows.
- Postal Inspection:High-speed parcel screening at international mail facilities addresses small-package contraband detection.
- Warehouse Security:Distribution center deployments emphasize chemical signature detection alongside physical access control.
Ports and terminals command the largest procurement volumes; border security presents the steepest expansion trajectory from baseline infrastructure gaps.
End User:
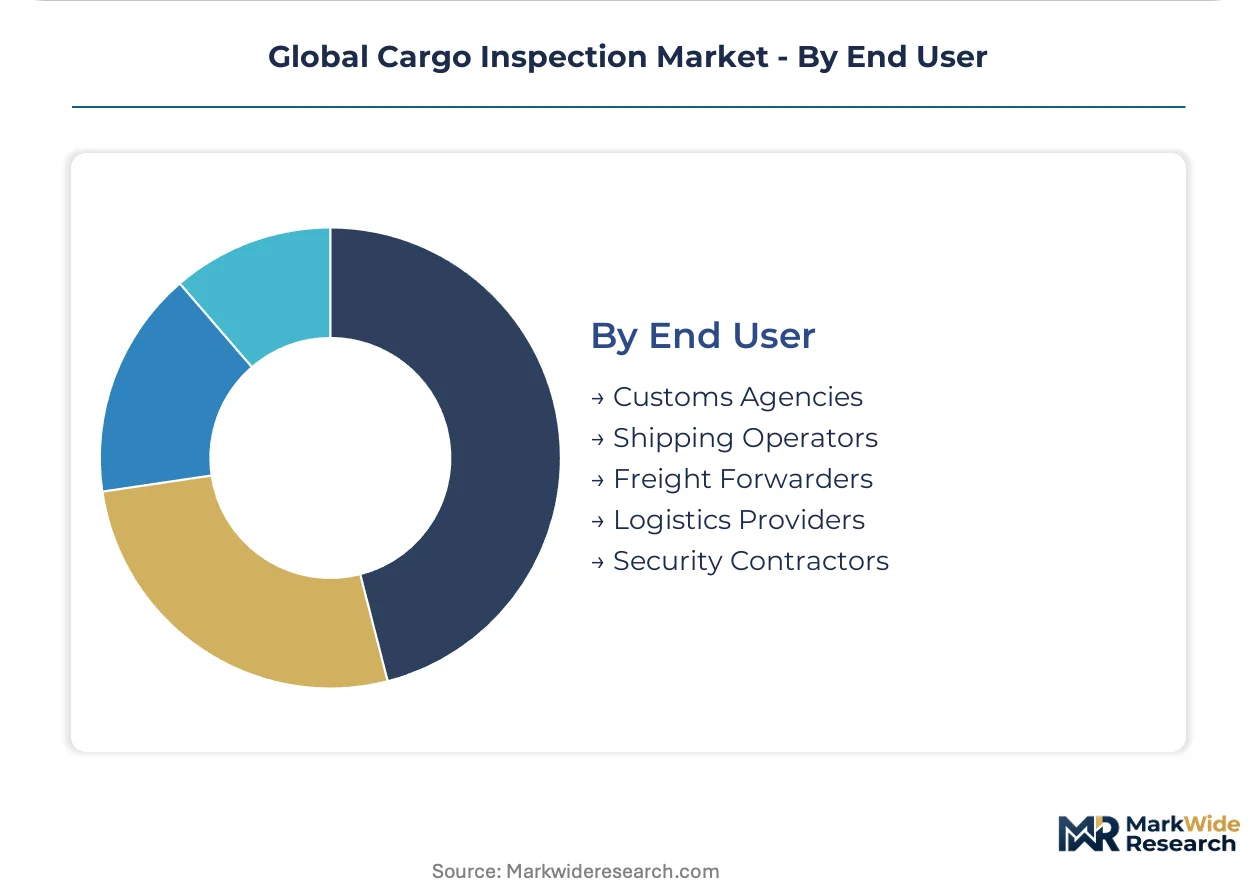
End user categories reflect divergent compliance incentives, with customs agencies bearing statutory inspection mandates while commercial operators respond to insurance and customer requirements.
- Customs Agencies:Government authorities including US CBP, EU DG TAXUD, and India's Central Board of Indirect Taxes and Customs specify equipment standards through tender processes. The World Customs Organization SAFE Framework and national implementations mandate escalating inspection coverage ratios that directly determine procurement cycles; ISO 17020 and ISO 17025 accreditation requirements stratify vendor eligibility.
- Shipping Operators:Container lines and vessel operators invest in pre-loading verification to reduce destination port delays. Maersk, MSC, and CMA CGM deploy inspection systems at origin terminals to certify cargo compliance before ocean transit; risk-based targeting algorithms prioritize high-value or sensitive route segments.
- Freight Forwarders:Consolidators and NVOCCs implement screening to satisfy customer chain-of-custody requirements.
- Logistics Providers:Third-party warehouse and distribution operators integrate inspection into value-added service offerings.
- Security Contractors:Private screening firms deliver inspection services under port authority or government outsourcing arrangements.
Customs agencies anchor public-sector procurement; shipping operators are gaining share fastest from supply chain resilience investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US CBP mandates anchor North American procurement cycles while Rotterdam and Singapore terminals compress equipment refresh timelines through three-dimensional imaging mandates. Customs modernization programs across India and Southeast Asia narrow technology gaps through domestic manufacturing incentives and port authority digitalization.
United States
Los Angeles and Long Beach terminals deploy dual-energy X-ray systems to reduce manual container opening rates under US CBP automation directives. The SAFE Framework implementation mandates escalating inspection coverage ratios that determine federal procurement appropriations. Pacific Northwest corridor operators integrate remote image analysis centers to virtualize traditional customs inspection labor pools.
Netherlands
Rotterdam port authority forces multi-year equipment refresh decisions as customs agencies mandate computed tomography for dense cargo discrimination. REACH chemical compliance extends to hazardous material documentation verification for bulk chemical shipments. Antwerp petrochemical terminals embed laboratory sampling into standard unloading workflows to satisfy regulatory mandates.
Singapore
PSA International procurement frameworks compress vendor negotiation cycles toward performance-guaranteed service agreements. The Maritime and Port Authority scales non-intrusive inspection programs through automated scanning compliance mandates. Tanjung Pelepas corridor expansion creates equipment replacement demand alongside Port Klang modernization.
India
Jawaharlal Nehru Port Trust and Mundra Port modernization programs generate gamma ray scanner deployment demand. The PLI scheme narrows technology gaps in cargo screening infrastructure through domestic manufacturing incentives. Central Board of Indirect Taxes and Customs procurement follows federal budget cycles with ISO 17020 accreditation requirements stratifying vendor eligibility.
Germany
Hamburg terminal operators respond to Union Customs Code modernization through automated scanning compliance investments. Federal Maritime and Hydrographic Agency protocols align with EU DG TAXUD equipment standards for border security applications. North Sea port clusters integrate legacy radiography systems with predictive risk targeting workflows.
Global Cargo Inspection Market Competitive Landscape
Full-service inspection networks and specialized testing laboratories split the market between integrated compliance platforms and technical certification depth. The vendor base concentrates around three archetypes: transcontinental laboratory networks sustaining high-volume trade lane throughput, classification society affiliates anchoring maritime inspection franchises, and petroleum and agricultural cargo specialists competing in emerging corridors. Consolidation pressures favor multi-year service contract bundling over discrete equipment sales, while ISO 17025 accreditation timelines extend competitive moats for incumbent qualification holders.
Within the transcontinental network tier, SGS Group and Bureau Veritas occupy positions defined by laboratory density and maritime protocol anchoring respectively. Intertek Group exemplifies the specialized testing archetype through petroleum and agricultural cargo protocol concentration. DNV GL AS sits within the classification society affiliate category, leveraging port-state control mandates for competitive positioning. These three patterns—integrated network scale, maritime regulatory anchoring, and commodity-specific technical depth—structure competitive differentiation across customs tender processes and private terminal operator procurement.
| Leading Market Players |
|---|
| Cotecna Inspection SA |
| TÜV SÜD |
| SGS Group |
| DNV GL AS |
| DEKRA SE |
| Bureau Veritas SA |
| ALS Limited |
| AmSpec Group |
| Intertek Group plc |
| Others |
Supply & Pricing Matrix
Isotope sourcing for gamma ray scanners concentrates in Canada and Russia, locking margin pools within maintenance contract structures rather than initial equipment sales. Port authorities now negotiate multi-year service bundles that embed cobalt-60 replacement cycles into predictable recurring revenue streams.
Pricing Analysis
Price spreads between Rotterdam and Mumbai terminals reach three-to-one for equivalent CT systems, reflecting installation complexity premiums and local certification costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 accreditation status and after-sales bundling intensity. Pricing pressure stems from Indian domestic manufacturing incentives compressing import equipment margins. Mid-tier port operators in Southeast Asia exhibit highest price sensitivity; mega-terminal operators at Singapore and Los Angeles prioritize performance guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock for radiation sources draws from Canadian cobalt mining operations and Russian cesium-137 processing facilities, creating geopolitical concentration risk. Detector arrays and linear accelerator components source from Germany, Japan, and the United States. Single-source vulnerability sits with isotope replacement logistics governed by nuclear materials transport protocols. Distribution runs through authorized service networks rather than equipment distributors, as port authorities contract directly with technology integrators for integrated compliance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue in cargo inspection expands faster than hardware sales, with maintenance contracts and remote image analysis subscriptions now driving vendor profitability. ISO 17025-accredited laboratory networks command pricing premiums that hardware-only competitors cannot match.
For Market Incumbents: Insulate market position through backward integration into isotope logistics and remote diagnostics platforms. Secure multi-year service contracts at Rotterdam and Singapore before CT refresh cycles complete. Certification timeline compression from ISO 17020 requirements creates defensive moats against unqualified entrants.
For New Entrants and Emerging Players: Mid-tier Indian port terminals represent the most penetrable entry point, with Jawaharlal Nehru Port Trust and Mundra Port modernization programs creating equipment replacement demand outside incumbent strongholds. Infrared-physical screening convergence in warehouse security offers second white-space target with lower capital barriers. Partner with domestic manufacturers under PLI scheme to bypass import cost disadvantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed inspection technology integrators lacking laboratory network scale. Long-term viability hinges on recurring revenue ratio exceeding hardware sales dependency. Watch US CBP appropriation cycles as inflection indicator for federal procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Platform Launch | Virtualizes inspection labor pools at Los Angeles and Long Beach terminals. |
| ISO 17025 Laboratory Acquisition | Secures vendor eligibility for EU DG TAXUD and Indian customs tenders. |
| Domestic Manufacturing Joint Venture | Accesses PLI incentives for gamma ray scanner production at Mundra Port corridor. |
| Performance-Guaranteed Service Agreement | Compresses traditional equipment leases at Singapore's PSA International procurement framework. |
| Dual-Energy X-ray Technology Licensing | Reduces manual container opening rates under US CBP automation directives. |
Research Methodology
Desk research of customs procurement databases, WCO SAFE Framework implementation reports, and port authority digitalization disclosures preceded structured interviews with customs technology procurement officers, terminal operations directors, scanner maintenance engineers, and laboratory accreditation specialists. Secondary validation drew from EU DG TAXUD equipment standards documentation, US CBP appropriation committee records, and Indian Central Board of Indirect Taxes and Customs tender archives. Bottom-up equipment deployment tracking and top-down market sizing triangulated volume estimates.
Assumptions held customs modernization funding commitments and non-intrusive inspection coverage ratio mandates fixed across the analysis window, while port throughput growth and isotope supply logistics varied. Segmentation dimensions modeled included scanner technology type, port tier by throughput volume, regulatory compliance tier, and service contract structure. CAGRs derived from equipment replacement cycle timing and service revenue attachment rates. Forecast inputs incorporated Rotterdam CT mandate implementation timelines and Indian PLI scheme participation thresholds.
Macroeconomic conditions sit as an overlay; deviation in trade volume growth or customs agency budget appropriations would shift the trajectory. Forecasts reflect documented procurement schedules and regulatory mandate calendars. Material shifts in WCO SAFE Framework national implementation timelines or isotope transport protocol restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Commercial Security Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
India CCTV Market